
 Nitrile Gloves Market | 2026-2036
Nitrile Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrile Gloves Market Analysis
Aftermarket service revenue for glove supply chain partners is tilting toward inventory management and just-in-time replenishment contracts as hospitals reduce warehousing costs. Top Glove Corporation Bhd leverages its integrated nitrile butadiene rubber production to control raw material costs across its Malaysian facilities. Hartalega Holdings Berhad differentiates through automated manufacturing lines that sustain output consistency at elevated throughput levels. Ansell Ltd anchors its position in specialized chemical-resistant formulations for industrial end-users.
Nitrile gloves are synthetic rubber hand protection devices formulated from acrylonitrile-butadiene copolymer, typically ranging from 3 to 8 mil in thickness, manufactured through dipping processes on ceramic formers followed by vulcanization and chlorination for donning ease. Their primary commercial purpose spans infection control in clinical settings, chemical splash protection in industrial environments, and contamination prevention in food handling and electronics assembly. Exam gloves within the product type dimension represent the mature volume base, while cleanroom gloves capture expanding margin pools from semiconductor and pharmaceutical manufacturing requirements. Medical grade classification dominates regulatory scrutiny and pricing premiums, whereas industrial grade competes on cost efficiency and durability metrics across automotive and chemical processing applications.
FDA quality system regulation and ISO 13485 medical device standards govern product performance, biocompatibility testing, and lot traceability for healthcare-bound shipments into the United States. OSHA personal protective equipment directives and REACH chemical compliance frameworks in Europe shape material formulation choices and supplier market access conditions. Stakeholders must monitor evolving nitrile butadiene rubber feedstock availability and assess dual-sourcing strategies against concentrated Malaysian production geography.
Market Dynamics
Healthcare procurement consolidation and FDA's tightened quality system regulation are compressing supplier margins while concentrating purchasing power among integrated hospital networks, forcing manufacturers to absorb compliance costs or exit the medical-grade segment entirely.
Growth Catalysts
- OSHA personal protective equipment mandates:Chemical processing and automotive facilities across the United States face expanded glove-wearing requirements for worker safety, driving replacement volume.
- Semiconductor cleanroom expansion:Malaysia and Thailand host expanding fabrication facilities requiring ISO-certified nitrile cleanroom gloves for contamination control.
- Acrylonitrile-butadiene copolymer formulation advances:Thinner 3-mil medical-grade gloves now match 5-mil puncture resistance, reducing raw material consumption per unit.
Market Restraints
- Malaysian production concentration:Overreliance on integrated nitrile butadiene rubber supply chains in Southeast Asia creates geographic vulnerability to weather and logistics disruptions.
- REACH chemical compliance costs:European registration requirements for nitrile formulations impose testing burdens that exclude smaller manufacturers from EU market access.
- Latex allergy substitution ceiling:Natural rubber latex gloves retain cost advantages in non-medical applications, capping nitrile penetration in price-sensitive industrial segments.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO medical device regulations are aligning with ISO 13485, opening import pathways for certified suppliers.
- Biodegradable nitrile formulations:Converging polymer science and enzymatic degradation technology addresses landfill disposal criticism from healthcare sustainability officers.
- Direct hospital system contracts:Bypassing traditional medical distributors through just-in-time inventory management platforms captures margin from intermediaries.
Industry Challenges
- ISO 13485 certification timelines:Medical-grade qualification requires 12-18 month validation cycles that delay revenue recognition for new production lines.
- Chlorination process chemistry expertise:Surface treatment for donning ease demands specialized technicians whose training pipelines remain underdeveloped outside established manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrile Gloves Market |
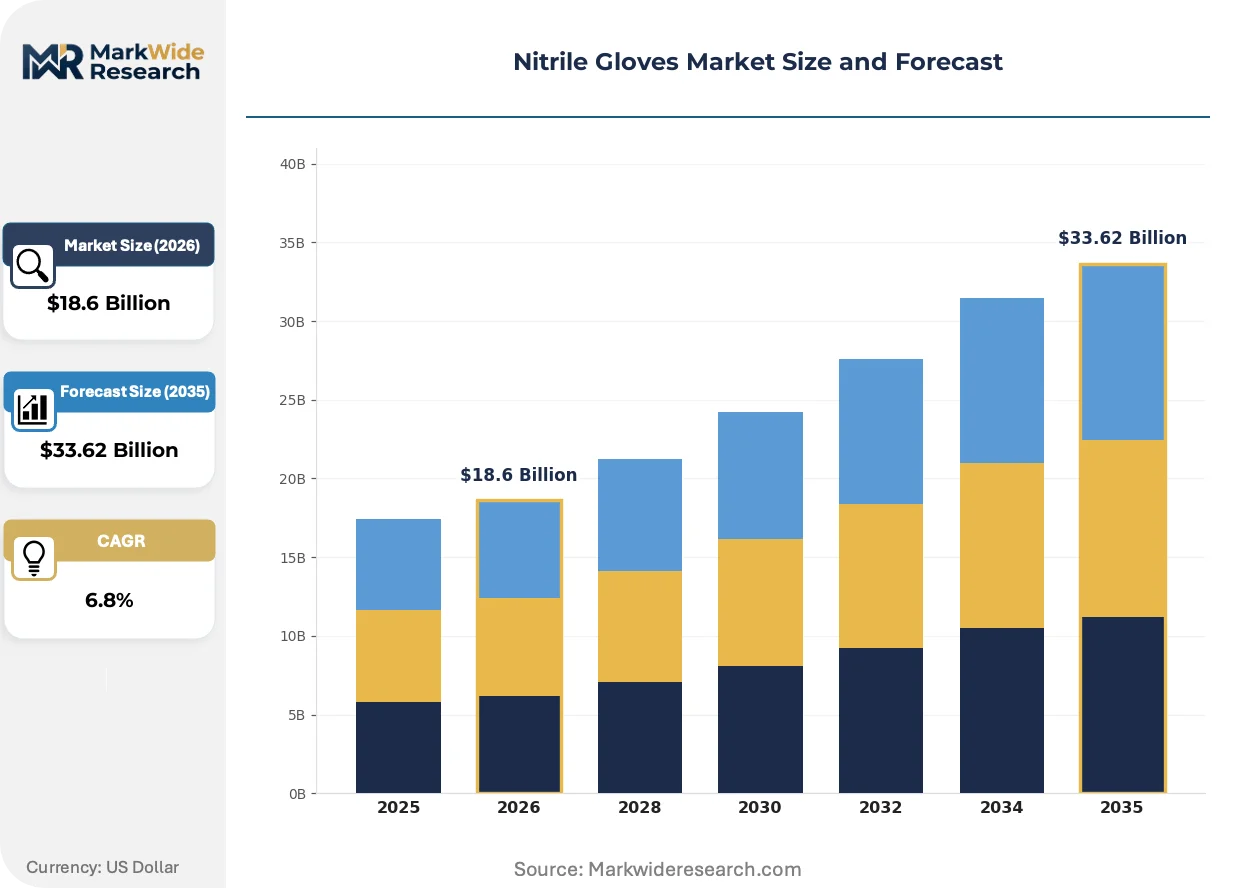
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exam Gloves, Industrial Gloves, Cleanroom Gloves, Food Handling Gloves Application: Healthcare, Automotive, Food Service, Electronics Thickness: Thin, Medium, Thick, Extra Thick Grade: Medical Grade, Industrial Grade, Food Grade, Custom Grade |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Ansell Ltd, Kossan Rubber Industries Bhd, Supermax Corporation Berhad, Unigloves (UK) Limited, Cardinal Health, Medline Industries, Inc., MCR Safety, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrile Gloves Market Emerging Trajectories
Automation and material science advances are compressing production costs while regulatory divergence between jurisdictions fragments compliance strategies, forcing suppliers to maintain parallel certification tracks for market access.
Automated dipping lines with real-time thickness monitoring are collapsing the quality variance between high-volume batches and custom small runs. Semiconductor fabs and pharmaceutical manufacturers in Singapore and South Korea now specify sub-2-mil thickness tolerances that only robotic formers achieve consistently. This capability compression enables mid-scale suppliers to bid on previously inaccessible cleanroom contracts without dedicated specialty lines.
EU MDR medical device regulation extends traceability requirements to single-use gloves, mandating lot-level digital records for ten-year retention. German and French hospital systems are rejecting shipments lacking compliant unique device identifiers, filtering non-compliant Asian suppliers from tender participation. The regulatory friction falls heaviest on industrial-grade producers attempting medical segment crossover without dedicated quality infrastructure.
Hospital supply chain directors are consolidating glove purchasing through group purchasing organizations that negotiate multi-year sole-source agreements. This buyer concentration displaces spot-market transactions and fragments remaining distributor relationships into logistics-only roles. The restructuring is most advanced in United States integrated delivery networks, where procurement officers now specify compliance dashboards as contract deliverables.
Nitrile Gloves Market Segmentation
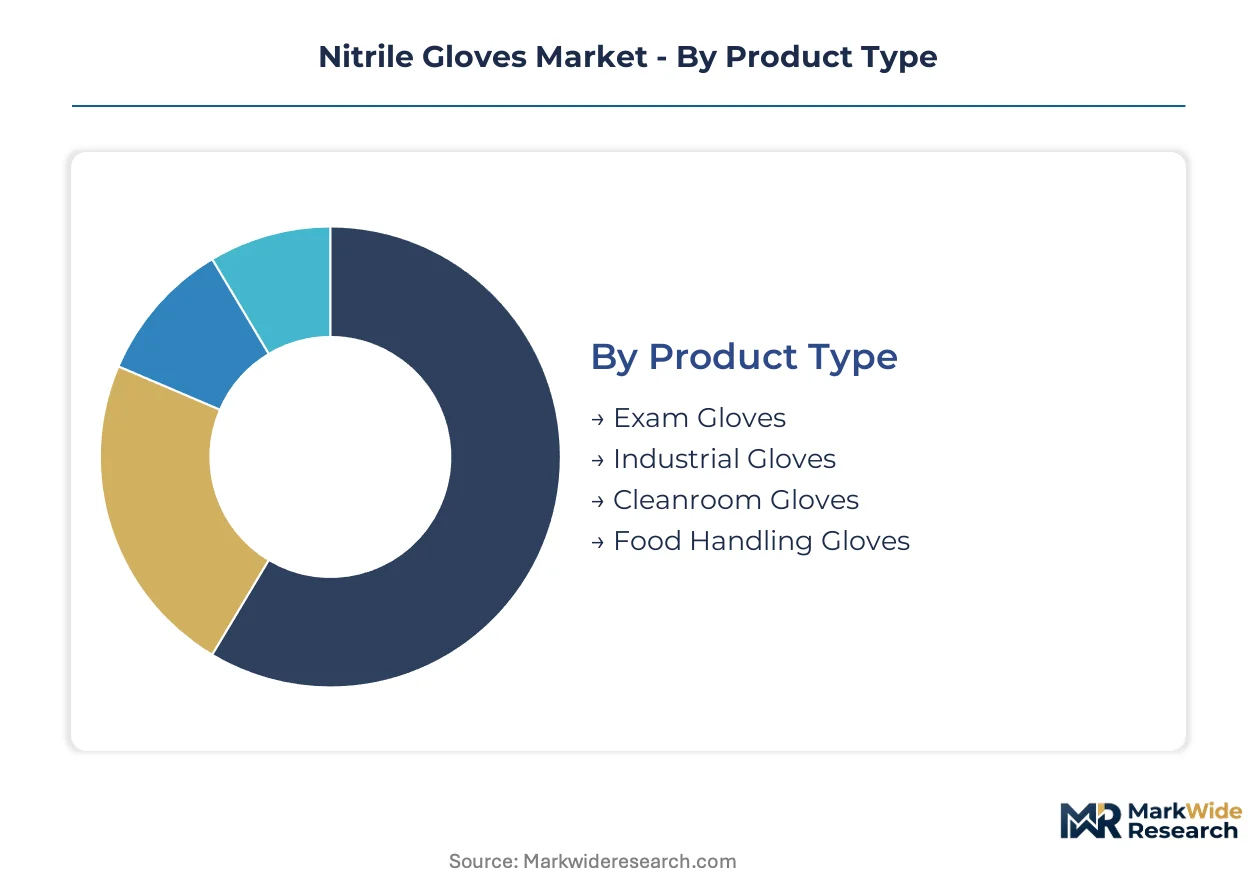
Segmentation in nitrile gloves determines procurement cycles, margin structures, and compliance pathways. Hospital systems route medical-grade exam gloves through 90-day contracts while industrial buyers purchase spot-market industrial grades on monthly horizons. Thickness and grade specifications further stratify supplier qualification requirements and manufacturing asset allocation.
Product Type:
Exam gloves turn inventory fastest at 45-60 day cycles, while cleanroom gloves sit in 180-day qualification pipelines before first shipment.
- Exam Gloves:Powder-free formulations dominate hospital procurement, with 3-mil to 5-mil thicknesses meeting FDA medical device standards. Demand concentrates in United States integrated delivery networks where group purchasing organizations negotiate sole-source agreements. Tighter FDA quality system regulation is compressing supplier margins and accelerating exits from non-compliant manufacturers.
- Cleanroom Gloves:Sub-2-mil precision tolerances achieved through robotic dipping lines serve semiconductor fabrication facilities in Singapore and South Korea. Malaysia and Thailand host expanding fab capacity requiring ISO-certified contamination control. EU MDR traceability mandates now filter non-compliant Asian suppliers from European pharmaceutical tenders.
- Industrial Gloves:Chemical-resistant formulations for automotive and chemical processing facilities compete on cost efficiency and durability metrics. OSHA personal protective equipment mandates drive replacement volume across United States manufacturing plants.
- Food Handling Gloves:Blue-colored variants support HACCP visual detection protocols in commercial kitchens and food processing lines. Food-grade certification requirements vary by national food safety authority jurisdiction.
Exam gloves anchor the volume base while cleanroom gloves gain share at the steepest rate.
Application:
Cost tier stratification separates healthcare's compliance-heavy premium pricing from automotive's efficiency-driven procurement.
- Healthcare:Infection control in hospitals and outpatient clinics drives powder-free nitrile consumption. FDA medical device quality system regulation and ISO 13485 certification govern supplier access. Procurement consolidation among integrated hospital networks concentrates purchasing power and demands compliance dashboards as contract deliverables.
- Electronics:Semiconductor and pharmaceutical manufacturing require sub-2-mil thickness tolerances and lot-level traceability. Singapore and South Korean fabs specify robotic former consistency that only automated lines achieve. EU MDR ten-year digital record retention mandates reshape supplier qualification.
- Automotive:Chemical splash protection and assembly line durability requirements prioritize cost efficiency over certification depth. OSHA mandates expand glove-wearing requirements but industrial-grade pricing caps margin capture.
- Food Service:Commercial kitchens and processing facilities balance visual detection protocols with disposable economics. National food safety authorities impose varying migration testing requirements for food-contact materials.
Healthcare commands premium pricing tiers while electronics applications expand most quickly.
Thickness:
Material science advances are collapsing the performance gap between thinner and thicker variants, altering raw material economics.
- Thin:3-mil medical-grade formulations now match 5-mil puncture resistance through acrylonitrile-butadiene copolymer advances. United States hospital systems specify thin variants to reduce per-unit costs without sacrificing protection.
- Medium:5-mil to 6-mil specifications balance dexterity and durability for general healthcare and light industrial tasks. This specification captures the broadest cross-application demand.
- Thick:7-mil to 8-mil variants serve chemical processing and extended-wear industrial environments. Automotive facilities specify thick gloves for solvent handling and parts cleaning operations.
- Extra Thick:Above 8-mil specifications address specialized chemical-resistant and heavy-duty mechanical protection. Limited volume concentrates in chemical manufacturing and hazardous materials handling.
Medium thickness dominates unit volume while thin variants climb the fastest on material efficiency gains.
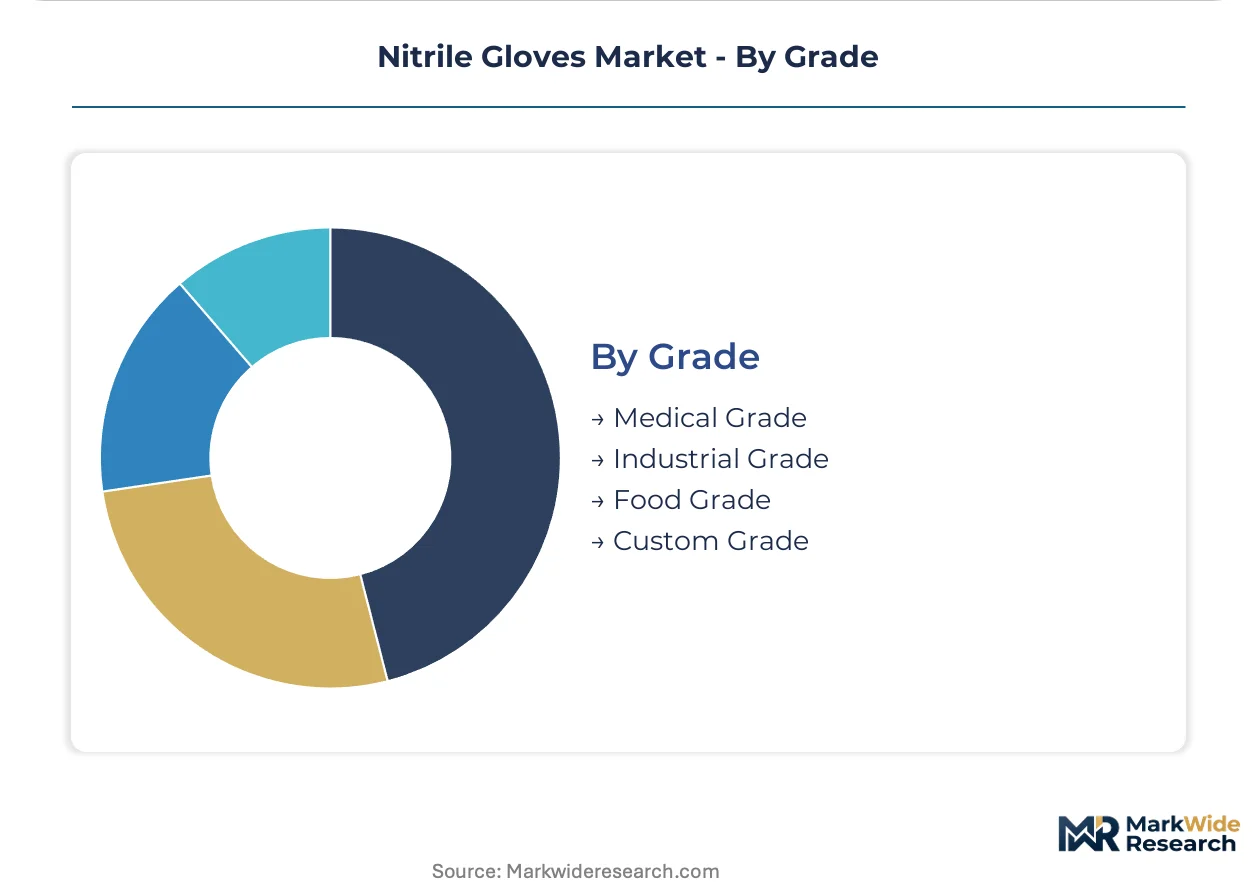
Grade:
Regulatory jurisdiction determines grade qualification pathways, with medical grade imposing the steepest certification barriers.
- Medical Grade:FDA quality system regulation, ISO 13485, and biocompatibility testing govern United States market access. Twelve-to-eighteen-month validation cycles delay revenue recognition for new production lines. Hospital procurement officers now specify compliance dashboards as multi-year contract deliverables.
- Industrial Grade:OSHA personal protective equipment directives shape formulation choices without medical-device depth. Cost efficiency and durability metrics dominate automotive and chemical processing selection criteria.
- Food Grade:National food safety authorities and HACCP protocols govern migration testing and visual detection requirements. Blue coloration supports contamination identification in commercial food handling.
- Custom Grade:Specialized formulations for semiconductor cleanrooms and pharmaceutical manufacturing combine thickness precision with extended traceability. EU MDR unique device identifier requirements filter supplier participation.
Medical grade anchors revenue concentration while custom grade expands on cleanroom and pharmaceutical manufacturing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Southeast Asia exhibit the highest price elasticity, while European pharmaceutical manufacturers absorb substantial premiums for traceability compliance. United States hospital procurement officers negotiate multi-year sole-source contracts that compress supplier margins. Chinese domestic demand responds aggressively to spot-market nitrile butadiene rubber price movements.
United States
Integrated delivery networks consolidate glove purchasing through group purchasing organizations, reducing distributor intermediaries to logistics-only roles. FDA quality system regulation and OSHA personal protective equipment mandates govern supplier access and worker safety requirements. Texas and California host the largest hospital system procurement offices, where compliance dashboards now feature as mandatory contract deliverables.
Malaysia
Integrated nitrile butadiene rubber supply chains support large-scale production clusters serving global export markets. The country's medical device authority aligns with ISO 13485 standards for international market access. Selangor and Perak states concentrate automated dipping facilities and chlorination expertise, with Port Klang handling bulk container shipments to North America and Europe.
Germany
EU MDR medical device regulation mandates ten-year lot-level digital record retention for single-use gloves entering hospital systems. REACH chemical compliance frameworks impose formulation testing burdens that filter smaller Asian suppliers from tender participation. The Rhine-Ruhr industrial corridor and Bavarian chemical processing hubs specify industrial-grade nitrile for solvent handling operations.
Thailand
Expanding semiconductor fabrication facilities drive cleanroom glove demand requiring sub-2-mil thickness tolerances. The Thai Food and Drug Administration enforces medical device registration parallel to international standards. Eastern Economic Corridor provinces host integrated nitrile butadiene rubber production and robotic former manufacturing lines serving electronics and pharmaceutical sectors.
India
Contract development and manufacturing organization expansion in pharmaceutical production opens import pathways for certified glove suppliers. CDSCO medical device regulations are aligning with ISO 13485, streamlining qualification timelines. Maharashtra and Gujarat states concentrate active pharmaceutical ingredient manufacturing facilities requiring contamination control protocols.
Nitrile Gloves Market Vendor Landscape
Capability concentration sits with automated manufacturing specialists; scale advantage sits with integrated nitrile butadiene rubber producers. The vendor base stratifies into three tiers: multinational diversified health care conglomerates, Southeast Asian integrated producers with captive raw material supply, and regional distributors with logistics-only positioning. Two dominant competitive moves are reshaping positioning: backward integration into nitrile butadiene rubber production to control feedstock costs, and direct hospital system contracting to capture distributor margins.
Among Malaysian integrated producers, Top Glove Corporation Bhd and Hartalega Holdings Berhad exemplify the scale-driven archetype through captive supply chain control. Ansell Ltd occupies a position within the specialized formulation tier, serving industrial end-users with chemical-resistant product lines. These three entities represent the structural poles of the competitive landscape: integrated volume leadership, automation-driven consistency, and application-specific differentiation.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Ansell Ltd |
| Kossan Rubber Industries Bhd |
| Supermax Corporation Berhad |
| Unigloves (UK) Limited |
| Cardinal Health |
| Medline Industries, Inc. |
| MCR Safety |
| Others |
Supply Flow & Price Mechanics
Idle dipping capacity in Malaysian production clusters is compressing spot-market quotes while simultaneously pressuring integrated producers to prioritize long-term service contracts over transactional volume. This utilization dynamic rewards suppliers with captive nitrile butadiene rubber supply chains and punishes toll manufacturers exposed to feedstock volatility.
Pricing Analysis
Aftermarket service revenue from just-in-time replenishment contracts and inventory management platforms now drives lifetime value beyond per-unit glove sales. Three-tier pricing structure across medical-grade premium, industrial-grade standard, and food-grade economy levels stratifies by certification depth and lot traceability. Cost compression in medical-grade segments is intensifying because FDA quality system regulation compliance costs are concentrating purchasing power among integrated hospital networks. Industrial buyers in Southeast Asia exhibit the highest price sensitivity, while European pharmaceutical manufacturers absorb substantial premiums for EU MDR-compliant traceability infrastructure.
Supply Chain Analysis
Nitrile butadiene rubber feedstock availability anchors upstream stability, with acrylonitrile and butadiene monomer supplies drawing from integrated petrochemical complexes in Malaysia, Thailand, and South Korea. Ceramic formers, chlorination chemistry, and automated dipping equipment constitute critical manufacturing inputs. Single-source vulnerability concentrates in Malaysian production geography, where weather disruptions and port congestion at Port Klang propagate delays across global shipments. Distribution runs through group purchasing organizations and medical distributors that are consolidating into logistics-only roles as hospital systems negotiate direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement platforms are reconstituting supplier relationships around compliance-dashboard interoperability, creating platform-economics dynamics where data integration becomes as critical as manufacturing scale.
For Market Incumbents: Build certification moats through ISO 13485 and FDA quality system regulation infrastructure that emerging entrants cannot replicate within viable timelines. Absorb compliance costs to defend medical-grade positioning against industrial-grade crossover attempts. Add chlorination process capacity in established Malaysian and Thai manufacturing clusters where technical expertise pools concentrate. For New Entrants and Emerging Players: Mid-tier cleanroom glove specifications for expanding semiconductor fabs in Thailand's Eastern Economic Corridor represent the most penetrable entry point, as robotic dipping line investments enable sub-2-mil precision without legacy overhead. Target Indian pharmaceutical manufacturing facilities where CDSCO alignment with ISO 13485 is streamlining import qualification. Pursue direct contracting with regional hospital systems bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated manufacturing sub-segments as robotic former technology commoditizes precision capabilities previously requiring dedicated specialty lines. Over a multi-year horizon, vertically integrated producers with captive nitrile butadiene rubber supply chains demonstrate superior margin resilience. Monitor FDA warning letter issuance rates as an inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Butadiene Rubber | Captive feedstock supply insulates Malaysian producers from acrylonitrile price volatility at Pasir Gudang petrochemical hubs. |
| Direct Hospital System Contracting | Bypassing medical distributors captures margin from intermediaries as GPOs consolidate purchasing across integrated delivery networks. |
| Automated Dipping Line Deployment | Robotic former consistency achieves sub-2-mil tolerances required by Singapore semiconductor fabrication facilities. |
| EU MDR Traceability Infrastructure | Ten-year digital record retention capabilities filter non-compliant Asian suppliers from German and French hospital tenders. |
| Biodegradable Formulation R&D | Enzymatic degradation technology addresses landfill disposal criticism from healthcare sustainability officers in United States systems. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement officers, glove manufacturing plant managers, biomedical engineers, group purchasing organization contract managers, and nitrile butadiene rubber supply specialists. Secondary validation drew from FDA medical device establishment registrations, ISO 13485 certification databases, customs trade records, hospital procurement databases, and SEC filings of listed glove manufacturers. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, thickness, and grade segmentation dimensions.
Calibration against historical capacity utilization rates, regulatory approval timelines, and raw material price movements anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, thickness specification, grade classification, and regional manufacturing cluster. CAGRs were derived from regression analysis of demand drivers including healthcare expenditure trends, OSHA mandate expansion, and semiconductor fab capacity additions. Forecast inputs incorporated nitrile butadiene rubber feedstock availability trajectories and chlorination process chemistry expertise distribution.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, trade policy shifts affecting Malaysian exports, or semiconductor capital equipment investment waves would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and supply chain continuity. Cross-checking against hospital procurement database benchmarks and GPO contract award frequencies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Skin Tac Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Global Medical Elastomers Market