
 Global Medical Mask Market | 2026-2036
Global Medical Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Mask Market Foresight
Polypropylene melt-blown nonwovens is repositioning cellulose and cotton as the dominant filtration substrate in medical mask manufacturing, cutting unit costs while boosting bacterial filtration efficiency above 95 percent. 3M leverages its electrostatic charging technology to sustain premium positioning in the respirator segment. Kimberly-Clark Corporation anchors North American hospital supply contracts through direct distribution networks. Cardinal Health competes on scale by controlling private-label production for integrated delivery networks.
A medical mask is a loose-fitting or tight-fitting disposable device worn over the nose and mouth to block large-particle droplets, splashes, sprays, or splatter that may contain germs, constructed typically from three layers of spunbond and melt-blown polypropylene with ear loops or tie straps. Its primary commercial purpose is to protect the wearer from contact with infectious agents and to reduce the release of wearer-generated contaminants into sterile or vulnerable environments. Respirators and N95 masks command the highest margin pools due to fit-testing requirements and occupational health liability exposure, while surgical masks dominate absolute volume through standardized hospital purchasing. Melt-blown fabric technology leads filtration efficiency benchmarks, though nanofiber filters are gaining traction in premium segments where breathability at high particle capture rates justifies cost premiums.
The FDA governs surgical masks as Class II medical devices requiring 510(k) clearance, while NIOSH certifies N95 respirators under 42 CFR Part 84, creating a dual-track compliance burden that filters out low-capability manufacturers. The EU Medical Device Regulation and CE marking framework impose post-market surveillance obligations that extend liability across the distribution chain. OSHA's respiratory protection standard in the United States mandates annual fit testing for healthcare workers, institutionalizing recurring demand. Stakeholders must monitor how the WHO's pandemic preparedness framework reshapes national stockpile targets and whether biodegradability mandates from the EU Green Deal force material transitions before supply chains adapt.
Market Dynamics
Hospital procurement departments in Germany, Japan, and the United States are mandating larger respiratory protection stockpiles, compressing purchasing cycles and forcing manufacturers to reconfigure capacity planning around pandemic preparedness frameworks rather than seasonal flu patterns.
Growth Catalysts
- EU Medical Device Regulation:Tighter filtration performance thresholds under MDR are filtering out low-capability manufacturers, concentrating demand among certified suppliers with post-market surveillance infrastructure.
- Polypropylene melt-blown nonwovens:This substrate is repositioning cellulose and cotton in mask manufacturing, cutting unit costs while pushing bacterial filtration efficiency above 95 percent in surgical applications.
- OSHA respiratory protection standard:Annual fit-testing mandates for healthcare workers in the United States institutionalize recurring demand for N95 respirators and replacement cartridges.
Market Restraints
- Electrostatic charging technology concentration:Premium respirator manufacturing depends on specialized charging equipment controlled by a limited supplier base, creating single-source vulnerability for filtration media.
- Dual-track compliance burden:FDA 510(k) clearance for surgical masks and NIOSH 42 CFR Part 84 certification for respirators force parallel regulatory investments that exclude smaller manufacturers.
- Polypropylene price volatility:Crude oil-linked feedstock costs for melt-blown nonwovens compress margins during energy price spikes, particularly for standard surgical mask producers.
Strategic Opportunities
- Nanofiber filtration convergence:Electrospinning technology paired with biodegradable polymers is opening premium segments where breathability at high particle capture rates justifies cost premiums over melt-blown alternatives.
- EU Green Deal biodegradability mandates:Pending material transition requirements create first-mover advantage for manufacturers with cellulose-based or compostable substrate pipelines ahead of supply chain adaptation.
- Direct distribution to integrated delivery networks:Bypassing group purchasing organizations through captive logistics networks allows margin capture and contract exclusivity in North American hospital systems.
Industry Challenges
- NIOSH certification timeline compression:Respirator approval backlogs extend product launch windows by 12-18 months, straining working capital for manufacturers awaiting 42 CFR Part 84 clearance.
- Electrostatic charge stability expertise:Shortage of process engineers capable of maintaining filtration efficiency degradation curves below 5 percent over product shelf life limits quality-scale expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Mask Market |
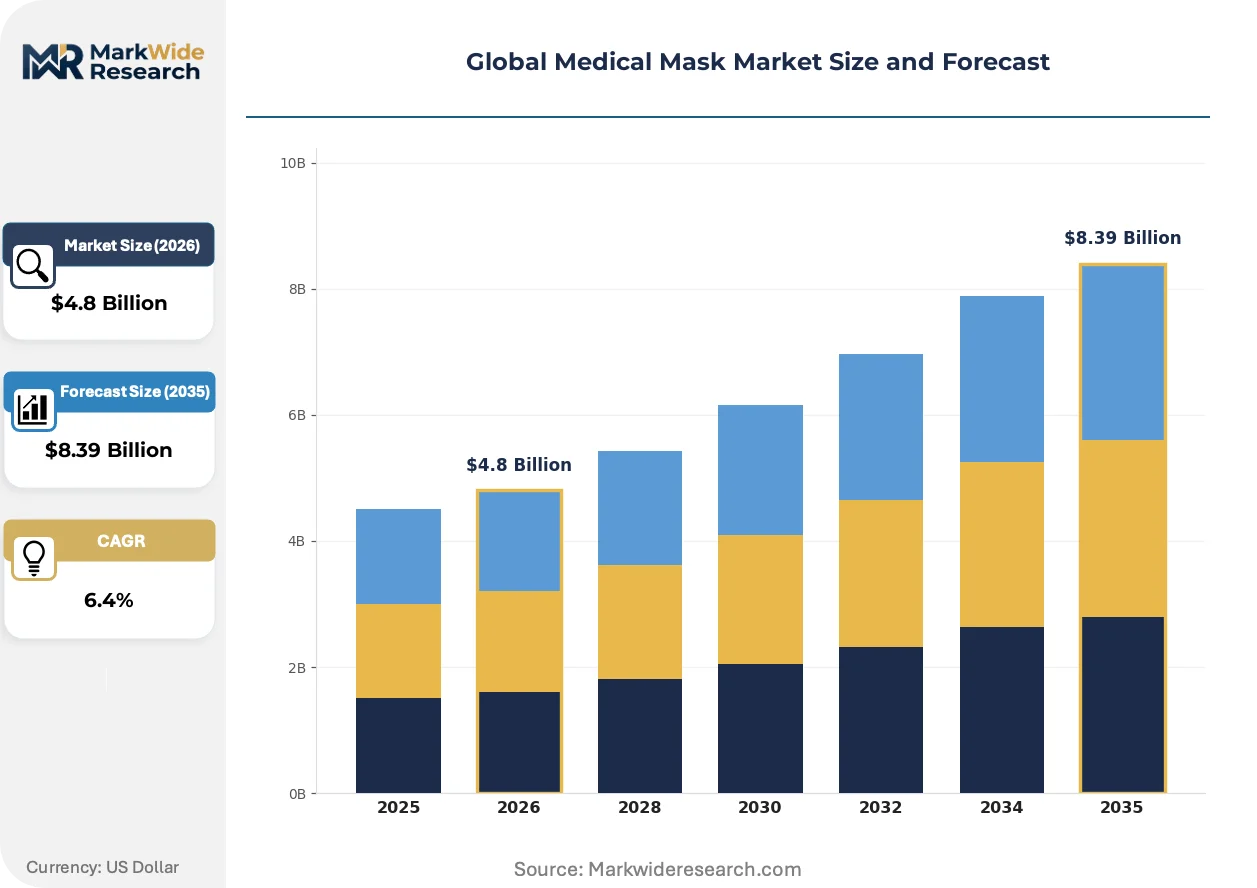
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
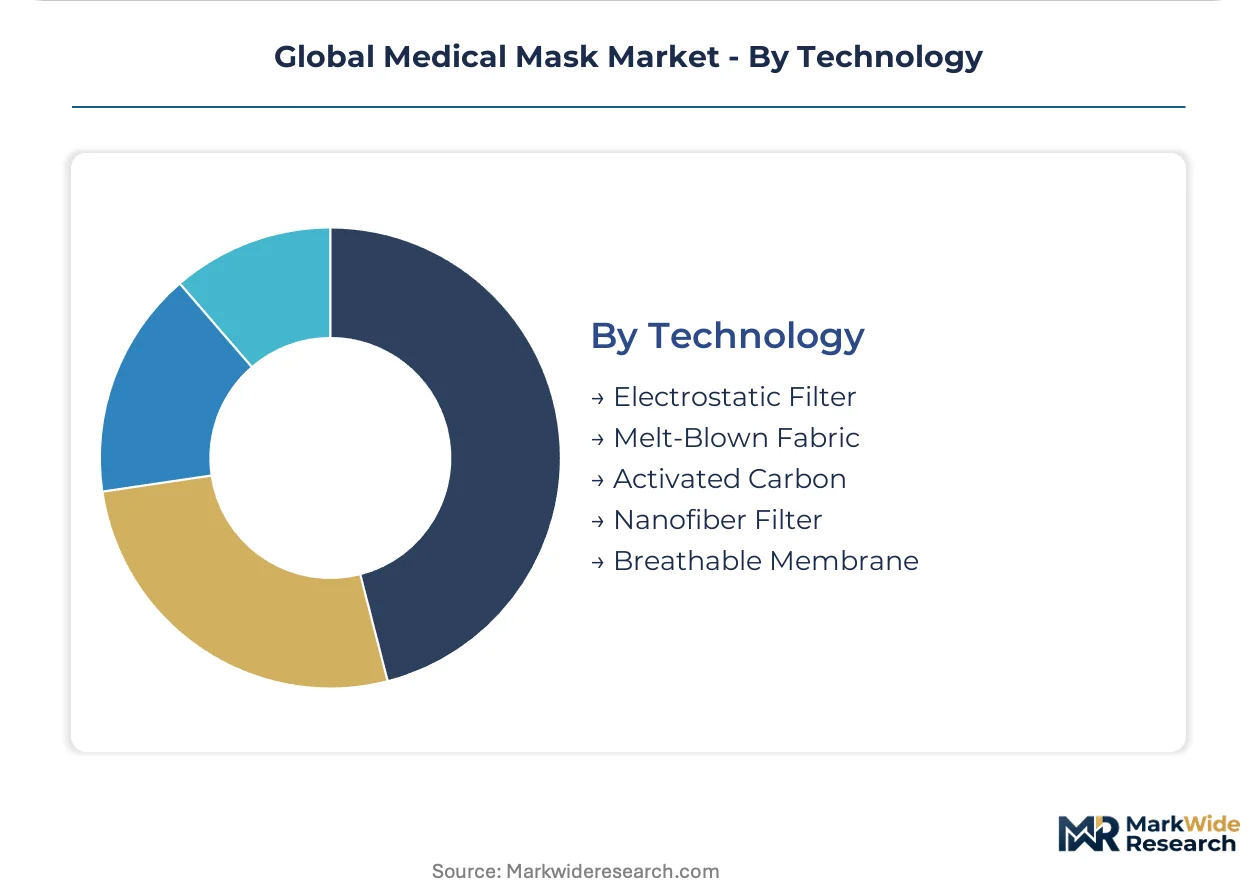
| Segmentation | Product Type: Surgical Masks, Respirators, Cloth Masks, N95 Masks, KN95 Masks Application: Hospital Settings, Dental Procedures, Laboratory Use, Emergency Services, Patient Care End User: Hospitals, Clinics, Laboratories, First Responders, Elderly Care Centers Technology: Electrostatic Filter, Melt-Blown Fabric, Activated Carbon, Nanofiber Filter, Breathable Membrane |
| Companies Covered | 3M, Honeywell International Inc., Cardinal Health, Medline Industries, Ansell Ltd., Kimberly-Clark Corporation, Owens & Minor, Prestige Ameritech, Moldex-Metric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Mask Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape competitive positioning across filtration tiers, with sustainability mandates beginning to penetrate procurement specifications in European healthcare systems.
Electrostatic charging technology is consolidating premium respirator manufacturing around suppliers with proprietary corona-treatment or tribocharging capabilities. Hospital systems with occupational health liability exposure are consolidating vendor lists toward these certified suppliers, compressing mid-tier competitors into commodity surgical mask segments where price competition intensifies.
REACH restrictions on perfluorinated compounds are forcing filtration media manufacturers to reformulate water-repellent treatments used in blood-borne pathogen resistance layers. German and French medical device distributors are accelerating qualification of fluorine-free alternatives, shifting supply contracts toward compliant suppliers ahead of enforcement deadlines.
Stockpile rotation contracts are displacing just-in-time purchasing in national health system procurement. The United States Strategic National Stockpile and Japan's national reserves are mandating vendor-managed inventory with guaranteed refresh cycles, locking manufacturers into multi-year supply agreements with penalty clauses for delivery failures.
Global Medical Mask Market Segmentation
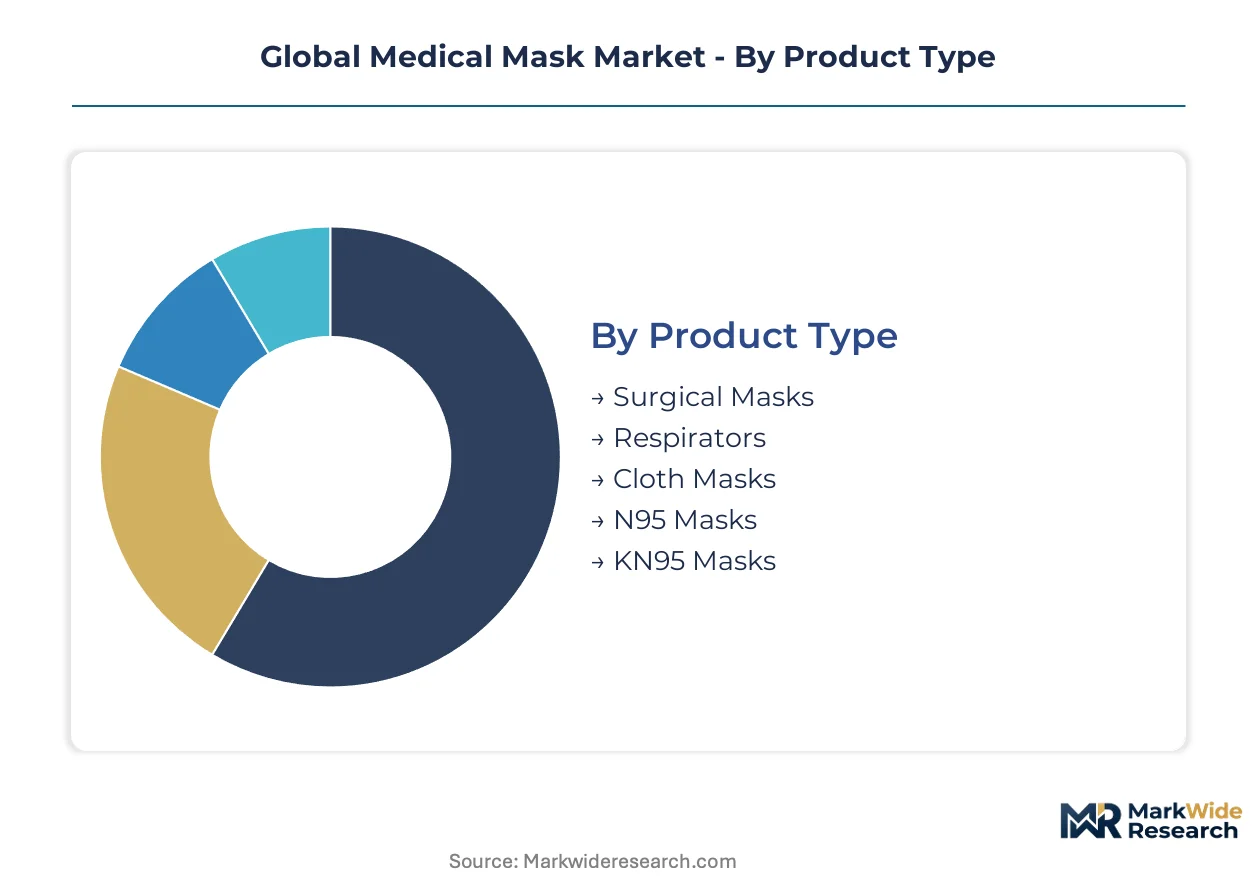
Medical mask segmentation reveals how procurement specifications, regulatory tiers, and material technologies fragment demand across healthcare settings. Understanding these divides exposes where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Supply concentration in melt-blown polypropylene fabrication favors manufacturers with captive nonwoven capacity, locking out commodity assemblers from high-specification segments.
- Surgical Masks:Three-ply spunbond-meltblown-spunbond construction delivers bacterial filtration efficiency above 95 percent. Hospital procurement in Germany and the United States concentrates volume here, though price compression intensifies as private-label producers expand capacity.
- Respirators:Tight-fitting devices with electrostatically charged filtration media require NIOSH certification under 42 CFR Part 84. OSHA-mandated annual fit-testing in US healthcare facilities institutionalizes replacement demand, sustaining premium pricing power.
- Cloth Masks:Reusable cotton or polyester blends lack standardized filtration validation, relegating them to community settings outside regulated healthcare environments.
- N95 Masks:NIOSH-approved particulate respirators with 95 percent minimum filtration efficiency against 0.3-micron particles anchor occupational health programs.
- KN95 Masks:Chinese GB 2626-2019 standard respirators face FDA emergency use authorization dependencies, constraining hospital adoption.
Today's leader: Respirators. Tomorrow's challenger: Nanofiber-enhanced surgical masks.
Application:
Cost tier stratification separates acute care mandates from elective procedure flexibility, with infection control liability driving specification divergence.
- Hospital Settings:Operating rooms and isolation wards demand fluid-resistant surgical masks or fit-tested respirators per Joint Commission standards. The United States and Japan concentrate spending here as tertiary centers expand negative-pressure capacity.
- Dental Procedures:Aerosol-generating interventions require ASTM Level 3 masks with 160 mmHg fluid resistance. US dental service organizations negotiate consolidated purchasing agreements, squeezing mid-tier distributors.
- Laboratory Use:Biosafety level protocols dictate respirator selection for airborne pathogen handling.
- Emergency Services:Pre-hospital providers balance portability against filtration in ambulance and field settings.
- Patient Care:General ward applications tolerate lower-specification masks where transmission risk remains moderate.
Volume concentrates in Hospital Settings. Steepest expansion trajectory: Emergency Services pre-positioning for pandemic readiness.
End User:
Customer type determines contract structure, with integrated delivery networks extracting volume discounts unavailable to fragmented purchasers.
- Hospitals:IDN procurement departments in the United States and Germany mandate vendor-managed inventory with stockpile rotation clauses. Cardinal Health and Medline capture share through direct distribution bypassing group purchasing organizations.
- Clinics:Outpatient facilities face lighter regulatory burden but growing OSHA scrutiny for respiratory protection programs.
- Laboratories:Research and diagnostic facilities require specialized respirators for chemical and biological hazards.
- First Responders:Fire departments and EMS agencies source through municipal procurement with extended replacement cycles.
- Elderly Care Centers:Long-term care facilities in Japan face heightened regulatory attention after pandemic mortality exposure.
Margin leader: Hospitals. Volume growth pivot: Elderly Care Centers.
Technology:
Material maturity curves separate proven melt-blown dominance from emerging nanofiber premium positioning.
- Melt-Blown Fabric:Polypropylene microfiber webs achieving 95 percent bacterial filtration efficiency anchor 80 percent of medical mask production. 3M and Kimberly-Clark control upstream resin and charging equipment supply.
- Nanofiber Filter:Electrospun polymer webs below 100 nanometers enable high particle capture at reduced breathing resistance. German and Japanese manufacturers pilot production for premium surgical segments.
- Electrostatic Filter:Corona-charged or tribocharged media enhance particle attraction without denser fiber packing.
- Activated Carbon:Adsorptive layers address nuisance odor in industrial healthcare settings.
- Breathable Membrane:Microporous films balance moisture vapor transmission with liquid barrier properties.
Established standard: Melt-Blown Fabric. Technology transition target: Nanofiber Filter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wuhan's nonwoven manufacturing corridor anchors global melt-blown polypropylene supply, with German and Japanese medical device clusters driving specification standards for hospital procurement.
United States
Hospital procurement departments mandate larger respiratory protection stockpiles under pandemic preparedness frameworks. OSHA's annual fit-testing requirement for healthcare workers sustains recurring N95 demand. The Strategic National Stockpile rotation contracts concentrate supply relationships around direct-distribution networks in the Midwest and Southeast hospital systems.
Germany
Tertiary care centers expand negative-pressure capacity, driving specification-grade surgical mask volumes. The EU Medical Device Regulation tightens filtration performance thresholds, filtering out uncertified suppliers. The Rhine-Ruhr industrial corridor hosts post-market surveillance infrastructure that supports MDR compliance for export-oriented manufacturers.
Japan
Elderly care facilities face heightened regulatory attention after pandemic mortality exposure in long-term care settings. METI coordinates national reserve stockpiles with vendor-managed inventory clauses. The Kansai region's medical device distributors accelerate qualification of fluorine-free water-repellent treatments ahead of REACH enforcement deadlines.
China
Domestic hospital infrastructure spending on infection control supports melt-blown fabric capacity expansion. NMPA alignment with international standards shapes export certification pathways for respirator manufacturers. The Yangtze River Delta concentration of electrostatic charging equipment suppliers creates single-source vulnerability for premium filtration media.
India
CDSCO medical device rules impose quality standards that compress informal manufacturer participation. Central government hospital procurement aggregates volume through the Government e-Marketplace platform. Maharashtra and Gujarat textile clusters pivot toward surgical mask assembly as polypropylene feedstock availability improves.
Global Medical Mask Market Competitive Landscape
Global majors compete with regional champions across certification infrastructure and direct-distribution reach. The market structures around three tiers: integrated healthcare suppliers with captive nonwoven capacity, specialized respirator manufacturers with NIOSH certification expertise, and private-label assemblers serving commodity surgical segments. Dominant competitive moves include backward integration into melt-blown polypropylene production and bypassing group purchasing organizations through vendor-managed inventory contracts with integrated delivery networks.
Within the integrated healthcare supplier tier, 3M and Kimberly-Clark Corporation represent archetypes of electrostatic charging technology control and direct hospital distribution dominance. Cardinal Health exemplifies scale-driven private-label production for North American integrated delivery networks. These three anchors illustrate how certification infrastructure and logistics integration separate premium positioning from commodity price competition.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Cardinal Health |
| Medline Industries |
| Ansell Ltd. |
| Kimberly-Clark Corporation |
| Owens & Minor |
| Prestige Ameritech |
| Moldex-Metric |
| Others |
Supply & Pricing Matrix
Captive melt-blown polypropylene production anchors both supply security and pricing power for tier-one manufacturers, while outsourced fabric dependence exposes commodity assemblers to margin compression when oil-linked feedstock costs spike. Hospital procurement departments in Germany and the United States leverage volume concentration to extract contract discounts, yet NIOSH-certified respirator suppliers retain premium positioning through fit-testing mandates that institutionalize replacement demand.
Pricing Analysis
Polypropylene resin pass-through mechanics dominate surgical mask pricing, with crude oil volatility transmitting directly to unit economics for non-integrated producers. Three-tier pricing structure across premium respirators, standard surgical masks, and economy-grade procedural masks reflects certification grade divergence and volume scale. Cost compression in standard surgical tiers is intensifying because private-label capacity expansion floods hospital group purchasing channels. Integrated delivery networks exhibit lowest price sensitivity due to liability-driven specification mandates, while outpatient clinics face acute budget constraints.
Supply Chain Analysis
Ocean freight rate volatility from Wuhan to Rotterdam and Long Beach shapes landed cost structures for European and North American distributors sourcing melt-blown media. Supply concentrates in China, Germany, and the United States, with the Yangtze River Delta hosting electrostatic charging equipment fabrication that feeds global respirator production. Raw material dependencies center on polypropylene resin, spunbond nonwoven backing, and fluorine-free water-repellent treatments reformulated under REACH restrictions. Single-source vulnerability in corona-treatment machinery creates chokepoint exposure for premium filtration media. Distribution runs through vendor-managed inventory contracts with integrated delivery networks and national stockpile programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement specifications hardening toward NIOSH-certified respirators and MDR-compliant surgical masks that filter out marginal suppliers.
For Market Incumbents: Cement certification infrastructure as the primary defensive moat by accelerating NIOSH submission pipelines and locking hospital systems into multi-year stockpile rotation agreements. Nanofiber filtration convergence from German and Japanese manufacturers threatens electrostatic melt-blown dominance, demanding R&D investment in electrospinning capabilities or strategic partnerships with substrate innovators. Backward integration into polypropylene resin compounding insulates margin structures from oil price volatility. For New Entrants and Emerging Players: Elderly care centers in Japan represent an underserved buyer archetype with heightened regulatory attention after pandemic mortality exposure and limited incumbent penetration. Fluorine-free water-repellent treatment qualification ahead of REACH enforcement deadlines opens white-space in European supply contracts. Direct distribution partnerships with municipal EMS procurement departments bypass consolidated hospital purchasing channels. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap respirator specialists with dormant NIOSH certifications because OSHA-mandated fit-testing institutionalizes recurring revenue streams resistant to price erosion. Five-to-ten-year viability hinges on biodegradability pipeline positioning ahead of EU Green Deal material mandates. The signal to watch is NIOSH approval timeline compression, which would strain working capital for uncertified aspirants and accelerate consolidation toward cleared suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Investment | OSHA-mandated fit-testing institutionalizes recurring demand for approved respirators in US healthcare. |
| Backward Integration into Melt-Blown Media | Captive polypropylene nonwoven production insulates margins from crude oil-linked feedstock volatility. |
| EU MDR Compliance Infrastructure | Post-market surveillance capabilities concentrate hospital procurement relationships among certified suppliers. |
| Nanofiber Filtration Partnership | Electrospinning technology access opens premium segments where breathability justifies cost premiums. |
| Vendor-Managed Inventory Contracts | Direct distribution to integrated delivery networks bypasses group purchasing organization margin extraction. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down melt-blown capacity tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at filtration media manufacturers combined with secondary validation from FDA 510(k) filings, NIOSH certification databases, EU MDR notified body records, and hospital procurement databases. Cross-referencing shipment data from customs records with disclosed capacity expansions at major nonwoven producers enables supply-side triangulation against demand-side purchasing surveys.
Historical trendline analysis of surgical mask and respirator volumes across the analysis window establishes baseline growth patterns segmented by product type, application setting, end-user category, and filtration technology. Modeled dimensions include certification tier, geographic regulatory cluster, and stockpile versus just-in-time procurement channel. CAGRs derive from regression analysis against healthcare infrastructure spending, infection control budget allocations, and pandemic preparedness framework adoption. Forecast inputs incorporate OSHA enforcement patterns, EU MDR transition timelines, and polypropylene price elasticity coefficients.
Underlying measurement precision varies by segment; NIOSH-certified respirator volumes carry tighter precision due to mandatory reporting requirements than commodity surgical mask estimates subject to private-label opacity. Forecasts reflect assumptions about regulatory enforcement intensity, oil price trajectory, and hospital consolidation pace that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Suture Tapes Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Luer Plug Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
Prepackaged Medical Kits and Trays Market