
 Direct Methanol Fuel Cell Market | 2026-2036
Direct Methanol Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Methanol Fuel Cell Market Intelligence
Direct sales channels for methanol fuel cell stacks is tilting toward system integrators and defense contractors who bundle power units with installation services. SFC Energy AG dominates European military and off-grid telecom deployments through captive engineering support. Toshiba Energy Systems & Solutions Corporation anchors Japanese demand with stationary backup systems for commercial buildings. Horizon Fuel Cell Technologies extends its position across Asian portable electronics supply chains through modular stack architectures.
A direct methanol fuel cell converts liquid methanol and ambient oxygen into electrical energy via an electrochemical reaction at temperatures typically below 120 degrees Celsius, employing a proton exchange membrane electrolyte and platinum-ruthenium catalyst layers on porous carbon electrodes. The technology serves applications requiring silent, refuelable power without hydrogen infrastructure dependence. Portable systems lead current shipment volumes due to soldier-borne electronics and remote sensor networks, while stationary installations capture stronger margins through long-duration backup contracts for telecom towers. Hybrid systems integrating methanol reforming with lithium buffering represent the fastest-expanding technology segment as users seek load-following capability without battery bulk.
The US EPA and FAA maintain distinct certification pathways for methanol fuel cells in stationary and aviation auxiliary applications, with the latter pushing developers toward crashworthy tank designs. Japan's METI coordinates national hydrogen and fuel cell standards through JIS certification, while the EU F-Gas Regulation indirectly steers adoption by restricting conventional refrigerants in remote cooling systems paired with off-grid power. Stakeholders must track evolving catalyst material restrictions under REACH and corresponding supply chain adjustments for ruthenium sourcing.
Market Dynamics
Hybrid system architectures are compressing the addressable market for pure-play methanol fuel cells as defense and telecom operators prioritize load-following capability over standalone simplicity. Platinum-ruthenium supply concentration and evolving catalyst material restrictions under REACH are forcing stack manufacturers toward alternative electrode formulations.
Growth Catalysts
- Japan's METI hydrogen roadmap:Revised subsidy frameworks for clean off-grid power channel investment toward lighter membrane technologies and accelerate stationary backup deployments.
- Soldier-borne electronics:Portable power requirements for dismounted operations pull compact fuel cell stacks into military procurement pipelines.
- South Korean defense modernization:Telecom operators and unmanned systems programs trial methanol-based auxiliary power for remote base stations.
Market Restraints
- Platinum-ruthenium price volatility:Precious metal input costs concentrate in South African and Russian supply corridors, compressing stack margins.
- Hydrogen infrastructure competition:PEM fuel cells with established refueling networks threaten methanol's infrastructure-independence advantage.
- REACH catalyst restrictions:Ruthenium sourcing compliance adds regulatory friction to European manufacturing footprints.
Strategic Opportunities
- Aviation auxiliary power:FAA crashworthy tank certification pathways open auxiliary power unit retrofit potential for regional aircraft.
- EU F-Gas Regulation:Restrictions on conventional refrigerants in remote cooling systems pair methanol fuel cells with off-grid thermal management.
- Lithium-methanol hybrid buffering:Convergence with battery energy storage creates premium pricing for load-following systems.
Industry Challenges
- Electrocatalyst synthesis expertise:Thin-film deposition and nanoparticle dispersion skill gaps constrain stack manufacturing scale-up.
- Multi-agency certification timelines:EPA stationary and FAA aviation pathways impose sequential testing burdens on product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Methanol Fuel Cell Market |
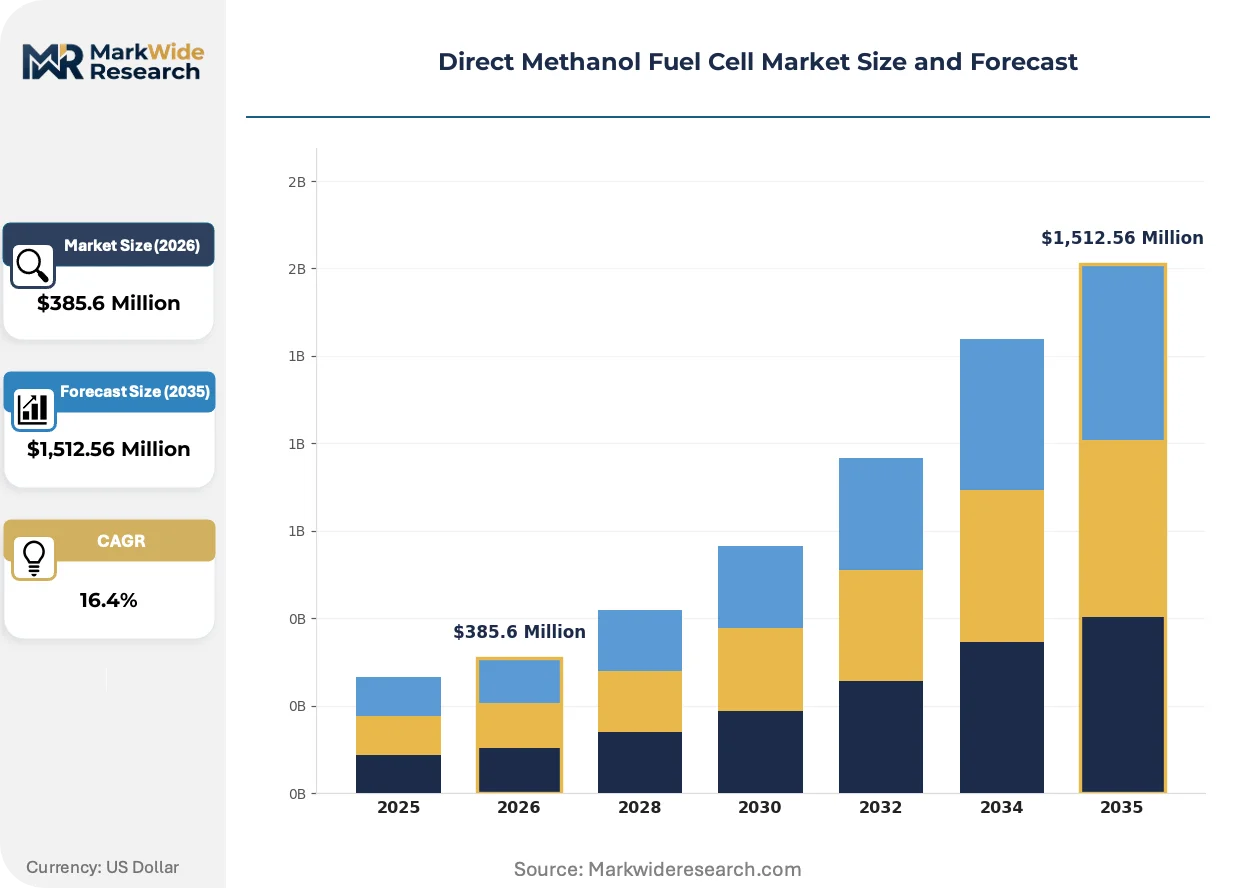
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,512.56 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Transportation, Military Technology: Proton Exchange Membrane, Passive Air Breathing, Active Air Supply, Hybrid Systems Application: Remote Power Supply, Backup Power, Auxiliary Power Units, Portable Electronics End User: Consumer Electronics, Defense Forces, Commercial Vehicles, Telecommunication |
| Companies Covered | Toshiba Energy Systems & Solutions Corporation, Roland Gumpert, Blue World Technologies, Oorja Protonics, MeOH Power, SFC Energy AG, Advent Technologies, Horizon Fuel Cell Technologies, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Methanol Fuel Cell Market Strategic Shifts & Innovations
Membrane electrode assembly architectures and system integration approaches are converging around hybrid configurations. Stack manufacturers compete on thermal management sophistication and refueling logistics rather than pure electrochemical efficiency.
Membraneless microfluidic fuel cell designs are hybridizing with conventional proton exchange membrane stacks to reduce platinum loading. Defense contractors in South Korea and Japan pilot these architectures for soldier-borne power. The technology is hybridizing cost structures by compressing precious metal requirements while maintaining energy density.
REACH authorization requirements for ruthenium compounds are tightening catalyst supply chain documentation. European stack manufacturers face reformulation deadlines or substitution investments. Stationary backup systems for commercial buildings encounter the steepest compliance cost escalation.
Telecom tower operators now unbundle power purchase agreements from equipment procurement. System integrators capture recurring revenue through fuel logistics and maintenance contracts. South Korean defense and telecom sectors display the most advanced service-contract penetration.
Direct Methanol Fuel Cell Market Segmentation
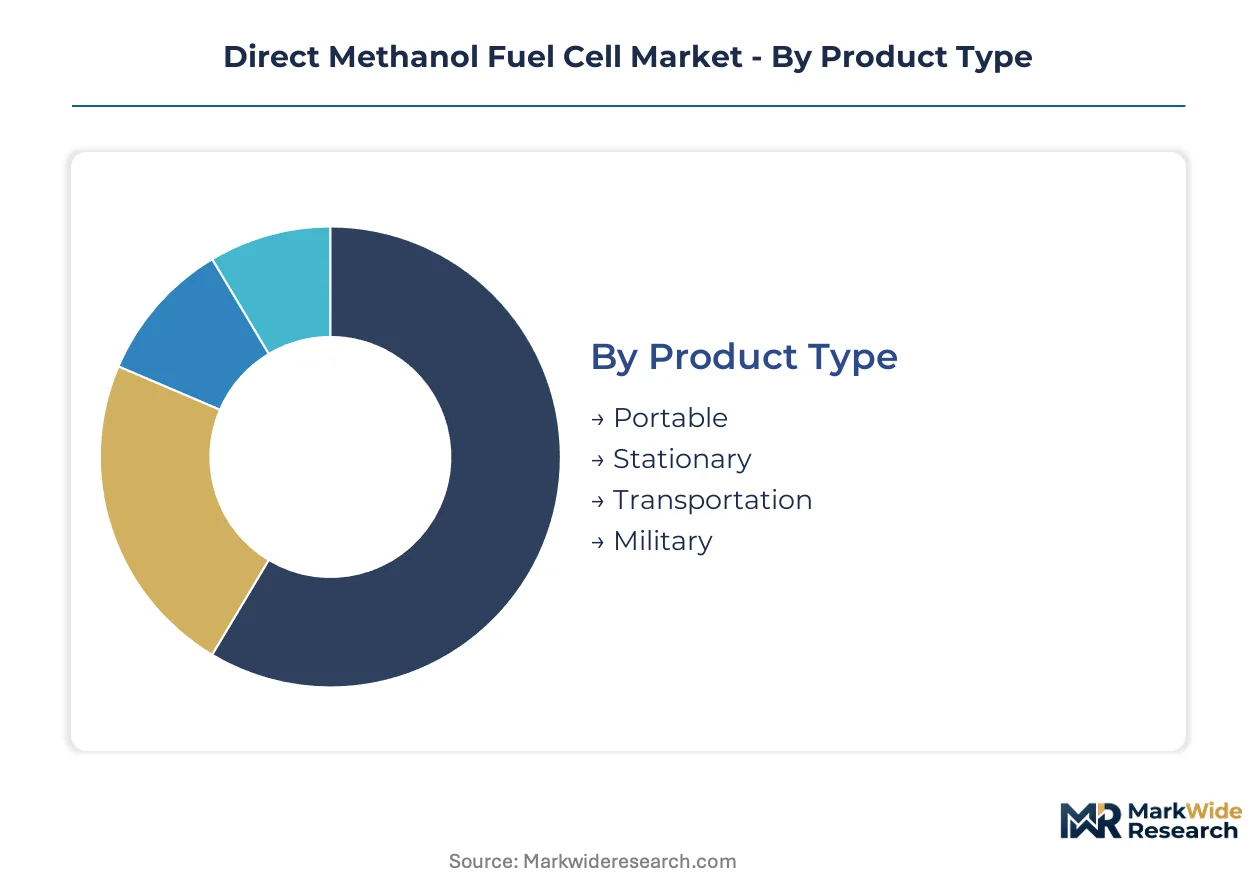
Direct methanol fuel cell deployments fragment sharply across mobility requirements and infrastructure constraints. Segmentation reveals how defense procurement, telecom backup contracts, and portable electronics supply chains pull technology development in divergent directions.
Product Type:
Use-case spectrum spans soldier-borne power to grid-independent telecom towers, with each application imposing distinct size, weight, and refueling logistics constraints.
- Portable:Compact stacks under 100W power dismounted soldier electronics and remote sensor networks. Japanese defense forces and South Korean unmanned systems programs drive procurement volumes through silent operation requirements.
- Stationary:Long-duration backup systems for commercial buildings and telecom towers command premium pricing through fuel logistics contracts. Toshiba Energy Systems anchors Japanese demand with integrated installation services.
- Transportation:Auxiliary power units for commercial vehicles face competition from battery-electric and hydrogen fuel cell alternatives. Limited methanol refueling infrastructure constrains fleet adoption outside captive logistics operations.
- Military:Ruggedized systems prioritize electromagnetic compatibility and crashworthiness over efficiency metrics. SFC Energy dominates European deployments through captive engineering support and field service networks.
The dominant share belongs to Portable, while Hybrid Systems integration is expanding most quickly across product categories.
Technology:
Cost tier stratification separates laboratory-grade membrane performance from field-deployable simplicity, with catalyst loading and thermal management representing the primary cost drivers.
- Proton Exchange Membrane:Standard architecture employing Nafion or hydrocarbon membranes with platinum-ruthenium catalyst layers. Japanese METI subsidies accelerate lighter membrane development for stationary applications.
- Passive Air Breathing:Eliminates blower power draw through natural convection cooling. Portable electronics manufacturers favor these stacks for consumer devices where acoustic signature and parasitic load matter.
- Active Air Supply:Forced air systems achieve higher power density through optimized cathode stoichiometry. Telecom backup installations in South Korea deploy active cooling for sustained high-output operation.
- Hybrid Systems:Lithium-methanol buffering combines fuel cell endurance with battery load-following. Defense and telecom operators prioritize this architecture for applications requiring rapid power transients without fuel cell ramp limitations.
Proton Exchange Membrane retains the installed base majority, though Hybrid Systems are gaining share fastest through premium pricing for integrated energy storage.
Application:
Customer procurement patterns separate capital equipment purchases from recurring fuel service contracts, with remote infrastructure operators driving the shift toward performance-based agreements.
- Remote Power Supply:Off-grid installations for environmental monitoring and border surveillance. South Korean defense modernization programs trial methanol systems against diesel generator alternatives.
- Backup Power:Stationary systems for commercial buildings and critical infrastructure. Japanese JIS certification requirements shape product specifications for grid-connected standby applications.
- Auxiliary Power Units:Aviation and vehicular applications requiring crashworthy tank designs. FAA certification pathways impose sequential testing burdens extending development timelines.
- Portable Electronics:Soldier-borne power and professional field equipment. Horizon Fuel Cell Technologies extends across Asian supply chains through modular stack architectures.
Backup Power commands the largest contract value, while Auxiliary Power Units are climbing the fastest as aviation retrofit programs advance.
End User:
Volume concentration varies dramatically across procurement sophistication, with defense and telecom buyers driving standardization while consumer electronics remains fragmented.
- Consumer Electronics:Niche camping and professional equipment markets. Portable electronics manufacturers accelerate procurement of compact stacks for premium outdoor power products.
- Defense Forces:Soldier-borne power and unmanned systems programs. South Korean and Japanese defense ministries specify methanol compatibility with existing logistics chains.
- Commercial Vehicles:Fleet auxiliary power and refrigeration units. Limited methanol distribution infrastructure constrains adoption to captive fleet operations with centralized fueling.
- Telecommunication:Remote base station backup and off-grid tower power. South Korean telecom operators display the most advanced service-contract penetration with unbundled fuel logistics.
Telecommunication holds the dominant revenue position, while Defense Forces are expanding most quickly through modernization procurement pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japanese stationary backup contracts while South Korean defense procurement drives volume absorption. German engineering-intensive military deployments sustain margin premiums through captive service networks. Regulatory divergence across METI subsidy frameworks, FAA certification pathways, and REACH catalyst restrictions fragments competitive positioning.
Japan
Stationary backup systems for commercial buildings anchor domestic procurement volumes. METI coordinates national hydrogen and fuel cell standards through JIS certification, accelerating lighter membrane technology development. Toshiba Energy Systems anchors demand in Tokyo-Osaka corridors with integrated installation services for grid-connected standby applications.
South Korea
Defense modernization programs and unmanned systems trials pull methanol-based auxiliary power into military procurement pipelines. MFDS maintains pharmaceutical-grade chemical oversight that indirectly shapes methanol purity specifications for fuel cell applications. Seoul Capital Area telecom operators display the most advanced service-contract penetration with unbundled fuel logistics agreements.
United States
Aviation auxiliary power unit retrofit programs advance through FAA crashworthy tank certification pathways. EPA maintains distinct stationary certification requirements that impose sequential testing burdens on product development cycles. Greater Boston and Pacific Northwest clusters host defense contractors piloting soldier-borne electronics power systems.
Germany
European military and off-grid telecom deployments sustain demand through engineering-intensive service contracts. ECHA REACH authorization requirements for ruthenium compounds tighten catalyst supply chain documentation for stack manufacturers. Bavaria and Baden-Württemberg industrial corridors concentrate stationary backup system integration expertise.
China
Portable electronics supply chains absorb compact fuel cell stacks for consumer and professional equipment markets. MIIT coordinates industrial standards for fuel cell technologies through GB certification frameworks. Pearl River Delta and Yangtze River Delta manufacturing clusters drive modular stack architecture production for regional export markets.
Direct Methanol Fuel Cell Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in membrane electrode assembly and catalyst formulation. Market structure tilts toward consolidated defense and telecom procurement channels where captive engineering support determines contract capture. Three archetypes dominate: Japanese conglomerates with stationary backup integration, German military specialists with field service networks, and Asian modular stack suppliers with electronics supply chain penetration. Competitive moves concentrate on hybrid system architecture development and alternative catalyst formulation to preempt REACH compliance costs.
Among Japanese integrated energy conglomerates, Toshiba Energy Systems & Solutions Corporation and Panasonic Corporation occupy positions in stationary backup and portable electronics tiers respectively. SFC Energy AG exemplifies the European military specialist archetype with German engineering-intensive deployment models. Horizon Fuel Cell Technologies represents the Asian modular architecture approach across portable electronics supply chains.
| Leading Market Players |
|---|
| Toshiba Energy Systems & Solutions Corporation |
| Roland Gumpert |
| Blue World Technologies |
| Oorja Protonics |
| MeOH Power |
| SFC Energy AG |
| Advent Technologies |
| Horizon Fuel Cell Technologies |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
The Shanghai-Rotterdam maritime corridor's container cost volatility compresses margins for stack manufacturers sourcing ruthenium catalyst precursors from South African refineries, while downstream price differentiation widens between defense contractors absorbing premium logistics and telecom operators negotiating fuel-service bundles.
Pricing Analysis
Configured-to-order pricing for ruggedized military stacks commands premium spreads over standard portable electronics units. Three-tier pricing structure across premium, standard, and economy levels stratifies by membrane performance grade and JIS certification tier. Cost compression in the economy tier intensifies because Chinese modular suppliers are absorbing platinum-ruthenium volatility through volume scale. Defense procurement channels exhibit least price sensitivity; consumer electronics distributors demonstrate highest.
Supply Chain Analysis
Extended payment terms from South Korean system integrators are reshaping working capital requirements for membrane electrode assembly specialists. Ruthenium refining concentrates in South Africa, platinum in Russia, and membrane fabrication in Japan and Germany. The stack supply chain rests on precious metal commodity volatility, membrane polymer feedstock availability, and precision catalyst deposition equipment. Single-source vulnerability concentrates in South African ruthenium corridor. Distribution runs through captive engineering-service contracts rather than component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where fuel logistics and maintenance contracts expand faster than hardware shipments, particularly among South Korean telecom operators unbundling power purchase agreements.
For Market Incumbents: Pre-empt REACH catalyst substitution deadlines by accelerating alternative electrode formulation R&D before reformulation costs escalate. Lock in ruthenium supply through long-term offtake agreements with South African refiners to defend margin position against precious metal volatility. Vertical integration into membrane electrode assembly production in Germany or Japan reduces regulatory compliance friction.
For New Entrants and Emerging Players: Establish a beachhead in lithium-methanol hybrid buffering systems where defense and telecom procurement is concentrating fastest. Portable electronics supply chains offer penetrable entry through modular stack architectures compatible with existing Asian manufacturing clusters. Lead with FAA crashworthy tank certification as differentiated go-to-market angle for aviation auxiliary power retrofits.
For Investors and Strategic Acquirers: Carve-out targets emerge from Japanese industrial conglomerates seeking to divest non-core stationary backup divisions amid hydrogen infrastructure competition. Five-to-ten year viability hinges on hybrid system architecture dominance and catalyst material substitution success. Monitor FAA certification completion timelines as inflection indicator for aviation auxiliary power unit retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Catalyst Formulation | Preempts REACH ruthenium authorization costs for European manufacturing footprints. |
| Hybrid System Architecture Development | Captures premium pricing from defense and telecom load-following requirements. |
| FAA Crashworthy Tank Certification | Unlocks aviation auxiliary power retrofit opportunity in regional aircraft segments. |
| Fuel Logistics Service Contracts | Converts capital equipment sales into recurring revenue streams with telecom operators. |
| Membrane Electrode Assembly Scale-Up | Addresses thin-film deposition skill gaps constraining stack manufacturing expansion. |
Research Approach
A spread of perspectives from stack manufacturing engineers, defense procurement officers, telecom infrastructure planners, and catalyst supply specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with membrane electrode assembly technologists and fuel cell system integrators with secondary validation through METI subsidy disclosure filings, FAA certification docket reviews, ECHA REACH authorization updates, and customs trade data on platinum-group metal flows. Bottom-up shipment estimates triangulated against top-down addressable market sizing across the analysis window.
Demand-supply balance modeling anchored forecast outputs, with segmentation across portable, stationary, transportation, and military product types; proton exchange membrane, passive air breathing, active air supply, and hybrid system technologies; and remote power supply, backup power, auxiliary power unit, and portable electronics applications. CAGRs derived from installed base evolution, replacement cycle analysis, and penetration rate assumptions for hybrid architectures. Key inputs included defense modernization procurement pipeline disclosures and telecom tower electrification timelines.
Stress conditions across platinum-ruthenium price bands, REACH authorization timeline delays, and hydrogen infrastructure buildout rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on subsidy continuity and certification pathway efficiency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Global Micro Fuel Cells Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
Fuel Cell Interconnectors Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Membrane Electrode Assembly Market