
 Africa Drilling and Completion Fluids Market | 2026-2036
Africa Drilling and Completion Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Drilling and Completion Fluids Market Outlook
Synthetic fluid formulations is tilting the Africa drilling and completion fluids technology stack toward higher-performance, lower-toxicity systems. Baker Hughes Company leverages its integrated drilling services footprint to anchor synthetic fluid supply across West African offshore contracts. Halliburton Company sustains competitive positioning through specialized deepwater fluid engineering capabilities in Angolan waters. Schlumberger Limited dominates the high-barrier offshore segment with proprietary synthetic systems engineered for high-pressure, high-temperature African basins.
Drilling and completion fluids are engineered liquid and slurry systems—typically comprising weighted brines, synthetic base fluids, or water-based blends with barite, bentonite, and chemical additives—circulated during well construction to control formation pressure, transport cuttings, and stabilize boreholes. Their primary commercial purpose is enabling safe, efficient hydrocarbon extraction while minimizing formation damage and environmental release. Water-based fluids retain cost leadership across onshore African markets, while synthetic fluids command premium positioning in deepwater Nigeria and Angola where regulatory standards restrict oil-based discharge. Oil-based fluids face structural decline as environmental compliance tightens, compressing margin pools in legacy onshore workover operations.
Nigeria's Department of Petroleum Resources enforces local content quotas that reshape procurement patterns for drilling contractors, while Angola's petroleum regulator mandates environmental impact assessments for offshore fluid discharge. Ghana's Petroleum Commission applies ISO-aligned standards for drilling waste management, elevating compliance costs for service providers. Stakeholders must monitor how diverging national local-content rules reshape supplier eligibility and fluid system selection across the continent's producing basins.
Market Dynamics
Synthetic base fluid systems are displacing legacy oil-based formulations across West African offshore operations, driven by tightening discharge regulations and pre-salt drilling complexity.
Growth Catalysts
- Angolan pre-salt exploration:Deepwater blocks off Cabinda and Kwanza Basin require high-performance synthetic fluids for HPHT well conditions, pulling specialized formulation demand.
- Nigerian local content mandates:The Department of Petroleum Resources enforces domestic sourcing thresholds that redirect procurement toward indigenous fluid blending facilities.
- Synthetic base fluid technology:Advanced ester-based and internal olefin systems deliver superior thermal stability and biodegradability ratings versus mineral oil alternatives.
Market Restraints
- Barite supply concentration:Weighting agent sourcing clusters with Chinese and Moroccan producers, exposing African blenders to freight cost volatility and currency fluctuation risk.
- High synthetic fluid cost structure:Ester and olefin base stocks trade at 3-4x premium to diesel-based equivalents, compressing contractor margins on fixed-dayrate contracts.
- Angolan environmental licensing:The petroleum regulator's extended impact assessment timelines delay offshore campaign starts by 4-8 months versus regional peers.
Strategic Opportunities
- Ghanaian offshore development:Tweneboa-Enyenra-Ntomme and Sankofa fields present untapped synthetic fluid demand as production ramps toward 200,000 bpd targets.
- Modular blending infrastructure:Containerized fluid plants near Port Harcourt and Luanda reduce logistics costs and satisfy local content rules without permanent facility investment.
- Drill cuttings reinjection technology:Zero-discharge systems pair with synthetic fluids to eliminate seafloor discharge permitting entirely, creating regulatory arbitrage in sensitive blocks.
Industry Challenges
- HPHT fluid engineering expertise:Deepwater Angola operations require rheologists and chemists capable of formulating above 350°F bottom-hole temperatures, a skillset concentrated with legacy IOC personnel.
- Multi-jurisdiction compliance complexity:Operators working Nigeria-Angola-Ghana rotations must maintain three distinct waste management certifications and fluid specification databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Drilling and Completion Fluids Market |
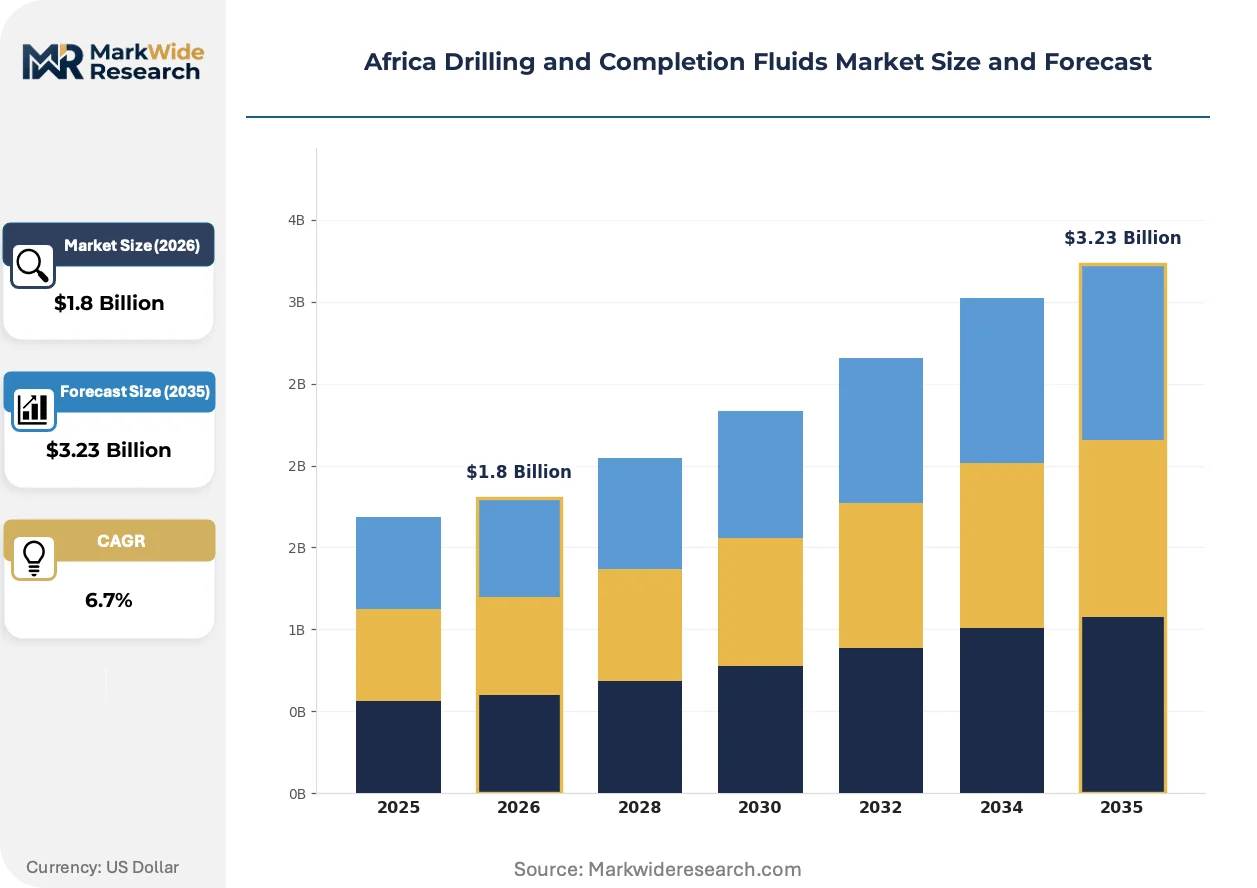
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Fluids, Oil-Based Fluids, Synthetic Fluids, Foam Fluids Application: Onshore Drilling, Offshore Drilling, Workover Operations, Completion Operations End User: Oil Exploration Companies, Service Providers, Drilling Contractors, Mining Operators Distribution Channel: Direct Sales, Distributors, Online Sales, Retailers |
| Companies Covered | Baker Hughes Company, Halliburton Company, Schlumberger Limited, Weatherford International Plc, National Oilwell Varco Inc, Newpark Resources Inc, CES Energy Solutions Corp, Superior Energy Services Inc, Tetra Technologies, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Drilling and Completion Fluids Market Strategic Shifts
Digital fluid monitoring systems and biodegradable additive packages are reconfiguring how operators manage downhole chemistry and environmental liability across African basins.
Real-time downhole fluid analysis is virtualizing traditional mud logging workflows. Offshore contractors in Nigerian deepwater blocks now deploy sensor-integrated drillstrings that transmit density, viscosity, and gas readings to shore-based centers. This architecture is virtualizing the need for dedicated offshore mud engineers, compressing headcount requirements while accelerating formation response times.
Ghana's Petroleum Commission has aligned drilling waste management standards with ISO 14001 and OSPAR protocols, eliminating the regulatory gap that previously allowed lower-cost disposal methods. The commission now mandates third-party certification for all cuttings treatment systems before offshore deployment. Deepwater operators have responded by pre-qualifying only synthetic fluid systems with established biodegradability documentation.
Integrated service contracting is consolidating historically fragmented procurement. Nigerian independents and marginal field operators now favor single-source agreements covering fluids, solids control, and waste management versus discrete vendor relationships. This preference shift is most visible in the Niger Delta onshore segment, where smaller acreage holders lack technical staff to coordinate multi-vendor logistics.
Africa Drilling and Completion Fluids Market Segmentation
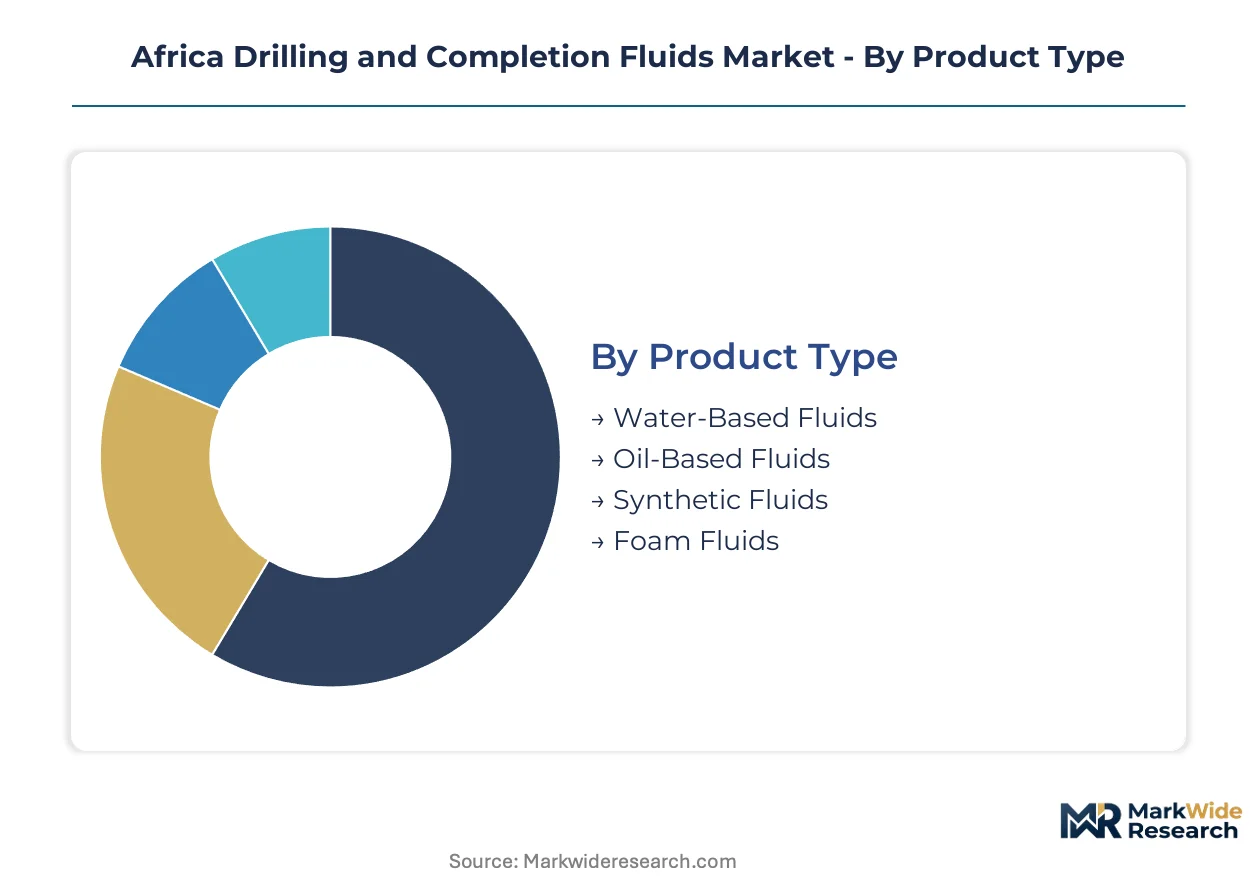
Fluid system selection in African hydrocarbon basins hinges on balancing formation characteristics against regulatory discharge limits. Each product category carries distinct cost profiles and environmental compliance footprints that reshape contractor procurement across Nigeria's Niger Delta and Angola's pre-salt blocks.
Product Type:
Cost tier differentiation separates commodity formulations from engineered synthetic systems across West African drilling campaigns.
- Water-Based Fluids:Bentonite-weighted aqueous systems dominate Niger Delta onshore operations where shallow well depths and porous formations tolerate lower-density chemistry. Nigerian independents favor these formulations for marginal field development where dayrate economics compress fluid budgets.
- Synthetic Fluids:Ester-based and internal olefin formulations command premium positioning in Angolan deepwater blocks where HPHT conditions exceed 350°F bottom-hole temperatures and environmental regulators prohibit oil-based discharge. Cabinda operators specify these systems for pre-salt exploration where thermal stability and biodegradability ratings determine permit eligibility.
- Oil-Based Fluids:Diesel-mineral oil blends retain residual demand in legacy onshore workover operations across mature Nigerian fields where regulatory grandfathering delays full synthetic conversion.
- Foam Fluids:Nitrogen-stabilized systems address underbalanced drilling applications in depleted Niger Delta reservoirs where formation pressure has dropped below hydrostatic norms.
Water-Based Fluids hold installed capacity. Synthetic Fluids is rotating up the share rankings.
Application:
Volume concentration tracks exploration intensity across offshore frontiers versus mature basin workover cycles.
- Offshore Drilling:Deepwater campaigns in Angola's Kwanza Basin and Ghana's Tweneboa-Enyenra-Ntomme fields pull high-performance synthetic fluid volumes where subsea completions demand zero-discharge chemistry. Extended-reach wells here circulate 15,000+ barrels per wellbore.
- Onshore Drilling:Niger Delta cluster drilling and Ghana's onshore Voltaian Basin operations consume water-based and low-synthetic blends where logistics infrastructure supports bulk delivery and waste management costs remain manageable.
- Workover Operations:Mature field interventions across Nigeria's Ogoniland and Angola's Cabinda onshore stripper wells require minimal fluid volumes with rapid deployment turnaround.
- Completion Operations:Gravel pack and fracturing fluid systems in pre-salt completions demand specialized brine chemistry with precise density control for sand control integrity.
Offshore Drilling commands the steepest expansion trajectory. Onshore Drilling retains volume leadership in barrel terms.
End User:
Customer type stratification reflects capital access and technical staffing depth across the African operator landscape.
- Oil Exploration Companies:IOCs and NOCs including Nigerian Petroleum Development Company and Sonangol P&P specify fluid systems directly, leveraging in-house drilling engineering teams to qualify formulations for HPHT pre-salt conditions.
- Drilling Contractors:Transocean, Seadrill, and local Nigerian drilling firms procure fluids as part of integrated well construction packages, passing through costs on dayrate or turnkey contracts.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes supply formulated systems through integrated service contracts covering fluids, solids control, and waste management.
- Mining Operators:Limited penetration in geothermal and mineral exploration drilling across East African Rift systems where water-based systems suffice for shallow coring operations.
Oil Exploration Companies dictate technical specifications. Service Providers are consolidating procurement influence through integrated contracting.
Distribution Channel:
Supply concentration patterns mirror the physical infrastructure constraints of African port logistics and local content mandates.
- Direct Sales:Major fluid blenders including Baker Hughes and Halliburton maintain direct relationships with IOC drilling departments, bypassing intermediaries for deepwater campaign volumes where technical service integration is mandatory.
- Distributors:Indigenous Nigerian suppliers including Dangote Oil & Gas and regional Angolan blenders serve NOC and independent operators through stocking agreements at Port Harcourt and Luanda port facilities.
- Online Sales:Minimal penetration limited to additive chemicals and spare parts procurement by remote onshore drilling camps with satellite connectivity.
- Retailers:Negligible channel presence given bulk volume requirements and specialized handling protocols for weighted drilling fluids.
Direct Sales anchors premium offshore volumes. Distributors are capturing share in Nigerian local content-compliant procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Africa's drilling and completion fluids trade flows reflect concentrated import dependency for synthetic base stocks and barite weighting agents, with limited indigenous blending capacity forcing reliance on Port Harcourt and Luanda port infrastructure for formulation and distribution.
Nigeria
Niger Delta deepwater blocks and marginal field developments drive synthetic fluid demand for HPHT well conditions. The Department of Petroleum Resources enforces local content quotas mandating domestic sourcing thresholds for drilling services. Port Harcourt anchors fluid blending infrastructure where indigenous suppliers co-locate with international service companies to satisfy procurement rules.
Angola
Pre-salt exploration in the Kwanza Basin and Cabinda offshore blocks pulls high-performance synthetic formulations for subsea completions. The petroleum regulator mandates extended environmental impact assessments for offshore fluid discharge permits. Luanda serves as the primary logistics hub where containerized blending plants reduce import lead times for deepwater campaigns.
Ghana
Tweneboa-Enyenra-Ntomme and Sankofa field developments generate synthetic fluid demand as production targets approach 200,000 barrels per day. The Petroleum Commission applies ISO 14001-aligned drilling waste management standards that elevate compliance costs. Takoradi port facilities support offshore supply chains with third-party certification requirements for cuttings treatment systems.
Egypt
Offshore Mediterranean gas discoveries and onshore Western Desert drilling sustain water-based and synthetic fluid consumption for extended-reach wells. The national petroleum regulator oversees environmental compliance for discharge protocols in sensitive offshore blocks. Alexandria and Port Said concentrate fluid logistics infrastructure serving IOC operators in the Nile Delta and offshore concessions.
Mozambique
Rovuma Basin LNG development and deepwater exploration create nascent demand for zero-discharge synthetic systems in ultra-deepwater blocks. The national petroleum institute administers environmental licensing for offshore drilling campaigns. Maputo and Pemba ports handle limited fluid volumes as infrastructure scales to support future LNG feedstock drilling.
Africa Drilling and Completion Fluids Market Competitive Environment
On the supply side, the industry is consolidated around integrated oilfield service majors with captive fluid formulation capabilities, while regional blenders compete for local content-compliant procurement in Nigerian and Angolan onshore segments. Three archetypes dominate: full-service integrated providers controlling technology and supply chains; independent fluid specialists competing on price for standard formulations; and indigenous joint ventures satisfying domestic sourcing mandates. Competitive dynamics center on strategic partnerships with NOCs for integrated service contracts and modular blending infrastructure investments near port logistics hubs.
Among the integrated service tier, Baker Hughes Company, Halliburton Company, and Schlumberger Limited exemplify the technology-intensive archetype with proprietary synthetic systems engineered for African HPHT conditions. These entities occupy positions spanning formulation chemistry through waste management integration, anchoring premium pricing in deepwater Nigeria and Angola where technical service bundling determines contract awards. Regional procurement influence is consolidating through single-source agreements covering fluids, solids control, and environmental compliance.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Halliburton Company |
| Schlumberger Limited |
| Weatherford International Plc |
| National Oilwell Varco Inc |
| Newpark Resources Inc |
| CES Energy Solutions Corp |
| Superior Energy Services Inc |
| Tetra Technologies |
| Others |
Value Chain & Pricing Dynamics
Port Harcourt-Luanda freight corridors transmit cost volatility from Chinese barite loading ports directly into African blender margins, while synthetic base stock premiums widen the technology gap between deepwater contractors and onshore independents. Diesel-mineral oil legacy formulations retain cost anchoring in Nigerian workover markets where regulatory grandfathering delays full synthetic conversion, compressing procurement flexibility for marginal field operators.
Pricing Analysis
Synthetic-versus-oil-based pricing gaps structure contractor procurement across West African offshore campaigns, with ester and internal olefin systems commanding substantial premiums over diesel-based equivalents. Three-tier pricing structure across premium synthetic, mid-grade water-based, and economy oil-based levels differentiates by HPHT certification grade and environmental compliance documentation. Pricing pressure stems from fixed-dayrate contracts that prevent pass-through of base stock cost spikes to NOC clients. Nigerian independents exhibit highest price sensitivity in marginal field developments where fluid budgets compress dayrate economics, while Angolan pre-salt operators demonstrate lowest sensitivity given permit eligibility requirements.
Supply Chain Analysis
Extended payment terms from Angolan petroleum regulator licensing delays force blenders to carry 4-8 month working capital exposure before campaign revenue recognition. Barite weighting agent sourcing concentrates with Chinese and Moroccan producers, while synthetic base stock manufacturing anchors in North American and European specialty chemical complexes. Supply chain risk manifests as single-source vulnerability for high-purity barite grades essential for HPHT density requirements. Distribution runs through integrated service contracts where Baker Hughes, Halliburton, and Schlumberger bundle formulation with solids control and waste management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drilling and completion fluids markets reward service-attach depth where integrated waste management and real-time monitoring subscriptions expand recurring revenue faster than commodity fluid volumes. Environmental compliance layers now generate margin premiums exceeding base formulation economics.
For Market Incumbents: Pre-empt modular blending infrastructure deployment near Port Harcourt and Luanda to capture local content procurement before indigenous joint ventures consolidate Nigerian NOC relationships. Defend synthetic fluid technology leadership through proprietary HPHT additive packages that lock in Angolan pre-salt specifications. Backward integration into barite toll-processing agreements mitigates Chinese supply concentration risk. For New Entrants and Emerging Players: Ghanaian offshore development gaps present immediate white-space opportunity as Tweneboa-Enyenra-Ntomme production ramps toward capacity targets without established fluid supply relationships. East African Rift geothermal drilling offers secondary penetration path where water-based systems suffice and integrated majors maintain limited presence. Containerized blending plant leasing models satisfy local content rules without permanent facility capital deployment. For Investors and Strategic Acquirers: Regional fluid specialists with existing Nigerian Petroleum Commission certification and Port Harcourt port access represent priority acquisition archetypes for integrated service majors seeking local content compliance shortcuts. Long-term viability hinges on synthetic formulation IP depth rather than commodity blending capacity. Watch Angolan environmental licensing timeline compression as inflection signal—accelerated permitting would unlock campaign starts and pull forward synthetic fluid demand.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Blending Infrastructure Deployment | Containerized plants near Port Harcourt satisfy Nigerian local content mandates without permanent capital commitment. |
| Synthetic Base Stock Backward Integration | Captive ester and olefin supply secures margin control against specialty chemical price volatility. |
| Zero-Discharge Technology Certification | Drill cuttings reinjection systems paired with synthetic fluids eliminate Angolan seafloor discharge permitting entirely. |
| Integrated Service Contract Consolidation | Single-source agreements covering fluids, solids control, and waste management capture Nigerian independent procurement. |
| Real-Time Downhole Monitoring Platform | Sensor-integrated drillstrings virtualize offshore mud engineer headcount while accelerating formation response. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drilling contractors, NOC procurement directors, fluid formulation chemists, and environmental compliance officers across Nigerian, Angolan, and Ghanaian operations. Secondary validation drew from Nigerian Department of Petroleum Resources local content filings, Angolan petroleum regulator environmental impact assessments, Ghana Petroleum Commission ISO 14001 certification records, and SEC 10-K disclosures from integrated service companies. Bottom-up well count and fluid volume estimates triangulated against top-down market value reconstructions.
Calibration against historical campaign data and disclosed contract values anchored the projection framework across the analysis window. Segmentation dimensions modeled include fluid system technology tier, application category across offshore and onshore drilling, end-user type from IOCs to independents, and distribution channel structure. CAGRs derived from weighted average of bottom-up volume trajectories and top-down value expansion. Industry-specific inputs incorporated Angolan pre-salt well complexity indices and Nigerian marginal field development schedules.
Macroeconomic conditions sit as an overlay; deviation in Brent crude price corridors, naira and kwanza exchange rate volatility, or Chinese barite export tariff regimes would shift the trajectory. Forecasts reflect assumptions documented across stakeholder interviews and secondary sources. Regulatory acceleration in Angolan environmental licensing, synthetic base stock technology breakthroughs, or West African pipeline infrastructure completion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Smart Pigging Market
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Smart Well Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Well Testing Services Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
Thailand Oil and Gas Upstream Market