
 Alkaline Fuel Cell Market | 2026-2036
Alkaline Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Alkaline Fuel Cell Market Outlook
Germany is rewriting deployment timelines for alkaline fuel cell capacity through its national hydrogen strategy and dedicated electrolyzer corridors. AFC Energy PLC leverages its ammonia-cracking integration to sustain project pipelines across European industrial zones. GenCell Ltd. anchors off-grid backup deployments with alkaline systems that operate without platinum-group catalysts. Toyota Motor Corporation dominates transportation-linked fuel cell R&D, though its alkaline-adjacent work extends into stationary power through partnership networks.
Alkaline fuel cells employ potassium hydroxide electrolyte, typically at concentrations of 30-45 percent, operating at 60-90°C with nickel-based electrodes that eliminate precious metal dependence. This electrochemical architecture delivers primary industrial and commercial purpose through long-duration, zero-emission power generation for facilities requiring continuous baseload or resilient backup. Stationary installations occupy the largest margin pool given their scale and integration complexity with existing grid infrastructure. Portable segments lead unit volume growth through military and emergency services procurement, while transportation applications compete with proton-exchange alternatives on start-up dynamics and power density benchmarks.
The EU Green Deal and F-Gas Regulation shape product standards by restricting fluorinated components in competing proton-exchange membranes, indirectly advantaging alkaline architectures. Japan's METI hydrogen roadmap and South Korea's MFDS equipment certification framework direct public subsidy toward domestically manufactured fuel cell stacks, influencing supply chain localization decisions. Stakeholders must monitor electrolyte management advances and catalyst degradation rates as the decisive variables for total cost of ownership comparisons against solid-oxide and PEM alternatives.
Market Dynamics
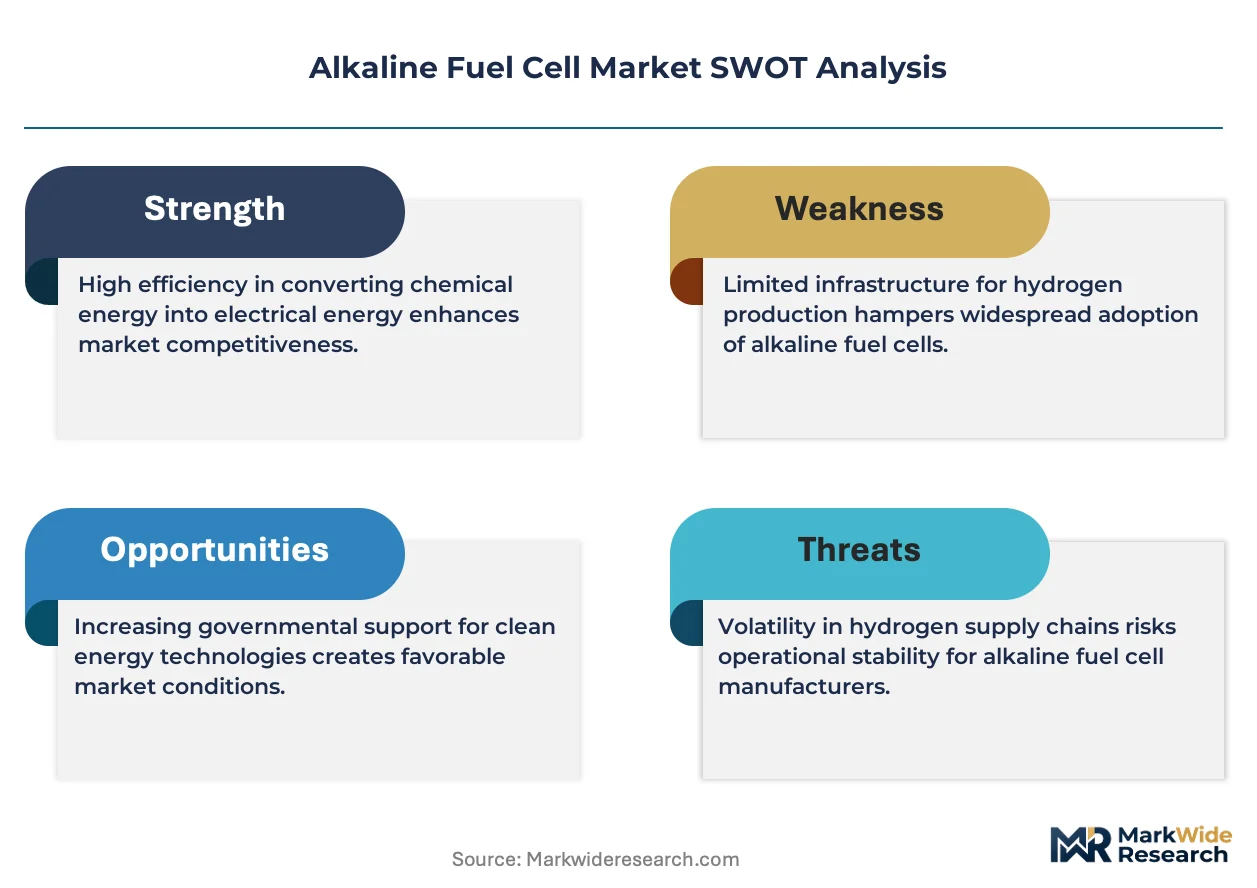
The EU F-Gas Regulation is compressing competitive alternatives by restricting fluorinated components in proton-exchange membranes, redirecting industrial procurement toward alkaline architectures that use potassium hydroxide electrolyte and nickel-based electrodes without precious metal dependence.
Growth Catalysts
- Data center baseload demand:Hyperscale facilities in Germany and Japan require continuous zero-emission power that alkaline fuel cells provide through 24/7 operation without grid dependency.
- China's dual carbon goals:MEE emissions benchmarks tighten industrial power standards, accelerating deployment of zero-emission baseload technologies in manufacturing corridors.
- South Korea's MFDS certification:The equipment framework directs public subsidy toward domestically manufactured fuel cell stacks, creating localized procurement pipelines.
Market Restraints
- Electrolyte management costs:Potassium hydroxide concentration maintenance at 30-45 percent requires continuous monitoring systems that inflate operational expenditure.
- Catalyst degradation rates:Nickel electrode performance decay under thermal cycling limits stack lifetime compared to solid-oxide alternatives.
- PEM substitution threat:Proton-exchange membrane systems capture transportation applications through superior start-up dynamics and power density benchmarks.
Strategic Opportunities
- Ammonia cracking integration:Industrial zones in Germany and the Netherlands are piloting alkaline systems with ammonia-to-hydrogen conversion for off-grid chemical processing.
- Military portable procurement:Emergency services and defense agencies in Japan and South Korea are expanding unit volume through ruggedized field deployments.
- EU Green Deal alignment:The emissions framework creates regulatory tailwind for alkaline architectures that avoid fluorinated membrane components entirely.
Industry Challenges
- Electrolyte handling certification:Corrosive potassium hydroxide management requires specialized technician training that extends deployment timelines.
- Grid integration complexity:Stationary installations face synchronization challenges with existing electrical infrastructure that demand custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkaline Fuel Cell Market |
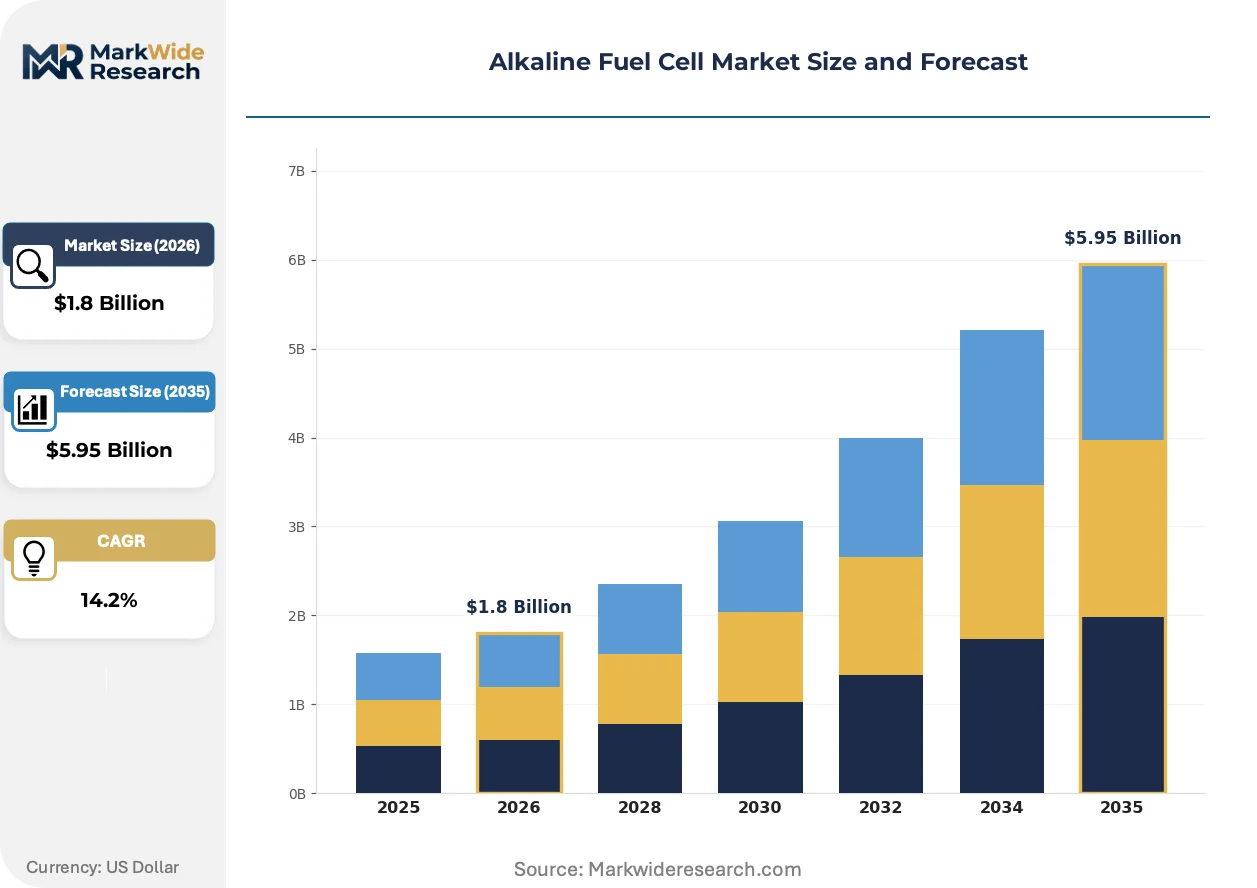
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Backup, Automotive End User: Commercial, Industrial, Residential, Government Application: Power Generation, Transportation, Emergency Services, Material Handling Size: Micro, Small, Medium, Large |
| Companies Covered | GenCell Ltd., Toyota Motor Corporation, AFC Energy PLC, ITM Power Plc, NGK Insulators, Ltd., Plug Power Inc., FuelCell Energy Inc., Nel ASA, Ballard Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkaline Fuel Cell Market Strategic Shifts
Electrochemical architecture refinement is compressing total cost of ownership differentials against competing fuel cell technologies. Three developments are redirecting competitive positioning across stationary power, portable emergency systems, and industrial heat applications.
Advanced electrolyte circulation systems are digitizing operational monitoring through real-time concentration and temperature telemetry. Data center operators in Germany and Japan are adopting these sensor-integrated stacks to optimize maintenance scheduling. The technology is digitizing predictive service models that reduce unplanned downtime.
The EU F-Gas Regulation restricts perfluorinated compounds in competing membrane technologies. Industrial equipment manufacturers face reformulation costs or technology switching decisions. Stationary power segments are responding fastest by specifying alkaline architectures in new procurement tenders.
Power purchase agreements for continuous baseload are displacing traditional equipment ownership in data center and telecom applications. Energy service companies in South Korea and Germany now contract for guaranteed uptime rather than selling hardware. This restructuring concentrates buyer leverage with operators who can integrate fuel cells with on-site hydrogen storage.
Alkaline Fuel Cell Market Segmentation
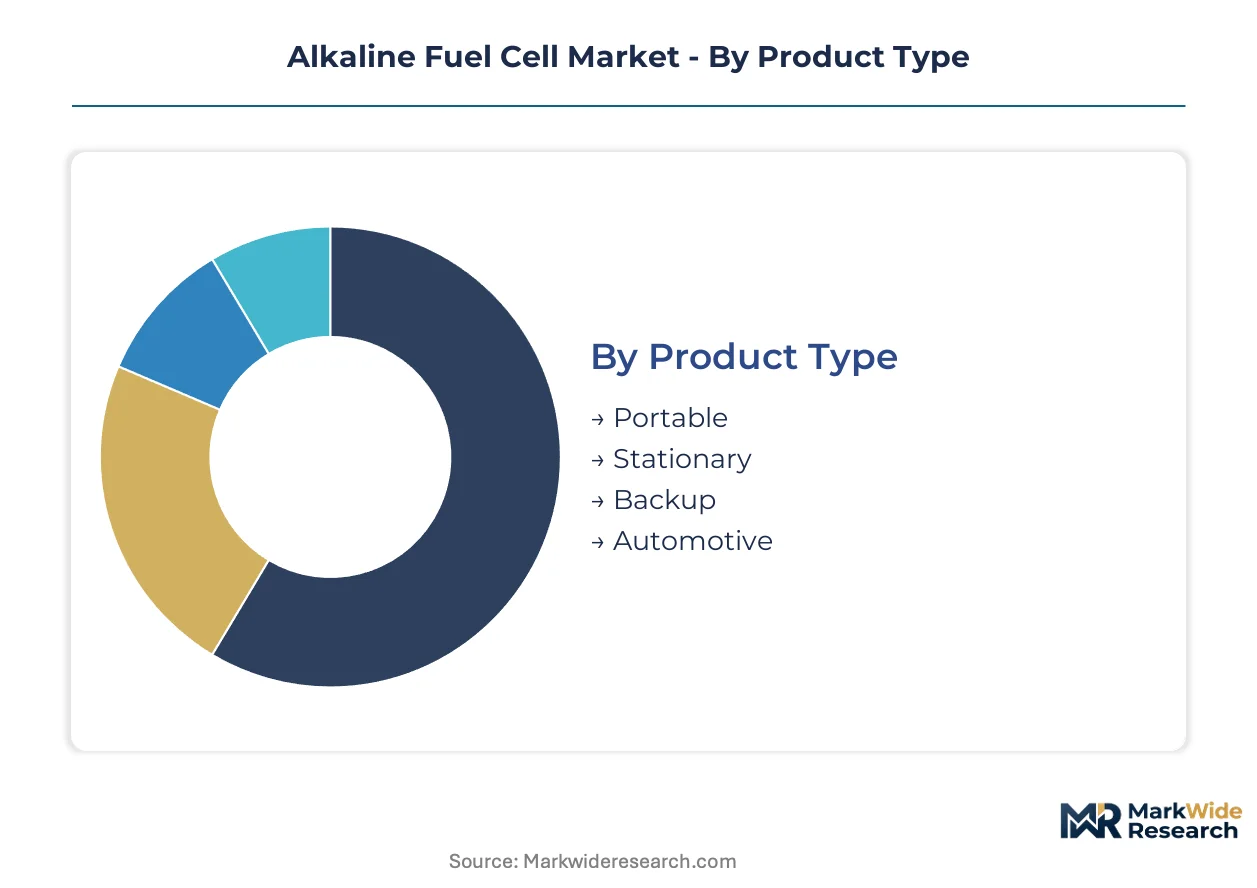
Alkaline fuel cell architectures diverge sharply across deployment contexts. Product form factor, end-user procurement authority, and application duty cycle each dictate distinct electrolyte management requirements and electrode specifications that reshape competitive positioning.
Product Type:
Application context determines physical packaging and thermal management architecture across alkaline fuel cell systems.
- Stationary:Grid-tied installations integrate 60-90°C potassium hydroxide stacks with continuous electrolyte circulation for data center baseload in Germany and Japan. Hyperscale operators specify nickel-electrode systems for 24/7 uptime without grid dependency.
- Portable:Ruggedized units eliminate external thermal management through passive cooling designs. Military and emergency services procurement in South Korea and Japan drives unit volume through field-deployable configurations.
- Backup:Standby systems prioritize rapid activation sequences for telecom infrastructure resilience. Off-grid installations in industrial zones favor ammonia-cracking integration for hydrogen autonomy.
- Automotive:Transportation applications compete with proton-exchange alternatives on start-up dynamics and volumetric power density benchmarks.
Stationary systems command the established base. The steepest expansion runs through portable military procurement.
End User:
Procurement authority shapes electrolyte handling certification requirements and maintenance contracting structures.
- Industrial:Manufacturing facilities deploy large-format stacks for process heat and captive power generation. China's MEE emissions benchmarks accelerate zero-emission baseload adoption in chemical processing corridors.
- Commercial:Data center operators contract for guaranteed uptime through power purchase agreements rather than equipment ownership. Energy service companies in Germany and South Korea consolidate buyer leverage through hydrogen storage integration.
- Government:Public procurement frameworks direct subsidy toward domestically manufactured stacks under South Korea's MFDS certification and Japan's METI hydrogen roadmap.
- Residential:Distributed micro-installations face cost barriers from electrolyte monitoring systems and specialized technician requirements.
Industrial deployments anchor current revenue concentration. Government procurement channels are climbing the fastest.
Application:
Duty cycle characteristics determine electrode degradation profiles and stack replacement economics.
- Power Generation:Continuous baseload operation maximizes capacity factor and amortizes capital expenditure across extended service intervals. Grid synchronization requirements demand custom engineering for electrical infrastructure integration.
- Emergency Services:Intermittent activation cycles accelerate nickel electrode thermal fatigue. Defense agencies specify ruggedized portable units for disaster response and field medical support.
- Transportation:Start-stop dynamics favor proton-exchange membrane alternatives with superior cold-start performance and power density metrics.
- Material Handling:Warehouse forklift fleets utilize mid-size stacks for indoor emissions compliance. Distribution centers in Germany pilot alkaline systems for 24/7 logistics operations.
Power generation retains the dominant revenue share. Emergency services procurement is expanding most quickly.
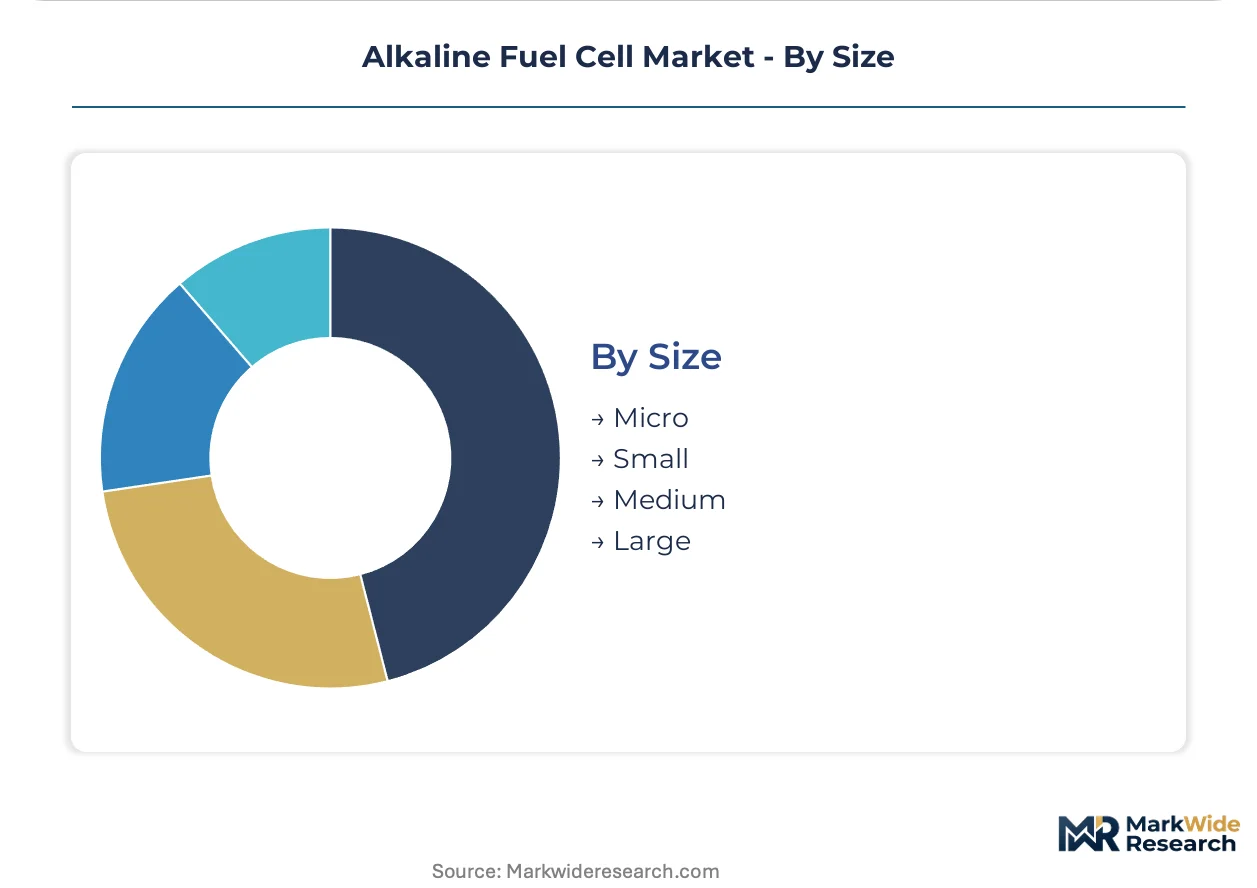
Size:
Scale determines electrolyte volume management complexity and thermal regulation architecture.
- Large:Grid-scale installations exceed 1 MW output with centralized potassium hydroxide reservoir systems. Data center operators in Germany and Japan specify large-format stacks for baseload displacement of grid electricity.
- Medium:Industrial process heat applications balance footprint constraints against thermal efficiency optimization. Manufacturing corridors in China deploy medium-scale systems for emissions-compliant captive power.
- Small:Distributed commercial installations serve telecom backup and remote facility electrification. South Korean energy service companies aggregate small-stack portfolios into guaranteed uptime contracts.
- Micro:Sub-kilowatt units target portable military and emergency services deployment. Field units eliminate precious metal dependence through nickel-based electrode architectures.
Large installations command the established base. Micro-scale portable systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Germany, Japan, China, South Korea, and the United States, where national hydrogen strategies and emissions regulations are accelerating alkaline fuel cell deployment across industrial corridors and data center clusters.
Germany
Hyperscale data center operators in Frankfurt and Berlin demand continuous zero-emission baseload that alkaline systems provide through 24/7 operation. The EU Green Deal and F-Gas Regulation restrict fluorinated membrane components, redirecting procurement toward potassium hydroxide architectures. Industrial zones in North Rhine-Westphalia pilot ammonia-cracking integration for off-grid chemical processing.
Japan
Telecom infrastructure resilience and disaster response capabilities drive stationary and portable deployments across the archipelago. METI's hydrogen roadmap directs public subsidy toward domestically manufactured fuel cell stacks under JIS certification frameworks. The Kanto region around Tokyo anchors manufacturing concentration for nickel-electrode systems serving grid-scale storage applications.
China
Manufacturing corridors in the Yangtze River Delta face tightening MEE emissions benchmarks under dual carbon goals that favor zero-emission baseload technologies. State-directed investment flows into electrolyzer and fuel cell stack production for captive industrial power. Jiangsu and Zhejiang provinces host pilot installations for process heat in chemical processing facilities.
South Korea
MFDS equipment certification frameworks direct public procurement toward domestically manufactured alkaline stacks for government and utility applications. Energy service companies in Seoul aggregate small-stack portfolios into guaranteed uptime contracts with hydrogen storage integration. The Busan-Ulsan industrial complex deploys medium-scale systems for emissions-compliant captive power in petrochemical operations.
United States
Data center operators in Virginia and Texas seek grid-independent baseload as reliability concerns mount across regional transmission organizations. EPA emissions standards and state-level clean energy mandates create regulatory tailwind for zero-emission technologies. The Pacific Northwest explores ammonia-to-hydrogen conversion for off-grid backup in remote facility electrification.
Alkaline Fuel Cell Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in electrode and electrolyte circulation subsystems. The vendor base organizes around three archetypes: diversified industrial conglomerates with fuel cell divisions, pure-play electrochemical technology developers, and energy service companies bundling hardware with uptime guarantees. Competitive moves concentrate on strategic partnerships for ammonia-cracking integration and geographic expansion through certified manufacturing localization.
Within the pure-play electrochemical tier, AFC Energy PLC and GenCell Ltd. exemplify differentiated technology positioning, while Toyota Motor Corporation anchors the diversified industrial archetype with cross-sector fuel cell R&D spanning transportation and stationary applications. These three entities represent distinct strategic postures: ammonia-to-hydrogen integration specialization, ruggedized off-grid deployment focus, and platform-scale manufacturing leverage across partnership networks.
| Leading Market Players |
|---|
| GenCell Ltd. |
| Toyota Motor Corporation |
| AFC Energy PLC |
| ITM Power Plc |
| NGK Insulators, Ltd. |
| Plug Power Inc. |
| FuelCell Energy Inc. |
| Nel ASA |
| Ballard Power Systems |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese nickel electrode supply determines both pricing tier spreads and supply chain shape, compressing margins for European and Japanese stack assemblers while amplifying procurement leverage for integrated conglomerates with captive metallurgical capacity.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across alkaline fuel cell procurement, separating JIS-certified Japanese stacks from MFDS-certified South Korean alternatives and uncertified economy-tier imports. Price differentiation rests on electrolyte management system sophistication and nickel electrode purity grades, with hyperscale data center operators in Germany and Japan exhibiting lowest price sensitivity due to uptime guarantees. Cost compression in the portable military segment is intensifying because South Korean defense procurement consolidates volume under single-source national champions.
Supply Chain Analysis
Contract manufacturing concentration sits with NGK Insulators in Japan and domestic state-linked fabricators in China for electrode substrate production. Supply draws from Indonesia and the Philippines for nickel laterite feedstock, South Korea for precision electrolyte circulation pumps, and Germany for ammonia-cracking integration modules. Single-source vulnerability concentrates in potassium hydroxide membrane supply from Chinese chemical processors. Distribution runs through energy service companies in Germany and South Korea that bundle hardware with hydrogen storage and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale data center operators and government procurement agencies that aggregate demand under long-term power purchase agreements, fragmenting vendor pricing power across fragmented equipment suppliers.
For Market Incumbents: Pre-empt PEM substitution in transportation-adjacent stationary applications by accelerating ammonia-cracking integration partnerships in North Rhine-Westphalia and Rotterdam industrial zones. Defend electrode supply security through backward integration into Indonesian nickel processing or binding offtake agreements with metallurgical specialists, as Chinese export licensing tightens under dual carbon enforcement. For New Entrants and Emerging Players: Establish a beachhead in South Korean military portable procurement under MFDS certification pathways, where domestic content requirements create protected demand pools. Target German telecom backup segments through ruggedized micro-stack offerings that eliminate precious metal dependence, leveraging the EU F-Gas Regulation's fluorinated membrane restrictions as competitive wedge against PEM incumbents. For Investors and Strategic Acquirers: South Korea's MFDS certification deadline reshapes the acquisition landscape toward certified domestic manufacturers with established government procurement pipelines. Long-term viability centers on stack producers with demonstrated electrolyte management IP and ammonia-to-hydrogen integration capabilities. Monitor catalyst degradation rate improvements as the decisive signal for total cost of ownership convergence with solid-oxide alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Cracking Integration | Enables off-grid hydrogen autonomy for German chemical processing corridors under EU emissions benchmarks. |
| Domestic Certification Investment | MFDS and JIS pathways unlock public subsidy flows in South Korea and Japan procurement frameworks. |
| Electrolyte Circulation IP Development | Real-time concentration telemetry reduces unplanned downtime for German data center baseload contracts. |
| Nickel Electrode Supply Security | Indonesian metallurgical partnerships mitigate Chinese export licensing risk under tightening MEE enforcement. |
| Power Purchase Agreement Structuring | Guaranteed uptime contracts concentrate buyer leverage with South Korean energy service aggregators. |
Study Parameters
The analysis maps stationary baseload, portable military, and backup telecom segments, each validated through fuel cell system engineers, data center procurement directors, and defense agency technical evaluators. Primary interviews with utility planning officers, EPC contractors, and hydrogen supply specialists combined with secondary validation from FERC interconnection filings, IEA hydrogen deployment databases, and national hydrogen roadmap publications. Bottom-up stack shipment data triangulates against top-down power capacity installations across the projection horizon.
Assumptions held electrolyte concentration maintenance costs and nickel electrode degradation curves constant across scenarios, while varying ammonia-cracking adoption rates and PEM substitution pressure in transportation applications. The analytical framework models product type, end-user procurement authority, application duty cycle, and regional regulatory cluster segmentation. CAGRs derive from capacity factor optimization curves and electrolyte management learning rates, with hydrogen storage integration economics and grid synchronization cost trajectories as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity tariffs, nickel commodity volatility, or Chinese dual carbon enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions without forward revision guarantees. Quarterly review of MFDS certification issuance rates, German electrolyzer corridor commissioning timelines, and potassium hydroxide export licensing patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Hydrogen Recirculation Blower for Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Aircraft Fuel Cell Market