
 Southeast Asia Oil and Gas Downstream Market | 2026-2036
Southeast Asia Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Oil and Gas Downstream Market Analytics
Maintenance and reliability contracting is pivoting from episodic repairs to continuous performance guarantees across Southeast Asian refineries. PT Pertamina leverages its monopoly over Indonesian downstream infrastructure to anchor national fuel security. Petroliam Nasional Berhad sustains integrated petrochemical margins through its Pengerang complex. Shell plc competes on digital refining analytics and carbon management services.
Southeast Asia oil and gas downstream encompasses crude oil refining, natural gas processing, and the manufacture of fuels, petrochemicals, and specialty products with typical refinery complexity indices ranging from 6 to 12 depending on coking and hydrocracking capacity. The sector supplies transportation energy, plastics feedstock, and industrial heat to ASEAN manufacturing bases. Refined fuels retain the largest value share due to persistent gasoline and diesel demand across Indonesia, Thailand, and Vietnam. Petrochemical products represent the fastest-expanding segment as regional plastic consumption and export-oriented manufacturing climb. Storage and processing services capture disproportionate margins where import dependency and strategic reserve obligations concentrate tank farm and terminal investments.
Indonesia's B20-B40 biodiesel mandate from the Ministry of Energy and Mineral Resources forces refinery reconfiguration toward lighter crude slates and co-processing units. Thailand's Department of Alternative Energy Development and Efficiency enforces biofuel blending standards that alter product mix economics. Vietnam's Ministry of Industry and Trade regulates petroleum product imports through quota and storage licensing frameworks. Stakeholders must monitor how carbon border adjustments and IMO marine fuel sulfur rules redirect capital toward residue upgrading and hydrogen production units.
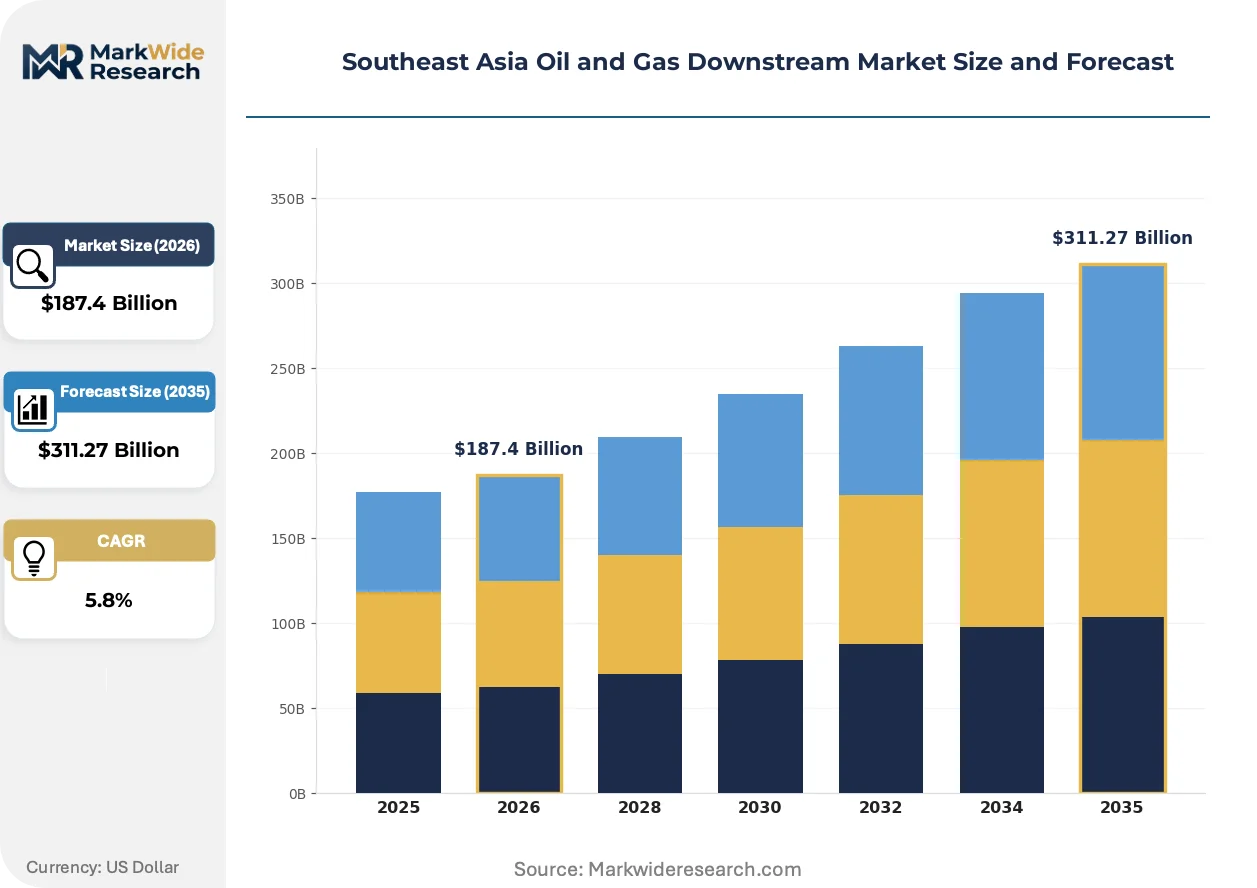
Market Dynamics
Indonesia's B20-B40 biodiesel mandate is forcing refinery reconfiguration across Southeast Asia, compelling operators to invest in co-processing units and lighter crude slates while reshaping product mix economics throughout the regional downstream chain.
Growth Catalysts
- Automotive Petrochemical Demand:ASEAN automotive manufacturers are accelerating consumption of polymer feedstocks for lightweight vehicle components, pulling propylene and aromatics through integrated refinery-petrochemical complexes in Thailand and Vietnam.
- Biofuel Mandate Escalation:Indonesia's Ministry of Energy and Mineral Resources B20-B40 framework is creating dedicated demand for fatty acid methyl ester co-processing infrastructure and hydrotreated vegetable oil units.
- Marine Fuel Sulfur Rules:IMO 2020 low-sulfur regulations are redirecting capital toward residue upgrading and vacuum gas oil hydrotreaters at Singapore and Malaysian marine bunkering hubs.
Market Restraints
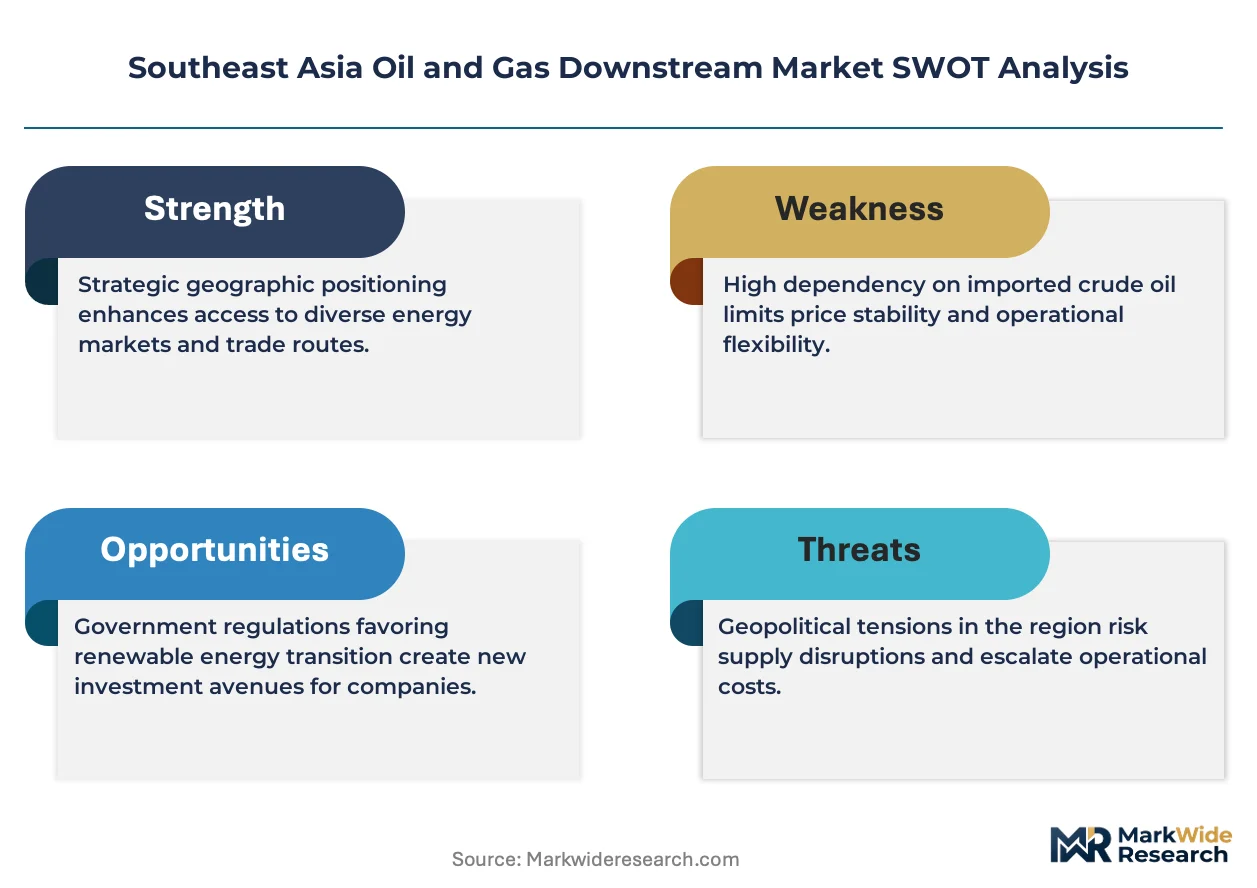
- Crude Import Dependency:Southeast Asian refiners source over three-quarters of feedstock from Middle Eastern and African suppliers, exposing margin volatility to OPEC+ production decisions and Suez Canal transit disruptions.
- Carbon Border Adjustment Exposure:The EU Carbon Border Adjustment Mechanism threatens export competitiveness for ASEAN petrochemical derivatives destined for European automotive and packaging end-uses.
- Residue Upgrading Capex Burden:Heavy sour crude processing capability requires coker and hydrocracker investments exceeding $2 billion per complex, concentrating viable projects among state-backed operators.
Strategic Opportunities
- Vietnam Industrial Corridor Expansion:The Dung Quat and Nghi Son refining clusters are capturing plastics demand from northern Vietnam's electronics assembly and textile manufacturing zones.
- Hydrogen Production Integration:Refinery off-gas capture and electrolysis projects are positioning Singapore and Thailand as regional low-carbon hydrogen hubs for ammonia and synthetic fuel synthesis.
- Digital Twin Analytics:Predictive maintenance platforms are opening performance-based contracting models for reliability services across Indonesian and Malaysian downstream assets.
Industry Challenges
- Specialized Process Engineering Talent:Deep conversion unit design and catalyst selection expertise remains concentrated among a limited pool of contractors, constraining project execution timelines.
- Legacy Control System Integration:Southeast Asian refineries built in the 1990s require DCS migration and cybersecurity hardening before advanced analytics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Oil and Gas Downstream Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemical Products, Lubricants, Asphalt Service Type: Transportation, Storage, Processing, Distribution End User: Automotive, Aviation, Marine, Industrial Distribution Channel: Direct Sales, Retail Outlets, Wholesalers, Online Platforms |
| Companies Covered | PTT Public Company Limited, PT Pertamina, Petroliam Nasional Berhad, Shell plc, Exxon Mobil Corporation, Vietnam Oil and Gas Group, Perusahaan Gas Negara Tbk, Chevron Corporation, TotalEnergies SE, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Oil and Gas Downstream Market Evolving Landscape
Electrification of process heat and hydrogen production is disrupting traditional fired-heater economics across Southeast Asian refineries. Digitalization and regulatory tightening are compressing the viable technology window for conventional conversion units.
Electrolytic hydrogen production is electrifying refinery fuel gas systems and hydrocracker hydrogen supply chains. Thai and Singaporean operators are piloting 100-megawatt alkaline and PEM electrolyzer installations. This technology is electrifying the cost structure of residue upgrading, displacing steam methane reforming in new project economics.
Thailand's Department of Alternative Energy Development and Efficiency biofuel blending standards are mandating ethanol and biodiesel percentages that alter gasoline and diesel pool optimization. Refiners must reconfigure FCC naphtha treatment and diesel hydrotreater severity to meet oxygenate specifications. The PTT Group and regional independents are responding with dedicated biofuel import terminals and co-processing revamps.
Refinery reliability contracting is migrating from time-and-materials to availability guarantees with penalty clauses. Indonesian national oil company procurement divisions are unbundling maintenance from operations, creating standalone performance contracts. This shift is most visible in Java-based refining clusters where Pertamina is trialing five-year integrated service agreements.
Southeast Asia Oil and Gas Downstream Market Segmentation
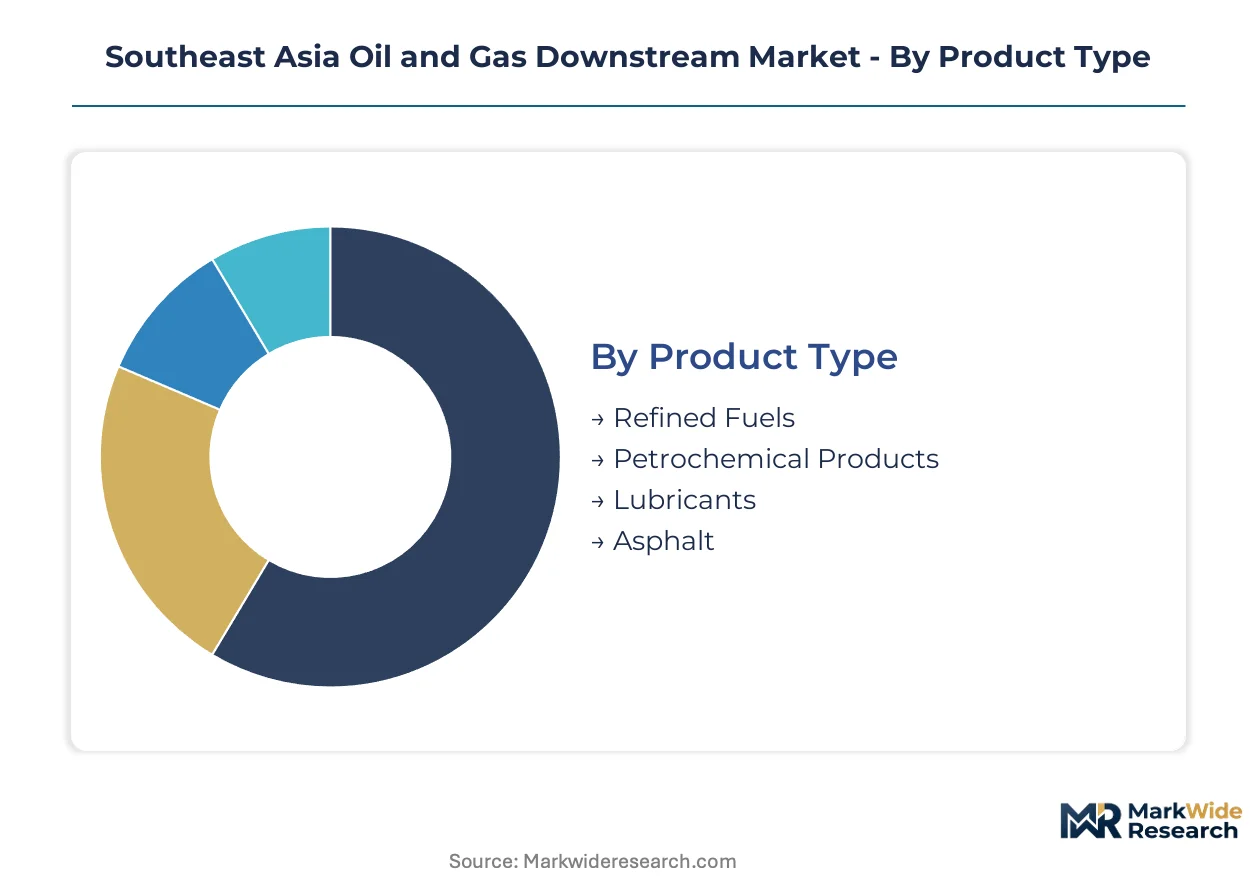
Segmentation in Southeast Asian downstream oil and gas reveals how refinery configuration, logistics infrastructure, and regulatory mandates fragment value capture across distinct product-service combinations. Each dimension carries divergent margin profiles and capital intensity requirements.
Product Type:
Volume concentrates in transportation fuels while premium margins concentrate in petrochemical derivatives and specialty products.
- Refined Fuels:Gasoline, diesel, and jet kerosene constitute the foundational output of Indonesian and Thai refineries. Demand from Vietnam's industrial corridor and Indonesia's Java-based vehicle fleet sustains throughput at Pertamina and PTT Group complexes. The B20-B40 biodiesel mandate is forcing co-processing investments that alter diesel pool economics.
- Petrochemical Products:Polymer feedstocks including propylene, aromatics, and olefins command superior margins through integration with ASEAN automotive and electronics manufacturing. Thailand's Pengerang complex and Vietnam's Nghi Son cluster anchor regional supply to plastics converters and textile producers. This segment is expanding most quickly as lightweight vehicle components and packaging demand accelerate.
- Lubricants:High-viscosity base oils and finished lubricants serve industrial machinery and commercial fleet maintenance across Malaysian and Singaporean distribution networks.
- Asphalt:Road construction binders derived from vacuum residue processing supply infrastructure projects in Indonesia's Trans-Java toll road expansion and Philippine highway development.
Today's leader: Refined Fuels. Tomorrow's challenger: Petrochemical Products.
Service Type:
Margin distribution follows asset ownership concentration, with processing and storage commanding premium returns in import-dependent markets.
- Transportation:Pipeline networks, coastal tankers, and road tanker fleets move products from Singapore's Jurong Island storage hub to Indonesian archipelago terminals and Thai provincial depots. Marine logistics dominate inter-country movements given archipelagic geography.
- Storage:Strategic petroleum reserve obligations and commercial tank farm operations generate stable fee income at locations including Indonesia's Tanjung Priok and Vietnam's Dung Quat. Import dependency across ASEAN elevates terminal utilization and lease rates.
- Processing:Crude distillation, conversion, and treating services transform feedstock into specification products. Complexity indices ranging from 6 to 12 determine yield structures and margin capture at Indonesian and Malaysian refineries.
- Distribution:Wholesale product movements to industrial off-takers and retail network supply constitute the lowest-margin service tier with highest volume throughput.
Processing assets absorb the capital. Storage assets capture the rent.
End User:
Customer concentration varies by product specification, with aviation and marine demanding certified fuels and automotive absorbing standardized gasoline and diesel pools.
- Automotive:Passenger vehicles, commercial trucks, and two-wheelers consume the majority of gasoline and biodiesel-blended diesel output across Indonesia, Thailand, and Vietnam. Biofuel mandates directly shape product formulation for this segment.
- Aviation:Jet A-1 kerosene specifications require dedicated hydrotreating and additive injection at Singapore Changi and Bangkok Suvarnabhumi supply points. International airline procurement concentrates volume at major hub airports.
- Marine:IMO 2020 low-sulfur fuel oil and marine gas oil specifications have redirected Singapore and Malaysian bunker hub investments toward residue upgrading and desulfurization capacity.
- Industrial:Power generation, cement manufacturing, and chemical processing plants consume fuel oil, naphtha, and natural gas liquids across ASEAN manufacturing zones.
Automotive pulls the volume. Aviation and marine pull the specification premiums.
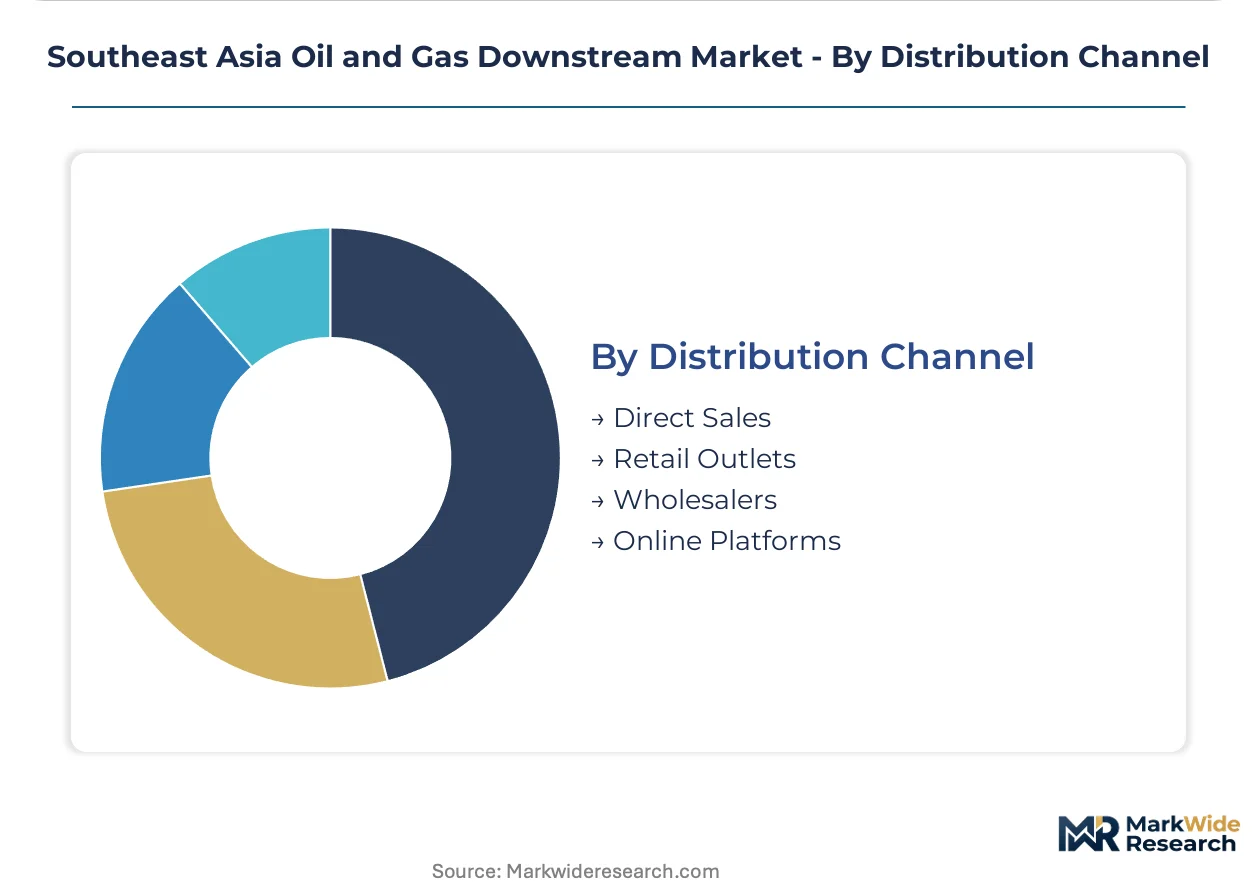
Distribution Channel:
Channel economics reflect customer scale and product standardization, with direct sales to large industrial off-takers outperforming fragmented retail networks.
- Direct Sales:Long-term offtake contracts with power utilities, petrochemical plants, and mining operations provide volume certainty and reduced marketing overhead for Indonesian and Thai refiners.
- Retail Outlets:Branded service station networks including Pertamina's SPBU and PTT's retail footprint compete on location density and loyalty programs in urban Indonesian and Thai markets.
- Wholesalers:Independent distributors supply provincial markets, construction sites, and agricultural users across archipelagic and mainland Southeast Asia where direct refiner presence is uneconomical.
- Online Platforms:Digital fuel ordering and fleet card management systems are emerging in Singapore and Malaysian commercial segments, though physical delivery infrastructure remains the binding constraint.
Direct sales dominate industrial margins. Retail networks dominate consumer presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery operators across Southeast Asia exploit regulatory gaps between national biofuel mandates and carbon accounting standards to optimize margin capture. Indonesia's aggressive biodiesel escalation and Thailand's integrated petrochemical complexes attract capital that might otherwise deploy to stricter jurisdictions. Vietnam's industrial corridor and Singapore's marine bunkering hub complete the arbitrage map.
Indonesia
Java-based vehicle fleets and archipelagic marine transport sustain gasoline and diesel demand at Pertamina's Cilacap and Balikpapan refineries. The Ministry of Energy and Mineral Resources enforces B20-B40 biodiesel mandates that force co-processing investments and lighter crude slate selection. The Java refining cluster anchors national fuel security through state-controlled infrastructure monopoly.
Thailand
ASEAN automotive manufacturing pulls polymer feedstocks through PTT Group's integrated refinery-petrochemical complexes. The Department of Alternative Energy Development and Efficiency mandates ethanol and biodiesel blending percentages that alter gasoline pool optimization. The Map Ta Phut and Pengerang industrial zones concentrate residue upgrading capacity for regional marine fuel supply.
Vietnam
Northern electronics assembly and textile manufacturing zones drive plastics demand through the Dung Quat and Nghi Son refining clusters. The Ministry of Industry and Trade regulates petroleum product imports through quota and storage licensing frameworks. The Nghi Son complex captures premium margins from China-adjacent industrial demand.
Singapore
IMO 2020 marine fuel specifications redirect bunker hub investments toward residue upgrading and desulfurization capacity at Jurong Island. The Maritime and Port Authority enforces low-sulfur fuel oil standards that concentrate high-complexity refining investments. The island storage and processing hub arbitrages regional crude differentials for Asian shipping lanes.
Malaysia
Petroliam Nasional Berhad's Pengerang complex sustains integrated petrochemical margins through deep conversion units serving ASEAN manufacturing. The Sustainable Energy Development Authority oversees biofuel blending standards that shape diesel pool economics. The Johor refining corridor leverages Singapore-adjacent logistics for marine bunkering and regional product distribution.
Southeast Asia Oil and Gas Downstream Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with state-backed national oil companies dominating infrastructure ownership while international majors compete on technology and carbon management services. Market structure concentrates around three tiers: integrated petrochemical operators with refinery complexity indices above 10, standalone fuel refiners processing lighter crude slates, and storage-terminal specialists capturing rent from import-dependent economies. Strategic archetypes include state-backed energy security anchors, global majors licensing digital refining analytics, and regional independents optimizing biofuel co-processing. Dominant competitive moves center on residue upgrading capacity expansion and performance-based maintenance contracting unbundling.
Within the state-backed anchor tier, PT Pertamina and Petroliam Nasional Berhad exemplify national infrastructure control strategies that prioritize fuel security over marginal returns. PTT Public Company Limited occupies a position bridging state priority and commercial petrochemical integration. These operators represent the capital-intensive end where refinery complexity investments exceed two billion dollars per complex and project execution timelines stretch across regulatory cycles. Their positioning reflects the structural reality that viable deep conversion capacity concentrates among entities with sovereign balance sheet backing.
| Leading Market Players |
|---|
| PTT Public Company Limited |
| PT Pertamina |
| Petroliam Nasional Berhad |
| Shell plc |
| Exxon Mobil Corporation |
| Vietnam Oil and Gas Group |
| Perusahaan Gas Negara Tbk |
| Chevron Corporation |
| TotalEnergies SE |
| Others |
Value Network & Pricing Analysis
Indonesia's B20-B40 biodiesel mandate is compelling refiners to reconfigure product slates toward lighter crude processing, forcing supply chains to absorb fatty acid methyl ester co-processing infrastructure costs that compress diesel pool margins across the regional downstream chain.
Pricing Analysis
Direct-to-industrial offtake contracts command premium pricing stability over fragmented retail networks. Pricing stratifies across specification-certified marine fuels, standard automotive diesel blends, and economy-grade fuel oil for power generation. Cost compression in residual fuel upgrading is intensifying because residue hydrotreater investments exceed two billion dollars per complex. Industrial power utilities exhibit lowest price sensitivity due to long-term contractual pass-through mechanisms, while provincial wholesale distributors face acute margin pressure from biofuel mandate compliance costs.
Supply Chain Analysis
Marine freight costs from Middle Eastern crude terminals to Singapore and Indonesian receiving ports constitute a structural margin determinant for Java-based and Thai refining clusters. Feedstock supply concentrates in Saudi Arabian, Iraqi, and Nigerian export streams. Catalyst and specialized hydrocracker internals draw from German, Japanese, and US manufacturing bases. Single-source vulnerability in deep conversion unit engineering constrains project execution timelines. Distribution runs through Singapore's Jurong Island storage hub for archipelagic redistribution to Indonesian terminals and Vietnamese coastal depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by irreplaceable downstream infrastructure and escalating biofuel mandate compliance requirements that perpetuate capital deployment cycles.
For Market Incumbents: Acquire residue upgrading and hydrogen production assets to deepen conversion capability against emerging low-carbon fuel competitors. State-backed operators should consolidate co-processing technology licensing positions before international licensors restrict technology transfer. Biofuel mandate escalation represents the primary margin pressure point requiring lighter crude slate procurement control. For New Entrants and Emerging Players: Provincial Indonesian fuel distributors outside Java represent the most penetrable buyer archetype for independent storage and terminal operators. Vietnam's northern industrial corridor offers white-space opportunity for specialty petrochemical feedstock supply. Marine bunkering services at secondary Indonesian ports present entry vectors with lower capital intensity than integrated refining. For Investors and Strategic Acquirers: Asymmetric upside sits with hydrogen production infrastructure operators positioned for ammonia and synthetic fuel synthesis feedstock demand. The five-to-ten year viability window favors assets with electrolyzer integration potential and refinery off-gas capture capability. Carbon border adjustment implementation timelines in European destination markets serve as the critical inflection signal for petrochemical derivative export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Residue Upgrading Capacity Expansion | Deep conversion units at Pengerang and Nghi Son capture IMO 2020 marine fuel premiums. |
| Hydrogen Production Integration | Electrolyzer installations in Singapore and Thailand anchor regional low-carbon ammonia supply. |
| Biofuel Co-Processing Revamp | Fatty acid methyl ester units at Indonesian refineries satisfy B20-B40 mandate requirements. |
| Digital Twin Analytics Deployment | Predictive maintenance platforms enable performance-based contracting at Pertamina facilities. |
| Strategic Storage Terminal Acquisition | Tank farm assets at Tanjung Priok and Dung Quat capture rent from import-dependent economies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured refinery operations directors, marine fuel procurement managers at Singapore bunker suppliers, petrochemical plant managers at Thai and Vietnamese complexes, and biofuel policy officials at Indonesia's Ministry of Energy and Mineral Resources. Secondary validation drew from customs crude import records, ASEAN energy ministry statistical releases, SEC filings by integrated oil companies, and IMO marine fuel specification registers. Bottom-up capacity utilization modeling and top-down demand aggregation triangulated segment outputs.
Segment-weighting applied product type, service tier, and end-use industry dimensions across the projection horizon. Refined fuels, petrochemical derivatives, lubricants, and asphalt categories carried distinct margin and growth trajectories. Processing, storage, transportation, and distribution service types received differential capital intensity weightings. CAGRs derived from elasticity-adjusted demand projections and announced capacity expansion timelines. Crude slate shift assumptions and biofuel mandate escalation schedules served as primary forecast inputs.
Underlying measurement precision varies by segment; petrochemical product flows carry tighter precision than fragmented wholesale distribution channels. Forecasts reflect documented assumptions regarding regulatory implementation timelines and crude price corridor expectations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Riserless Light Well Intervention Market