
 Hydrogen Fuel Cells Market | 2026-2036
Hydrogen Fuel Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Fuel Cells Market Intelligence
Automotive-grade fuel cell stack durability is bifurcating the competitive landscape into suppliers capable of 25,000-hour lifespans versus those confined to shorter-cycle stationary applications. Ballard Power Systems leverages its captive membrane electrode assembly production to control stack cost curves across heavy-duty transport. Plug Power anchors North American green hydrogen logistics through its electrolyzer-fuel cell integration strategy. Nel ASA specializes in PEM electrolysis paired with downstream fuel cell integration, extending its reach from hydrogen production into end-use deployment.
Hydrogen fuel cells electrochemically convert hydrogen and oxygen into electricity, with proton exchange membrane variants operating at 60-80°C and achieving 40-60% electrical efficiency depending on system design. Their primary commercial purpose centers on dispatchable zero-emission power where battery energy density proves insufficient for duty cycles. Proton exchange membrane systems dominate transportation applications due to rapid cold-start capability and power density suited to vehicular packaging constraints. Solid oxide technology occupies stationary distributed generation where high operating temperatures enable combined heat and power configurations with superior system-level efficiency. Material handling equipment represents the most mature application segment, with fuel cell forklifts already displacing lead-acid batteries in multi-shift warehouse operations at major distribution centers.
The U.S. Department of Energy hydrogen and fuel cell program shapes R&D priorities through cost and durability targets, while EPA heavy-duty vehicle emissions standards directly create compliance demand for fuel cell powertrains. California Air Resources Board zero-emission vehicle mandates function as the de facto North American market access gate for automotive fuel cell certification. Stakeholders must monitor electrolyzer capacity buildout timelines against fuel cell deployment curves, as hydrogen supply constraints remain the binding variable for demand realization across all end-use segments.
Market Dynamics
The U.S. Inflation Reduction Act hydrogen production tax credit is compressing green hydrogen costs faster than electrolyzer deployment curves, pulling fuel cell economics into competitive range against diesel in heavy-duty transport corridors.
Growth Catalysts
- Zero-emission vehicle mandates:California Air Resources Board regulations create compliance pull for fuel cell powertrains in Class 8 trucks and transit buses. Fleet operators face binding decarbonization deadlines with limited battery alternatives for long-haul duty cycles.
- Heavy-duty transport electrification:Battery energy density constraints in 500+ mile routes position proton exchange membrane systems as the viable zero-emission option for regional trucking and drayage operations.
- Hydrogen hub infrastructure:U.S. Department of Energy regional clean hydrogen hubs are concentrating production and distribution assets along freight corridors, reducing refueling risk for early fleet adopters.
Market Restraints
- Platinum group metal cost volatility:Membrane electrode assembly fabrication relies on iridium and platinum catalyst loadings, exposing stack cost structures to precious metal commodity swings.
- Electrolyzer supply concentration:Proton exchange membrane electrolyzer manufacturing concentrates in European and East Asian supply bases, creating geographic bottlenecks for green hydrogen scaling.
- Compression and storage technical limits:Gaseous hydrogen at 700 bar requires carbon fiber reinforced polymer tanks with complex certification cycles, constraining vehicle packaging and total cost of ownership reduction.
Strategic Opportunities
- Maritime propulsion applications:International Maritime Organization emission targets for 2030 and 2050 create regulatory pull for fuel cell auxiliary power and primary propulsion in coastal vessels and ferries.
- Data center backup power:Hyperscale operators in Northern Virginia and Frankfurt are piloting fuel cell systems to replace diesel generators under corporate renewable energy commitments and local air quality regulations.
- Solid oxide fuel cell convergence:High-temperature systems paired with electrolysis for reversible operation enable combined heat and power configurations in industrial clusters, capturing waste heat for process applications.
Industry Challenges
- Membrane electrode assembly fabrication talent:Thin-film catalyst coating and hot pressing operations require specialized process engineering expertise that remains concentrated at a handful of research institutions and incumbent suppliers.
- Heavy-duty vehicle certification timelines:EPA and California Air Resources Board validation protocols for fuel cell powertrains extend 18-24 months, compressing product launch windows against evolving emission standards.
- Hydrogen fueling protocol standardization:SAE J2601 fueling communication and ISO 19880-1 station safety specifications create multi-jurisdictional compliance complexity for equipment suppliers and station operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Fuel Cells Market |
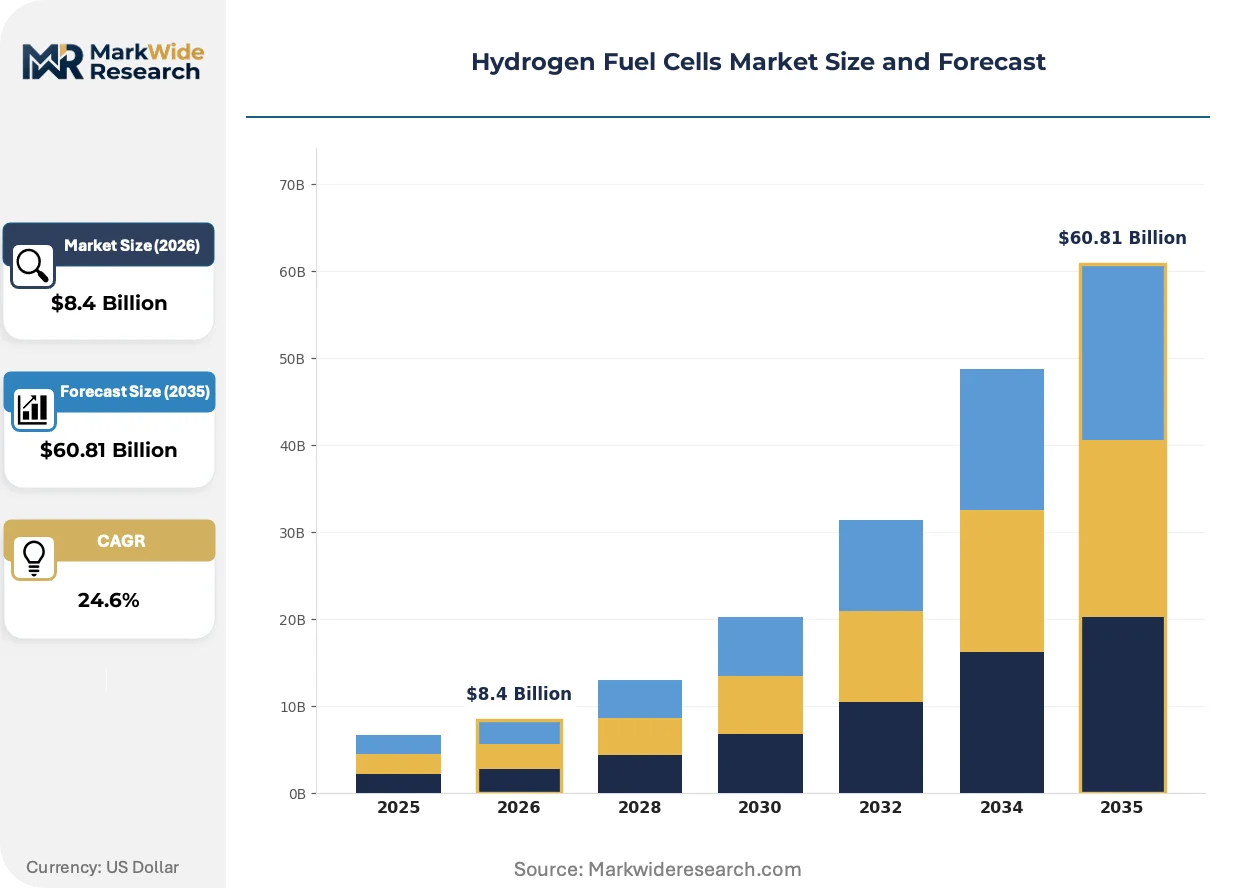
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Solid Oxide, Alkaline, Phosphoric Acid, Molten Carbonate Application: Material Handling Equipment, Portable Power, Backup Power, Transportation, Distributed Generation End User: Heavy-Duty Vehicles, Aerospace, Telecom, Data Centers, Commercial Buildings Deployment: Stationary, Mobile, Residential, Industrial, Remote |
| Companies Covered | Ballard Power Systems, Plug Power, FuelCell Energy, Doosan Fuel Cell, Bloom Energy, Panasonic Corporation, Intelligent Energy, Nel ASA, Linde, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Fuel Cells Market Strategic Shifts & Innovations
Stack cost reduction trajectories and electrolyzer manufacturing scale-up are converging to reposition fuel cells from demonstration projects to contracted fleet deployments.
Bipolar plates with stamped stainless steel flow fields are displacing machined graphite alternatives in automotive-scale production. OEMs in South Korea and Japan are qualifying these designs for 25,000-hour durability targets. This transition is compressing stack bill-of-materials costs while enabling high-volume stamping press throughput.
The EU F-Gas Regulation phase-down schedules are accelerating refrigerant choices in fuel cell thermal management systems. Manufacturers are redesigning balance-of-plant components to accommodate low-global-warming-potential alternatives. Stationary and transport system suppliers in Germany and the Netherlands face 2027 compliance deadlines driving engineering resource allocation.
Fleet operators are consolidating procurement around total-cost-of-ownership contracts bundling hydrogen supply, maintenance, and vehicle lease terms. Third-party asset managers are displacing direct ownership in California and South Korea heavy-duty segments. This shift concentrates buyer power with logistics platforms and energy retailers possessing hydrogen sourcing capabilities.
Hydrogen Fuel Cells Market Segmentation
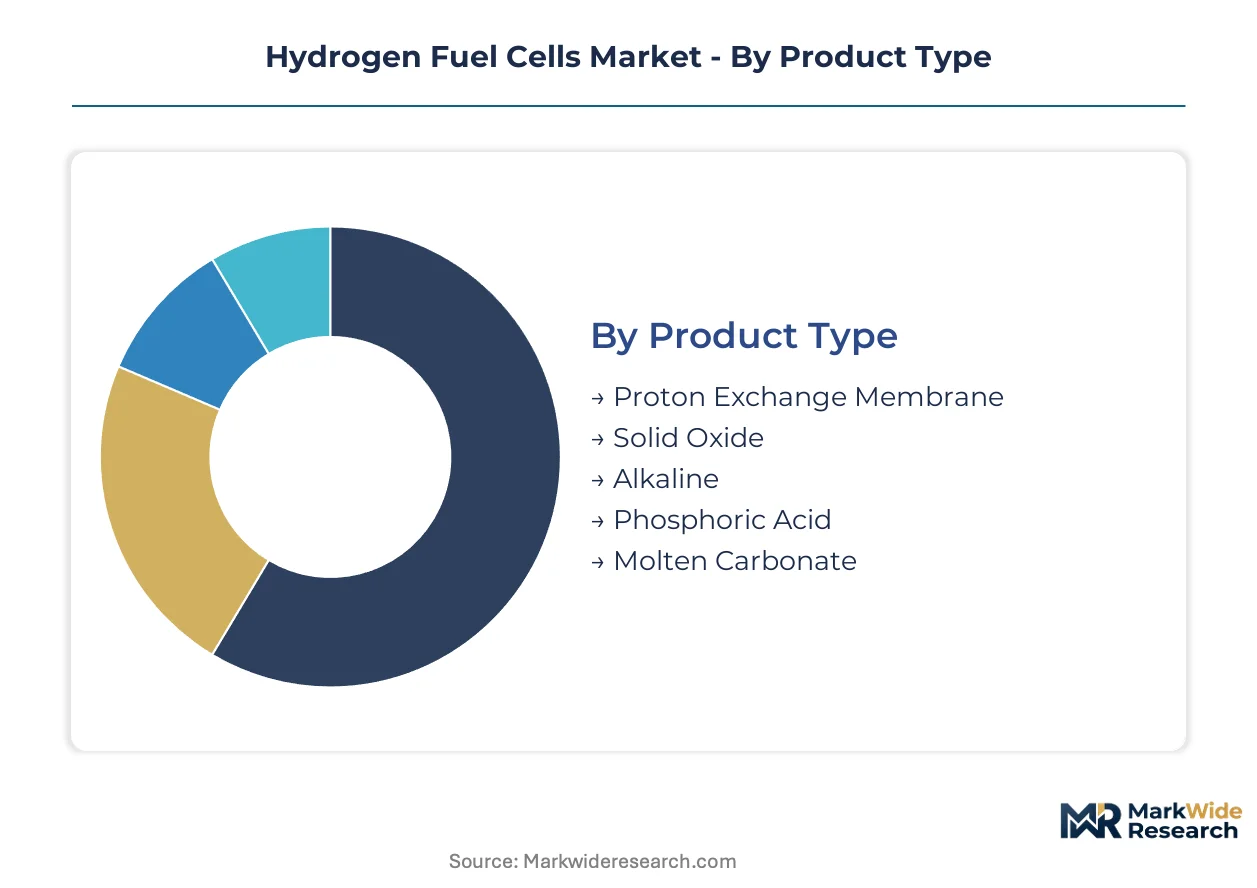
Technology differentiation in hydrogen fuel cells creates distinct competitive arenas where proton exchange membrane systems face battery substitution in transport, while solid oxide variants compete against grid power in stationary applications. Segmentation clarity determines supplier positioning across divergent cost structures and regulatory compliance requirements.
Product Type:
Proton exchange membrane technology confronts intensifying lithium-ion substitution pressure in automotive applications, whereas alkaline and phosphoric acid systems face obsolescence risk from advancing PEM cost curves.
- Proton Exchange Membrane:Polymer electrolyte membranes operating at 60-80°C deliver rapid cold-start capability and 40-60% electrical efficiency. Demand concentrates in California heavy-duty trucking corridors where CARB zero-emission mandates eliminate diesel alternatives for 500+ mile routes. Platinum and iridium catalyst loadings expose stack economics to precious metal volatility.
- Solid Oxide:Ceramic electrolyte systems at 800-1000°C enable combined heat and power configurations with 60%+ system efficiency. Deployment clusters in German industrial parks where EU F-Gas Regulation compliance deadlines drive thermal management redesigns. High operating temperatures constrain transport applications to maritime auxiliary power.
- Alkaline:Liquid electrolyte designs using potassium hydroxide achieve lower catalyst costs through non-precious metal electrodes. Niche adoption persists in legacy stationary installations with established maintenance protocols.
- Phosphoric Acid:Molten phosphoric acid electrolyte systems at 150-200°C serve existing distributed generation fleets. Limited new deployment as PEM and solid oxide cost trajectories compress addressable market space.
- Molten Carbonate:High-temperature carbonate salt electrolytes at 650°C suit large-scale stationary power above 1MW. Commercial traction lags due to corrosion management complexity and extended startup cycles.
Proton exchange membrane retains volume leadership; solid oxide holds the steepest expansion curve.
Application:
Cost tier stratification separates mature material handling deployments with proven total-cost-of-ownership economics from emerging transportation segments requiring hydrogen infrastructure subsidies.
- Material Handling Equipment:Fuel cell forklifts displace lead-acid batteries in multi-shift warehouse operations at major distribution centers. Walmart and Amazon facilities in California and Pennsylvania anchor fleet procurement with 24/7 uptime requirements. Battery swapping downtime costs justify premium fuel cell capital expenditure.
- Transportation:Class 8 trucks and transit buses face binding CARB compliance deadlines with no battery alternative for long-haul duty cycles. Hyundai and Toyota OEM programs in South Korea and Japan validate 25,000-hour stack durability targets. Hydrogen station network density determines corridor viability.
- Backup Power:Telecom towers and critical infrastructure deploy fuel cells for diesel generator replacement under corporate renewable commitments. Data center pilots in Northern Virginia test grid-independent resilience configurations.
- Portable Power:Military and emergency response applications leverage hydrogen energy density for off-grid deployment. Limited commercial scale due to cylinder logistics complexity.
- Distributed Generation:Industrial facilities pair solid oxide systems with process heat recovery. South Korean manufacturing complexes integrate fuel cells into combined heat and power microgrids.
Material handling equipment commands margin stability; transportation claims the steepest expansion curve.
End User:
Customer type concentration reflects procurement power consolidation around logistics platforms with hydrogen sourcing capabilities versus fragmented commercial building ownership.
- Heavy-Duty Vehicles:Fleet operators negotiate total-cost-of-ownership contracts bundling hydrogen supply, maintenance, and vehicle lease terms. Third-party asset managers displace direct ownership in California drayage and regional trucking segments. DOE hydrogen hub infrastructure reduces refueling risk for early adopters.
- Data Centers:Hyperscale operators in Frankfurt and Northern Virginia pilot fuel cell backup systems to replace diesel generators under local air quality regulations. Corporate renewable energy procurement targets drive technology evaluation.
- Telecom:Tower operators in India and Southeast Asia test fuel cells for grid-unreliable locations. Diesel theft and maintenance logistics create total-cost-of-ownership pressure.
- Aerospace:Auxiliary power unit applications face certification timelines extending 18-24 months. FAA validation protocols compress product launch windows against emission standard evolution.
- Commercial Buildings:Fragmented ownership structures impede aggregate demand formation. Cogeneration economics depend on local utility rate structures and thermal load profiles.
Heavy-duty vehicles retain volume leadership; data centers hold the steepest expansion curve.
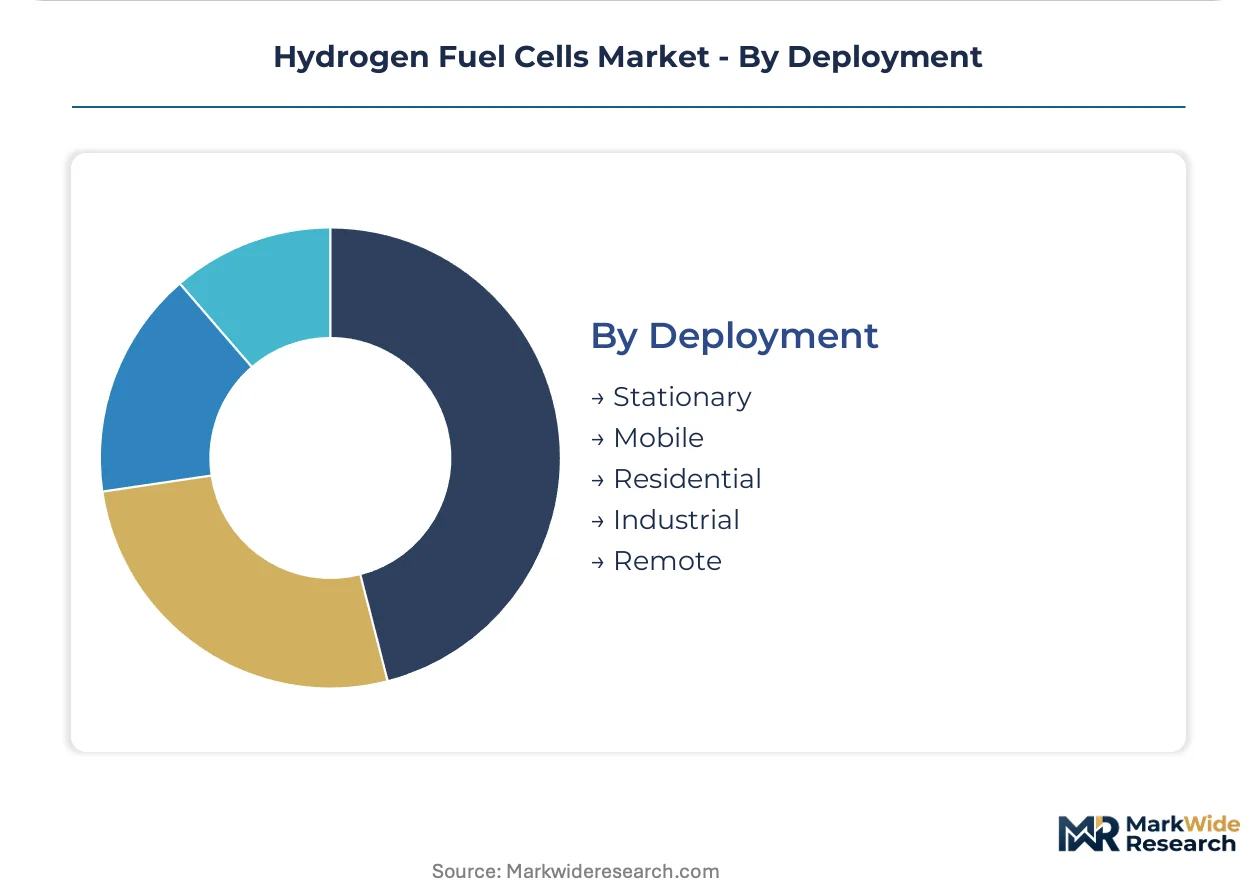
Deployment:
Geographic deployment patterns concentrate stationary systems in industrial clusters with process heat integration potential, while mobile applications track hydrogen corridor infrastructure buildout.
- Stationary:Industrial and commercial installations leverage existing natural gas pipeline proximity for hydrogen blending or dedicated supply. German chemical parks anchor solid oxide deployment with combined heat and power thermal integration.
- Mobile:Vehicle-mounted systems require 700 bar gaseous hydrogen storage with carbon fiber reinforced polymer tanks. SAE J2601 fueling protocol standardization creates multi-jurisdictional compliance complexity.
- Industrial:Manufacturing facilities integrate fuel cells into microgrids with renewable energy firming. South Korean industrial policy supports domestic supply chain development.
- Remote:Mining operations and island grids displace diesel generation where fuel logistics dominate operating costs. Limited addressable market due to infrastructure capital requirements.
- Residential:Micro-combined heat and power systems face competition from heat pump electrification. Japanese Ene-Farm program provides subsidy reference for deployment economics.
Stationary deployment retains volume leadership; mobile holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for fuel cell stacks and electrolyzer components concentrate manufacturing value in South Korea, Japan, and Germany while the United States and China scale domestic hydrogen hub deployment. Trade flows in membrane electrode assemblies and bipolar plates track regional specialization in automotive and stationary applications.
United States
California's zero-emission vehicle mandate drives Class 8 truck and transit bus procurement, with the Inflation Reduction Act hydrogen production tax credit compressing green hydrogen costs. The U.S. Department of Energy regional clean hydrogen hubs concentrate production assets along freight corridors in Texas, California, and the Midwest. Fleet operators in Los Angeles-Long Beach drayage routes negotiate total-cost-of-ownership contracts bundling hydrogen supply with vehicle leases.
South Korea
Hyundai Motor Group's fuel cell electric vehicle program anchors domestic stack demand, with government hydrogen economy roadmaps targeting 6.2 million FCEVs by 2040. The Ministry of Trade, Industry and Energy funds domestic electrolyzer manufacturing scale-up through the Hydrogen Economy Implementation Plan. Industrial clusters in Ulsan and Incheon integrate fuel cells into petrochemical refinery hydrogen networks and port logistics operations.
Japan
Toyota's Mirai platform and commercial vehicle partnerships sustain PEM stack demand, with the Ministry of Economy, Trade and Industry's Green Growth Strategy targeting 20 million tonnes annual hydrogen supply by 2050. The Ene-Farm residential micro-cogeneration program provides subsidy reference for stationary deployment economics. Manufacturing concentration in Aichi Prefecture links automotive fuel cell production to Nagoya industrial corridor hydrogen infrastructure.
Germany
Chemical park demand for industrial process heat and the EU Green Deal hydrogen import targets drive solid oxide and PEM system deployment. The Federal Ministry for Economic Affairs and Climate Action's National Hydrogen Strategy funds electrolyzer manufacturing scale-up in North Rhine-Westphalia. Industrial clusters in the Ruhr region and Leuna chemical park anchor fuel cell integration into steel decarbonization and ammonia production pathways.
China
Fuel cell vehicle deployment concentrates in Beijing-Tianjin-Hebei, Shanghai, and Guangdong demonstration zones, with the Ministry of Industry and Information Technology's New Energy Vehicle Industry Development Plan targeting 50,000 FCEVs by 2025. State-owned enterprise electrolyzer manufacturing scales in Shandong and Jiangsu provinces. The Yangtze River Delta hydrogen corridor connects Shanghai port logistics to regional refueling infrastructure.
Hydrogen Fuel Cells Market Key Industry Players
Listed leaders compete with private specialists across capital access and technology development timelines, creating a tiered structure where public companies leverage equity markets for electrolyzer and stack manufacturing scale-up while private operators concentrate on niche application engineering. The competitive landscape fragments across proton exchange membrane automotive suppliers, solid oxide stationary specialists, and integrated hydrogen production-to-use platforms. Strategic archetypes include captive membrane electrode assembly producers controlling stack cost curves, electrolyzer-fuel cell integrators anchoring green hydrogen logistics, and balance-of-plant component suppliers enabling system-level efficiency gains. Dominant competitive moves encompass backward integration into precious metal catalyst sourcing and strategic partnerships for hydrogen station network deployment.
Among North American-listed specialists, Ballard Power Systems, Plug Power, and FuelCell Energy occupy distinct archetype positions. Ballard represents the captive manufacturing model with in-house membrane electrode assembly production. Plug Power exemplifies the integrated hydrogen logistics platform combining electrolyzer output with downstream fuel cell deployment. FuelCell Energy anchors the stationary distributed generation segment with carbonate fuel cell configurations for industrial power applications. These three listed entities compete for capital allocation against European and Asian specialists including Nel ASA, Doosan Fuel Cell, and Panasonic Corporation, each representing regional supply chain and end-use specialization patterns.
| Leading Market Players |
|---|
| Ballard Power Systems |
| Plug Power |
| FuelCell Energy |
| Doosan Fuel Cell |
| Bloom Energy |
| Panasonic Corporation |
| Intelligent Energy |
| Nel ASA |
| Linde |
| Others |
Cost & Logistics Intelligence
California Air Resources Board zero-emission certification gates both membrane electrode assembly supplier qualification and stack pricing tiers simultaneously, compressing margin structures for uncertified entrants while rewarding durable 25,000-hour performers with premium positioning in heavy-duty transport contracts.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in hydrogen fuel cell procurement. Premium tiers capture California CARB-certified stacks with 25,000-hour durability guarantees and bundled hydrogen supply contracts, while economy tiers serve stationary applications with shorter-cycle membrane electrode assemblies. Price differentiation stems from platinum group metal catalyst loadings and ISO 19880-1 station safety certification status. Cost compression in standard tiers is intensifying because bipolar plate stamping automation is displacing machined graphite alternatives. Fleet operators with total-cost-of-ownership contracts show least price sensitivity; fragmented commercial building owners exhibit highest sensitivity to capital expenditure differentials.
Supply Chain Analysis
Just-in-time membrane electrode assembly procurement dominates automotive-scale production, while strategic stockpiling of iridium and platinum concentrates among Korean and Japanese OEMs hedges against precious metal volatility. Manufacturing gravity centers on South Korea, Japan, and Germany for stack assembly, with China scaling electrolyzer component output. Raw material dependencies include perfluorinated polymer membranes, carbon fiber reinforced polymer tanks, and rare earth catalyst coatings. Single-source vulnerability in proton exchange membrane electrolyzer manufacturing creates geographic chokepoint risk. Distribution runs through integrated hydrogen logistics platforms bundling production, compression, and station deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against lithium-ion battery energy density improvements that threaten PEM transport applications below 500-mile duty cycles. Incumbents must navigate battery cost curves while solidifying hydrogen corridor infrastructure lock-in.
For Market Incumbents: Shield 25,000-hour durability certification as the primary competitive moat against emerging Chinese stack suppliers. Backward integration into captive membrane electrode assembly production controls platinum cost exposure. Prioritize California hydrogen hub corridor density to embed switching costs for fleet operators evaluating battery alternatives.
For New Entrants and Emerging Players: Lead with solid oxide fuel cell combined heat and power configurations in German industrial clusters where EU F-Gas Regulation compliance deadlines concentrate demand. Maritime auxiliary power and data center backup segments present white-space penetration below incumbent radar. Pursue equipment-as-a-service revenue models bundling maintenance with hydrogen supply guarantees.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across proton exchange membrane stack manufacturing as stamped bipolar plate automation scales. Five-to-ten year viability hinges on electrolyzer-fuel cell integration platforms with proven green hydrogen offtake contracts. Target acquisition archetypes include captive catalyst coating specialists and regional hydrogen station network operators. Watch electrolyzer capacity buildout timelines against fuel cell deployment curves as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Backward Integration | Captive catalyst coating controls platinum cost curves for Ballard and Plug Power stack output. |
| Hydrogen Hub Corridor Concentration | DOE regional hub deployment embeds refueling infrastructure lock-in along Texas-California freight routes. |
| Solid Oxide CHP Thermal Integration | Ruhr chemical park deployments capture process heat for German steel decarbonization pathways. |
| Maritime Propulsion Certification Investment | IMO 2030 emission targets create regulatory pull for Hyundai and Toyota coastal vessel programs. |
| Fleet TCO Contract Consolidation | Third-party asset managers bundle hydrogen supply with vehicle leases in Los Angeles-Long Beach drayage. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, DOE hydrogen program disclosures, and EU F-Gas Regulation compliance databases. Primary interviews engaged fuel cell stack procurement directors at heavy-duty fleet operators, membrane electrode assembly process engineers, and hydrogen station network developers. Secondary validation drew from California Air Resources Board certification records, EPA heavy-duty vehicle emissions filings, and customs trade data for electrolyzer component flows. Bottom-up stack shipment tallies triangulate against top-down hydrogen demand projections across transport and stationary segments.
Segmentation dimensions modeled span proton exchange membrane versus solid oxide technology, material handling through maritime application tiers, and stationary versus mobile deployment modes. CAGRs derive from electrolyzer capacity buildout curves mapped against fuel cell deployment timelines across the analysis window. Industry-specific forecast inputs include platinum group metal price volatility assumptions and CARB zero-emission mandate compliance trajectory.
Forecasts assume regulatory continuity in EPA heavy-duty standards and California CARB mandates; material policy shifts would require re-modeling. Hydrogen supply constraint scenarios and battery energy density breakthroughs constitute primary revision triggers. Revision becomes warranted when electrolyzer manufacturing scale-up delays cross thresholds that compress fuel cell deployment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Global Micro Fuel Cells Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market