
 Wireless Electric Vehicle Charger Market | 2026-2036
Wireless Electric Vehicle Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Electric Vehicle Charger Market Outlook
Magnetic resonance coupling with foreign object detection is rewriting how automakers integrate charging hardware without physical connectors. WiTricity Corporation leverages its patent portfolio to dominate licensing for passenger vehicle pad architectures. Electreon Wireless Ltd. anchors its position through dynamic charging demonstrations on public roadways in Israel, Sweden, and Italy. Robert Bosch GmbH extends its automotive supplier relationships into aftermarket wireless retrofit kits for existing EV fleets.
Wireless electric vehicle chargers transfer electrical energy across an air gap through electromagnetic induction or resonant magnetic coupling, typically operating at frequencies between 81-90 kHz with power levels from 3.6 kW to 300 kW depending on application. The primary industrial purpose is eliminating connector wear, enabling automated charging for autonomous vehicles, and reducing infrastructure maintenance in high-utilization settings. Static chargers occupy the dominant revenue position due to residential garage and fleet depot deployments where vehicles park for predictable durations. Resonant charging represents the fastest-expanding technology segment because its tolerance for coil misalignment suits real-world parking variability better than tightly-coupled inductive alternatives. Fleet operators constitute the highest-margin end-user category, as route-optimized charging contracts generate recurring service revenue beyond hardware sales.
The SAE J2954 standard in the United States, China's GB/T 38775 protocol, and the EU's Alternative Fuels Infrastructure Regulation collectively shape product certification requirements and cross-border equipment compatibility. China's SAMR enforces electromagnetic compatibility testing that adds six to twelve months to market entry for non-domestic suppliers. Stakeholders must monitor which regulatory bloc's interoperability mandate achieves de facto global adoption first, as this determines where R&D investment and manufacturing scale concentrate.
Market Dynamics
The Wireless Electric Vehicle Charger Market pivots on SAE J2954 standard harmonization, which forces hardware interoperability across vehicle OEMs and infrastructure providers, compressing proprietary system margins while accelerating fleet-scale procurement consolidation.
Growth Catalysts
- California ZEV Mandate Corridors:Public transit agencies in Los Angeles and San Francisco deploy inductive charging for electric bus fleets, creating anchor demand that validates technology economics for private logistics operators.
- Resonant Magnetic Coupling:Tolerance for coil misalignment up to 150mm eliminates precise parking requirements, reducing driver friction and enabling automated charging for autonomous vehicle prototypes.
- EU Alternative Fuels Infrastructure Regulation:Binding deployment targets for charging infrastructure across member states mandate interoperability certification, opening procurement pipelines for standardized wireless pad systems.
Market Restraints
- Copper and Ferrite Supply Concentration:Coil winding materials face pricing volatility from concentrated Chinese rare earth processing, squeezing pad manufacturer margins at power levels above 11 kW.
- Electromagnetic Compatibility Testing:China's SAMR enforcement adds six-to-twelve month certification delays for non-domestic suppliers, freezing market entry timelines regardless of technical readiness.
- Conductive Fast-Charging Substitution:350 kW DC rapid chargers at highway corridors capture long-haul fleet preference where dwell time minimization outweighs connector wear elimination.
Strategic Opportunities
- Dynamic Charging Highways:Israel, Sweden, and Italy pilot in-road coil installations that charge vehicles in motion, unlocking revenue models based on distance-traveled billing rather than hardware sales.
- Autonomous Vehicle Integration:Self-parking and self-charging capability convergence positions wireless pads as enabling infrastructure for robotaxi and delivery drone depot networks.
- India PLI Scheme for Auto Components:Production-linked incentives for advanced automotive electronics attract domestic coil and inverter manufacturing, reducing import dependence for sub-continent fleet deployments.
Industry Challenges
- Power Electronics Talent Scarcity:RF engineering and magnetic design expertise shortages delay product development cycles for resonant frequency tuning and foreign object detection algorithms.
- Multi-Standard Certification Burden:SAE J2954, GB/T 38775, and IEC 61980 testing requirements force redundant engineering investment for suppliers targeting cross-border fleet contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Electric Vehicle Charger Market |
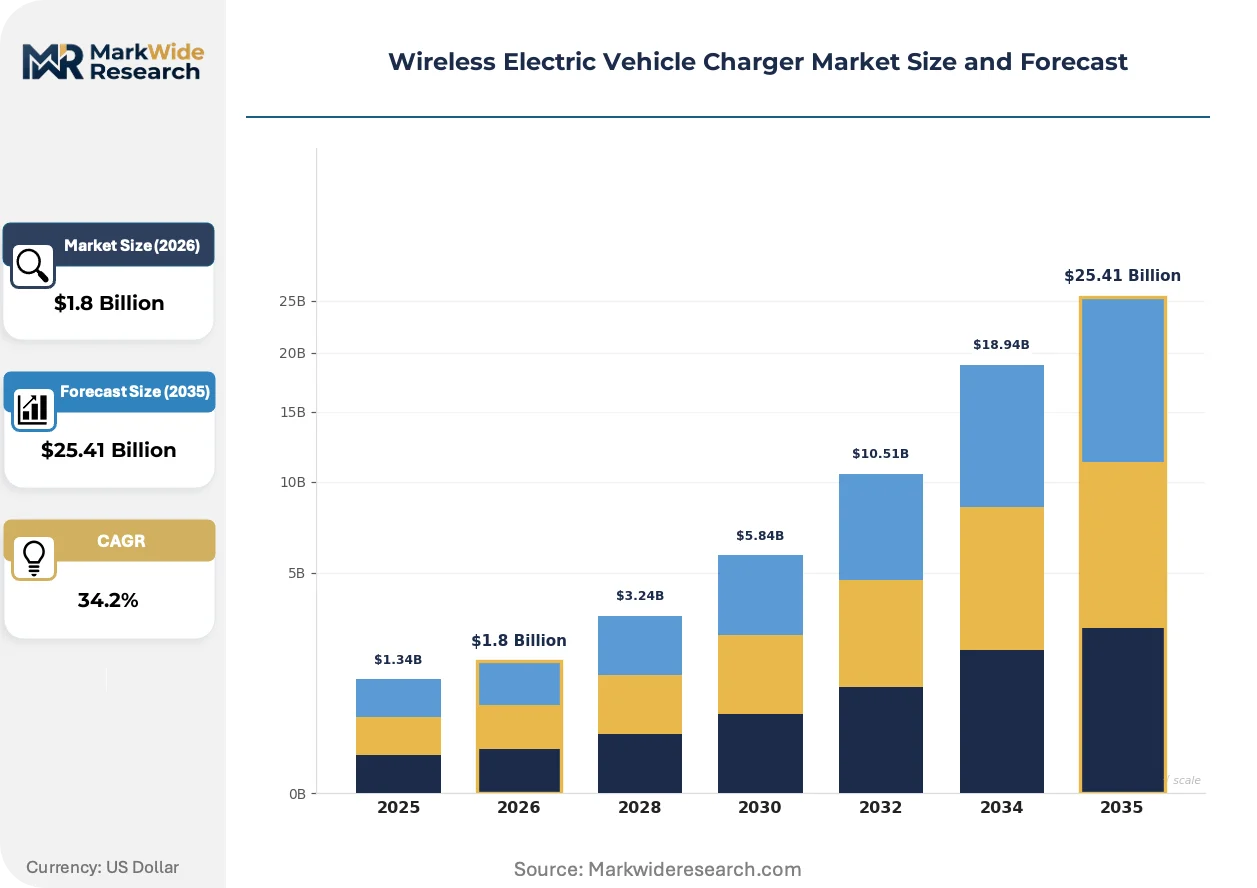
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $25.41 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Chargers, Mobile Chargers, Integrated Chargers, Fast Chargers Technology: Inductive Charging, Resonant Charging, Magnetic Field Charging, Capacitive Charging End User: Fleet Operators, Individual Consumers, Commercial Users, Public Transport Installation: Home Installation, Commercial Installation, Public Installation, Industrial Installation |
| Companies Covered | WiTricity Corporation, Electreon Wireless Ltd., InductEV Inc., Plugless Power Inc., HEVO Inc., TGOOD Global Ltd, Toyota Motor Corporation, Continental AG, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Electric Vehicle Charger Market Strategic Shifts
Magnetic resonance architectures are collapsing the historical trade-off between charging speed and positional flexibility, forcing incumbent inductive suppliers to retool or exit while opening procurement to new subsystem specialists.
Bi-directional power flow capability is collapsing the boundary between vehicle and grid infrastructure, enabling EVs to discharge into building loads or utility networks. Fleet operators in Germany and Japan pilot vehicle-to-grid wireless integration for depot microgrids, compressing payback periods for charging hardware through energy arbitrage revenue. This collapse of unidirectional assumptions forces inverter manufacturers to redesign for grid-synchronization compliance.
The EU's Alternative Fuels Infrastructure Regulation mandates wireless charging interoperability by 2025 for public infrastructure receiving member state funding. Equipment suppliers must certify to EN 12944 electromagnetic compatibility and mechanical safety standards, shifting R&D investment toward modular pad architectures that adapt to multiple vehicle ground clearances. Nordic municipalities lead compliance, bundling wireless charging into zero-emission bus tender requirements.
Route-optimized charging contracts are displacing hardware ownership models for fleet operators. Logistics providers in California's Central Valley negotiate per-mile charging subscriptions with infrastructure vendors, transferring capital risk to suppliers while locking in operational expenditure predictability. This preference shift concentrates procurement authority with fleet managers rather than facility capital planners, altering sales force structure and contract design.
Wireless Electric Vehicle Charger Market Segmentation
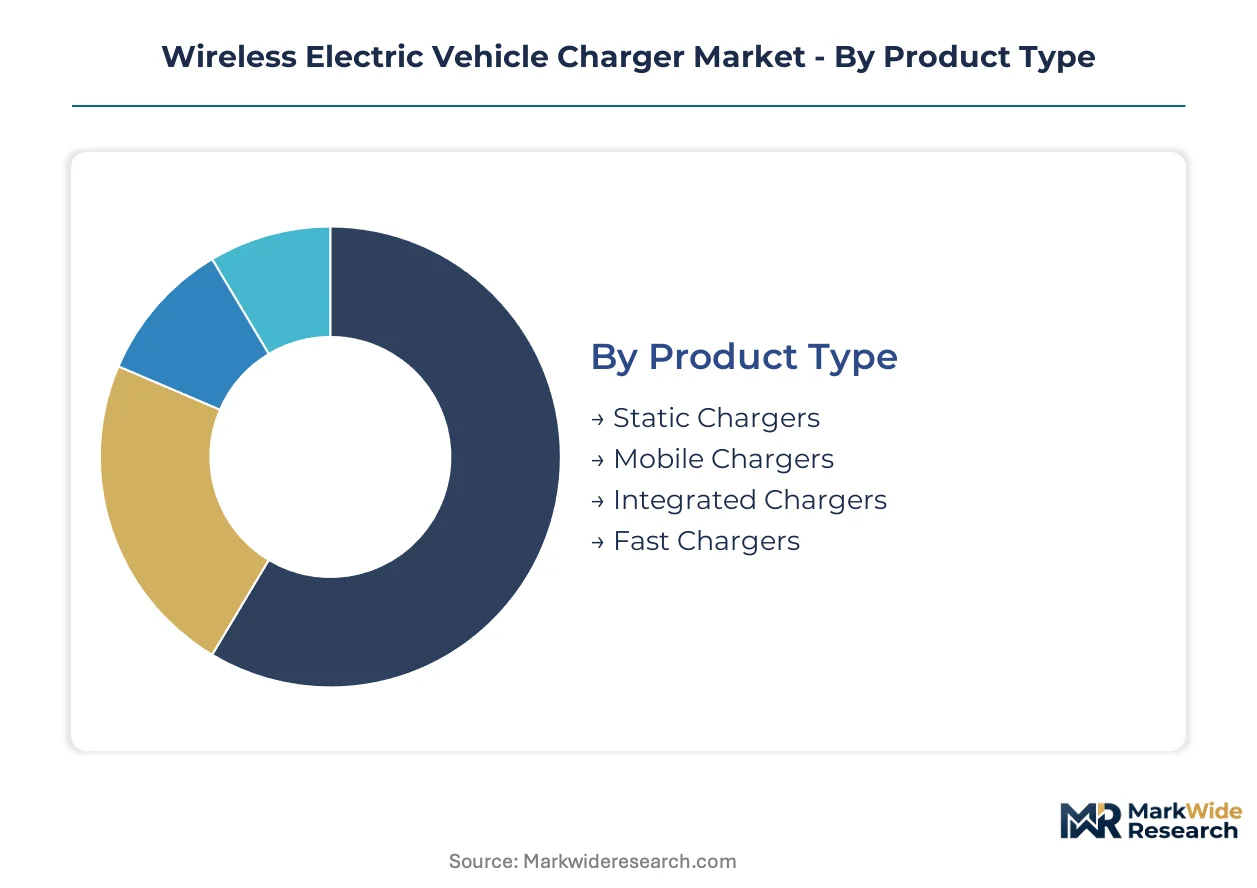
Segmentation in wireless EV charging reveals how hardware economics, service intensity, and deployment complexity vary across use cases. Fleet operators demand route-optimized charging contracts with predictive maintenance, while residential installations prioritize plug-and-play simplicity with minimal after-sales intervention.
Product Type:
After-sales service intensity varies dramatically across product architectures, with depot-deployed systems requiring scheduled coil alignment verification and foreign object detection calibration that residential units rarely need.
- Static Chargers:Fixed pad systems operate at 3.6 kW to 11 kW for overnight residential charging or fleet depot dwell periods. California transit agencies in Los Angeles and San Francisco anchor procurement volumes through standardized SAE J2954-compliant installations. Coil replacement and firmware updates dominate service revenue streams.
- Mobile Chargers:Portable units with detachable transmitter pads enable temporary deployment at event venues or construction sites. Demand concentrates in Germany's commercial logistics corridors where seasonal fleet scaling requires flexible infrastructure without permanent electrical work.
- Integrated Chargers:Factory-embedded receiver coils eliminate aftermarket installation friction for OEM vehicle programs. Automakers in Japan and South Korea specify these for premium electric sedan launches.
- Fast Chargers:High-power static systems deliver 50 kW to 300 kW for commercial turnaround applications. Highway corridor operators in Italy pilot these for electric bus rapid charging alongside Electreon dynamic charging demonstrations.
Static chargers hold the largest share; momentum sits with fast chargers as fleet electrification compresses dwell time requirements.
Technology:
Cost tier separation in technology selection drives divergent R&D investment patterns, with premium resonant architectures commanding higher licensing fees while basic inductive systems compete on manufacturing scale.
- Inductive Charging:Tightly-coupled transformer architectures require precise coil alignment within 10 mm tolerances. Legacy deployments in early electric bus fleets in Sweden rely on this proven but positioning-sensitive approach.
- Resonant Charging:Magnetic resonance coupling tolerates coil misalignment up to 150 mm through matched resonant frequencies between 81-90 kHz. WiTricity Corporation's patent licensing dominates passenger vehicle pad architectures. Fleet operators in California's Central Valley prioritize this technology for automated parking compatibility.
- Magnetic Field Charging:Dynamic in-road coil systems enable charging-in-motion through segmented transmitter arrays. Israel, Sweden, and Italy host public roadway pilots with distance-traveled billing models.
- Capacitive Charging:Electric field coupling across plate electrodes avoids magnetic core materials entirely. Research programs in Japan's METI-funded consortia explore this for reduced rare earth dependence.
Resonant charging dominates new installations; magnetic field charging shows steepest expansion trajectory as dynamic highway pilots validate technical feasibility.
End User:
Customer type determines contract structure, with fleet procurement favoring service-based subscriptions and individual consumers transacting through hardware ownership with minimal ongoing vendor relationships.
- Fleet Operators:Route-optimized charging contracts generate recurring service revenue beyond equipment margins. Logistics providers in California negotiate per-mile subscriptions with infrastructure vendors.
- Individual Consumers:Residential garage installations prioritize seamless smartphone integration and minimal maintenance. Sales cycles align with new electric vehicle purchases rather than independent infrastructure decisions.
- Commercial Users:Workplace and retail parking deployments balance utilization rates with customer dwell time patterns. Property managers in Germany bundle charging into lease agreements for corporate campuses.
- Public Transport:Municipal bus agencies mandate interoperability certification and 99.5% uptime guarantees. Nordic municipalities lead zero-emission bus tender requirements with wireless charging specifications.
Fleet operators command the highest margins; public transport delivers the most predictable long-term contract volumes.
Installation:
Installation complexity scales with electrical infrastructure requirements, from single-phase residential circuits to industrial substations serving multi-megawatt depot arrays.
- Home Installation:Single-phase 240V connections support 3.6 kW to 7.2 kW residential pads. Permitting simplicity in the United States accelerates adoption compared to European electrical inspection requirements.
- Commercial Installation:Three-phase industrial connections enable 11 kW to 22 kW workplace charging. Property developers in Japan integrate these into mixed-use building standards.
- Public Installation:Curbside and parking structure deployments require weatherproofing and vandalism resistance. Municipal procurement in Italy specifies EN 12944 electromagnetic compatibility compliance.
- Industrial Installation:Dedicated substations and thermal management systems support 100 kW+ fleet depot arrays. Warehouse operators in California's Inland Empire scale these for electric delivery van consolidation.
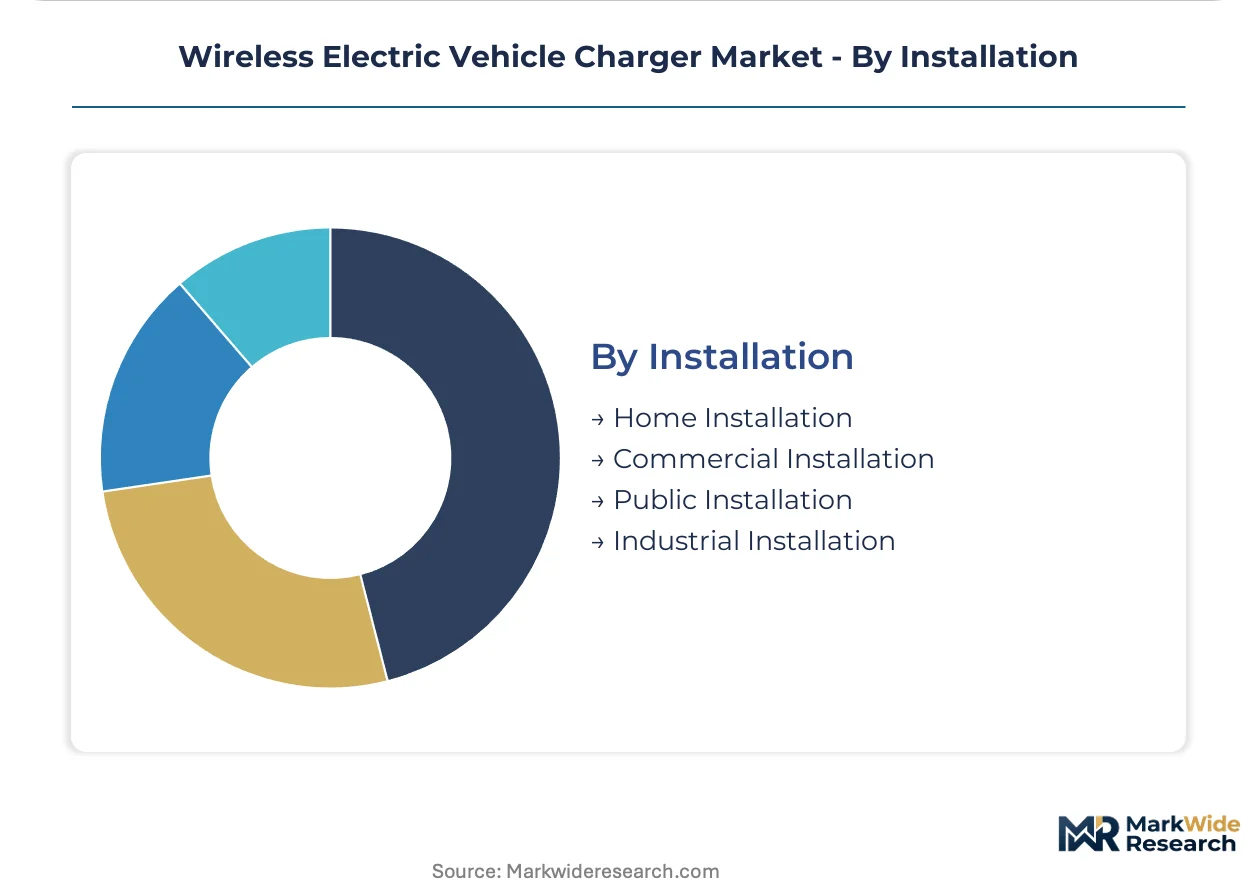
Home installation represents the largest installed base; industrial installation is gaining share fastest as commercial fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement managers in California's Central Valley negotiate route-optimized charging subscriptions with infrastructure vendors, transferring capital risk to suppliers while locking in operational expenditure predictability.
United States
Los Angeles and San Francisco public transit agencies deploy inductive charging for electric bus fleets, creating anchor demand that validates technology economics. SAE International's J2954 standard harmonizes interoperability requirements across vehicle OEMs and infrastructure providers. California's zero-emission vehicle mandate corridors concentrate pilot installations for dynamic charging systems.
China
Domestic rare earth processing dominance secures copper and ferrite supply chains for coil winding materials at competitive cost positions. SAMR electromagnetic compatibility testing adds six-to-twelve month certification delays for non-domestic suppliers. Yangtze River Delta manufacturing clusters scale pad production for export markets.
Germany
Workplace and retail parking deployments balance utilization rates with customer dwell time patterns across commercial logistics corridors. EU Alternative Fuels Infrastructure Regulation mandates interoperability certification for public infrastructure receiving member state funding. Property managers in corporate campuses bundle charging into lease agreements.
Sweden
Nordic municipalities lead zero-emission bus tender requirements with wireless charging specifications bundled into procurement contracts. EN 12944 electromagnetic compatibility and mechanical safety standards shift R&D investment toward modular pad architectures. Public roadway pilots host Electreon dynamic charging demonstrations with distance-traveled billing models.
Italy
Highway corridor operators pilot fast chargers for electric bus rapid charging alongside dynamic charging installations on public roadways. Municipal procurement specifies EN 12944 compliance for curbside and parking structure deployments. Industrial installations in northern logistics hubs support electric delivery van consolidation.
Wireless Electric Vehicle Charger Market Competitive Environment
Channel-controlling players compete with product-specialist players across licensing, hardware manufacturing, and fleet service contracting tiers. The vendor base organizes around patent holders, automotive tier-one suppliers, and infrastructure operators with distinct margin profiles and capital intensity requirements. Three archetypes dominate: technology licensors extracting royalties from standardized pad architectures, integrated automotive suppliers extending existing OEM relationships, and fleet-focused operators monetizing through subscription revenue rather than equipment sales. Competitive moves concentrate on strategic partnerships for pilot deployment validation and geographic expansion through regulatory certification stacking.
Within the technology licensor tier, WiTricity Corporation and Electreon Wireless Ltd. occupy positions as archetype anchors for passenger vehicle pad architectures and dynamic charging demonstrations respectively. Robert Bosch GmbH exemplifies the automotive supplier extension model, leveraging existing tier-one relationships into aftermarket wireless retrofit kits. These three entities represent the dominant competitive positioning patterns visible across the market structure.
| Leading Market Players |
|---|
| WiTricity Corporation |
| Electreon Wireless Ltd. |
| InductEV Inc. |
| Plugless Power Inc. |
| HEVO Inc. |
| TGOOD Global Ltd |
| Toyota Motor Corporation |
| Continental AG |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta freight corridors carry ferrite cores and copper windings from Chinese processing centers to pad assembly plants, transmitting upstream material cost volatility into three-tier pricing structures that separate SAE J2954-certified systems from basic inductive alternatives. Fleet procurement managers in California's Central Valley absorb this freight cost layering through route-optimized subscription contracts that index hardware fees to rare earth price movements.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate fleet depot procurement, embedding raw material risk into infrastructure vendor margins. Price differentiation rests on certification tier—SAE J2954-compliant pads command premium positioning against unlicensed inductive alternatives—and after-sales service bundling that includes foreign object detection calibration. Pricing pressure stems from 350 kW DC rapid charger substitution at highway corridors where dwell time minimization outweighs connector wear elimination. Fleet operators exhibit highest price sensitivity due to capital expenditure constraints, while municipal transit agencies accept premium tiers for 99.5 percent uptime guarantees.
Supply Chain Analysis
Contract manufacturing concentrates with Yangtze River Delta electronics manufacturing service providers and South Korean power electronics specialists holding resonant inverter capacity. Coil winding materials draw from Chinese rare earth processing dominance for ferrite cores and Chilean copper cathode imports. Single-source vulnerability runs through concentrated ferrite supply from Chinese state-owned processors. Distribution runs through automotive tier-one supplier networks and direct fleet service contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF engineering and magnetic design expertise shortages compress product development timelines, creating acquisition premiums for teams with resonant frequency tuning and foreign object detection algorithm capabilities.
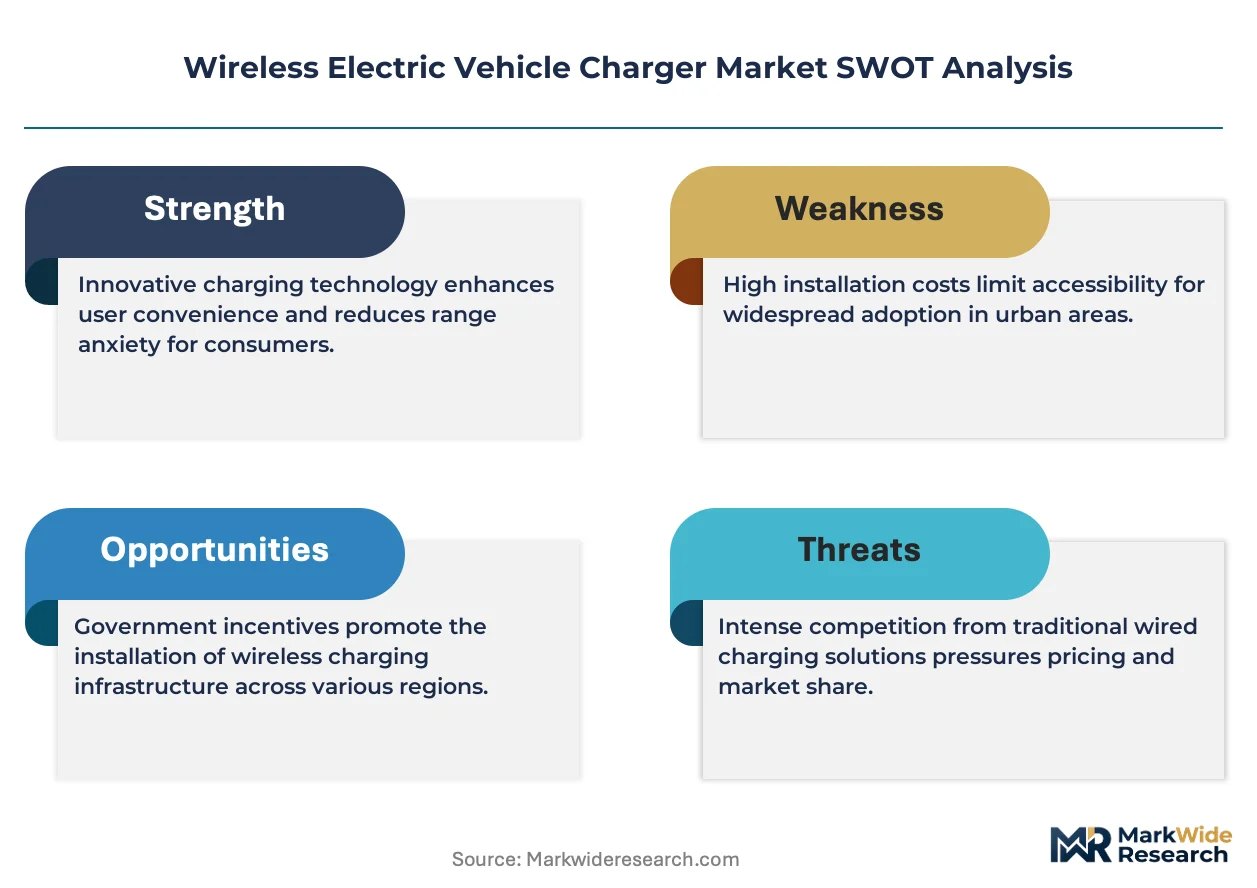
For Market Incumbents: Entrench patent licensing revenue through aggressive SAE J2954 certification stacking that freezes out proprietary inductive alternatives. Secure backward integration into ferrite core production through offtake agreements with Chinese processors, defending margin position against copper price volatility that squeezes pad manufacturers at power levels above 11 kW. For New Entrants and Emerging Players: Pursue aftermarket wireless retrofit kits for existing EV fleets in Germany's commercial logistics corridors, where seasonal infrastructure scaling demands portable deployment without permanent electrical work. Target India's PLI scheme for auto components to establish domestic coil and inverter manufacturing, reducing import dependence for sub-continent fleet deployments through production-linked incentive qualification. For Investors and Strategic Acquirers: Patent-rich subsystem specialists with resonant magnetic coupling IP and established automotive OEM relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on which regulatory bloc's interoperability mandate achieves de facto global adoption first. Watch for SAE J2954 harmonization announcements across United States, Canada, and Mexico as signal of R&D investment concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Patent Portfolio Licensing | WiTricity Corporation's IP dominance extracts royalties from standardized passenger vehicle pad architectures. |
| Dynamic Highway Pilot Expansion | Electreon Wireless Ltd. validates distance-traveled billing models in Israel, Sweden, and Italy public roadway demonstrations. |
| Automotive Supplier Relationship Extension | Robert Bosch GmbH leverages tier-one OEM channels into aftermarket wireless retrofit kit distribution. |
| Fleet Service Subscription Scaling | California Central Valley logistics providers lock in per-mile charging contracts transferring capital risk to infrastructure vendors. |
| Regulatory Certification Stacking | Multi-standard compliance across SAE J2954, GB/T 38775, and IEC 61980 opens cross-border fleet procurement pipelines. |
Study Parameters
Desk research of automotive supplier SEC filings, SAE International standards documentation, and EU Alternative Fuels Infrastructure Regulation implementation reports preceded structured interviews with fleet procurement managers, wireless charging hardware engineering leads, and municipal transit agency contract officers. Secondary validation drew from customs trade data for ferrite and copper imports, patent filing databases, and infrastructure deployment tracking across pilot corridor programs. Bottom-up installation forecasts triangulated against top-down market sizing from automotive production projections.
Assumption sets held SAE J2954 standard harmonization and EU interoperability mandates fixed while varying copper price trajectories and fleet electrification penetration rates across the analysis window. Segmentation modeling incorporated product type, technology architecture, end-user category, and installation complexity dimensions. CAGRs derived from logistic curve fitting to fleet deployment schedules and residential adoption patterns, with power electronics cost decline curves and rare earth supply elasticity as key inputs.
Macroeconomic conditions sit as an overlay; deviation in copper price volatility, Chinese rare earth export policy, or California ZEV mandate enforcement intensity would shift the trajectory. Quarterly review of SAE standards committee proceedings, SAMR certification queue lengths, and Nordic municipal tender award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
Electric Car Charging Pile Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market