
 Global Micro Fuel Cells Market | 2026-2036
Global Micro Fuel Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micro Fuel Cells Market Outlook
Portable military power demand is decoupling from traditional battery procurement patterns across NATO-aligned defense ministries. SFC Energy anchors European battlefield energy contracts with methanol-based field units. Intelligent Energy competes on air-cooled system architecture for soldier-worn loads. Toshiba extends its solid-state fuel cell research into compact form factors for remote monitoring applications.
Micro fuel cells convert chemical energy from hydrogen or methanol into electrical power through electrochemical reactions, typically operating at outputs below 100 watts with membrane electrode assemblies measuring micrometers to millimeters in thickness. These systems serve as lightweight, refuelable power sources for applications where battery weight or recharge logistics create operational constraints. Direct methanol fuel cells dominate current military and portable device deployments due to liquid fuel handling advantages and established supply chains. Proton exchange membrane fuel cells capture growing interest in automotive OEM auxiliary power units where rapid cold-start capability matters. Membrane technology specialization determines thermal efficiency thresholds and catalyst loading requirements across product tiers.
FAA certification protocols constrain airborne micro fuel cell deployments in the United States, while ECHA REACH regulations govern platinum catalyst sourcing and membrane material compliance across European manufacturing bases. Japan's METI enacts hydrogen safety standards that directly shape domestic product qualification timelines for wearable electronics integration. Stakeholders must track evolving ISO safety benchmarks for hydrogen storage miniaturization alongside military specification shifts that redefine acceptable power density thresholds for fielded systems.
Market Dynamics
Defense ministries in the United States and Germany are rewriting portable power specifications, forcing suppliers to abandon lithium-ion dominance for methanol-fed electrochemical systems that eliminate forward-deployed charging logistics.
Growth Catalysts
- Japan METI hydrogen roadmap:Domestic certification standards for wearable micro fuel cells compress product qualification timelines, accelerating commercialization of consumer electronics integration.
- Soldier-worn power loads:NATO battlefield energy requirements now specify refuelable systems under 2 kilograms, creating procurement pull for direct methanol architectures.
- Solid oxide miniaturization:Advances in thin-film electrolyte deposition enable operating temperatures below 500°C, unlocking auxiliary power applications previously reserved for combustion engines.
Market Restraints
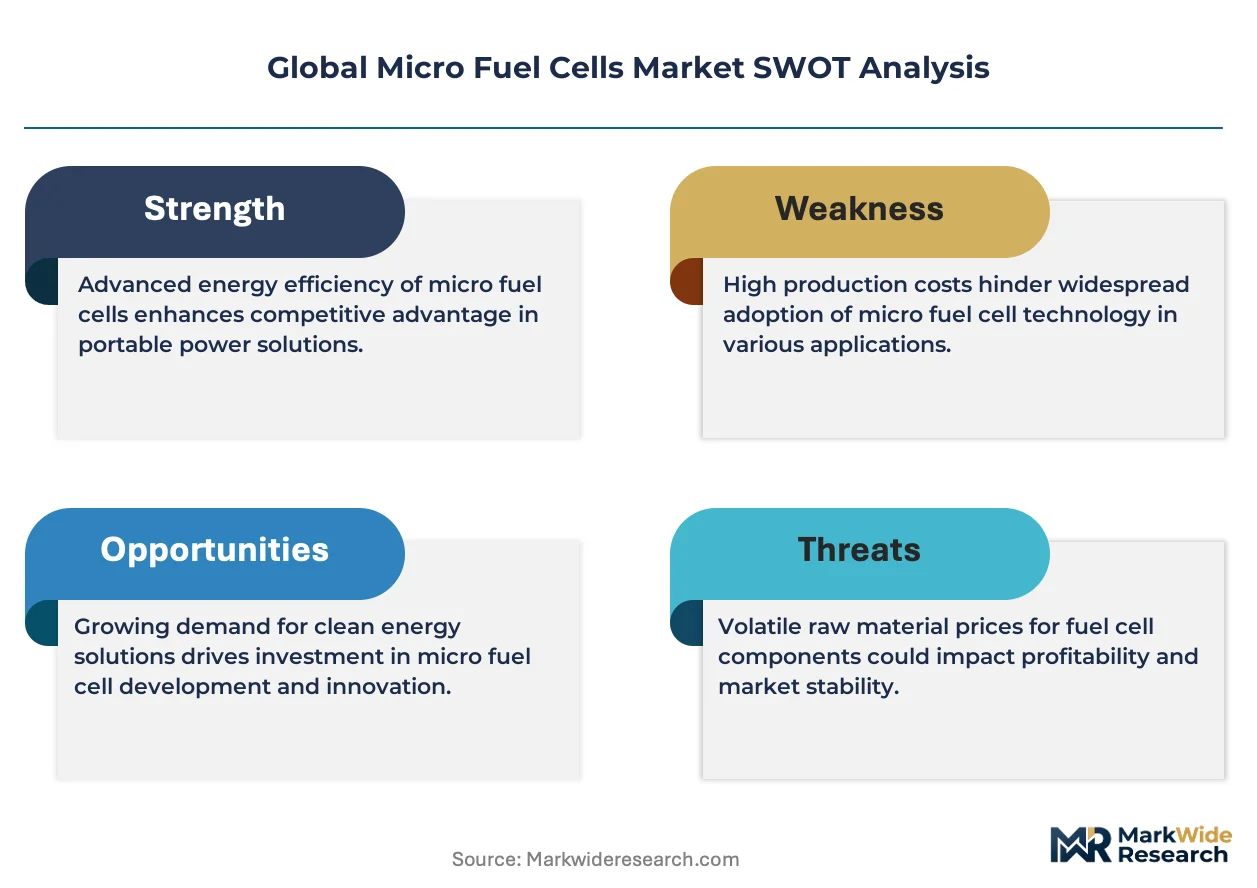
- Platinum catalyst dependency:ECHA REACH regulations constrain supply chains for membrane electrode assemblies, elevating input cost volatility for European manufacturers.
- FAA airborne certification:Hydrogen storage miniaturization protocols remain unresolved for commercial aviation auxiliary power, blocking a high-value application vertical.
- Lithium-ion substitution pressure:Solid-state battery energy density improvements threaten micro fuel cell positioning in consumer electronics below 50-watt output thresholds.
Strategic Opportunities
- Remote monitoring infrastructure:Off-grid environmental sensors in Australia and Canada present unserved demand for extended-duration power without battery replacement logistics.
- South Korea consumer electronics cluster:Samsung and LG supply chain integration programs create captive offtake channels for compact fuel cell prototypes in next-generation device categories.
- EU Green Deal industrial decarbonization:Auxiliary power unit mandates for material handling equipment open commercial vehicle applications previously dominated by diesel generators.
Industry Challenges
- Electrocatalyst manufacturing talent:Specialized expertise in membrane electrode assembly fabrication concentrates in Germany and Japan, constraining capacity expansion elsewhere.
- Multi-regional certification timelines:Simultaneous navigation of FAA, METI, and ISO hydrogen safety standards extends product launch cycles by 18-24 months for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micro Fuel Cells Market |
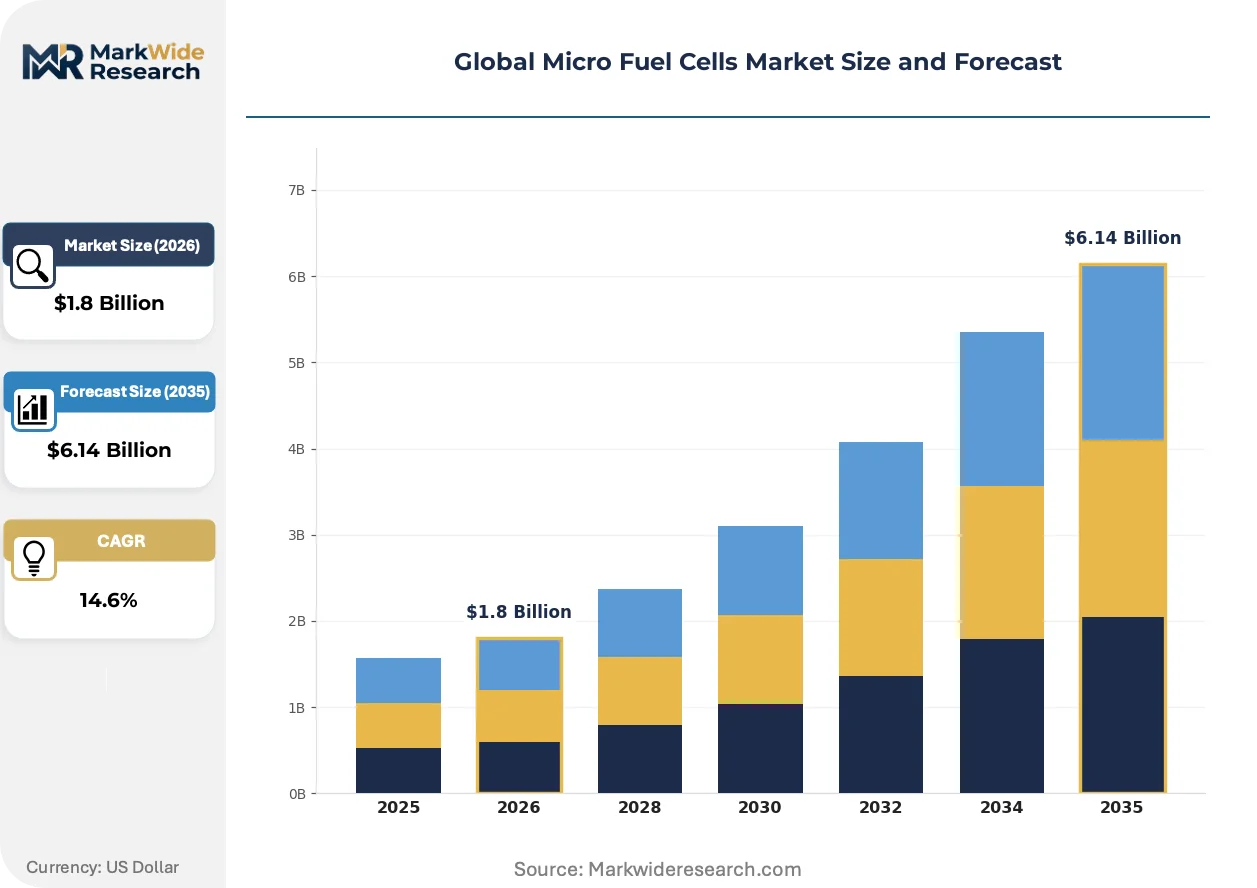
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Methanol Fuel Cells, Proton Exchange Membrane Fuel Cells, Alkaline Fuel Cells, Microbial Fuel Cells End User: Consumer Electronics, Automotive OEMs, Military Applications, Portable Devices Technology: Catalyst Technology, Membrane Technology, Hybrid Technology, System Architecture Application: Backup Power Supply, Remote Monitoring, Electric Vehicles, Wearable Electronics |
| Companies Covered | Siemens, Plug Power, Toshiba, SFC Energy, Panasonic, Nuvera Fuel Cells, Intelligent Energy, PowerCell Sweden, Aisin Seiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micro Fuel Cells Market Strategic Shifts
Membrane electrode assembly architectures are bifurcating between air-cooled field systems and liquid-cooled stationary units, with thermal management choices now determining addressable market boundaries rather than pure electrochemical performance.
Direct methanol fuel cell technology converts liquid methanol to electrical power through platinum-ruthenium catalyzed oxidation at the anode. Military procurement offices in the United States and Germany are adopting this architecture for soldier-worn loads at accelerating contract velocity. The technology is expanding into remote monitoring applications where battery replacement logistics prove cost-prohibitive for dispersed sensor networks.
Japan's METI enacted hydrogen safety standards for micro-scale systems that directly shape wearable electronics qualification timelines. These regulations compress domestic product development cycles while creating technical barriers for non-compliant imports. Consumer electronics manufacturers targeting Japanese distribution channels must redesign fuel storage geometries to satisfy localized pressure vessel specifications.
Defense procurement offices are abandoning battery ownership models for battlefield power, instead contracting fuel logistics as a service. Equipment suppliers in Germany and the United States are restructuring pricing around methanol delivery rather than hardware transfer. This transformation is most visible in NATO-aligned ministries where operational readiness metrics now prioritize refueling simplicity over capital expenditure minimization.
Global Micro Fuel Cells Market Segmentation
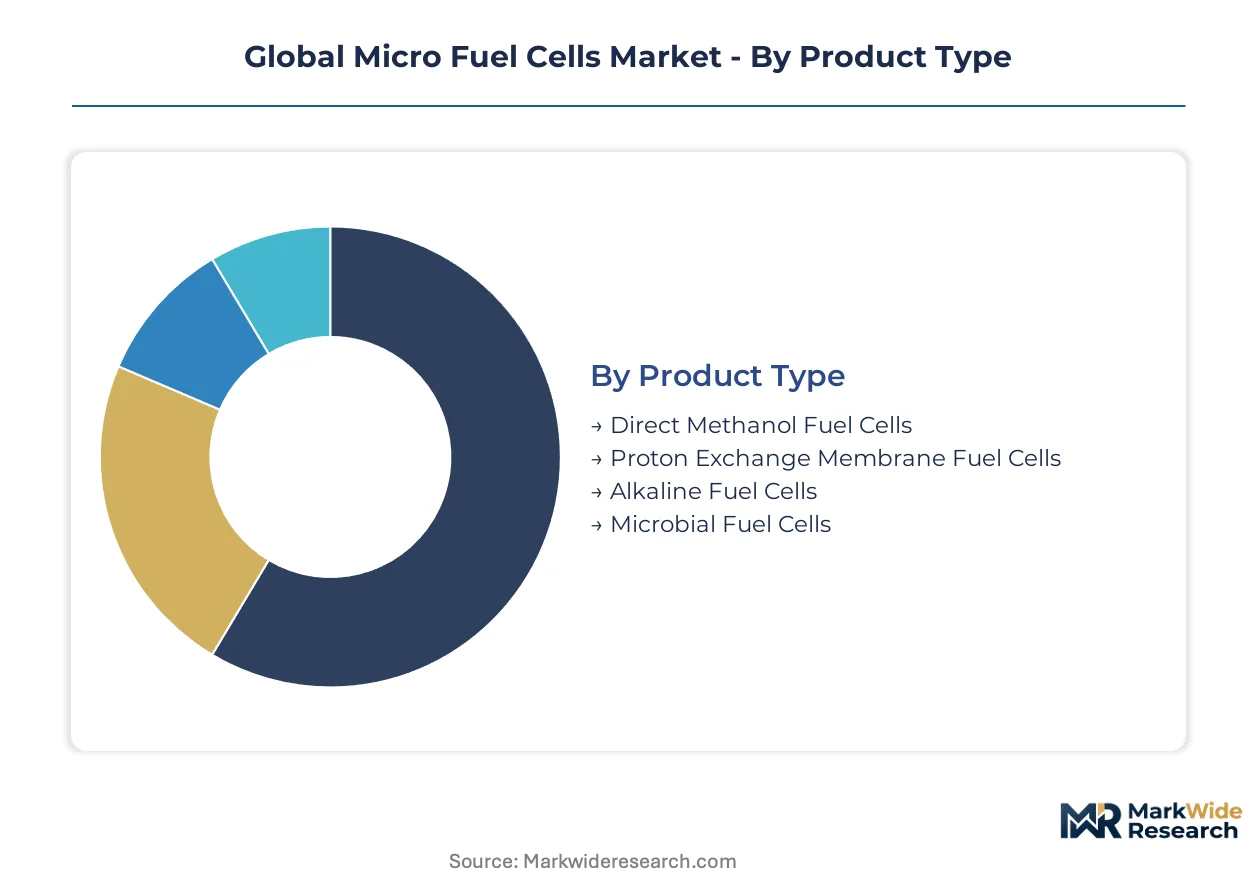
Micro fuel cell architectures diverge sharply across electrochemical pathways, thermal management requirements, and membrane electrode assembly specifications. Each segmentation axis reveals distinct competitive dynamics between incumbent liquid-fuel systems and emerging hydrogen-fed alternatives.
Product Type:
Electrochemical conversion chemistry determines fuel handling logistics, catalyst loading economics, and military certification trajectories across product tiers.
- Direct Methanol Fuel Cells:Platinum-ruthenium anode catalysts oxidize liquid methanol at 60-120°C operating temperatures, eliminating compressed hydrogen storage requirements. NATO procurement offices in Germany and the United States specify this architecture for soldier-worn loads under 2 kilograms where forward-deployed refueling simplicity outweighs energy density penalties.
- Proton Exchange Membrane Fuel Cells:Solid polymer electrolyte membranes conduct protons between hydrogen-fed anodes and air-breathing cathodes, achieving rapid cold-start capability below freezing temperatures. Japanese METI hydrogen safety standards are accelerating domestic qualification timelines for wearable electronics integration in Tokyo and Osaka manufacturing clusters.
- Alkaline Fuel Cells:Liquid potassium hydroxide electrolyte systems achieve higher conversion efficiency than acidic alternatives but require pure hydrogen and oxygen feeds, constraining deployment to controlled industrial environments.
- Microbial Fuel Cells:Bioelectrochemical systems leverage exoelectrogenic bacteria to oxidize organic substrates, finding niche validation in wastewater treatment facilities and remote ecological monitoring stations where fuel logistics are impractical.
Direct Methanol Fuel Cells lead on scale; Proton Exchange Membrane Fuel Cells lead on momentum.
End User:
Customer procurement patterns split between mission-critical military specifications and consumer electronics volume economics.
- Consumer Electronics:Samsung and LG supply chain integration programs in South Korea are validating compact fuel cell prototypes for next-generation device categories where battery weight constraints limit functionality.
- Automotive OEMs:Auxiliary power unit applications in commercial vehicles are expanding under EU Green Deal industrial decarbonization mandates, displacing diesel generators in material handling equipment across German manufacturing bases.
- Military Applications:Methanol logistics-as-a-service contracts are replacing battery ownership models across NATO-aligned defense ministries, with SFC Energy and Intelligent Energy competing on field refueling architecture.
- Portable Devices:Off-grid environmental sensor networks in Australia and Canada present unserved demand for extended-duration power without battery replacement logistics in dispersed deployment scenarios.
Military Applications command premium pricing; Consumer Electronics offer volume scaling pathways.
Technology:
Component-level specialization determines thermal efficiency thresholds and manufacturing talent concentration.
- Catalyst Technology:Platinum group metal loading optimization dominates membrane electrode assembly cost structures, with ECHA REACH regulations constraining European supply chains and elevating input volatility.
- Membrane Technology:Thin-film electrolyte deposition advances are enabling solid oxide miniaturization below 500°C operating temperatures, unlocking auxiliary power applications previously reserved for combustion engines.
- Hybrid Technology:Fuel cell-battery hybrid architectures optimize transient response and peak load handling for wearable electronics where power demand fluctuates unpredictably.
- System Architecture:Air-cooled versus liquid-cooled thermal management choices now determine addressable market boundaries rather than pure electrochemical performance metrics.
Membrane Technology anchors differentiation; Catalyst Technology concentrates cost risk.
Application:
Use-case power duration requirements and refueling accessibility shape technology selection criteria.
- Backup Power Supply:Stationary installations in telecommunications infrastructure prioritize reliability over energy density, favoring established direct methanol architectures with proven field longevity.
- Remote Monitoring:Dispersed environmental sensors in Australian outback and Canadian Arctic regions demand multi-year autonomous operation where battery replacement logistics prove cost-prohibitive.
- Electric Vehicles:Range-extender auxiliary power units for light electric vehicles are gaining traction in Japanese urban mobility pilots under METI hydrogen roadmap deployment timelines.
- Wearable Electronics:Form factor constraints below 100 milliliters fuel storage capacity are driving solid-state fuel cell research at Toshiba and competing Japanese electronics conglomerates.
Remote Monitoring captures unserved demand; Wearable Electronics faces solid-state battery substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as suppliers migrate toward jurisdictions with streamlined hydrogen safety certification. Cost-of-compliance gaps between METI's accelerated timelines and FAA's unresolved protocols are concentrating investment in Asia-Pacific production bases.
United States
Defense procurement offices are abandoning battery ownership models for methanol logistics-as-a-service contracts. FAA certification protocols for airborne hydrogen storage remain unresolved, blocking commercial aviation auxiliary power applications. Battlefield energy requirements in Virginia and Texas procurement corridors now specify refuelable systems under 2 kilograms.
Germany
NATO-aligned defense ministries are rewriting portable power specifications to eliminate forward-deployed charging logistics. ECHA REACH regulations constrain platinum catalyst supply chains for membrane electrode assemblies. SFC Energy anchors European battlefield energy contracts from manufacturing bases in Bavaria and North Rhine-Westphalia.
Japan
METI hydrogen roadmap timelines are compressing domestic certification standards for wearable micro fuel cell systems. Carbon neutrality targets accelerate product qualification for consumer electronics integration. Toshiba extends solid-state fuel cell research into compact form factors from Tokyo and Osaka manufacturing clusters.
South Korea
Samsung and LG supply chain integration programs are validating compact fuel cell prototypes for next-generation device categories. Domestic demand concentrates in Seoul's consumer electronics cluster where battery weight constraints limit functionality. National industrial policy supports hydrogen economy transition through targeted R&D subsidies.
Australia
Off-grid environmental sensor networks in Queensland and Western Australia present unserved demand for extended-duration power without battery replacement logistics. Remote monitoring infrastructure spans dispersed deployment scenarios where fuel logistics prove cost-prohibitive. National hydrogen strategy frameworks are accelerating pilot programs for remote power applications.
Global Micro Fuel Cells Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers build membrane electrode assembly fabrication lines to capture NATO defense contracts. The vendor base splits between integrated fuel cell system manufacturers and specialized membrane technology providers. Three archetypes define competitive positioning: defense-focused logistics-as-a-service contractors, consumer electronics integration specialists, and auxiliary power unit developers for commercial vehicles. Geographic expansion and strategic partnerships represent the dominant competitive moves as firms navigate multi-regional certification timelines.
Within the defense-contractor archetype, SFC Energy and Intelligent Energy exemplify divergent thermal management approaches for soldier-worn loads. Toshiba occupies a position bridging consumer electronics and solid-state research vectors. These three anchors represent distinct strategic postures: European battlefield logistics specialization, air-cooled system architecture development, and Japanese conglomerate R&D integration.
| Leading Market Players |
|---|
| Siemens |
| Plug Power |
| Toshiba |
| SFC Energy |
| Panasonic |
| Nuvera Fuel Cells |
| Intelligent Energy |
| PowerCell Sweden |
| Aisin Seiki |
| Others |
Value Chain & Pricing Dynamics
Platinum group metal price indices cascade through membrane electrode assembly fabrication into tiered product pricing across military and consumer electronics segments. ECHA REACH compliance costs in Germany and platinum-ruthenium loading optimization in Japan concentrate cost pressure on European and Asian manufacturers serving NATO defense contracts.
Pricing Analysis
Distributor margins for direct methanol fuel cell systems compress pricing stratification across premium, standard, and economy tiers based on certification grade and volume scale. METI-compliant systems for Japanese consumer electronics command brand premiums over uncertified alternatives. Cost compression in standard-tier membrane electrode assemblies intensifies as solid-state battery substitution threatens sub-50-watt applications. Military procurement offices exhibit lowest price sensitivity due to operational readiness mandates, while consumer electronics OEMs in South Korea drive hardest bargain negotiations.
Supply Chain Analysis
Specialized electrocatalyst manufacturing talent concentrates in Germany and Japan, constraining membrane electrode assembly capacity expansion elsewhere. Supply chains draw from South Korean precision component suppliers, German platinum group metal processors, and Japanese thin-film electrolyte deposition specialists. Single-source vulnerability in platinum-ruthenium catalyst sourcing elevates risk exposure for European manufacturers under ECHA REACH restrictions. Distribution runs through defense logistics contractors for military applications and direct OEM integration programs for consumer electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Micro Fuel Cells Market compounds steadily as defense procurement shifts from battery ownership to fuel logistics-as-a-service models across NATO-aligned ministries.
For Market Incumbents: Hedge platinum price volatility through long-term offtake agreements with South African and Russian metal suppliers. Deepen backward integration into membrane electrode assembly fabrication in Bavaria and North Rhine-Westphalia to defend margin position against emerging Asian competitors. Accelerate METI certification investment to maintain access to Japanese consumer electronics distribution channels threatened by solid-state battery substitution. For New Entrants and Emerging Players: The 40-60% price-point gap between premium METI-certified systems and uncertified economy alternatives creates white-space opportunity in Australian and Canadian remote monitoring infrastructure. Target off-grid environmental sensor networks where battery replacement logistics prove cost-prohibitive. Pursue direct-to-OEM partnerships with material handling equipment manufacturers under EU Green Deal auxiliary power mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane electrode assembly fabrication expertise concentrates in Germany and Japan. Five-to-ten year viability favors specialists with captive defense contract pipelines and METI certification capabilities. Acquisition target archetype: mid-cap fuel cell developers with NATO logistics-as-a-service contracts and thin-film electrolyte intellectual property. Watch for FAA hydrogen storage miniaturization protocol resolution as inflection signal for commercial aviation auxiliary power vertical.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Capacity Expansion | Captures NATO defense contract volume as methanol logistics-as-a-service models replace battery procurement. |
| Backward Integration into Catalyst Sourcing | Mitigates ECHA REACH platinum supply constraints for European manufacturers serving German defense ministries. |
| METI Certification Acceleration | Unlocks Japanese consumer electronics distribution channels for wearable micro fuel cell integration. |
| Remote Monitoring Partnership Development | Addresses unserved demand in Australian outback and Canadian Arctic environmental sensor networks. |
| Thin-Film Electrolyte R&D Investment | Enables solid oxide miniaturization below 500°C for auxiliary power applications in material handling equipment. |
Study Parameters
Coverage spans North America, Europe, Asia-Pacific, and Australia, with primary inputs from each combining interviews with defense procurement officers, fuel cell system engineers, membrane technology specialists, and consumer electronics supply chain managers. Secondary validation draws from FAA certification filings, METI hydrogen safety standard updates, ECHA REACH regulatory amendments, and NATO battlefield energy specification documents. Bottom-up unit shipment estimates triangulate against top-down defense budget allocation analysis.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include electrochemical pathway, thermal management architecture, membrane electrode assembly specification, end-use application, and regional regulatory cluster. CAGRs derive from deployment trajectory analysis of soldier-worn power systems, consumer electronics integration timelines, and auxiliary power unit commercialization curves. Industry-specific inputs incorporate methanol logistics cost curves and platinum group metal price volatility bands.
Caveats apply where FAA hydrogen storage miniaturization protocol resolution, ECHA REACH platinum catalyst restriction tightening, or solid-state battery energy density breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about defense procurement velocity and METI certification timeline compression. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market