
 Fuel Cell Interconnectors Market | 2026-2036
Fuel Cell Interconnectors Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Interconnectors Market Analytics
Modular stack packaging is consolidating around standardized bipolar plate dimensions that simplify procurement for original equipment manufacturers. Ballard Power Systems leverages vertical integration across membrane electrode assembly and plate stamping to control cost curves. Plug Power sustains geographic dominance in North American material handling through captive hydrogen infrastructure. Ceres Power differentiates via steel interconnect architectures optimized for solid oxide operating temperatures above 700°C.
Fuel cell interconnectors are conductive components that electrically series-connect individual cells within a stack while distributing reactant gases and managing thermal flux; metallic bipolar plates typically achieve contact resistances below 10 mΩ·cm² through gold or nitride surface coatings to prevent corrosion in acidic PEM environments. The metallic material segment anchors volume production due to stamping scalability and thickness reduction potential below 0.1 mm. Composite plates occupy niche aerospace and portable power roles where weight constraints override cost sensitivity. Solid oxide technology leads in stationary power generation applications where ceramic interconnects tolerate extreme thermal cycling.
EPA tailpipe standards and the EU F-Gas Regulation shape product roadmaps by mandating zero-emission pathways for commercial vehicle fleets and restricting fluorinated membrane chemistries. California Air Resources Board zero-emission vehicle mandates directly accelerate bipolar plate qualification cycles for heavy-duty platforms. ISO 14687 hydrogen fuel quality standards and REACH substance restrictions govern material selection and surface coating compositions across export markets. Stakeholders must monitor evolving certification timelines as regional hydrogen hub deployments scale manufacturing volumes without compromising plate-to-plate dimensional tolerances.
Market Dynamics
Stack standardization pressures and tightening emissions mandates are compressing bipolar plate qualification cycles while concentrating procurement around South Korean and German manufacturing clusters.
Growth Catalysts
- California Air Resources Board zero-emission mandates:Heavy-duty trucking fleets in the United States face binding decarbonization timelines that accelerate fuel cell stack deployment and interconnect demand.
- Steel stamping scalability:Metallic bipolar plate manufacturing achieves thickness reduction below 0.1 mm, enabling cost curves that match proton exchange membrane fuel cell volume ramps.
- South Korean hydrogen hub buildouts:Doosan and Hyundai supply chains anchor concentrated manufacturing capacity that pulls interconnect procurement toward domestic qualified suppliers.
Market Restraints
- Noble metal coating cost volatility:Gold and nitride surface treatments for corrosion resistance in acidic PEM environments expose plate margins to precious metal price swings.
- Ceramic interconnect supply concentration:Solid oxide fuel cell stationary power applications depend on limited high-temperature ceramic manufacturing capacity concentrated in specialized facilities.
- REACH substance restrictions:European surface coating chemistries face compliance friction that extends material qualification timelines and limits coating formulation flexibility.
Strategic Opportunities
- India electrolyzer manufacturing scale-up:PLI scheme incentives for green hydrogen production create captive demand for interconnect components in domestic fuel cell stack assembly.
- Aviation auxiliary power units:Composite bipolar plate architectures penetrate aerospace weight-constrained applications where metallic density penalties exclude conventional solutions.
- EU F-Gas Regulation phase-down:Fluorinated membrane chemistry restrictions accelerate alternative membrane development that reshapes interconnect surface compatibility requirements.
Industry Challenges
- ISO 14687 hydrogen fuel quality certification:Plate-to-plate dimensional tolerance maintenance under high-volume manufacturing requires metrology investments that strain mid-cap supplier balance sheets.
- Membrane electrode assembly integration complexity:Bipolar plate sealing interface engineering demands specialized polymer compatibility expertise that concentrates in vertically integrated stack manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Interconnectors Market |
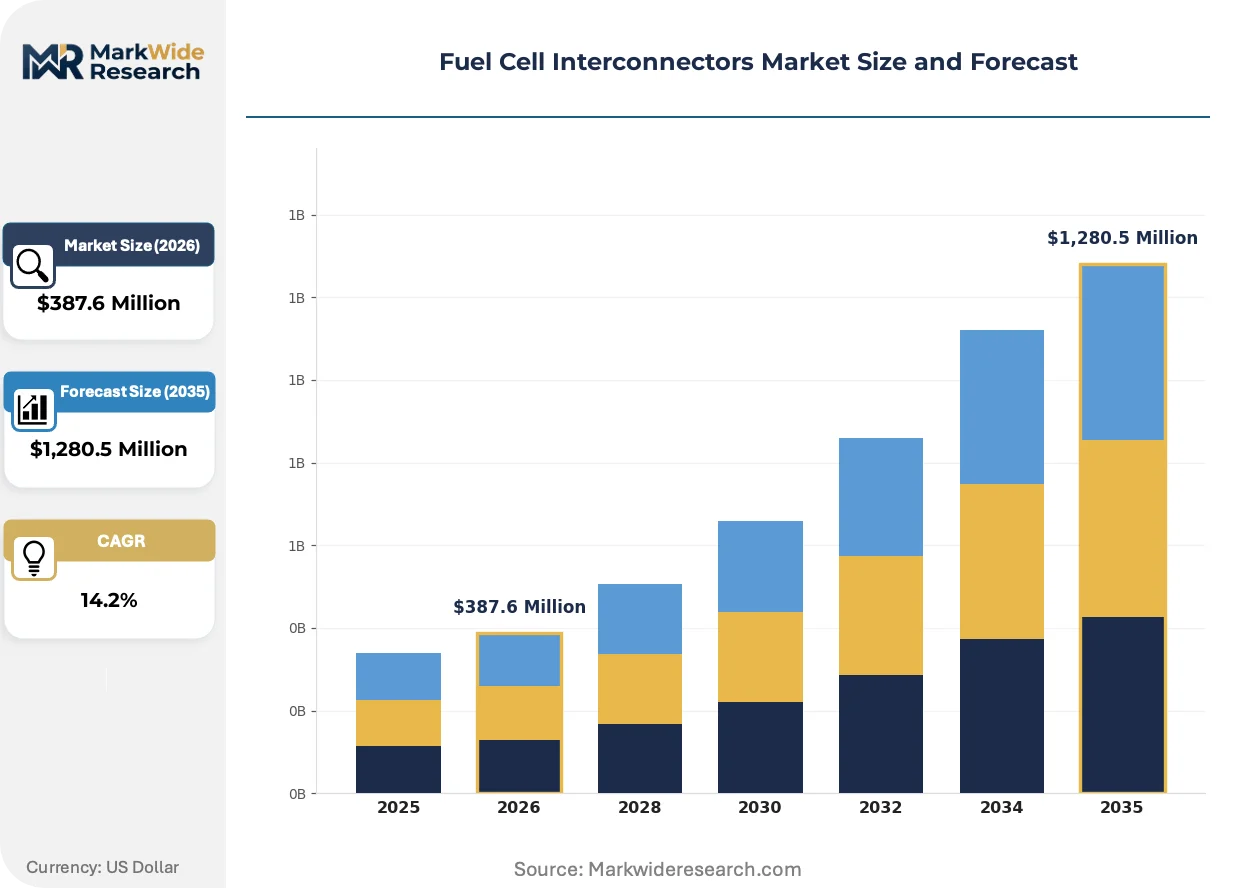
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Plates, End Plates, Manifolds, Interconnects Material: Graphite, Metallic, Composite, Polymer End User: Automotive, Industrial, Power Generation, Aerospace Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Direct Methanol |
| Companies Covered | Ballard Power Systems, Plug Power, FuelCell Energy, Bloom Energy, Ceres Power, ITM Power, SFC Energy, Doosan Fuel Cell, Horizon Fuel Cell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Interconnectors Market Evolving Landscape
Surface engineering advances and procurement model compression are reshaping how interconnect specifications propagate through fuel cell supply chains.
Ultrathin metallic bipolar plates with sub-0.1 mm thickness profiles are expanding into heavy-duty trucking stack designs where volumetric power density requirements dominate total cost of ownership calculations. North American fleet operators specify these architectures for 2026-2027 platform launches. The technology is expanding into applications previously reserved for thicker graphite composite alternatives.
EPA tailpipe standards for commercial vehicles are forcing zero-emission powertrain commitments that cascade into accelerated bipolar plate qualification cycles. California's Advanced Clean Trucks regulation creates binding purchase obligations for heavy-duty OEMs. Stack manufacturers respond by pre-qualifying multiple plate suppliers to avoid single-source bottlenecks.
Buyer consolidation around integrated stack suppliers is compressing independent component procurement channels. Material handling and stationary power end-users increasingly source complete fuel cell systems rather than discrete interconnects. Germany and South Korea exhibit the most pronounced channel consolidation as hydrogen hub deployments concentrate vendor relationships.
Fuel Cell Interconnectors Market Segmentation
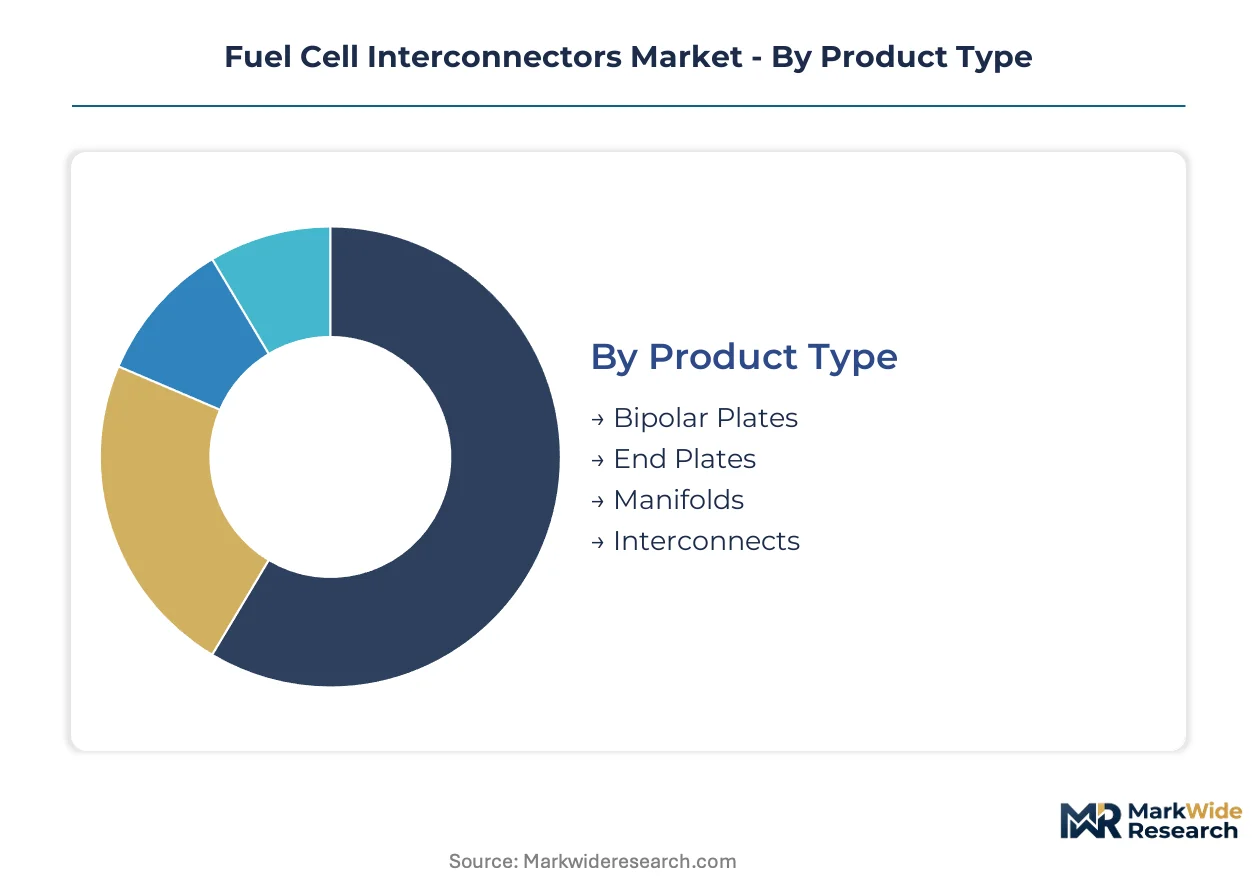
Segmentation reveals how capital deployment and technical specifications diverge across fuel cell interconnect applications. Procurement patterns bifurcate between high-volume automotive stamping operations and specialized ceramic manufacturing for stationary power.
Product Type:
Capital intensity peaks with bipolar plate manufacturing, where precision stamping and coating lines demand the heaviest upfront tooling investment.
- Bipolar Plates:Stamped metallic substrates with gold or nitride surface coatings achieve contact resistances below 10 mΩ·cm² for proton exchange membrane stacks. Heavy-duty trucking fleets in California and Germany specify ultrathin profiles below 0.1 mm to maximize volumetric power density.
- End Plates:Compression-molded polymer or machined aluminum structures anchor stack mechanical integrity and sealing interfaces. Material handling equipment deployments through Plug Power's captive infrastructure concentrate procurement around integrated stack suppliers rather than discrete component vendors.
- Manifolds:Gas distribution channels machined or molded to match specific stack geometries.
- Interconnects:Ceramic or metallic current collectors for solid oxide and alkaline architectures.
Bipolar plates absorb the bulk of installed capacity; end plates are expanding most quickly as modular stack packaging standardizes around captive supplier relationships.
Material:
Cost tier stratification separates commodity-scale metallic stamping from premium composite formulations where weight constraints override unit economics.
- Metallic:Stainless steel and titanium substrates dominate volume production through stamping scalability and thickness reduction potential. South Korean manufacturing clusters serving Doosan Fuel Cell and Hyundai supply chains concentrate qualified supplier capacity.
- Graphite:Compression-molded plates with resin binders occupy mid-tier stationary power applications where corrosion resistance in acidic environments matches metallic alternatives at lower tooling cost.
- Composite:Carbon-fiber reinforced polymers penetrate aerospace auxiliary power units where density penalties exclude conventional metallic solutions.
- Polymer:Injection-molded insulating and structural components for end plate and manifold applications.
Metallic materials command the dominant production share; composites are climbing the fastest as aviation electrification programs validate weight-reduced architectures.
End User:
Application maturity varies sharply between established material handling deployments and nascent aerospace qualification cycles.
- Automotive:Heavy-duty trucking platforms in North America and Europe drive bipolar plate demand through zero-emission mandates from California Air Resources Board and tightening EU frameworks. OEM pre-qualification of multiple plate suppliers accelerates to avoid single-source bottlenecks.
- Industrial:Forklift and stationary power systems sustain geographic concentration in North American material handling through captive hydrogen infrastructure.
- Power Generation:Solid oxide fuel cell installations for grid-scale and distributed generation.
- Aerospace:Auxiliary power unit development programs evaluating composite plate architectures.
Automotive applications anchor current volume; aerospace is gaining share fastest as weight-constrained platforms advance through certification.
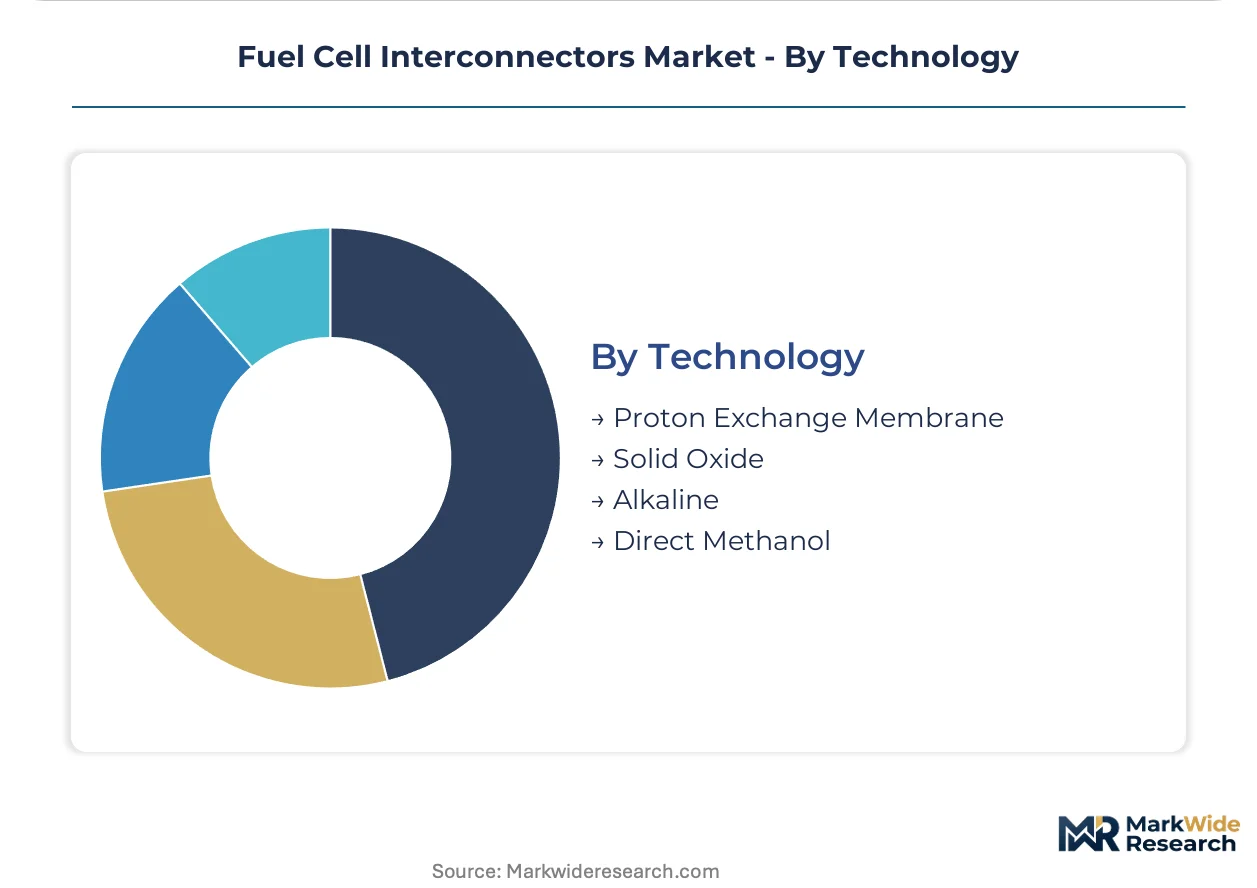
Technology:
Operating temperature regimes dictate material selection and manufacturing process compatibility across fuel cell chemistries.
- Proton Exchange Membrane:Low-temperature operation below 100°C enables metallic bipolar plate architectures with corrosion-resistant coatings. EPA tailpipe standards and California Advanced Clean Trucks regulation cascade into accelerated plate qualification timelines for commercial vehicle stacks.
- Solid Oxide:Ceramic interconnects tolerate extreme thermal cycling above 700°C in stationary power applications. Ceres Power's steel interconnect architectures differentiate through high-temperature metallic alternatives that challenge conventional ceramic supply concentration.
- Alkaline:Liquid electrolyte systems with reduced precious metal catalyst requirements.
- Direct Methanol:Portable power applications with specialized interconnect compatibility for methanol crossover environments.
Proton exchange membrane technology holds the dominant installed base; solid oxide is expanding most rapidly as stationary power generation scales manufacturing volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea and Germany's hydrogen corridor states concentrate qualified manufacturing capacity for fuel cell interconnectors, with tax incentives and production-linked schemes pulling supply chain investments toward clustered deployment zones.
United States
Heavy-duty trucking fleets in California drive bipolar plate demand through zero-emission mandates binding OEM purchase obligations. EPA tailpipe standards and California Air Resources Board regulations compress qualification timelines for commercial vehicle stacks. The San Francisco Bay Area and Los Angeles manufacturing corridors anchor pre-qualification programs for multiple plate suppliers.
Germany
Industrial hydrogen hub buildouts in North Rhine-Westphalia and Bavaria accelerate stationary power interconnect procurement. The EU F-Gas Regulation and national hydrogen strategy shape surface coating chemistry roadmaps for PEM compatibility. Stuttgart and Munich industrial clusters concentrate bipolar plate stamping capacity serving domestic fuel cell stack assembly.
South Korea
Doosan Fuel Cell and Hyundai supply chains anchor concentrated manufacturing demand for metallic interconnect components. Production-linked incentive schemes under the national hydrogen economy roadmap pull qualified supplier capacity toward domestic manufacturing zones. The Ulsan and Incheon industrial corridors host integrated stack production facilities with captive interconnect sourcing.
Japan
METI hydrogen and fuel cell strategic roadmaps guide interconnect material selection for automotive and stationary applications. JIS standards and national decarbonization targets accelerate bipolar plate qualification for commercial vehicle platforms. The Nagoya and Tokyo metropolitan manufacturing belts concentrate precision stamping operations for PEM stack components.
China
Dual carbon goals and GB standards for fuel cell electric vehicles expand domestic interconnect production capacity. MIIT new energy vehicle mandates cascade into bipolar plate demand for heavy-duty truck and bus platforms. The Yangtze River Delta and Pearl River Delta hydrogen industry clusters concentrate metallic plate manufacturing for regional stack assembly.
Fuel Cell Interconnectors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the fuel cell interconnectors competitive landscape. The vendor base stratifies between vertically integrated stack manufacturers controlling captive interconnect production and independent component suppliers serving modular procurement channels. Three archetypes dominate: integrated system houses with in-house plate stamping, specialized metallic fabricators with coating expertise, and materials-science firms developing ceramic alternatives for high-temperature applications. Capacity expansion and strategic partnerships represent the dominant competitive moves as hydrogen hub deployments scale manufacturing volumes.
Among North American integrated system houses, Ballard Power Systems and Plug Power occupy positions exemplifying the captive production archetype, with geographic concentration in fuel cell manufacturing corridors. FuelCell Energy and Bloom Energy represent the stationary power specialist tier, while Ceres Power anchors the high-temperature metallic interconnect differentiation vector for solid oxide applications. Doosan Fuel Cell exemplifies the Asia-Pacific conglomerate model with supply chain concentration around domestic qualified supplier networks.
| Leading Market Players |
|---|
| Ballard Power Systems |
| Plug Power |
| FuelCell Energy |
| Bloom Energy |
| Ceres Power |
| ITM Power |
| SFC Energy |
| Doosan Fuel Cell |
| Horizon Fuel Cell Technologies |
| Others |
Value Network & Pricing Analysis
California Air Resources Board zero-emission mandates gate qualified supply access and premium-tier pricing power by restricting commercial vehicle stack deployments to pre-certified plate suppliers with proven corrosion resistance below 10 mΩ·cm².
Pricing Analysis
Margin tightening in standard-grade metallic plates reflects stamping overcapacity in South Korean manufacturing clusters competing for Doosan and Hyundai volume. Three-tier pricing structure across premium, standard, and economy levels separates gold-coated aerospace-qualified plates from nitride-treated automotive grades and uncoated graphite alternatives. Cost-down pressure on economy-tier graphite plates accelerates because Chinese compression-molding capacity expansion outpaces stationary power demand growth. Heavy-duty trucking OEMs exhibit highest price sensitivity due to total cost of ownership calculations, while aerospace auxiliary power unit developers accept premium positioning for weight-constrained composite architectures.
Supply Chain Analysis
Precision stamping technician shortages in Ulsan and Stuttgart industrial corridors constrain qualified bipolar plate output expansion despite capital equipment availability. Geographic supply concentration centers on South Korea, Germany, and China, with Incheon and North Rhine-Westphalia hosting integrated stack production. Raw material dependencies draw from Japanese specialty steel mills, South Korean titanium processors, and German nitride coating chemical suppliers. Single-source vulnerability persists in high-temperature ceramic interconnects for solid oxide applications, where limited furnace capacity concentrates in specialized facilities. Distribution runs through captive supplier relationships at integrated stack manufacturers rather than independent component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH substance restrictions and California Air Resources Board certification timelines erect barrier-to-entry moats favoring incumbent qualified suppliers with amortized metrology investments.
For Market Incumbents: Acquire precision stamping and coating equipment clusters to consolidate manufacturing footprint around South Korean and German hydrogen hub zones. Defensive positioning requires pre-qualifying multiple plate suppliers per stack program to mitigate single-source bottlenecks as EPA tailpipe standards compress commercial vehicle deployment timelines. Capacity addition in Incheon and Bavaria anchors geographic concentration strategies. For New Entrants and Emerging Players: Direct-to-stack-manufacturer digital procurement platforms offer white-space entry around modular packaging standardization. India's electrolyzer manufacturing scale-up under PLI scheme incentives presents the most penetrable geography for greenfield interconnect qualification. Composite bipolar plate architectures for aviation auxiliary power units provide application-specific differentiation where metallic density penalties exclude established suppliers. For Investors and Strategic Acquirers: Multiple plate supplier pre-qualification announcements by heavy-duty OEMs signal the leading indicator that manufacturing scale is transitioning from pilot to commercial volume. Five-to-ten year viability favors vertically integrated stack manufacturers with captive interconnect production over independent component suppliers facing channel compression. Acquisition target archetype: mid-cap metallic fabricators with coating expertise and existing automotive qualification relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemistry | In-house nitride and gold surface treatment control insulates plate margins from precious metal price volatility. |
| Geographic Manufacturing Footprint Expansion | Ulsan and Incheon cluster proximity to Doosan and Hyundai supply chains reduces logistics cost and qualification friction. |
| Technology Licensing for Composite Architectures | Carbon-fiber reinforced polymer plate IP partnerships penetrate aerospace weight-constrained applications. |
| Long-term Supply Agreement with Heavy-duty OEMs | California Advanced Clean Trucks regulation binding purchase obligations lock in volume commitments. |
| Joint Venture for Ceramic Interconnect Scale-up | High-temperature furnace capacity partnerships address solid oxide fuel cell stationary power supply concentration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with fuel cell stack engineering directors, bipolar plate procurement managers, hydrogen hub project developers, and surface coating R&D leads. Primary fieldwork triangulated against EPA enforcement actions, California Air Resources Board certification databases, EU F-Gas Regulation implementation reports, and South Korean hydrogen economy roadmap progress disclosures. Bottom-up stack deployment forecasts and top-down metallic materials demand estimates converged through iterative validation.
Segment-level granularity modeled technology chemistry, plate material substrate, end-use application, and geographic manufacturing cluster across the analysis window. Proton exchange membrane and solid oxide technology CAGRs derived from stack deployment pipelines, stationary power installation backlogs, and commercial vehicle platform launch schedules. Thickness reduction trajectories below 0.1 mm and corrosion resistance coating roadmaps informed metallic plate volume projections.
The model holds under sustained emissions mandate enforcement and hydrogen hub deployment schedules; deviation in precious metal price volatility or REACH substance restriction expansion would shift supplier margin structures and qualification timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Fuel Cell for Data Center Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market