
 Europe Fuel Cell Market | 2026-2036
Europe Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fuel Cell Market Foresight
Multi-source hydrogen procurement is recalibrating supply chain economics for European fuel cell manufacturers. Ballard Power Systems leverages its Canadian-European manufacturing bridge to anchor proton exchange membrane production for bus and truck OEMs. Ceres Power specializes in solid oxide electrolysis and fuel cell technology, positioning its steel-industry partnerships as a differentiated route to gigawatt-scale deployment. Nedstack sustains long-running marine and stationary projects, competing on stack lifetime metrics that reduce total cost of ownership for port operators.
A fuel cell converts chemical energy from hydrogen or hydrogen-rich fuels directly into electricity through electrochemical reactions, typically operating at efficiencies of 40-60% for low-temperature polymer electrolyte membrane systems and up to 85% when waste heat is captured in combined heat and power configurations. Its primary commercial purpose is to deliver zero-emission power for mobility, stationary generation, and off-grid applications where battery weight or charging infrastructure proves prohibitive. Polymer Electrolyte Membrane dominates automotive propulsion due to its cold-start capability and power density, while Solid Oxide leads in industrial applications where high-grade exhaust heat integrates with manufacturing processes. Transportation as an end user captures the deepest policy support pools, though Backup Power retains stable margins in telecom and critical infrastructure segments.
The EU Green Deal and F-Gas Regulation shape hydrogen infrastructure investment timelines and stack cooling agent specifications across member states. ECHA REACH compliance governs catalyst material sourcing, particularly platinum group metal content and recycling obligations. Germany's KBA vehicle type-approval processes and France's ANSM industrial safety standards create dual compliance tracks for cross-border equipment suppliers. Stakeholders must monitor how the EU AI Act extends to autonomous fuel cell system diagnostics and predictive maintenance algorithms in distributed energy assets.
Market Dynamics
The EU Green Deal's tightening emission ceilings for commercial vehicles are compressing hydrogen infrastructure investment timelines across member states. Steelmakers and chemical producers in Germany's industrial corridor now pilot solid oxide fuel cells for process heat, creating a dual-track demand structure that splits between mobility and stationary power applications.
Growth Catalysts
- EU Green Deal emission ceilings:Heavy-duty transportation fleets in Germany and the Netherlands face mandated fleet decarbonization deadlines, accelerating hydrogen fuel cell procurement for buses and trucks.
- Industrial process heat demand:Steelmakers and chemical plants in Germany's Ruhr region deploy solid oxide systems to replace natural gas-fired process heat, capturing waste heat for combined heat and power configurations.
- Marine sector harbor electrification:Port operators in Rotterdam and Hamburg specify fuel cell shore power systems to meet berth-side emission restrictions for container vessels.
Market Restraints
- Platinum group metal supply concentration:Catalyst materials for proton exchange membrane stacks depend on concentrated mining operations in South Africa and Russia, exposing European manufacturers to input cost volatility and geopolitical supply risk.
- F-Gas Regulation cooling agent restrictions:The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in fuel cell thermal management, forcing costly redesign of stack cooling systems before alternative fluids achieve scale.
- Battery electric vehicle substitution:Lithium-ion battery pack costs for urban delivery vans have fallen below fuel cell system costs for sub-200km daily routes, capturing light-duty segments where hydrogen refueling infrastructure remains sparse.
Strategic Opportunities
- Poland's emerging hydrogen valleys:The country's coal-dependent Silesian industrial region receives EU Just Transition Fund support to repurpose gas pipeline corridors for hydrogen distribution, creating greenfield deployment zones for stationary fuel cell installations.
- EU AI Act predictive maintenance integration:Autonomous fuel cell system diagnostics and algorithmic failure prediction in distributed energy assets open software-enabled service revenue streams for stack manufacturers.
- Maritime ammonia-to-hydrogen cracking:Converging solid oxide fuel cell technology with onboard ammonia decomposition systems addresses hydrogen storage density constraints for deep-sea shipping routes from European ports.
Industry Challenges
- Electrolyzer stack assembly technician shortage:The specialized welding and membrane electrode assembly skills required for gigawatt-scale manufacturing outpace vocational training program output in Germany and the Netherlands.
- KBA-ANSM dual certification timelines:Cross-border equipment suppliers face divergent vehicle type-approval processes between Germany's Federal Motor Transport Authority and France's National Agency for Food, Environmental and Occupational Health Safety, extending commercialization timelines by 8-14 months.
- Legacy natural gas boiler integration complexity:Industrial heat customers face piping retrofit costs and control system incompatibility when replacing existing process heat infrastructure with high-temperature fuel cell systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fuel Cell Market |
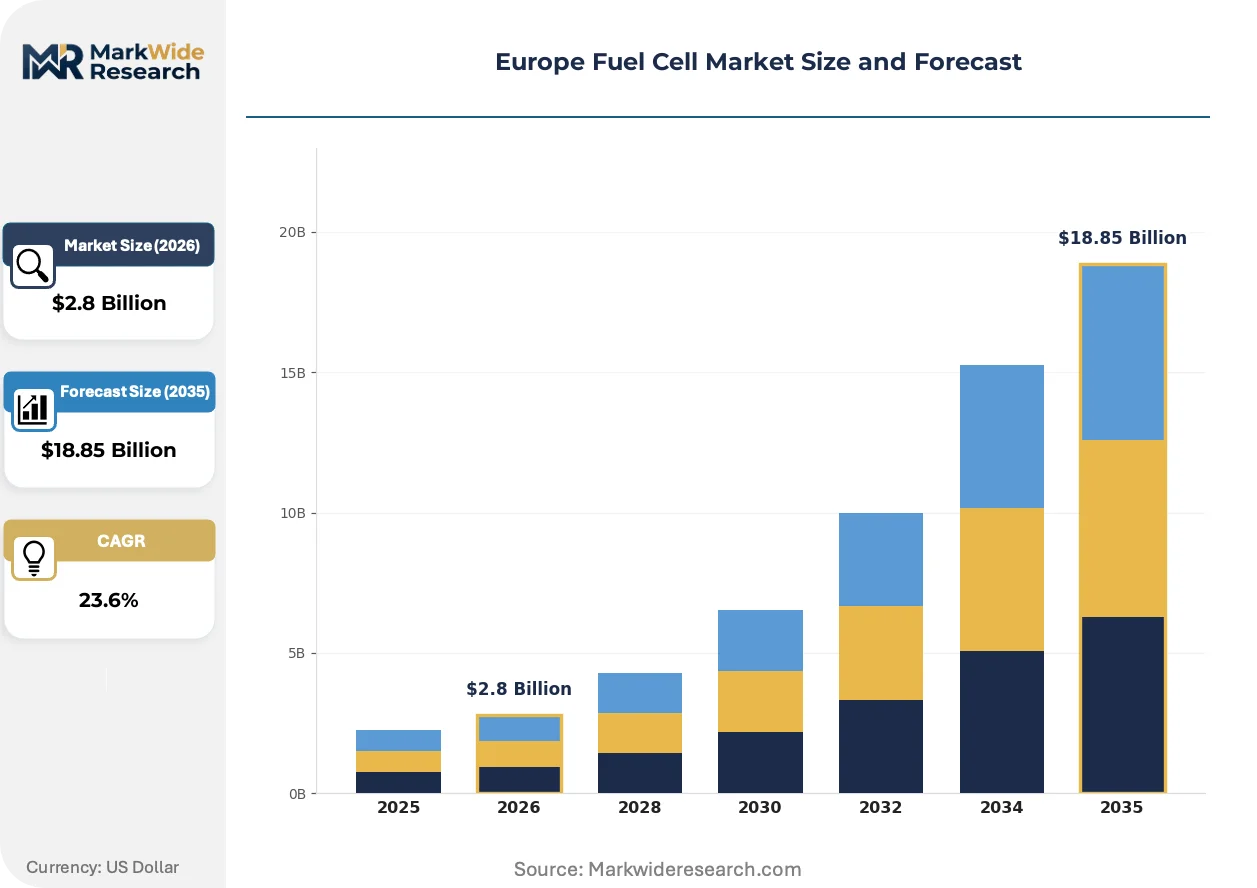
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $18.85 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Electrolyte Membrane, Solid Oxide, Phosphoric Acid, Alkaline End User: Transportation, Power Generation, Portable Electronics, Backup Power Application: Renewable Energy Storage, Industrial Applications, Automotive Propulsion, Residential Use Technology: Hydrogen Fuel Cells, Methanol Fuel Cells, Bipolar Plates, Fuel Processors |
| Companies Covered | Heliocentris, Ballard Power Systems, Ceres Power, Nedstack, PowerCell Sweden, AFC Energy, Topsoe, ElringKlinger, SFC Energy, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fuel Cell Market Shifts & Advancements
Electrolyzer-to-fuel cell technology convergence is compressing hydrogen supply chain economics across European industrial clusters. Solid oxide system manufacturers now integrate reversible operation modes, enabling single units to alternate between hydrogen production and power generation.
Automated membrane electrode assembly lines are automating quality control and stack consistency for proton exchange membrane production. Bus and truck OEMs in Germany and the Netherlands now demand defect rates below 50 parts per million for high-volume fleet contracts. This automation is compressing manufacturing lead times from 16 weeks to 6 weeks for standardized stack modules.
The EU F-Gas Regulation's phasedown schedule is forcing cooling system redesigns across low-temperature fuel cell portfolios. Stack manufacturers must qualify hydrofluoroolefin and natural refrigerant alternatives before 2027 supply restrictions take effect. The transportation segment faces the steepest compliance costs, as automotive thermal management architectures require complete revalidation.
Steelmakers in Germany's industrial corridor now contract for hydrogen supply on 15-year power purchase agreements rather than spot market procurement. This long-term offtake commitment structure transfers price risk to project developers and enables bankable financing for electrolyzer installations. The Ruhr region exhibits the densest concentration of these contracted arrangements.
Europe Fuel Cell Market Segmentation
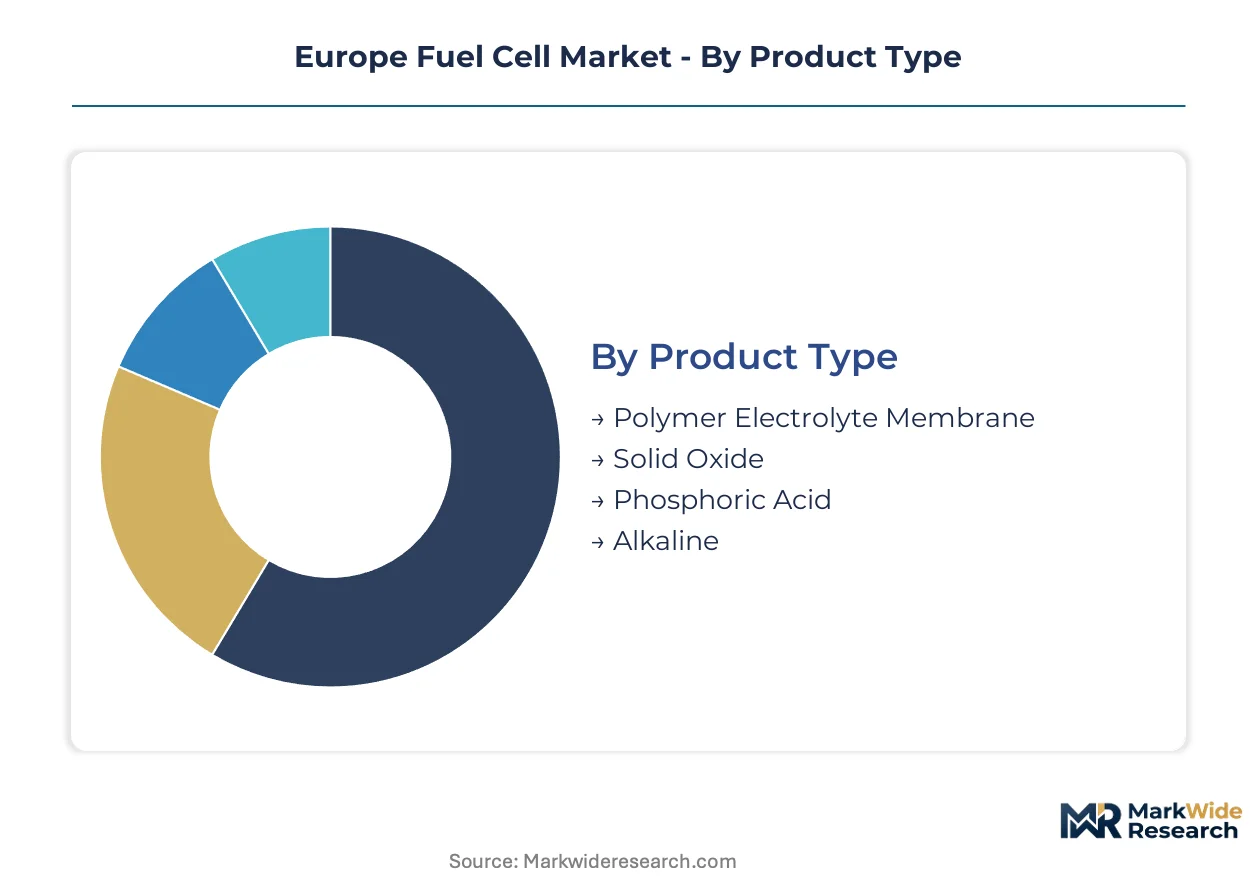
Technology selection in European fuel cell procurement follows distinct upgrade cycles across mobility and stationary applications. Product replacement timelines vary from 8-12 years for industrial solid oxide installations to 4-6 years for transportation proton exchange membrane stacks.
Product Type:
Replacement cycles differ sharply between low-temperature transportation stacks and high-temperature industrial systems, with upgrade decisions tied to electrolyzer supply contract renewals.
- Polymer Electrolyte Membrane:Operates at 60-80°C with platinum catalyst loading, enabling rapid cold-start for bus and truck fleets. German OEM procurement concentrates here as KBA type-approval pathways mature for heavy-duty vehicles.
- Solid Oxide:Ceramic electrolyte systems reach 800-1000°C, capturing waste heat for combined heat and power in Ruhr steelworks. Dutch chemical plants favor this technology for process heat integration where natural gas boilers face EU ETS carbon pricing pressure.
- Phosphoric Acid:Mid-temperature operation suits stationary commercial installations with established field durability.
- Alkaline:Lower cost catalysts using nickel and silver serve niche industrial applications with pure hydrogen supply.
Volume placements concentrate in Polymer Electrolyte Membrane; the faster expansion belongs to Solid Oxide.
End User:
Customer procurement authority separates fleet operators with centralized hydrogen contracts from distributed industrial buyers negotiating long-term power purchase agreements.
- Transportation:Municipal bus operators and logistics fleets in the Netherlands deploy proton exchange membrane stacks under EU Green Deal fleet decarbonization mandates. Rotterdam port authorities specify fuel cell shore power for berth-side compliance.
- Power Generation:Grid-scale installations and microgrids in Germany's industrial corridor anchor solid oxide demand. Steelmakers contract 15-year hydrogen supply agreements to underwrite electrolyzer project finance.
- Portable Electronics:Military and remote equipment applications sustain small-scale alkaline fuel cell demand.
- Backup Power:Telecom towers and critical infrastructure in France maintain phosphoric acid installations for extended runtime beyond battery limits.
Transportation commands the largest committed volumes; Power Generation exhibits the steepest expansion trajectory as industrial heat electrification accelerates.
Application:
Use-case economics split between revenue-generating industrial heat sales and cost-avoiding transportation compliance spending.
- Renewable Energy Storage:Reversible solid oxide systems in Denmark and Germany alternate between electrolysis and power generation, buffering wind curtailment for industrial offtake.
- Industrial Applications:Process heat substitution in German chemical plants drives high-temperature fuel cell deployment where EU carbon border adjustments threaten export competitiveness.
- Automotive Propulsion:Heavy-duty truck integration focuses on 350-700 bar hydrogen storage architectures for long-haul routes beyond battery range.
- Residential Use:Combined heat and power micro-CHP units in Japan and Korea inform European pilot programs for multi-family building integration.
Industrial Applications absorb the deepest capital commitments; Renewable Energy Storage is climbing the fastest as electrolyzer-fuel cell convergence matures.
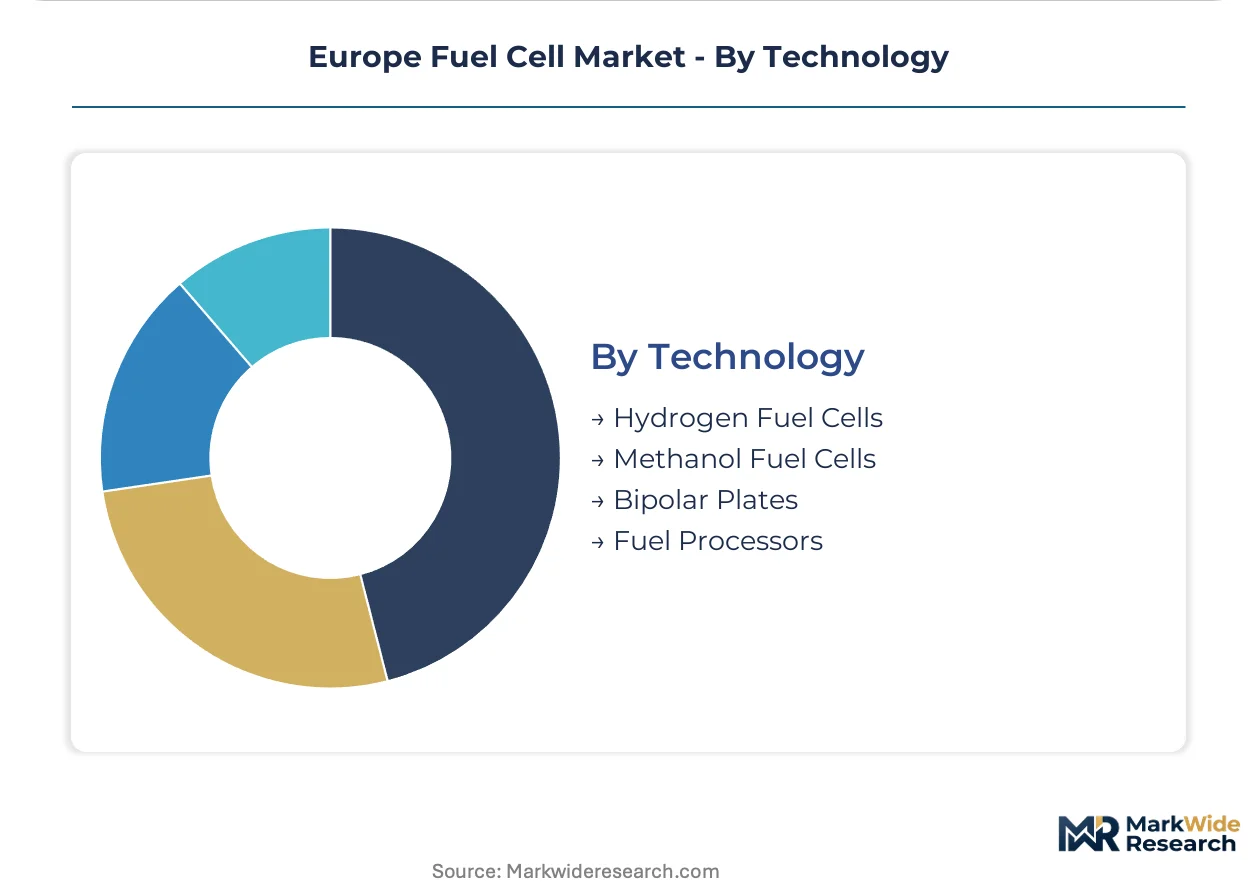
Technology:
Stack architecture choices determine supply chain exposure to platinum group metals versus ceramic manufacturing scale.
- Hydrogen Fuel Cells:Direct hydrogen oxidation dominates transportation and stationary applications, with stack designs optimizing for either pure hydrogen or reformate tolerance.
- Methanol Fuel Cells:Liquid fuel logistics suit remote and marine deployments where hydrogen infrastructure remains undeveloped, though carbon intensity depends on methanol source.
- Bipolar Plates:Graphite and metal plate manufacturing precision limits stack power density and manufacturing yield for high-volume automotive contracts.
- Fuel Processors:Onboard reforming systems enable natural gas or methanol feedstock flexibility for stationary applications with existing pipeline access.
Hydrogen Fuel Cells anchor current procurement volumes; Bipolar Plates represent the critical scaling constraint as gigawatt manufacturing targets approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum group metal supply corridors from South Africa and Russia anchor European fuel cell manufacturing exposure, concentrating catalyst procurement risk in Germany's industrial heartland where steelmakers and chemical plants pilot solid oxide installations.
Germany
Ruhr steelworks and Lower Saxony chemical clusters deploy solid oxide systems for process heat substitution under EU ETS carbon pricing pressure. KBA vehicle type-approval pathways mature for heavy-duty proton exchange membrane trucks. Hamburg port authorities specify fuel cell shore power for berth-side emission compliance.
Netherlands
Rotterdam harbor electrification mandates accelerate marine fuel cell procurement for container vessel shore power. Municipal bus operators in Randstad cities deploy proton exchange membrane fleets under national hydrogen corridor funding. ANVISA-aligned industrial safety standards govern cross-border equipment certification.
France
Auvergne-Rhône-Alpes chemical plants favor high-temperature fuel cells for natural gas boiler replacement. ANSM industrial safety standards create dual certification tracks with German KBA processes. Île-de-France telecom towers sustain phosphoric acid backup power installations beyond battery runtime limits.
Poland
Silesian coal-dependent industrial regions receive EU Just Transition Fund support to repurpose gas pipeline corridors for hydrogen distribution. Emerging hydrogen valleys in southern Poland attract greenfield stationary fuel cell deployment. Local steelmakers pilot solid oxide integration amid EU carbon border adjustment threats.
Sweden
Scandinavian automotive suppliers develop bipolar plate manufacturing precision for high-volume fleet contracts. Power generation applications concentrate in industrial clusters seeking combined heat and power configurations. National hydrogen strategy aligns electrolyzer installations with reversible solid oxide system deployment.
Europe Fuel Cell Market Competitive Landscape
Global majors compete with regional champions across technology specialization and industrial partnership depth. The vendor base splits between North American stack manufacturers with transatlantic production bridges, British solid oxide specialists with steel-industry alliances, and Nordic marine-focused producers competing on lifetime metrics. Three archetypes dominate: electrolyzer-fuel cell convergent players, membrane electrode assembly automation leaders, and reversible system integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as gigawatt-scale manufacturing targets approach.
Among North American-anchored producers, Ballard Power Systems exemplifies the transatlantic manufacturing bridge archetype. Ceres Power and Nedstack occupy differentiated positions within the European specialist tier—Ceres representing solid oxide electrolysis convergence with steel-industry partnerships, Nedstack anchoring marine and stationary lifetime optimization. These three illustrate how geographic origin and technology focus stratify competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Heliocentris |
| Ballard Power Systems |
| Ceres Power |
| Nedstack |
| PowerCell Sweden |
| AFC Energy |
| Topsoe |
| ElringKlinger |
| SFC Energy |
| Others |
Supply & Pricing Matrix
Platinum group metal spot indices cascade through European fuel cell stack manufacturing, compressing margins for proton exchange membrane producers while amplifying cost premiums for low-volume buyers dependent on spot catalyst procurement rather than long-term offtake contracts.
Pricing Analysis
Warranty bundling separates premium-tier stack suppliers from unbundled economy offerings, with Dutch port operators and German fleet managers negotiating comprehensive service agreements that embed predictive maintenance software. Three-tier pricing structure across premium, standard, and economy levels reflects platinum loading density and membrane electrode assembly automation grade. Cost compression in economy tiers is intensifying because battery electric alternatives capture urban delivery segments below 200km range. Municipal bus operators exhibit highest price sensitivity, while Ruhr steelmakers prioritize heat integration performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for stack module delivery to Nordic marine operators and Central European industrial clusters. South Africa and Russia concentrate platinum group metal mining, while China dominates bipolar plate graphite processing and South Korea anchors membrane electrode assembly equipment. Supply chain risk centers on single-source vulnerability for catalyst materials under ECHA REACH compliance timelines. Distribution runs through authorized service partners for aftermarket stack refurbishment and warranty claim processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Fuel Cell Market operates as a cost-of-compliance arena where EU Green Deal emission ceilings and F-Gas Regulation cooling agent restrictions erect regulatory moats that favor incumbents with certified product portfolios and established KBA-ANSM dual certification pathways.
For Market Incumbents: Extend membrane electrode assembly automation to compress defect rates below 50 parts per million for high-volume fleet contracts, defending against emerging Chinese stack manufacturers with cost-advantaged alkaline technology. Secure captive platinum group metal supply through recycling partnerships or long-term offtake with South African producers to hedge input cost volatility threatening margin sustainability. For New Entrants and Emerging Players: Capture Poland's Silesian hydrogen valleys where EU Just Transition Fund support creates greenfield deployment zones with repurposed gas pipeline infrastructure and limited incumbent presence. Target reversible solid oxide system integration for Denmark's wind curtailment buffering applications, leveraging electrolyzer-fuel cell convergence as a differentiated entry angle against established proton exchange membrane specialists. For Investors and Strategic Acquirers: The window for entry favors convergent technology players with reversible solid oxide capabilities and steel-industry partnership depth over pure-play transportation stack manufacturers facing battery electric substitution pressure. Watch electrolyzer project finance closure rates as the inflection indicator for bankable hydrogen supply contract availability that underwrites stationary fuel cell deployment scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Recycling | ECHA REACH compliance and South African supply risk drive captive platinum recovery capabilities. |
| Reversible Solid Oxide System Development | Ruhr steelmakers and Danish wind operators demand electrolyzer-fuel cell convergence for flexible hydrogen buffering. |
| Membrane Electrode Assembly Automation | German OEM procurement specifications require sub-50 ppm defect rates for fleet contract eligibility. |
| Marine Shore Power Certification | Rotterdam and Hamburg port authorities mandate berth-side fuel cell systems for container vessel compliance. |
| Polish Hydrogen Valley Partnership | EU Just Transition Fund support repurposes Silesian gas infrastructure for greenfield stationary deployment. |
Research Methodology
Independent corroboration across fuel cell stack manufacturers, electrolyzer project developers, and port authority procurement officers underwrites the qualitative findings, validated against EU Green Deal implementation timelines, ECHA REACH regulatory filings, KBA type-approval databases, and industrial hydrogen offtake contract registries. Bottom-up segmentation triangulation across technology type, end-use application, and geographic deployment pattern anchors volume estimates.
Rate-of-change decomposition separates policy-driven procurement acceleration from technology cost curve improvements across the projection horizon. The analytical framework models Polymer Electrolyte Membrane and Solid Oxide technology segments, transportation and power generation end-use splits, and country-level regulatory implementation clusters. CAGRs derive from electrolyzer capacity buildout trajectories, carbon border adjustment threat intensity for EU ETS-exposed industries, and F-Gas Regulation compliance cost pass-through assumptions.
The model holds under sustained EU Green Deal implementation and stable platinum group metal supply corridors; deviation in South African mining output or accelerated battery electric cost reduction would shift deployment trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Fuel Cell Interconnectors Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market