
 Boiler Turbine and Generator BTG Sales Market | 2026-2036
Boiler Turbine and Generator BTG Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Boiler Turbine and Generator BTG Sales Market Insights
The specialized welder and turbine blade machining workforce is rotating toward combined cycle gas turbine expertise as utilities phase out subcritical coal units. General Electric leverages its HA-class gas turbine technology leadership to capture utility-scale replacement cycles. Siemens Energy anchors European service contracts through its digital turbine monitoring platforms. Bharat Heavy Electricals Limited sustains domestic Indian demand via long-term equipment supply agreements with state generators.
Boiler Turbine and Generator BTG Sales encompass integrated power island equipment where steam or gas turbines convert thermal energy into rotational mechanical power, with generators producing electricity at 50 Hz or 60 Hz frequencies depending on grid standards. Steam turbines dominate mature markets where existing coal and nuclear fleets require lifecycle replacements, while gas turbines capture growth in markets prioritizing fuel flexibility and lower carbon intensity per megawatt-hour. Combined cycle technology configurations command premium positioning due to their 60%-plus thermal efficiency profiles, whereas waste heat recovery systems penetrate industrial cogeneration sites seeking to monetize exhaust streams.
The US EPA enforces emissions limits under the Clean Air Act that compel utilities to retrofit or retire legacy boiler assets, while India's CEA mandates efficiency standards for new thermal installations under national electricity plans. China's MEE enforces ultra-low emission norms that filter into export equipment specifications through GB standards compliance requirements. Stakeholders must weigh retrofit economics against greenfield combined cycle investments as carbon pricing mechanisms expand across jurisdictions.
Market Dynamics
Supercritical and ultra-supercritical steam cycles are compressing the addressable market for subcritical boiler retrofits as utilities face stranded asset risk from tightening thermal efficiency mandates.
Growth Catalysts
- India's National Electricity Plan:State-owned NTPC and regional generation companies are tendering 660 MW and 800 MW supercritical units under CEA-mandated efficiency corridors. Domestic manufacturing obligations under the PLI scheme localize supply chains.
- Combined cycle gas turbine adoption:Southeast Asian utilities in Vietnam, Thailand, and the Philippines are procuring F-class and H-class gas turbines to bridge baseload gaps as coal financing recedes.
- US EPA Clean Air Act enforcement:Mercury and Air Toxics Standards compliance deadlines are forcing coal fleet operators to choose between scrubber retrofits and full BTG replacement cycles.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloys for turbine blades concentrate among a handful of European and Japanese metallurgical suppliers, exposing OEMs to price volatility.
- Carbon pricing asymmetry:Uneven implementation of emissions trading schemes across jurisdictions distorts competitive economics between gas and coal-fired BTG investments.
- Renewable plus storage substitution:Utility-scale solar PV paired with lithium-ion batteries is capturing peak and intermediate load contracts previously served by simple cycle gas turbines.
Strategic Opportunities
- Industrial cogeneration retrofit:Refinery and petrochemical complexes in the US Gulf Coast and Rotterdam-Antwerp corridor are adding waste heat recovery steam generators to existing gas turbine installations.
- Hydrogen-ready gas turbine engineering:OEMs are developing combustor modifications and fuel handling systems capable of 30-50% hydrogen blending by volume.
- Digital twin deployment:Predictive maintenance platforms using physics-based modeling and operational sensor data are opening recurring revenue streams in service contracts.
Industry Challenges
- Specialized welder scarcity:Pipeline construction and shipbuilding are competing for the same ASME-certified pressure vessel welding labor pool, extending fabrication timelines.
- Long-lead forging capacity:Turbine rotor and generator forging presses require 18-24 month scheduling windows at limited global facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boiler Turbine and Generator BTG Sales Market |
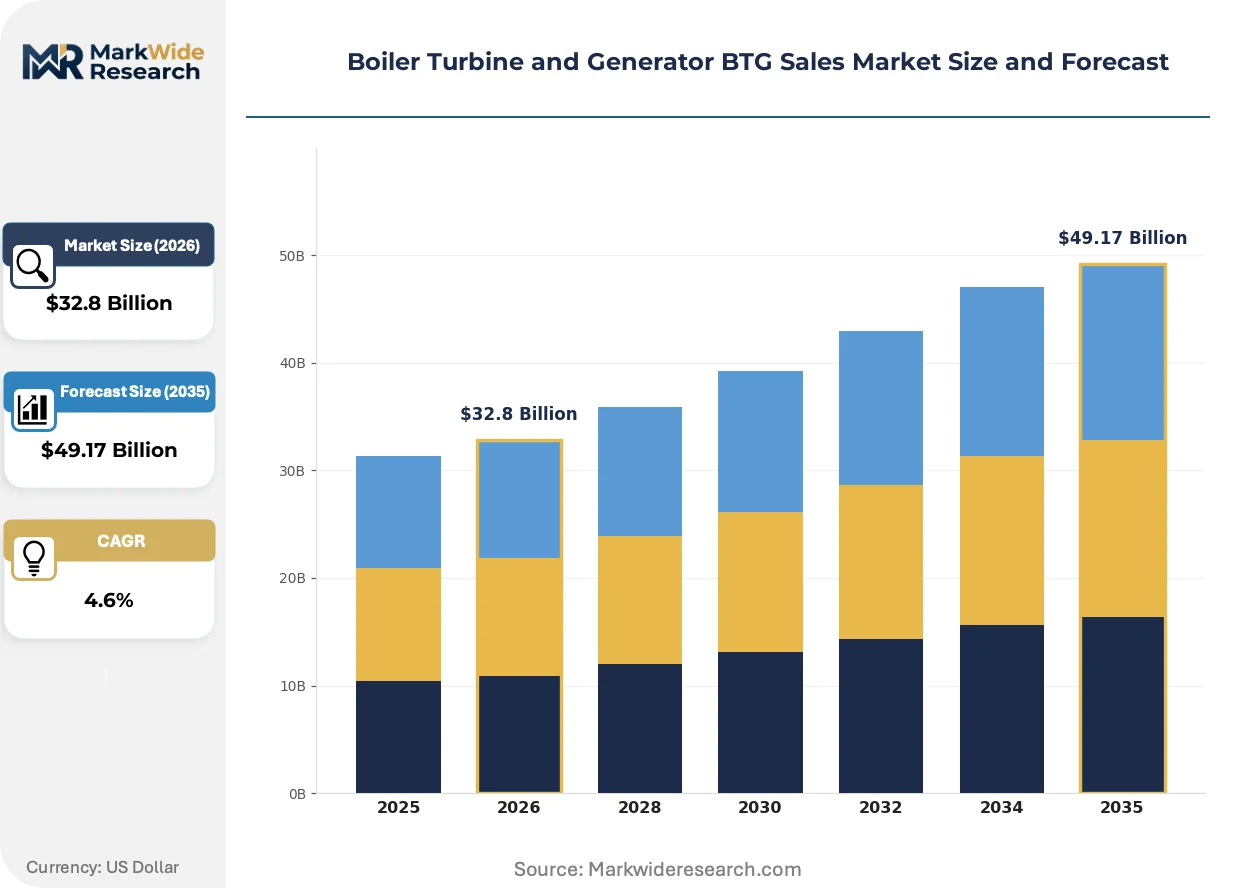
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Turbines, Gas Turbines, Boilers, Generators Application: Power Generation, Industrial Applications, Marine Applications, HVAC Systems End User: Utility Providers, Industrial Manufacturers, Marine Operators, Power Plants Technology: Combined Cycle, Cogeneration, Solar Thermal, Waste Heat Recovery |
| Companies Covered | General Electric, Siemens Energy, Mitsubishi Heavy Industries, Bharat Heavy Electricals Limited, Dongfang Electric Corporation, Toshiba Energy Systems, Doosan Heavy Industries & Construction, Shanghai Electric, Ansaldo Energia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boiler Turbine and Generator BTG Sales Market Trends and Innovations
Additive manufacturing is penetrating turbine component repair workflows, reducing downtime for blade tip restoration and combustion liner refurbishment. Digital instrumentation and advanced materials are converging to extend maintenance intervals.
Directed energy deposition and powder bed fusion techniques are displacing conventional weld repair and replacement casting for hot gas path components. MRO providers in North America and Western Europe are qualifying laser-clad stator vane segments for 50,000+ hour service lives. The economics of near-net-shape repair are compressing spare parts demand for legacy frame turbines.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in generator cooling systems, compelling redesign of hydrogen-cooled and air-cooled alternator architectures. OEMs serving European utilities must now certify alternative dielectric fluids and modified stator cooling circuits. This regulatory pressure is propagating into export specifications for Middle Eastern and African projects financed by European development institutions.
Power purchase agreement structures are compressing equipment procurement cycles as independent power producers front-load engineering to meet commercial operation date guarantees. Developers in Vietnam and Bangladesh are unbundling BTG packages to accelerate financial close, sourcing turbines from Western OEMs while procuring boilers and generators from Indian and Chinese suppliers. This disaggregated sourcing pattern is fragmenting traditional power island integration responsibilities.
Boiler Turbine and Generator BTG Sales Market Segmentation
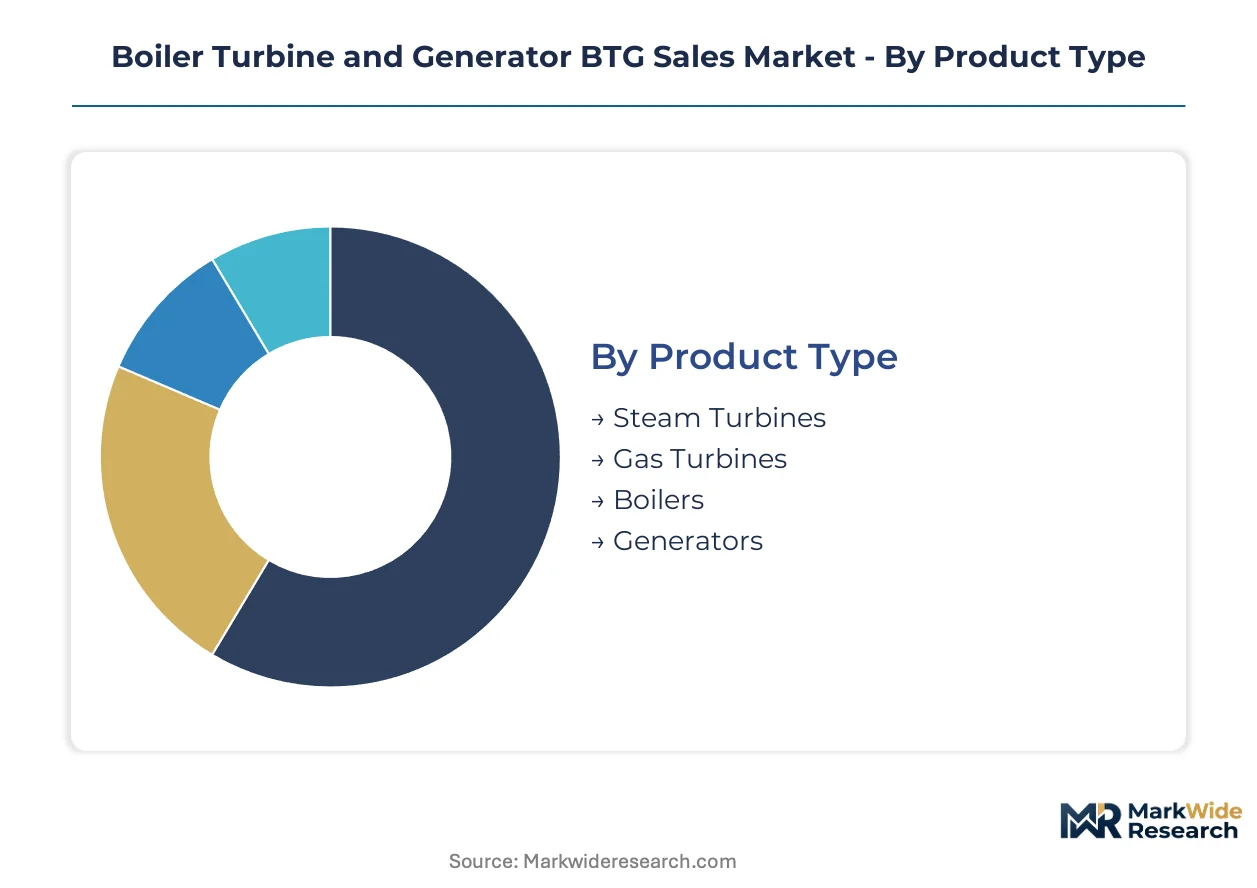
BTG equipment procurement channels diverge sharply by segment: utilities tender integrated power islands through EPC consortia, while industrial buyers source modular packages via direct OEM relationships. Channel economics dictate margin structures, with combined cycle gas turbines commanding premium positioning through turnkey contracting.
Product Type:
Steam turbines and gas turbines flow through utility-scale EPC channels requiring 18-24 month lead times, while boilers and generators see parallel sourcing through both EPC integrators and direct industrial procurement.
- Steam Turbines:These units convert thermal energy from superheated steam into rotational mechanical power, with blade alloys rated for 540°C+ inlet temperatures. Demand concentrates in India and Southeast Asia where state-owned NTPC and regional generation companies tender 660-800 MW supercritical replacements under CEA-mandated efficiency corridors.
- Gas Turbines:Aeroderivative and heavy-frame configurations burn natural gas or liquid fuels to drive compressors and power generators. Procurement clusters in Vietnam, Thailand, and the Philippines as utilities bridge baseload gaps with F-class and H-class units while coal financing recedes from development institutions.
- Boilers:Water-tube and fire-tube designs generate steam through coal, gas, or biomass combustion for power and process applications.
- Generators:Synchronous machines produce grid-frequency electricity at 50 Hz or 60 Hz, with hydrogen-cooled and air-cooled architectures replacing legacy HFC systems under EU F-Gas Regulation phase-down mandates.
By volume, Boilers lead due to retrofit cycles across existing coal fleets. By growth pace, Gas Turbines is ahead on combined cycle adoption in gas-transitioning markets.
Application:
Cost tier segmentation separates mission-critical baseload power from intermittent industrial process heat, with marine and HVAC applications occupying specialized premium and economy positioning respectively.
- Power Generation:Utility-scale installations deliver grid-stabilizing baseload and intermediate load capacity through centralized thermal plants. Investment concentrates in India's National Electricity Plan execution and US EPA-driven supercritical retrofits, though renewable-plus-storage substitution is compressing simple cycle gas turbine economics for peak contracts.
- Industrial Applications:Cogeneration and process steam systems serve refineries, petrochemical complexes, and manufacturing facilities seeking thermal efficiency. The US Gulf Coast and Rotterdam-Antwerp corridor are adding waste heat recovery steam generators to monetize exhaust streams from existing gas turbine installations.
- Marine Applications:Propulsion and auxiliary power systems for commercial shipping and naval vessels, subject to IMO emissions regulations.
- HVAC Systems:Absorption chilling and district heating applications utilizing waste heat or dedicated boiler capacity.
Power Generation dominates absolute spend. Industrial Applications is climbing fastest on refinery cogeneration retrofit demand.
End User:
Customer type determines contracting complexity, with utility providers demanding integrated performance guarantees while industrial manufacturers prioritize modular upgrade paths.
- Utility Providers:Grid-connected generation companies procure through competitive tenders with long-term service agreements. India's state-owned generators anchor volume through PLI-linked domestic manufacturing obligations, while Southeast Asian independent power producers unbundle BTG packages to accelerate financial close.
- Industrial Manufacturers:Process industries self-generate power and steam to hedge grid volatility and capture waste heat value. Refinery and chemical sector procurement is accelerating for hydrogen-ready turbine retrofits capable of 30-50% hydrogen fuel blending.
- Marine Operators:Shipping lines and naval fleets source propulsion systems through specialized marine engineering contractors.
- Power Plants:Captive industrial facilities and independent generators outside regulated utility structures.
Utility Providers command the largest contract values. Industrial Manufacturers is gaining share fastest on energy security priorities.
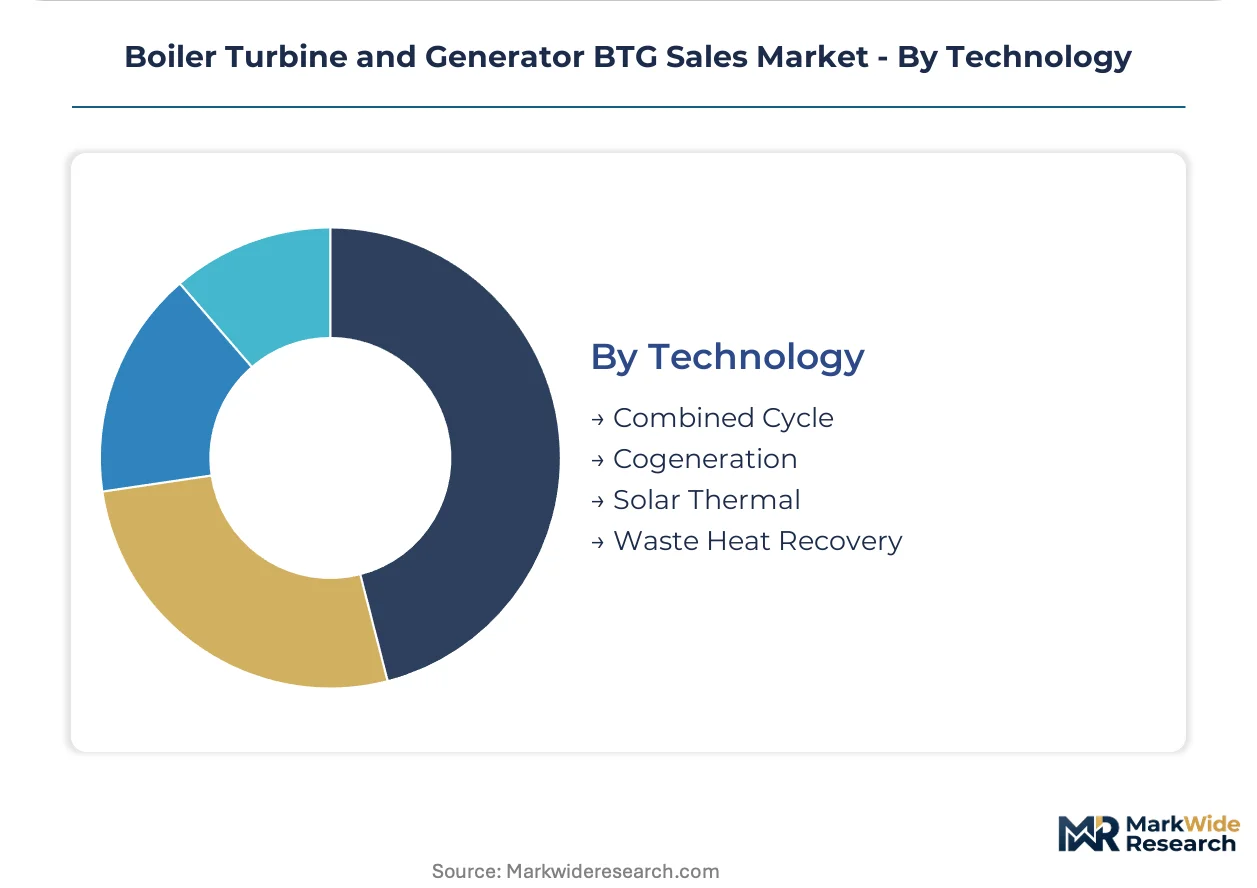
Technology:
Maturity gradients separate established combined cycle deployments from emerging configurations, with waste heat recovery penetrating industrial sites as solar thermal stalls on cost competitiveness.
- Combined Cycle:Gas turbines paired with heat recovery steam generators and steam turbines achieve 60%-plus thermal efficiency. Southeast Asian utilities in Vietnam and Bangladesh are the primary demand center as developers front-load engineering to meet commercial operation date guarantees.
- Cogeneration:Simultaneous electricity and useful heat production from single fuel sources maximizes energy utilization. US Gulf Coast refineries and European petrochemical clusters are retrofitting existing gas turbines with waste heat recovery steam generators to improve carbon intensity metrics.
- Solar Thermal:Concentrating solar power systems using parabolic troughs or power towers with thermal storage.
- Waste Heat Recovery:Organic Rankine cycle and steam-based systems convert exhaust heat from industrial processes or prime movers into electricity.
Combined Cycle leads by installed capacity additions. Waste Heat Recovery is expanding most quickly on industrial decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA-mandated efficiency corridors in India anchor supercritical boiler deployments, while EPA enforcement in the United States accelerates coal fleet replacement decisions. Southeast Asian utilities bridge baseload gaps with gas turbine procurement as coal financing recedes from development institutions.
India
NTPC and state generation companies tender 660 MW and 800 MW supercritical units under the National Electricity Plan. PLI scheme domestic manufacturing obligations localize supply chains for pressure parts and turbine rotors. Fabrication clusters in Gujarat and Tamil Nadu execute long-term equipment agreements with state-owned utilities.
United States
Mercury and Air Toxics Standards compliance deadlines force coal operators toward scrubber retrofits or full BTG replacement cycles. The EPA enforces emissions limits that compress subcritical boiler economics. Gulf Coast refineries add waste heat recovery steam generators to monetize exhaust streams from existing gas turbine installations.
Vietnam
Independent power producers unbundle BTG packages to accelerate financial close on combined cycle projects. F-class and H-class gas turbines capture procurement as coal financing recedes from European development institutions. Developers front-load engineering in Ho Chi Minh City and Hanoi to meet commercial operation date guarantees.
China
MEE ultra-low emission norms filter into export equipment specifications through GB standards compliance requirements. State-owned utilities retrofit existing coal fleets with supercritical upgrades to avoid stranded asset risk. Manufacturing concentration in Shanghai and Sichuan supplies both domestic replacement cycles and Belt and Road project exports.
Germany
EU F-Gas Regulation phase-down mandates redesign hydrogen-cooled and air-cooled alternator architectures for generator cooling systems. Siemens Energy anchors European service contracts through digital turbine monitoring platforms. Industrial cogeneration retrofits concentrate in the Rotterdam-Antwerp corridor access points.
Boiler Turbine and Generator BTG Sales Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated heavy-frame turbine manufacturing contrasting against fragmented boiler pressure part fabrication. Scale-driven OEMs anchor utility-scale power island integration, while regional fabricators capture retrofit and aftermarket service volumes. Strategic archetypes include full-power-island integrators, component-specialist suppliers, and digital service platform operators. Competitive moves concentrate on hydrogen-ready combustor engineering and predictive maintenance platform deployment.
Within the integrated OEM tier, General Electric and Siemens Energy exemplify scale-driven power island integration, while Bharat Heavy Electricals Limited occupies a position anchoring domestic Indian demand through state utility relationships. These three represent contrasting geographic and contractual archetypes: US-based global project execution, European digital-anchored service models, and India-centric domestic manufacturing obligations under PLI-linked procurement structures.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Bharat Heavy Electricals Limited |
| Dongfang Electric Corporation |
| Toshiba Energy Systems |
| Doosan Heavy Industries & Construction |
| Shanghai Electric |
| Ansaldo Energia |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month lead times for turbine rotor forgings concentrate pricing power among a handful of global heavy forging facilities, while Indian PLI-linked domestic manufacturing obligations compress landed costs for state utility procurement. This supply-side concentration lets integrated OEMs command turnkey premiums on combined cycle power islands, even as unbundled sourcing patterns among Southeast Asian IPPs fragment traditional margin structures.
Pricing Analysis
Price spreads between European and Asian BTG equipment deliveries widen on specialized alloy premiums and ASME certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates hydrogen-ready F-class turbines from refurbished frame units and basic subcritical boiler packages. Cost compression in the standard tier is intensifying because Indian and Chinese OEMs are absorbing domestic content requirements through localized fabrication clusters. Industrial cogeneration buyers exhibit the highest price sensitivity due to project IRR thresholds, while utility-scale IPPs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp corridors and container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for nickel-based superalloy consignments. Manufacturing gravity centers on Japan, Germany, and India for precision turbine blades, pressure vessel forgings, and PLI-compliant domestic assemblies respectively. Raw material flows draw from Chilean copper concentrates, Indonesian nickel laterites, and Australian metallurgical coal. Single-source vulnerability concentrates in the 18,000-ton press capacity segment for generator rotor forgings. Distribution runs through EPC consortia for utility-scale projects and direct OEM relationships for industrial retrofit accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BTG equipment demand sits in early-cycle expansion as hydrogen-ready gas turbine engineering opens replacement windows ahead of full decarbonization timelines. India's National Electricity Plan execution and Southeast Asian gas transition procurement provide dual adoption tailwinds through the analysis window.
For Market Incumbents: Secure long-lead forging capacity reservations at Japanese and German heavy press facilities to defend against supply-side bottlenecks. Anchor digital twin service contracts through predictive maintenance platform deployment, as aftermarket recurring revenue offsets margin compression on new equipment sales from Chinese and Indian OEM competition.
For New Entrants and Emerging Players: Differentiate on hydrogen combustion retrofit capability for existing F-class and H-class installed bases in the US Gulf Coast and Rotterdam-Antwerp corridor. Target waste heat recovery steam generator packages for refinery cogeneration expansions, where project scale permits modular entry without full power island integration capabilities.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle infrastructure play because supercritical coal fleet retirements and gas turbine efficiency upgrades create sustained demand regardless of net-zero timelines. Acquisition candidates include digital turbine monitoring platform operators and ASME-certified pressure vessel fabricators with hydrogen-ready welding qualifications. The signal to watch is FERC interconnection queue data for combined cycle project approvals.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Combustor Engineering | GE and Siemens Energy are qualifying 30-50% hydrogen blends to future-proof H-class turbine sales. |
| Long-Term Service Agreement Expansion | OEMs are anchoring recurring revenue through predictive maintenance platforms using physics-based digital twins. |
| Domestic Manufacturing Capacity Buildout | Bharat Heavy Electricals Limited is localizing supply chains under PLI-linked state utility procurement mandates. |
| Waste Heat Recovery Steam Generator Retrofit | US Gulf Coast refineries are adding HRSG packages to monetize exhaust streams from existing gas turbines. |
| Supercritical Boiler Efficiency Upgrade | Chinese utilities are retrofitting subcritical coal fleets to avoid stranded asset risk from MEE ultra-low emission norms. |
Research Methodology
Cross-validation between EPC contractor project databases and FERC interconnection filings anchors the qualitative findings on utility-scale procurement patterns. Primary interviews with utility planning officers, IPP project developers, EPC consortium procurement leads, and aftermarket service directors combined with secondary validation from EIA capacity data, IEA power sector reports, and CEA National Electricity Plan documents. Bottom-up equipment shipment tracking and top-down grid investment forecasts were reconciled across the analysis window.
Sensitivity analysis on fuel price trajectories and carbon pricing implementation schedules shapes the forecast framework. Segmentation dimensions modeled include fuel source, generation capacity tier, project ownership structure, and regional regulatory framework. CAGRs were derived from installed base replacement cycles and new capacity additions across the projection horizon. Industry-specific inputs incorporate EPA MATS compliance deadlines, Indian PLI scheme localization requirements, and EU F-Gas Regulation phase-down timelines.
Material uncertainties — abrupt renewable-plus-storage cost reductions, hydrogen infrastructure buildout delays, or nickel superalloy supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions on policy continuity and technology cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Europe Gas Turbine Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
North America Gas Generator Market
Generators
India Diesel Generator Market
Generators
Telecom Generator Market
Generators
Heat Recovery System Generator Market
Generators
Emergency Power Generators Sales Market
Generators
US Generator Sales Market
Generators
Construction Prime Power Generators Market
Generators
Reciprocating Power Generating Engine Market
Generators
Europe Diesel Generator Market
Generators
Commercial Standby Generator Sets Market
Generators
South America Portable Generator Market
Generators
Europe Generator Sets Market
Generators
Kuwait Diesel Gensets Market
Generators
Europe Turbo Generator Market