
 Germany Nuclear Imaging Market | 2026-2036
Germany Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Nuclear Imaging Market Foresight
Hospital procurement consortia across Germany's federal states is reconfiguring capital equipment purchasing for molecular imaging suites. Siemens Healthineers leverages its Erlangen manufacturing base to dominate domestic PET-CT system supply. GE Healthcare competes through specialized radiopharmaceutical distribution networks serving Rhineland university hospitals. Koninklijke Philips anchors its position in hybrid imaging through software-integrated SPECT platforms tailored to German clinical workflows.
Nuclear imaging encompasses diagnostic techniques utilizing radiolabeled tracers to visualize physiological function at the molecular level, with systems detecting gamma ray emissions through sodium iodide crystal arrays or lutetium-based scintillators to reconstruct tomographic images. PET scanners lead capital expenditure among product types due to superior spatial resolution in oncologic staging, while hybrid imaging devices represent the fastest-growing segment as hospitals consolidate anatomical and functional data acquisition. Oncology diagnostics commands the largest application share driven by prostate and neuroendocrine tumor imaging protocols, whereas neurology studies gain traction amid expanding amyloid plaque quantification for Alzheimer's assessment.
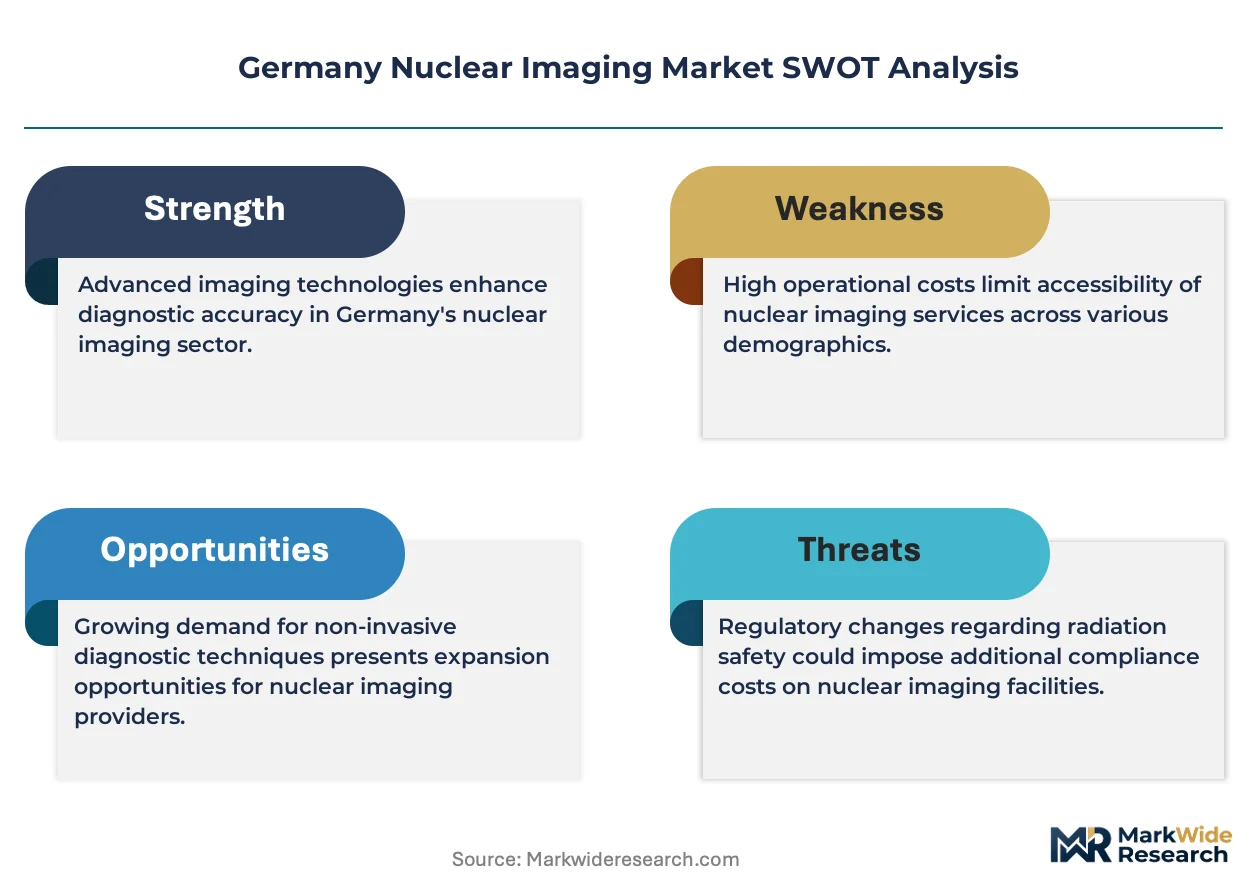
BfArM oversees medical device registration and vigilance reporting for nuclear imaging equipment, while the Federal Office for Radiation Protection (BfS) governs isotope handling licenses and waste disposal protocols that directly shape site installation requirements. Germany's adoption of EU Medical Devices Regulation (MDR) intensifies conformity assessment burdens for gamma camera manufacturers seeking market access. Stakeholders must monitor BfArM guidance on software-as-a-medical-device classification for AI-enhanced image reconstruction algorithms.
Market Dynamics
BfArM's tightened MDR enforcement is compressing market access timelines for gamma camera manufacturers while Bavaria's isotope production cluster concentrates tracer supply leverage among Munich-based university hospitals.
Growth Catalysts
- EU Medical Devices Regulation:MDR implementation under BfArM oversight accelerates quality differentiation among compliant radiopharmaceutical distributors.
- Oncology tracer protocols:Prostate and neuroendocrine tumor imaging departments at German university hospitals are expanding PET-CT utilization for precision staging.
- Amyloid plaque quantification:Neurology clinics across Baden-Württemberg are adopting standardized protocols for Alzheimer's diagnostic assessment.
Market Restraints
- Molybdenum-99 supply concentration:Reactor dependency on Belgium's BR-2 and the Netherlands' Petten facilities creates isotope availability vulnerability for German generators.
- BfS disposal protocols:Federal Office for Radiation Protection waste handling requirements impose site-specific installation constraints that extend project timelines.
- Short half-life logistics:Fluorine-18 and technetium-99m decay characteristics necessitate distributed production networks, fragmenting economies of scale.
Strategic Opportunities
- Theranostics convergence:Lutetium-177 radioligand therapy paired with diagnostic gallium-68 imaging creates unified service lines at Rhineland nuclear medicine centers.
- AI reconstruction algorithms:BfArM software-as-a-medical-device classification pathway enables regulatory clarity for machine learning-enhanced image processing.
- North Rhine-Westphalia procurement consortia:Hospital alliance purchasing models favor vendors offering integrated tracer-to-system service contracts.
Industry Challenges
- Radiopharmacist workforce scarcity:Specialized compounding expertise for GMP-compliant tracer production remains concentrated among aging professionals in Saxony and Thuringia.
- Hybrid imaging integration complexity:SPECT-CT and PET-MR system upgrades require PACS compatibility with legacy DICOM infrastructure at established German hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Nuclear Imaging Market |
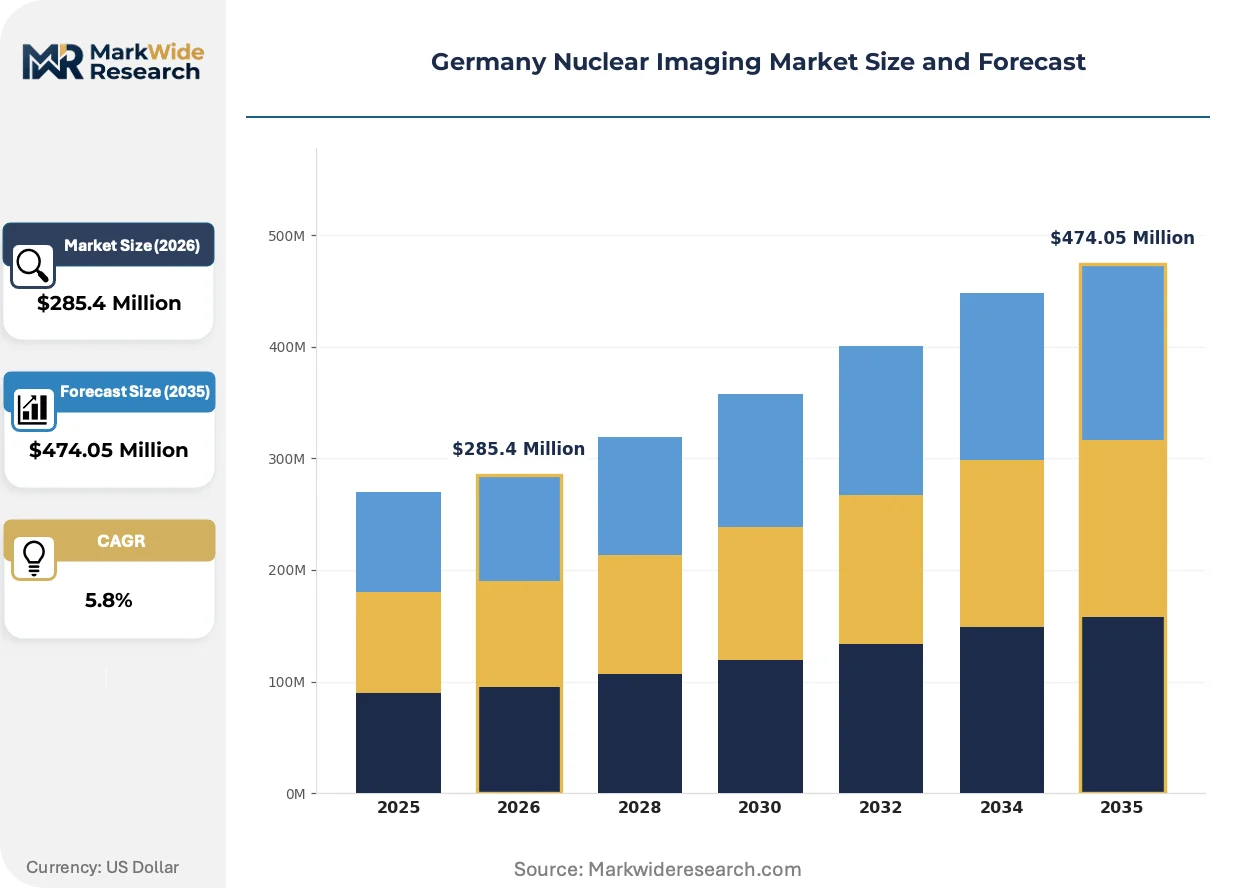
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SPECT Systems, PET Scanners, Gamma Cameras, Hybrid Imaging Devices Application: Oncology Diagnostics, Cardiology Imaging, Neurology Studies, Bone Scintigraphy, Thyroid Function Tests End User: Hospitals, Diagnostic Centers, Research Institutes, Specialty Clinics Deployment Model: Stationary Systems, Mobile Units, In-Clinic Installations, Telemedicine Integration |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Curium Pharma, Eckert & Ziegler AG, Bracco Imaging, Canon, ITM Isotope Technologies Munich SE, SurgicEye GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Nuclear Imaging Market Shifts & Advancements
Digital PET detector technology is compressing scan durations while BfArM's evolving software classification framework redefines competitive boundaries for AI-enhanced reconstruction vendors.
Silicon photomultiplier arrays are replacing conventional photomultiplier tubes in next-generation PET scanners. University hospital radiology departments in Lower Saxony and Hesse are prioritizing SiPM-based systems for their improved timing resolution and magnetic field compatibility. This solid-state detection architecture is rendering obsolete analog PMT-based designs that dominated German molecular imaging suites for three decades.
BfArM's guidance on software-as-a-medical-device classification establishes conformity assessment pathways for AI-enhanced image reconstruction algorithms. The regulation requires clinical validation documentation that extends development timelines for algorithm vendors. PET-CT manufacturers serving Bavaria's clinical research corridor are restructuring quality management systems to accommodate iterative software updates under MDR Article 120 transitional provisions.
Consortium-based capital equipment purchasing is consolidating decision authority among multi-hospital alliances. Rhineland procurement networks are unbundling after-sales service contracts from system acquisitions, favoring independent service organizations for maintenance coverage. This purchasing pattern shift is most pronounced among mid-sized community hospitals in North Rhine-Westphalia seeking operational flexibility amid constrained capital budgets.
Germany Nuclear Imaging Market Segmentation
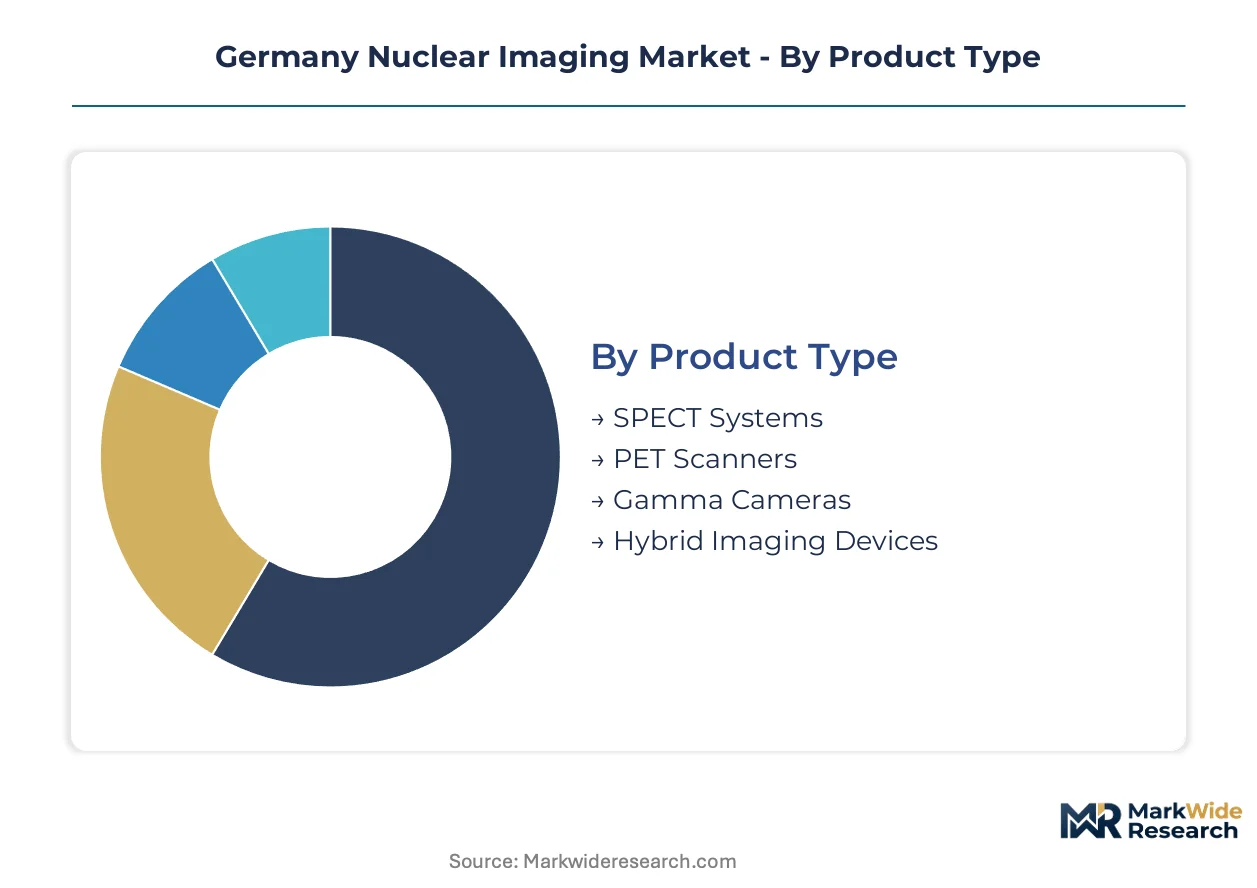
Equipment replacement cycles and tracer protocol expansion reshape procurement priorities across German nuclear imaging. Segment boundaries blur as hybrid architectures displace standalone systems and theranostics convergence redefines clinical workflows.
Product Type:
Capital turnover varies dramatically — PET scanners cycle every 7-9 years while gamma cameras operate 12-15 years, compressing manufacturer revenue predictability.
- PET Scanners:Lutetium-based scintillator arrays achieve sub-5mm spatial resolution for oncologic staging. Bavaria's university hospitals prioritize digital SiPM detector upgrades to accelerate scan throughput and reduce radiotracer dosing.
- Hybrid Imaging Devices:PET-CT and SPECT-CT systems consolidate anatomical CT with functional nuclear data acquisition. Rhineland procurement consortia favor these platforms for their PACS integration efficiency and reduced patient repositioning.
- SPECT Systems:Sodium iodide crystal arrays remain the workhorse for cardiac perfusion and bone imaging across community hospitals in Saxony.
- Gamma Cameras:Analog photomultiplier tube designs face accelerated obsolescence as BfArM MDR compliance costs mount for legacy manufacturers.
SPECT systems anchor the volume base while hybrid imaging devices gain share at the steepest rate.
Application:
Reimbursement intensity separates high-value oncology protocols from commoditized thyroid function testing.
- Oncology Diagnostics:Prostate-specific membrane antigen imaging with gallium-68 tracers dominates PET-CT scheduling at Munich's university hospitals. Neuroendocrine tumor protocols using somatostatin receptor ligands extend service line profitability.
- Neurology Studies:Amyloid plaque quantification for Alzheimer's assessment spreads across Baden-Württemberg memory clinics. Cerebral blood flow SPECT maintains utility in epilepsy surgical planning.
- Cardiology Imaging:Myocardial perfusion scintigraphy faces substitution pressure from coronary CT angiography in North Rhine-Westphalia cardiac centers.
- Bone Scintigraphy:Technetium-99m methylene diphosphonate scans retain cost advantage for metastatic disease staging in Thuringia regional hospitals.
- Thyroid Function Tests:Iodine-131 uptake measurements concentrate in endocrinology specialty practices with in-house gamma probe capability.
Oncology diagnostics commands the revenue concentration while neurology studies expand most quickly amid dementia care pathway restructuring.
End User:
Procurement authority consolidates among multi-hospital alliances while independent diagnostic centers fragment purchasing power.
- Hospitals:University medical centers in Munich, Heidelberg, and Cologne anchor tracer production and protocol development. Their capital budgets absorb hybrid imaging premiums through amortized patient volume.
- Diagnostic Centers:Outpatient nuclear medicine facilities in Bavaria and Hesse compete on appointment accessibility and specialized cardiac stress testing.
- Research Institutes:Helmholtz Center Munich and German Cancer Research Center drive radiopharmaceutical innovation through cyclotron infrastructure.
- Specialty Clinics:Urology and endocrinology focused practices in Lower Saxony deploy compact gamma cameras for same-day diagnostic loops.
Hospitals dominate installed base value while diagnostic centers capture volume growth in outpatient reimbursement shifts.
Deployment Model:
Site constraints and isotope logistics determine whether fixed installations or mobile configurations prevail.
- Stationary Systems:Lead-shielded suites with integrated radiopharmaceutical hot labs define permanent installations at major academic centers.
- Mobile Units:Trailer-mounted SPECT systems serve rural populations in Mecklenburg-Vorpommern where permanent specialist staffing proves uneconomical.
- In-Clinic Installations:Compact PET-CT footprints enable cardiology group practices in Baden-Württemberg to retain imaging revenue internally.
- Telemedicine Integration:Remote image interpretation protocols link community hospitals in Saxony-Anhalt with university radiology departments for complex case consultation.
Stationary systems retain the capital intensity concentration while mobile units address geographic access gaps with fastest deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's university hospitals extract pricing premiums from tracer production concentration, while North Rhine-Westphalia's procurement consortia compress equipment margins through collective bargaining power.
Bavaria
Munich's isotope production cluster anchors gallium-68 and fluorine-18 supply chains for prostate cancer imaging protocols. BfArM's MDR enforcement tightens quality documentation for radiopharmaceutical distributors serving the clinical research corridor. Erlangen's manufacturing base concentrates PET-CT system assembly under Siemens Healthineers' vertical integration.
North Rhine-Westphalia
Hospital procurement alliances in Cologne and Düsseldorf consolidate capital equipment purchasing for molecular imaging suites. BfS waste disposal protocols impose site-specific installation constraints that extend project timelines across the Rhineland. University hospitals in Aachen and Bonn drive theranostics convergence through lutetium-177 radioligand therapy paired with diagnostic imaging.
Baden-Württemberg
Memory clinics in Heidelberg and Stuttgart expand amyloid plaque quantification protocols for Alzheimer's assessment workflows. The state's medical device regulator aligns with EU MDR transitional provisions for AI-enhanced image reconstruction software classification. Mannheim's university medical center anchors neurology studies through standardized cerebral blood flow SPECT applications.
Lower Saxony
Community hospitals in Hanover prioritize silicon photomultiplier detector upgrades for improved timing resolution in cardiac perfusion imaging. Regional procurement networks favor independent service organizations for gamma camera maintenance coverage. Wolfsburg's diagnostic centers compete on appointment accessibility for specialized stress testing protocols.
Hesse
Outpatient nuclear medicine facilities in Frankfurt concentrate on thyroid function testing with in-house gamma probe capability. The state's integration with BfArM's software-as-a-medical-device pathway enables regulatory clarity for machine learning vendors. Darmstadt's research institutes support radiopharmaceutical innovation through cyclotron infrastructure partnerships.
Germany Nuclear Imaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in detector arrays and scintillator materials. The vendor base concentrates among three multinational conglomerates with domestic manufacturing footprints and a fragmented tier of radiopharmaceutical compounders. Strategic archetypes separate full-stack imaging system providers, isotope production specialists, and AI-enhanced reconstruction software vendors. Competitive moves center on unbundling after-sales service contracts from hardware acquisitions and restructuring quality management systems for MDR software classification compliance.
Within the integrated system tier, Siemens Healthineers anchors domestic PET-CT supply through its Erlangen manufacturing base. GE Healthcare occupies a position in specialized radiopharmaceutical distribution networks. Koninklijke Philips exemplifies the hybrid imaging specialization archetype through software-integrated SPECT platforms tailored to German clinical workflows.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Curium Pharma |
| Eckert & Ziegler AG |
| Bracco Imaging |
| Canon |
| ITM Isotope Technologies Munich SE |
| SurgicEye GmbH |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's escalating transport costs compress margins for radiopharmaceutical distributors while amplifying price premiums for Bavaria's Munich-based isotope cluster. This logistics pressure concentrates negotiating leverage among university hospitals with captive cyclotron capacity, forcing community hospitals into standardized pricing tiers with limited customization scope.
Pricing Analysis
Configured-to-order pricing for hybrid PET-CT systems commands substantial premiums over standard gamma camera configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by detector technology sophistication and after-sales service bundling. Cost compression in the economy tier intensifies because BfArM MDR compliance burdens disproportionately burden legacy manufacturers. Community hospitals in Saxony and Thuringia exhibit highest price sensitivity, whereas Munich's university medical centers prioritize performance specifications over acquisition cost.
Supply Chain Analysis
EU dual-use export controls on lutetium-based scintillator arrays and silicon photomultiplier technology constrain component flows from Netherlands and Belgian suppliers. Isotope production draws from Belgium's BR-2 reactor, the Netherlands' Petten facility, and domestic Bavarian cyclotron infrastructure. Single-source vulnerability pervades molybdenum-99 generator supply, with no German domestic production alternative. Distribution runs through specialized radiopharmaceutical logistics networks with temperature-controlled last-mile delivery to hospital hot labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany nuclear imaging market is recovering from cyclical trough conditions driven by deferred hospital capital expenditure during EU MDR transition periods. Equipment replacement cycles are reaccelerating as procurement consortia finalize compliance-aligned vendor qualifications.
For Market Incumbents: Harden service contract profitability by unbundling maintenance from hardware sales and establishing independent service organization partnerships. Siemens Healthineers and GE Healthcare must deepen cyclotron infrastructure partnerships to defend against tracer supply disruption threats. Certification investment in BfArM software-as-a-medical-device pathways provides defensive moats against AI reconstruction algorithm entrants.
For New Entrants and Emerging Players: Establish a beachhead in mobile SPECT services for rural Mecklenburg-Vorpommern and Saxony-Anhalt markets underserved by permanent installations. The diagnostic center segment offers lowest competitive density, particularly for specialized cardiac stress testing protocols. A go-to-market angle through telemedicine-integrated remote interpretation partnerships with university radiology departments bypasses capital-intensive system acquisition barriers.
For Investors and Strategic Acquirers: Radiopharmaceutical compounding specialists with GMP-compliant tracer production capabilities represent the most attractive acquisition archetype. Long-term viability hinges on theranostics convergence momentum and lutetium-177 therapy adoption curves. The signal to watch is BfArM guidance on AI-enhanced reconstruction algorithm reimbursement eligibility as inflection indicator for software-centric valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Software Classification Pathway | BfArM clarity on AI reconstruction algorithms enables regulatory-compliant product roadmaps for algorithm vendors. |
| Theranostics Service Line Integration | Lutetium-177 therapy paired with gallium-68 imaging consolidates revenue streams at Rhineland nuclear medicine centers. |
| SiPM Detector Technology Transition | Solid-state photomultiplier arrays displace analog PMT designs, rendering three decades of installed base obsolete. |
| Procurement Consortium Participation | North Rhine-Westphalia hospital alliances favor vendors offering bundled tracer-to-system service contracts. |
| Cyclotron Infrastructure Partnership | Munich's isotope production cluster anchors gallium-68 supply security for prostate cancer imaging protocols. |
Research Methodology
Desk research of BfArM regulatory guidance documents, EU Medical Devices Regulation implementation notices, and hospital procurement database records preceded structured interviews with nuclear medicine department heads, biomedical equipment procurement managers, radiopharmaceutical supply chain directors, and GPO contracts specialists. Secondary validation incorporated BfS radiation protection protocols, university hospital capital expenditure disclosures, and cyclotron infrastructure development filings. Bottom-up equipment installation tracking and top-down healthcare expenditure modeling were triangulated against tracer production volume estimates.
Assumptions held fixed across the analysis window include BfArM MDR enforcement intensity, EU isotope reactor operational status, and German hospital procurement consortium formation patterns. Variables modeled across segmentation dimensions encompassed product type replacement cycles, application-specific reimbursement rates, end-user capital budget allocation priorities, and deployment model site constraints. CAGRs were derived from installed base evolution projections and average selling price trajectory analysis. Forecast inputs incorporated silicon photomultiplier adoption curves and theranostics protocol expansion rates.
Stress conditions across molybdenum-99 supply disruption scenarios, BfS waste disposal protocol amendments, and AI software reimbursement policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and isotope logistics continuity. Material shifts in EU radiopharmaceutical export controls or BfArM software classification precedent would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Specialty PACS Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
South America Nuclear Imaging Market
Medical Imaging
Global Medical Cameras Market