
 Perfusion Radiology Market | 2026-2036
Perfusion Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Perfusion Radiology Market Analysis
Aftermarket service revenue is tilting toward software maintenance and AI algorithm updates as hardware replacement cycles lengthen. GE HealthCare leverages its installed base of CT scanners to bundle perfusion analytics subscriptions. Siemens Healthineers anchors its position through end-to-end integration from acquisition to quantitative reporting.
Perfusion radiology encompasses functional imaging techniques that measure blood flow, blood volume, and permeability in tissue using tracer kinetics, with CT perfusion typically employing iodinated contrast at 50-100 mL injection volumes and MR perfusion utilizing gadolinium-based agents or endogenous water proton labeling. CT perfusion dominates acute stroke triage due to sub-minute acquisition protocols, while arterial spin labeling gains share in pediatric and renal-impaired populations by eliminating exogenous contrast dependence. Dynamic susceptibility contrast retains primacy in neuro-oncology for its established correlation with tumor grade and treatment response.
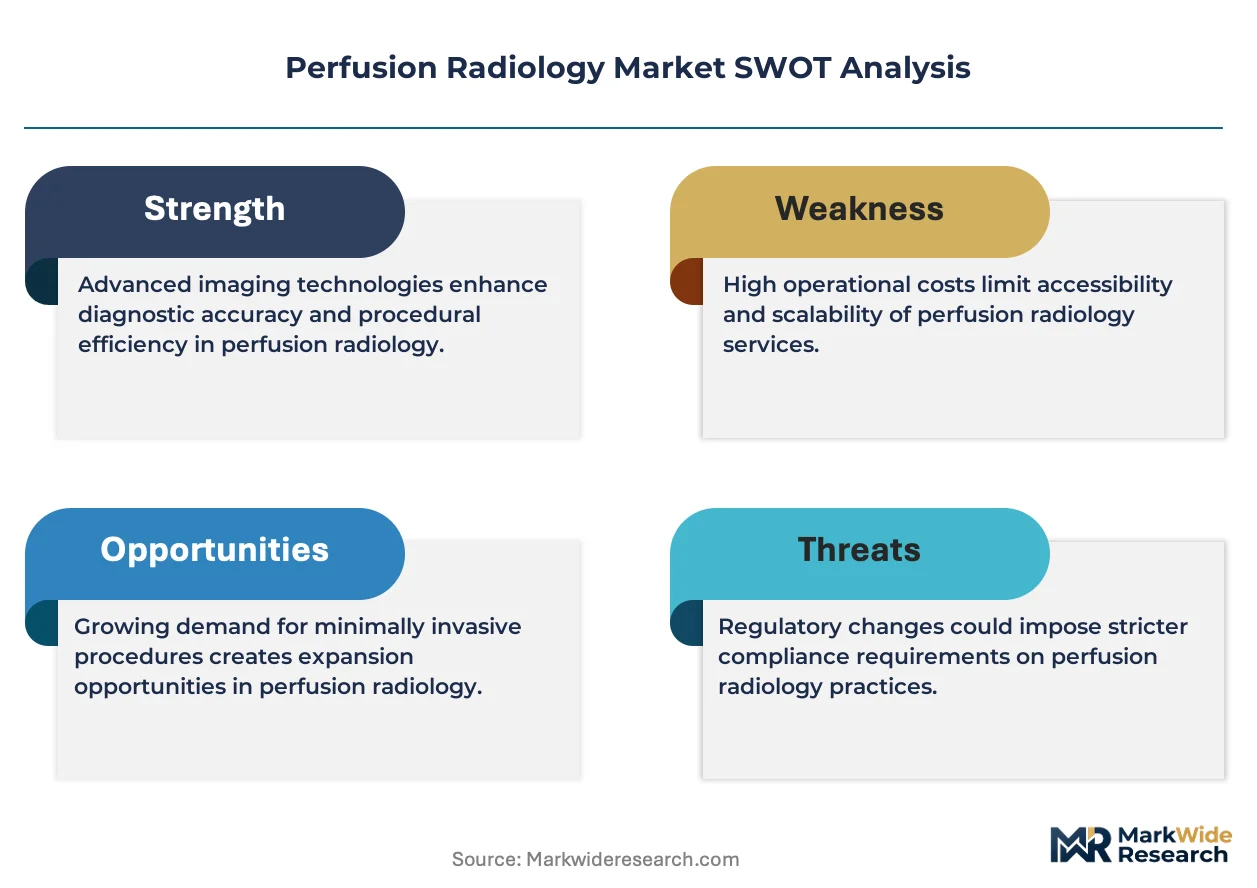
FDA 510(k) clearance requirements shape algorithm validation standards for AI-based perfusion quantification tools in the United States, while the EU Medical Device Regulation reclassifies software-assisted diagnosis into higher risk tiers across European markets. The European Medicines Agency and national competent authorities enforce gadolinium retention labeling that redirects clinical preference toward macrocyclic agents and non-contrast alternatives. Stakeholders must monitor reimbursement code fragmentation between technical and professional components as value-based imaging contracts expand.
Market Dynamics
CT perfusion protocols are compressing stroke triage windows from hours to minutes, forcing imaging departments to reconfigure workflow architecture around speed rather than throughput alone. This velocity imperative is reshaping capital allocation decisions across radiology service lines.
Growth Catalysts
- EU Medical Device Regulation reclassification:Higher-risk tiering for diagnostic software is accelerating clinical validation investments, elevating algorithm reliability standards across European university hospitals.
- Arterial spin labeling adoption:Pediatric oncology centers and renal-impaired patient populations are migrating toward non-contrast MR perfusion, expanding addressable clinical indications without gadolinium exposure concerns.
- German glioma protocol standardization:University hospital networks have embedded MR perfusion into mandatory treatment pathways, creating institutional lock-in for quantitative imaging platforms.
Market Restraints
- Gadolinium retention liability:EMA-mandated labeling for macrocyclic versus linear agents has increased insurance and documentation burdens, dampening contrast-enhanced procedure volumes in risk-averse institutions.
- CT scanner replacement cycle extension:Hardware lifespan stretching beyond ten years is deferring bundled perfusion software upgrades, compressing vendor recurring revenue streams.
- Reimbursement code fragmentation:Technical and professional component splits across Medicare and commercial payers create administrative friction that slows adoption in outpatient imaging centers.
Strategic Opportunities
- AI-enhanced quantification software:FDA 510(k) clearance pathways for ischemic core identification algorithms are compressing validation timelines, enabling faster market entry for developers with robust training datasets.
- Value-based imaging contracts:Outcome-based payment structures are emerging in integrated delivery networks, rewarding perfusion-guided treatment decisions with shared savings mechanisms.
- Stroke center network expansion:United States primary stroke certification programs are mandating advanced imaging capabilities, creating procurement pull-through for CT perfusion installations in community hospitals.
Industry Challenges
- Quantitative imaging biomarker standardization:Variability in perfusion parameter calculation across vendor platforms complicates multi-site clinical trials and regulatory submissions.
- Workflow integration complexity:PACS and EMR interoperability requirements demand substantial IT infrastructure investment that stretches radiology department capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perfusion Radiology Market |
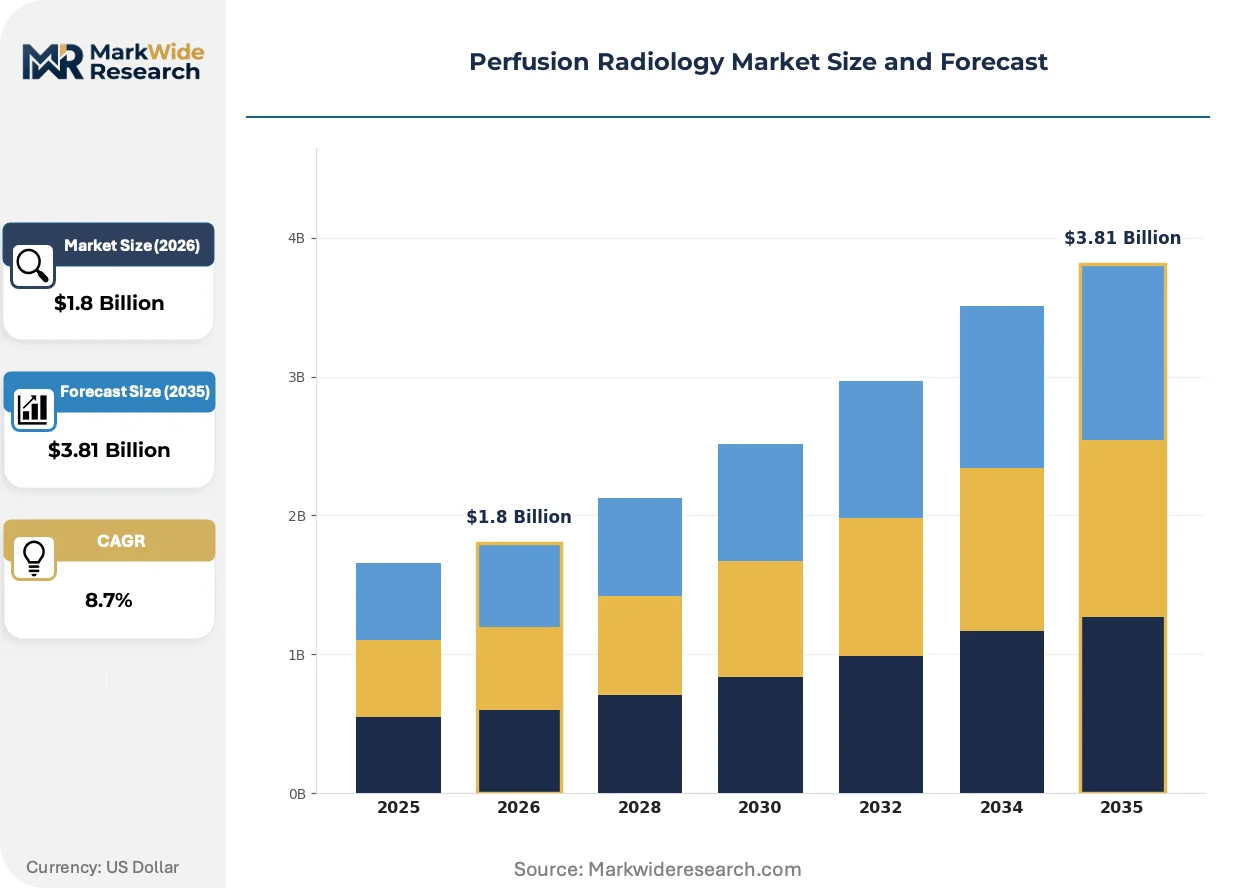
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Perfusion, MR Perfusion, Nuclear Medicine, Others End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Clinics Technology: Dynamic Susceptibility Contrast, Dynamic Contrast-Enhanced, Arterial Spin Labeling, Others Application: Oncology, Neurology, Cardiology, Traumatology |
| Companies Covered | Canon Medical Systems Corporation, FUJIFILM Corporation, GE HealthCare, Boston Scientific, Hitachi, Siemens Healthineers, Shimadzu Corporation, Abbott Laboratories, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfusion Radiology Market Emerging Trajectories
Software-defined imaging architectures are decoupling acquisition hardware from analysis layers, enabling algorithmic updates without scanner replacement. This modularization is redistributing value capture toward analytics vendors and cloud-based quantification services.
Arterial spin labeling is hybridizing with deep learning reconstruction to deliver contrast-free perfusion maps with spatial resolution approaching dynamic susceptibility contrast standards. Pediatric neuro-oncology programs at academic medical centers are piloting these sequences to eliminate gadolinium exposure in longitudinal tumor monitoring. The technology is hybridizing clinical workflows by collapsing the trade-off between safety and diagnostic confidence that previously forced protocol compromises.
FDA 510(k) clearance requirements for AI-based perfusion quantification are tightening validation dataset diversity mandates, requiring algorithm developers to demonstrate performance across scanner manufacturers and patient demographics. This regulatory pressure is consolidating development resources toward platforms with access to multi-institutional training data. Neuro-oncology applications face the steepest compliance burden due to the prognostic weight of perfusion-derived biomarkers in treatment planning.
Aftermarket service contracts are unbundling from hardware maintenance into standalone software subscription tiers, with AI algorithm update entitlements replacing preventive service visits as the primary retention mechanism. Integrated delivery networks in the United States are negotiating enterprise-wide perfusion analytics licenses that span multiple hospital systems. Germany and Japan exhibit similar procurement consolidation, though national reimbursement frameworks slow contract restructuring relative to commercial payer-dominated markets.
Perfusion Radiology Market Segmentation
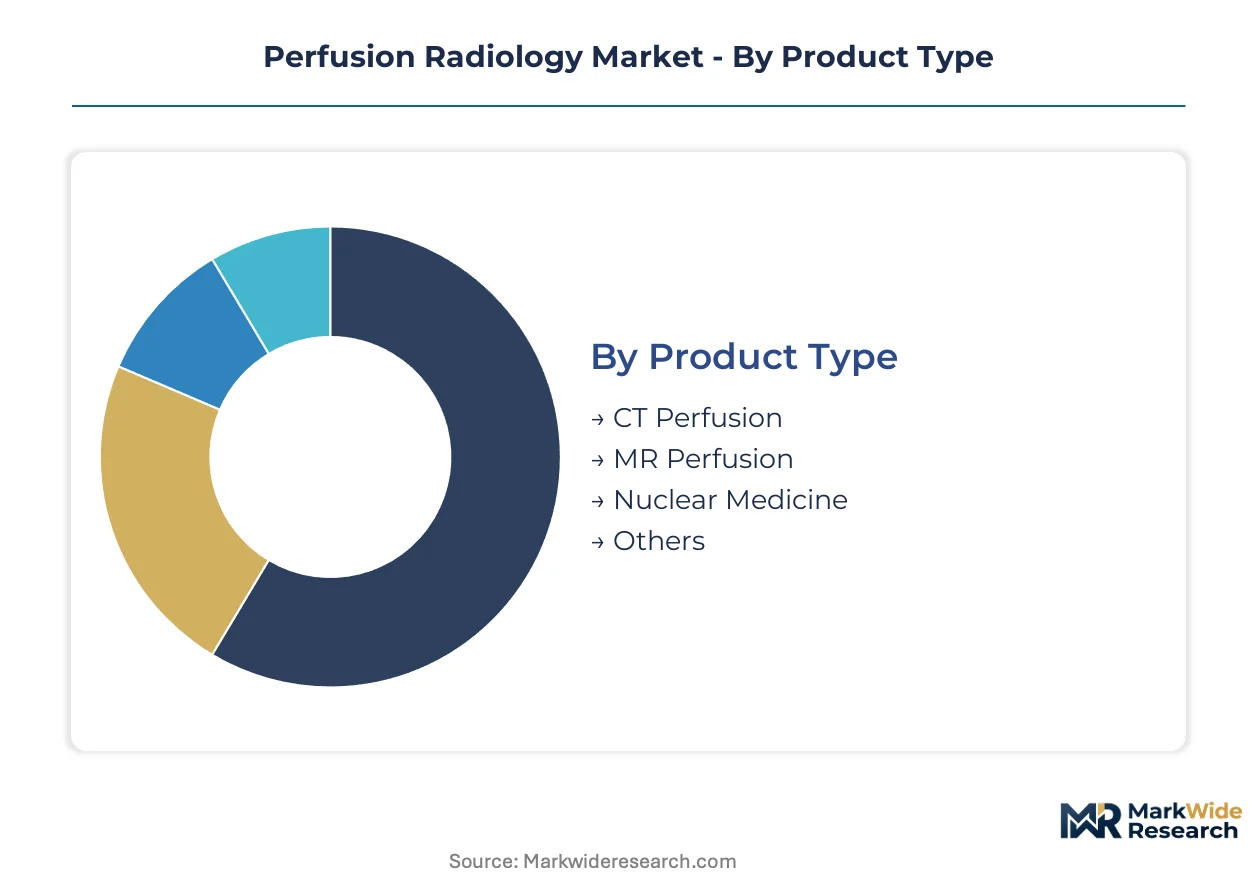
Perfusion radiology segmentation reveals divergent replacement cycles across hardware and software layers. CT scanner hardware stretches beyond a decade while AI algorithm updates refresh quarterly, creating misaligned vendor revenue streams.
Product Type:
CT Perfusion systems turn over slowest due to capital intensity, while AI software modules refresh fastest through subscription models.
- CT Perfusion:Iodinated contrast-based imaging employing 50-100 mL injection volumes delivers sub-minute acquisition protocols. United States stroke centers concentrate demand as primary stroke certification mandates compress triage windows from hours to minutes.
- MR Perfusion:Gadolinium-based dynamic susceptibility contrast and non-contrast arterial spin labeling sequences measure cerebral blood volume and permeability. German university hospital networks embed this modality into mandatory glioma treatment pathways, creating institutional procurement lock-in.
- Nuclear Medicine:PET and SPECT perfusion tracers quantify myocardial and cerebral blood flow through radiopharmaceutical kinetics.
- Others:Emerging optical and thermal perfusion monitoring technologies address intraoperative and wound assessment applications.
CT Perfusion dominates installed base. MR Perfusion is where expansion concentrates.
End User:
Capital allocation patterns separate high-acuity inpatient settings from volume-driven outpatient facilities.
- Hospitals:Academic medical centers and comprehensive stroke centers anchor demand for integrated perfusion suites with PACS connectivity. United States integrated delivery networks negotiate enterprise-wide analytics licenses spanning multiple hospital systems.
- Diagnostic Imaging Centers:Outpatient facilities face reimbursement code fragmentation between technical and professional components, slowing CT perfusion adoption despite favorable procedure economics.
- Research Institutions:Multi-site clinical trials drive demand for quantitative imaging biomarker standardization across vendor platforms.
- Clinics:Community-based neurology and cardiology practices concentrate on referral relationships rather than captive imaging capacity.
Hospitals command premium pricing. Diagnostic Imaging Centers represent the steepest expansion trajectory.
Technology:
Contrast dependence versus safety profiles create divergent clinical preference curves across patient populations.
- Dynamic Susceptibility Contrast:Gadolinium-based first-pass perfusion MRI retains primacy in neuro-oncology for established correlation with tumor grade. FDA 510(k) clearance requirements tighten validation dataset diversity mandates for AI-enhanced quantification tools.
- Arterial Spin Labeling:Endogenous water proton labeling eliminates exogenous contrast dependence entirely. Pediatric oncology centers and renal-impaired populations are migrating toward this non-contrast alternative, expanding addressable indications without gadolinium retention liability.
- Dynamic Contrast-Enhanced:Continuous contrast infusion protocols quantify vascular permeability and interstitial volume in oncologic applications.
- Others:Blood oxygen level-dependent and intravoxel incoherent motion techniques address specialized research and functional mapping requirements.
Dynamic Susceptibility Contrast dominates installed base. Arterial Spin Labeling is where expansion concentrates.
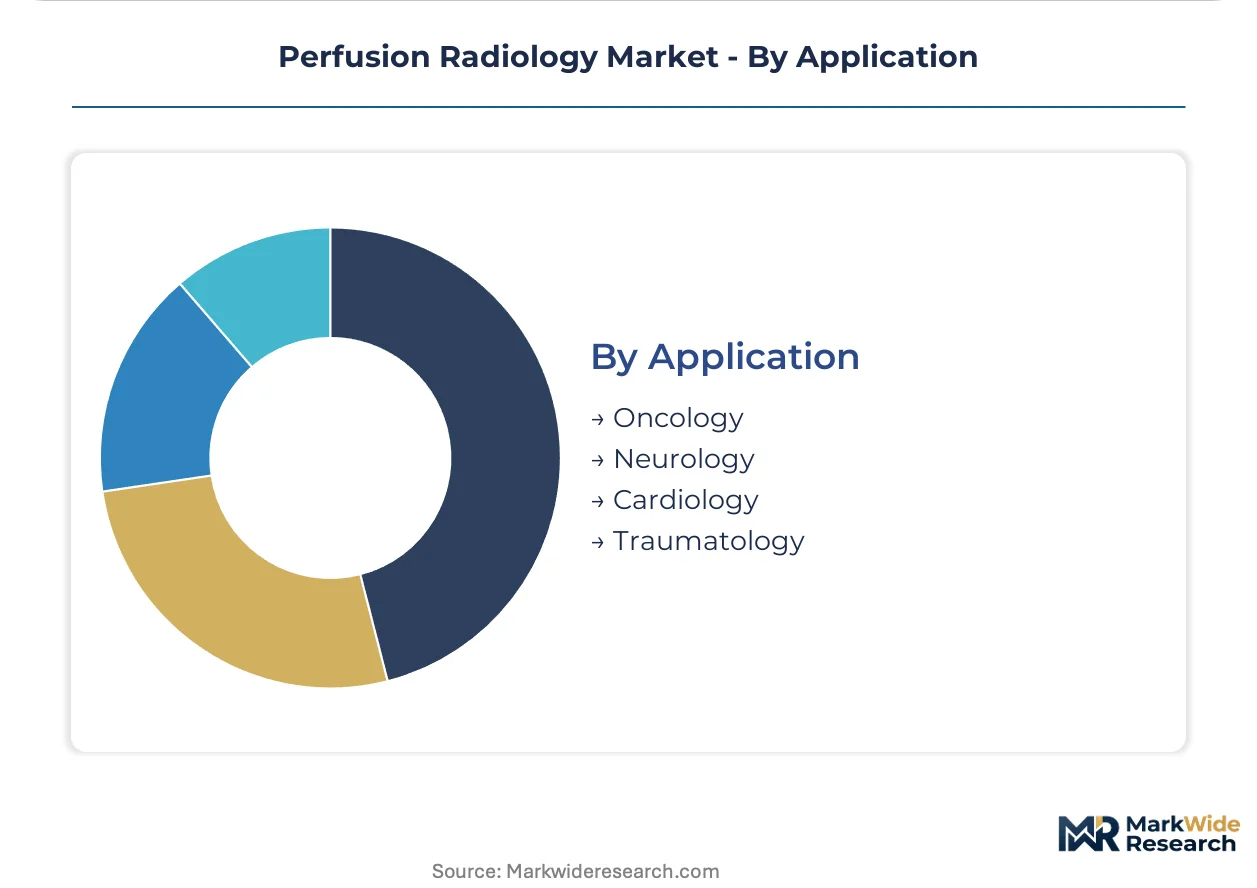
Application:
Reimbursement weighting and clinical urgency separate high-value acute indications from longitudinal monitoring applications.
- Oncology:MR perfusion biomarkers guide glioma treatment planning and response assessment through cerebral blood volume mapping. EMA-mandated gadolinium retention labeling redirects clinical preference toward macrocyclic agents and non-contrast alternatives.
- Neurology:CT perfusion protocols for acute ischemic stroke triage compress decision windows to minutes. United States stroke center network expansion creates procurement pull-through in community hospitals seeking primary stroke certification.
- Cardiology:Myocardial perfusion imaging through CT and MR techniques assesses coronary artery disease and microvascular dysfunction.
- Traumatology:Perfusion monitoring in extremity injury and compartment syndrome evaluation addresses emergency and surgical applications.
Neurology dominates installed base. Oncology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys MR perfusion for glioma protocol standardization, while the United States prioritizes CT perfusion velocity for stroke triage—this consumption-mix differential separates European oncology integration from North American emergency workflow optimization.
United States
Primary stroke certification programs mandate advanced imaging capabilities, driving CT perfusion installations in community hospitals. FDA 510(k) clearance pathways compress validation timelines for AI-enhanced ischemic core identification algorithms. Stroke centers in the Southeast and Midwest reconfigure workflow architecture around sub-minute acquisition protocols.
Germany
University hospital networks embed MR perfusion into mandatory glioma treatment pathways, creating institutional procurement lock-in for quantitative imaging platforms. EU Medical Device Regulation reclassification elevates algorithm reliability standards through higher-risk tiering for diagnostic software. Bavarian and Baden-Württemberg academic clusters anchor demand for integrated perfusion suites.
Japan
Pediatric oncology centers migrate toward arterial spin labeling sequences to eliminate gadolinium exposure in longitudinal tumor monitoring. METI standards guide software-defined imaging architectures that decouple acquisition hardware from analysis layers. Tokyo-Osaka metropolitan corridors concentrate pilot programs for deep learning reconstruction techniques.
United Kingdom
Integrated delivery networks negotiate enterprise-wide perfusion analytics licenses spanning multiple hospital systems. NHS reimbursement frameworks influence value-based imaging contract structures that reward perfusion-guided treatment decisions. London and Greater Manchester academic medical centers drive demand for quantitative biomarker standardization.
India
Diagnostic imaging centers face administrative friction from reimbursement code fragmentation, slowing CT perfusion adoption despite favorable procedure economics. CDSCO regulatory pathways shape clinical validation investments for AI-based quantification tools. Maharashtra and Karnataka hospital networks concentrate early procurement of subscription-based software tiers.
Perfusion Radiology Market Vendor Landscape
Capability concentration sits with imaging system integrators; scale advantage sits with diversified healthcare conglomerates. The vendor base separates into three tiers: full-stack modality manufacturers, AI-native software developers, and component specialists supplying contrast agents or reconstruction algorithms. Dominant competitive moves include software subscription unbundling from hardware maintenance and enterprise-wide analytics licensing across multi-hospital systems.
Within the integrated modality tier, GE HealthCare, Siemens Healthineers, and Canon Medical Systems occupy positions that exemplify divergent strategic anchoring—GE HealthCare leverages installed base bundling, Siemens Healthineers pursues end-to-end acquisition-to-reporting integration, and Canon Medical Systems represents the precision-focused Japanese manufacturing archetype with concentrated strength in detector technology and image reconstruction engines.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| FUJIFILM Corporation |
| GE HealthCare |
| Boston Scientific |
| Hitachi |
| Siemens Healthineers |
| Shimadzu Corporation |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| Others |
Supply Flow & Price Mechanics
Gadolinium-based contrast agent production concentrates in Ireland and France, anchoring margin capture for macrocyclic formulations downstream while arterial spin labeling adoption redistributes value toward software reconstruction licenses. Pricing power separates contrast-dependent from contrast-free modalities.
Pricing Analysis
Long-term subscription contracts dominate enterprise analytics licensing, with three-tier pricing structure across premium, standard, and economy levels tied to algorithm update frequency and PACS integration depth. Price differentiation hinges on FDA 510(k) clearance tier and stroke center certification status. Pricing pressure stems from hardware replacement cycle extension beyond ten years. Outpatient imaging centers exhibit highest price sensitivity; comprehensive stroke centers show lowest due to certification mandates.
Supply Chain Analysis
Export-control regimes for AI-enabled medical imaging software restrict algorithm transfer to certain jurisdictions, forcing localization of training data pipelines. Component manufacturing concentrates in Germany, Japan, and the United States for gradient coil assemblies and detector arrays. Raw material dependencies include high-purity iodine for CT contrast, rare earth elements for MRI magnets, and GPU clusters for deep learning reconstruction. Single-source vulnerability sits with specialized ASIC fabricators for real-time perfusion processing. Distribution runs through integrated delivery network procurement consortia and national hospital purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from AI algorithm subscriptions and quantitative reporting licenses is expanding faster than CT scanner hardware sales, creating a recurring-revenue opportunity that decouples vendor growth from capital expenditure cycles.
For Market Incumbents: Build installed-base moats through PACS-embedded workflow integration that raises switching costs for stroke centers. Consolidate position by acquiring arterial spin labeling reconstruction specialists before pediatric oncology standardization accelerates. Threaten margin compression from AI-native software vendors bypassing hardware bundling. Leverage vertical integration into cloud-based quantification services to capture analytics layer value. For New Entrants and Emerging Players: Pursue diagnostic imaging center outpatient facilities where reimbursement code fragmentation has slowed incumbent penetration. White-space concentrates in community hospital stroke certification programs seeking subscription-tier pricing without enterprise hardware commitments. Go-to-market through GPO contracts managers offering unbundled software licenses with rapid FDA 510(k) clearance timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed AI quantification platforms holding multi-institutional training datasets but lacking scanner OEM distribution. Five-to-ten year viability favors vendors with algorithmic update entitlements replacing preventive service visits as primary retention mechanisms. Watch FDA validation dataset diversity mandates as inflection indicator for consolidation toward platforms with cross-manufacturer training data.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Compresses validation timelines for ischemic core identification algorithms seeking stroke center adoption. |
| Hospital System Partnership | Secures enterprise-wide analytics licenses across multi-hospital integrated delivery networks. |
| Software Companion Development | Enables arterial spin labeling reconstruction modules that eliminate gadolinium exposure liability. |
| CE Marking Pathway | Navigates EU Medical Device Regulation higher-risk tiering for diagnostic software in German university hospitals. |
| Reimbursement Strategy | Aligns perfusion-guided treatment decisions with value-based imaging contract shared savings mechanisms. |
Methodological Framework
Operator-level perspectives from stroke center directors, neuroradiologists, hospital purchasing committee members, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, EMA gadolinium retention labeling directives, and hospital procurement contract filings. Bottom-up triangulation across CT and MR perfusion installation records converged with top-down spending estimates from integrated delivery network capital expenditure disclosures.
Scenario-bracketing framed projections across the analysis window, modeling adoption curves by modality type, end-user facility tier, contrast dependence profile, and regional regulatory cluster. CAGRs derived from weighted average of hardware replacement cycles and software subscription renewal rates. Forecast inputs incorporated stroke center certification program expansion timelines and EU MDR reclassification compliance costs.
Sensitivities concentrate around FDA validation dataset diversity mandate enforcement and arterial spin labeling spatial resolution thresholds achieving dynamic susceptibility contrast parity. Forecasts reflect documented assumptions on reimbursement code consolidation and hardware-software unbundling velocity. Material shifts in EU Medical Device Regulation diagnostic software risk tiering or CMS technical-professional component restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
Medical Holography Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
Global Spectral Computed Tomography (CT) Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
Global Elastography Imaging Market