
 Teleultrasound System Market | 2026-2036
Teleultrasound System Market Size, Share, and Industry Trends Forecast 2026-2036
Teleultrasound System Market Analytics
Semiconductor-grade silicon is rebalancing probe manufacturing economics as manufacturers shift from legacy piezoelectric ceramics. GE Healthcare leverages captive semiconductor partnerships to secure wafer supply. Koninklijke Philips NV anchors its premium tier through proprietary beamforming chipsets. Siemens Healthineers differentiates via integrated cloud architecture that streams raw RF data rather than compressed images.
A teleultrasound system comprises an ultrasound probe, a computing unit with beamforming hardware, and a low-latency transmission link that delivers real-time imaging data to remote interpreters. These systems operate at 2-15 MHz transducer frequencies and achieve frame rates above 30 fps over 4G or 5G networks, enabling obstetric, cardiac, and abdominal diagnostics where onsite specialists are unavailable. Portable devices lead volume shipments due to field-deployment flexibility in emergency and rural settings. AI Integration represents the fastest-expanding technology segment as FDA-cleared algorithms automate biometric measurements and flag anomalies during live scans. Console systems retain the largest margin pool in high-acuity hospital environments where multi-probe configurations and advanced Doppler modes justify capital expenditure.
FDA 510(k) pathways and HIPAA security requirements govern US market access, while the EU MDR and GDPR impose clinical-evidence and data-localization burdens on European deployments. India's CDSCO regulates imported diagnostic devices under the Medical Device Rules, creating compliance complexity for foreign manufacturers. Stakeholders must monitor spectrum allocation policies for 5G medical-grade networks and evolving reimbursement codes for remote interpretation services.
Market Dynamics
Semiconductor-grade silicon is rebalancing probe manufacturing economics as manufacturers shift from legacy piezoelectric ceramics, compressing production cycles and enabling volume scaling that was previously unattainable with ceramic transducer stacks.
Growth Catalysts
- Specialist Shortages in Tier-Two Cities:India's tier-two urban centers face persistent gaps in radiologist availability, driving deployment of remote interpretation infrastructure to bridge diagnostic access.
- FDA 510(k) Pathway Compression:Streamlined clearance mechanisms for remote diagnostic devices accelerate product-to-market timelines for manufacturers targeting US healthcare systems.
- 5G Spectrum Allocation:Medical-grade network prioritization policies across multiple jurisdictions enable sub-100ms latency transmission required for real-time cardiac and obstetric imaging.
Market Restraints
- Wafer Supply Concentration:Captive semiconductor partnerships at GE Healthcare and similar vertical arrangements limit spot-market availability for second-tier manufacturers.
- EU MDR Clinical Evidence Burden:European Medical Device Regulation mandates extensive clinical documentation that extends registration timelines and elevates compliance costs for cloud-streaming architectures.
- Compressed Image Standard Entrenchment:Legacy DICOM workflows and institutional preference for lossy compression formats create interoperability friction with raw RF data transmission protocols.
Strategic Opportunities
- Emergency Department Triage Integration:AI-augmented teleultrasound systems enable point-of-care decision support for trauma and acute cardiac presentations, expanding addressable use cases beyond traditional radiology workflows.
- India's CDSCO Import Pathway Simplification:Proposed revisions to Medical Device Rules may reduce registration complexity for foreign manufacturers targeting maternal health screening programs.
- Cloud-Native Beamforming Convergence:Integration of edge computing with proprietary chipsets allows real-time processing offload, reducing hardware footprint for portable deployments.
Industry Challenges
- RF Data Interpretation Skill Gap:Raw radiofrequency streaming requires specialized training distinct from conventional ultrasound image reading, constraining interpreter pool expansion.
- Multi-Probe Configuration Integration:Console systems demand complex calibration protocols across transducer arrays, elevating field service requirements and total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teleultrasound System Market |
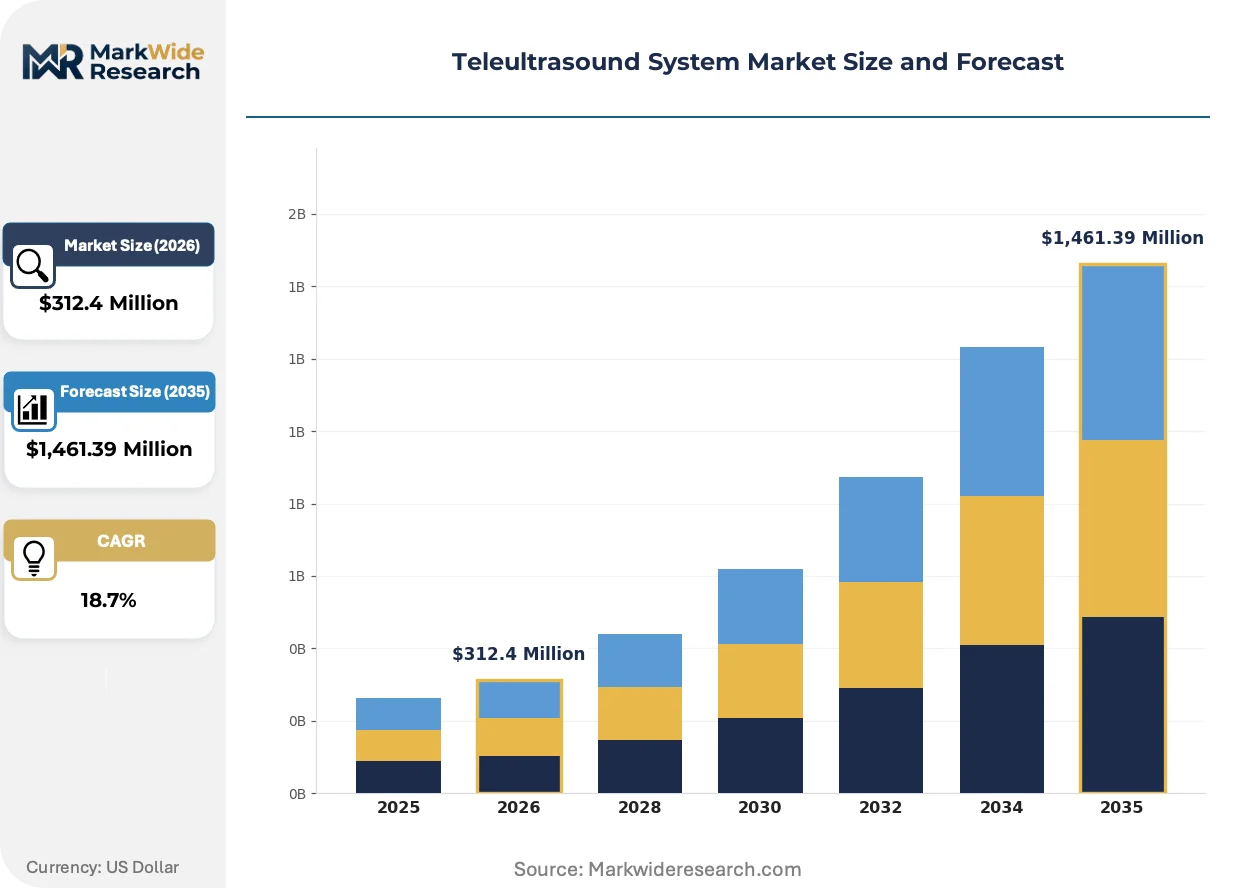
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Handheld Units, Console Systems, Imaging Software End User: Clinics, Hospitals, Diagnostic Centers, Home Care Technology: 2D Imaging, 3D Imaging, Doppler Ultrasound, AI Integration Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | GE Healthcare, Koninklijke Philips NV, Siemens Healthineers, Mindray, Fujifilm, Remote Medical Technologies LLC, Canon Medical Systems, Robo Medical, AdEchoTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teleultrasound System Market Evolving Landscape
Probe architecture is fragmenting into interchangeable component ecosystems that decouple transducer heads from processing units, enabling hardware refresh cycles independent of full system replacement.
Semiconductor beamforming chipsets are modularizing ultrasound system design by separating analog front-end acquisition from digital signal processing. Rural hospitals across Vietnam and Indonesia adopt these configurable platforms to match probe capabilities with specific screening protocols. This disaggregation is compressing capital expenditure thresholds and allowing procurement of specialized transducers without console redundancy.
The EU AI Act's risk classification framework is recategorizing diagnostic algorithms as high-risk systems requiring conformity assessment and post-market surveillance. Manufacturers serving European deployments must establish quality management systems that trace algorithm training data and validation performance. Cloud-streaming vendors with integrated AI modules face the steepest compliance elevation, particularly those targeting obstetric anomaly detection.
Institutional purchasing is consolidating around subscription-based service models that unbundle hardware acquisition from interpretation access and software maintenance. Hospital systems in Brazil and Mexico increasingly favor per-scan pricing over capital purchase, shifting vendor revenue toward recurring streams. This transformation pressures manufacturers to develop remote monitoring infrastructure and predictive maintenance capabilities that were previously optional.
Teleultrasound System Market Segmentation
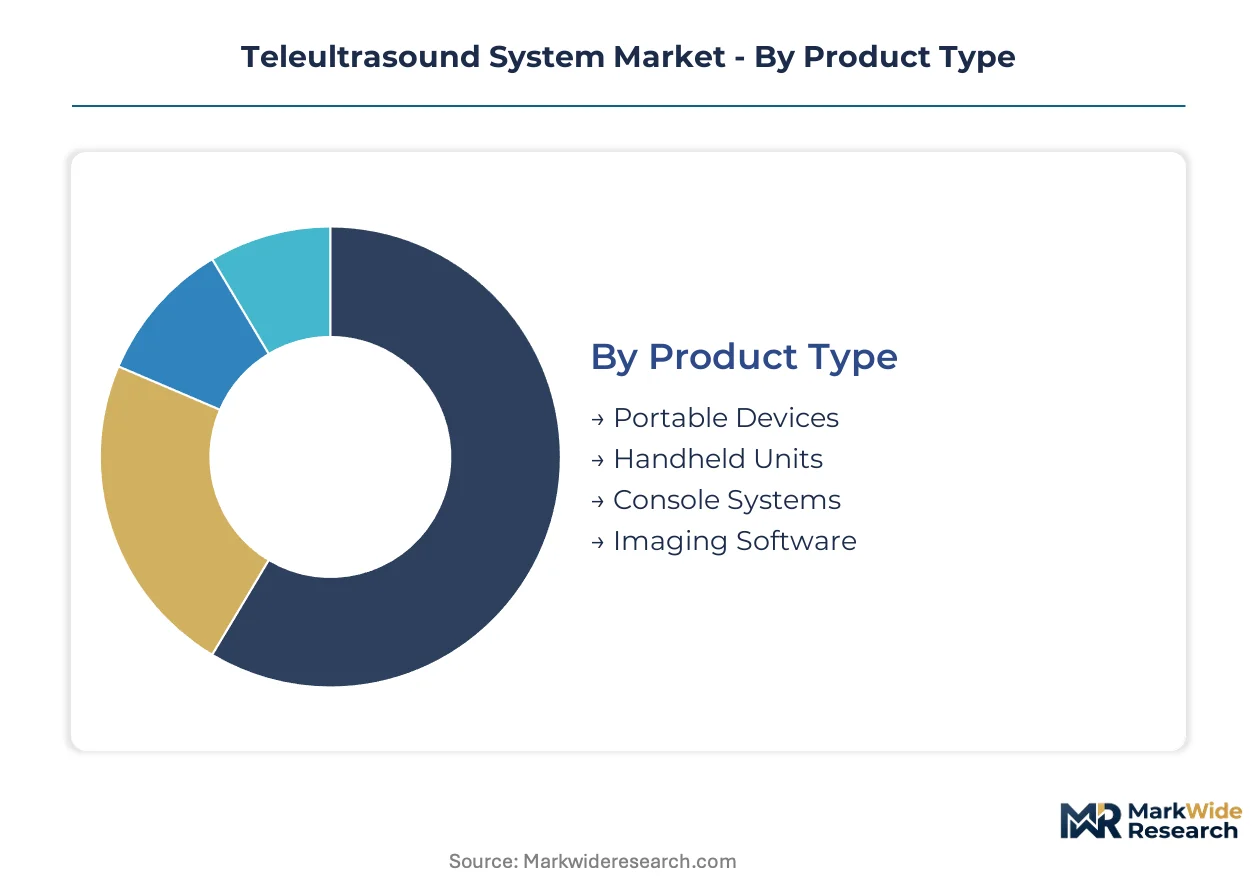
Teleultrasound system purchasing decisions pivot on deployment environment constraints, connectivity infrastructure, and interpreter availability. Buyers match product configurations to specific clinical workflows rather than acquiring generalized platforms.
Product Type:
Procurement prioritizes field-deployment flexibility and total cost of ownership over raw imaging performance in underserved geographies.
- Portable Devices:Battery-powered units with integrated beamforming processors operate independently of fixed infrastructure. Rural hospitals across Vietnam and Indonesia deploy these for maternal health screening where power reliability varies.
- Console Systems:Multi-probe configurations with advanced Doppler modes anchor high-acuity hospital environments. India's tier-two cities justify capital expenditure through shared radiologist access across departments.
- Handheld Units:Smartphone-tethered probes reduce hardware footprint for emergency responders.
- Imaging Software:Cloud-native platforms enable raw RF data streaming and AI-augmented interpretation.
Volume sits with Portable Devices; growth tilts toward Imaging Software.
End User:
Capital availability and specialist density determine facility-level adoption patterns across healthcare tiers.
- Hospitals:Acute care institutions deploy console systems for cardiac and trauma applications requiring real-time specialist consultation. India's CDSCO registration requirements shape procurement timelines for imported equipment.
- Clinics:Outpatient facilities favor handheld and portable configurations for point-of-care diagnostics. Southeast Asian maternal health programs concentrate demand here.
- Diagnostic Centers:Dedicated imaging facilities balance throughput requirements against equipment utilization rates.
- Home Care:Emerging deployments target chronic disease monitoring with simplified operator interfaces.
Revenue concentrates with Hospitals; expansion accelerates fastest in Home Care.
Technology:
Regulatory clearance velocity and algorithm training data access separate commercial viability from technical promise.
- AI Integration:FDA-cleared algorithms automate biometric measurements during live scans. The EU AI Act's high-risk classification imposes conformity assessment burdens on obstetric anomaly detection modules.
- 2D Imaging:Established protocols dominate reimbursement codes and interpreter training curricula. Legacy DICOM workflows entrench this modality in institutional purchasing.
- 3D Imaging:Volumetric reconstruction requires higher bandwidth and specialized interpretation skills.
- Doppler Ultrasound:Hemodynamic assessment capabilities justify premium positioning in cardiac applications.
Installed base favors 2D Imaging; capability investment flows toward AI Integration.
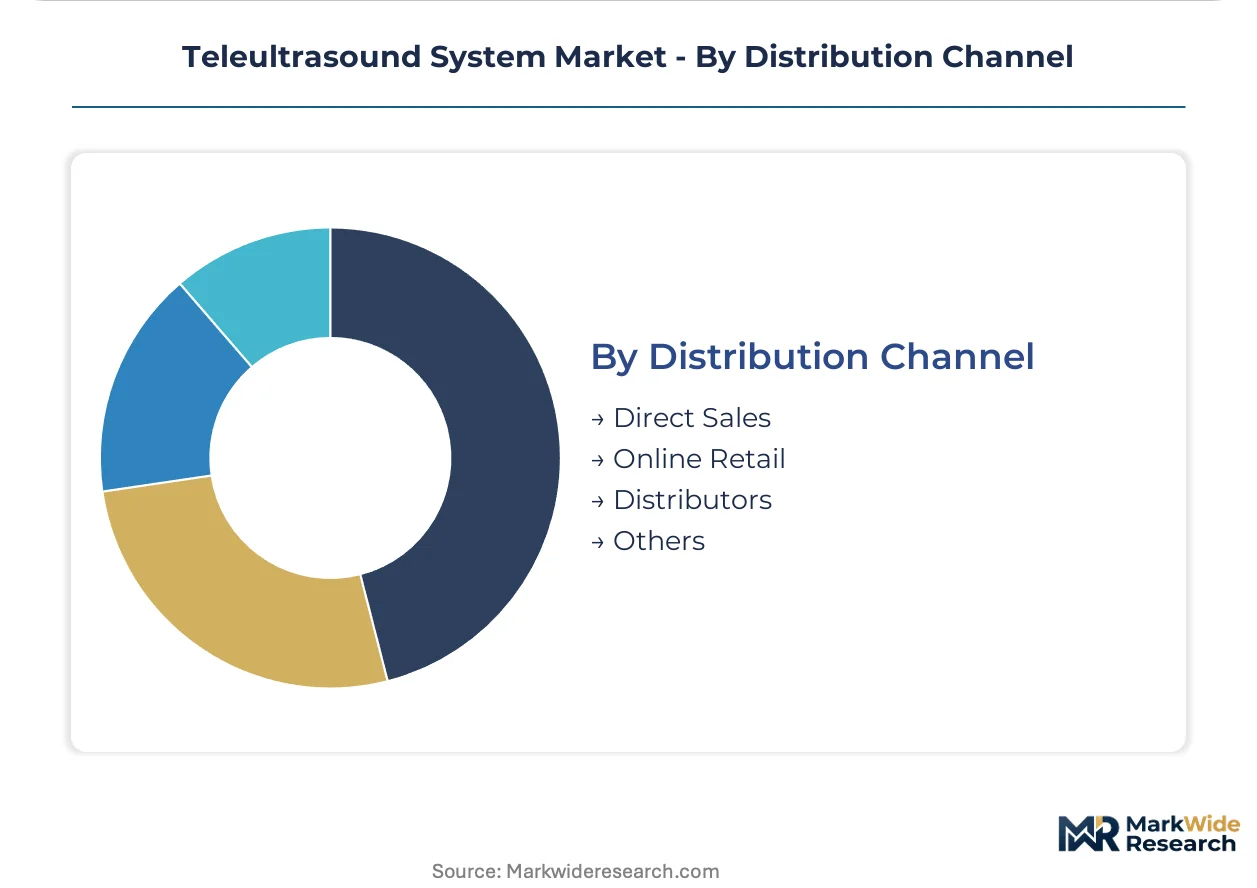
Distribution Channel:
Service bundling requirements and regulatory compliance complexity reshape channel economics.
- Direct Sales:Manufacturers deploy field service engineers for console system installation and calibration. India's CDSCO import regulations favor direct relationships for documentation compliance.
- Distributors:Local inventory and technical support networks penetrate secondary cities. Brazilian and Mexican hospital systems increasingly favor per-scan pricing arrangements through these channels.
- Online Retail:Handheld units and software licenses move through digital procurement platforms.
- Others:Government tender processes and NGO procurement programs operate outside standard commercial channels.
Transaction volume flows through Distributors; margin capture concentrates with Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's tier-two cities concentrate specialist shortages that drive teleultrasound deployment for maternal health screening, while Southeast Asian rural hospitals adopt portable systems for emergency diagnostics. Vietnam and Indonesia anchor volume demand through government-backed rural health programs. Regulatory fragmentation across FDA, EU MDR, and India's CDSCO shapes market access timelines.
United States
Emergency department triage integration and AI-augmented point-of-care diagnostics propel hospital procurement. FDA 510(k) pathways compress clearance timelines for remote diagnostic devices. Texas Medical Center and Mayo Clinic clusters in Houston and Rochester pilot raw RF data streaming protocols for cardiac applications.
India
Tier-two urban centers face persistent radiologist gaps that remote interpretation infrastructure must bridge. CDSCO import regulations under Medical Device Rules create compliance complexity for foreign manufacturers. Maharashtra's Mumbai-Pune corridor concentrates diagnostic center deployments, while Karnataka's Bengaluru anchors startup activity in AI-integrated imaging software.
Germany
EU MDR clinical evidence mandates extend registration timelines for cloud-streaming architectures. GDPR data localization requirements impose additional compliance burdens on vendors serving European deployments. Baden-Württemberg's Stuttgart region hosts precision manufacturing clusters supplying semiconductor beamforming components.
Vietnam
Rural maternal health screening programs drive portable device adoption where power reliability varies across provinces. Government spectrum allocation for 5G medical-grade networks enables sub-100ms latency transmission. Ho Chi Minh City anchors distributor networks penetrating secondary cities with per-scan pricing arrangements.
Brazil
Subscription-based service models unbundle hardware acquisition from interpretation access across hospital systems. ANVISA regulates imported diagnostic devices with documentation requirements favoring direct manufacturer relationships. São Paulo's metropolitan hospitals justify console system capital expenditure through shared radiologist access.
Teleultrasound System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier console systems consolidating around integrated platform vendors while portable and handheld categories fragment across component assemblers. The vendor base stratifies into three archetypes: semiconductor-captive incumbents with wafer supply control, cloud-native challengers streaming raw RF data, and AI-integrated specialists automating biometric measurements. Dominant competitive moves include backward integration into semiconductor partnerships and geographic expansion through distributor-owned inventory networks.
Within the semiconductor-captive tier, GE Healthcare and Koninklijke Philips NV occupy positions that exemplify supply security strategies, while Siemens Healthineers anchors the cloud-architecture vector with integrated platforms. These three incumbents represent distinct competitive positioning: GE Healthcare through captive wafer partnerships, Philips through proprietary beamforming chipsets, and Siemens through raw data streaming differentiation.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips NV |
| Siemens Healthineers |
| Mindray |
| Fujifilm |
| Remote Medical Technologies LLC |
| Canon Medical Systems |
| Robo Medical |
| AdEchoTech |
| Others |
Value Network & Pricing Analysis
Semiconductor-captive incumbents with wafer supply control anchor pricing discipline through backward integration into probe manufacturing, compressing cost structures for premium-tier console systems while spot-market-dependent assemblers absorb margin erosion in handheld categories. This ownership pattern concentrates pricing power with vertically integrated manufacturers serving India's tier-two hospital clusters and Southeast Asian rural health programs.
Pricing Analysis
Volume concentrates with portable devices while margin capture tilts toward console systems and imaging software subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI-integrated platforms from CE-marked mid-tier configurations and unbundled probe hardware. Pricing pressure stems from semiconductor wafer supply concentration that elevates input costs for second-tier manufacturers. Clinics and emergency responders exhibit highest price sensitivity, while acute care hospitals prioritize multi-probe capability over per-unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale hospital procurement, while distributor-owned inventory networks penetrate Vietnam and Indonesia's secondary cities with per-scan service arrangements. Manufacturing concentrates in Germany's precision component clusters, China's electronics assembly hubs, and South Korea's semiconductor foundries. Probe assembly draws from semiconductor-grade silicon wafers, piezoelectric ceramic substrates, and cloud-computing infrastructure. Single-source vulnerability in beamforming chipset supply elevates risk for cloud-streaming vendors. Distribution runs through government tender processes for maternal health programs and NGO procurement channels outside standard commercial flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
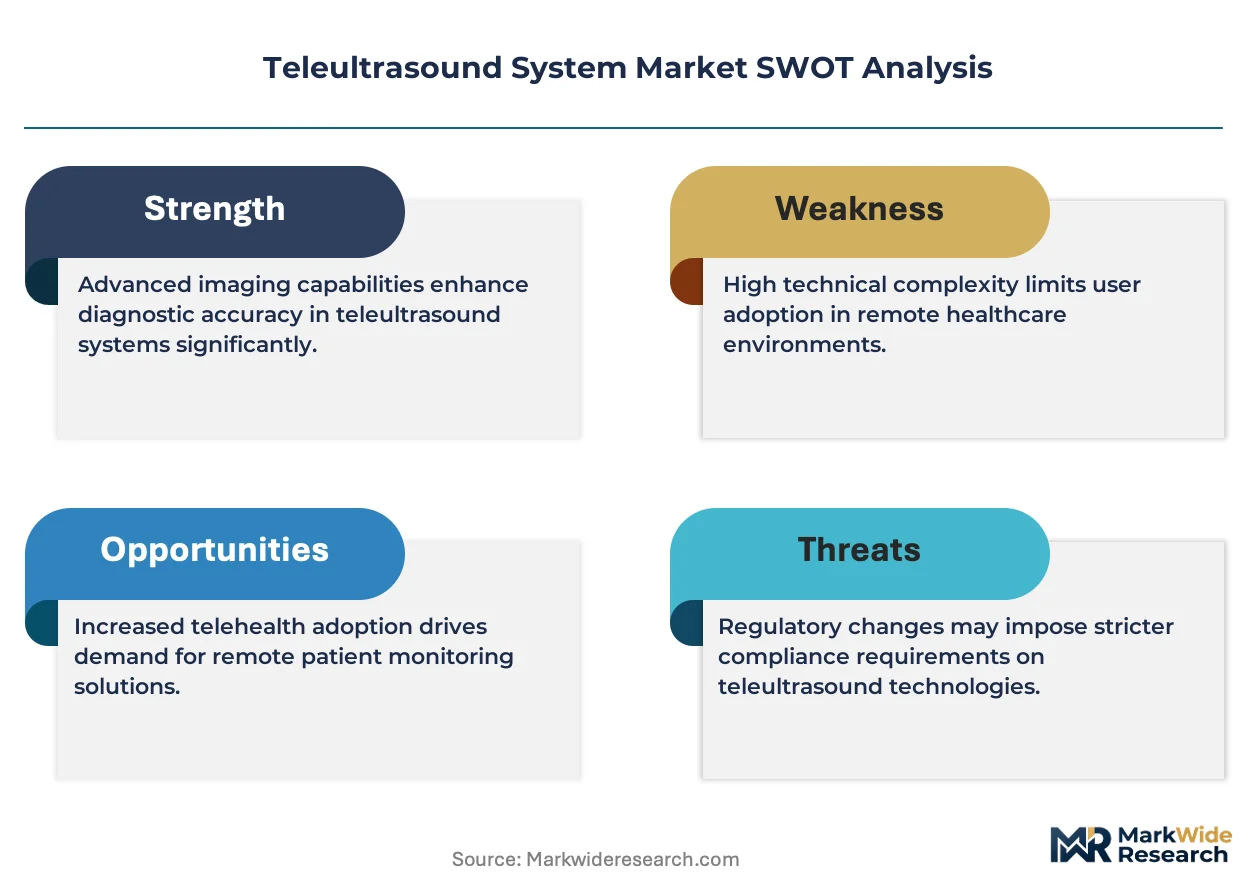
Semiconductor supply concentration and EU MDR compliance burdens are forcing weaker assemblers toward exit or acquisition, consolidating share among wafer-secure incumbents and cloud-native challengers with AI integration capabilities.
For Market Incumbents: To counter cloud-native challengers streaming raw RF data, GE Healthcare and Philips must deepen captive semiconductor partnerships to secure wafer allocation for proprietary beamforming chipsets. Hospital system partnership consolidation in Brazil and Mexico demands predictive maintenance infrastructure investment to defend recurring revenue streams against per-scan pricing entrants. For New Entrants and Emerging Players: Digital-channel routes through online retail platforms enable smartphone-tethered probe penetration of emergency responder and home care segments with minimal field service footprint. India's CDSCO import pathway simplification proposals create the most penetrable regulatory opening for maternal health screening programs. AI-augmented interpretation software licensing offers the strongest go-to-market angle against hardware-captive incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor AI-integrated software specialists in India's Bengaluru corridor and Vietnam's Ho Chi Minh City distributor networks amid CDSCO compliance cost pressures. Long-term viability across the projection horizon rests on FDA 510(k) clearance velocity and 5G medical-grade spectrum allocation stability. Watch for EU AI Act high-risk classification enforcement as the inflection signal for cloud-streaming vendor compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Partnership Consolidation | Captive wafer supply secures beamforming chipset allocation for GE Healthcare and Philips against spot-market volatility. |
| FDA 510(k) Pathway Acceleration | Streamlined clearance for AI-integrated remote diagnostic devices compresses product-to-market timelines for US hospital procurement. |
| Cloud-Native RF Data Streaming | Siemens Healthineers' raw data architecture differentiates against compressed-image legacy workflows in cardiac applications. |
| Subscription Service Model Transition | Per-scan pricing penetration in Brazilian and Mexican hospital systems shifts vendor revenue toward recurring software streams. |
| 5G Medical-Grade Network Prioritization | Vietnam and Indonesia spectrum allocation enables sub-100ms latency transmission for real-time obstetric and trauma diagnostics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and cloud-platform integration specialists. FDA 510(k) clearance databases, EU MDR conformity assessment records, India's CDSCO import registrations, and semiconductor trade flow statistics provided validation benchmarks. Bottom-up shipment modeling across probe categories reconciled with top-down healthcare capital expenditure surveys.
Data-stream reconciliation across portable device shipment volumes, console system installation records, and imaging software subscription counts enabled cross-validation of manufacturer-reported figures. Segmentation dimensions spanned product type, end-user facility tier, technology modality, and regional regulatory cluster. CAGRs were derived from curve-fitting across historical penetration rates and projected infrastructure deployment timelines. 5G network rollout schedules and AI algorithm clearance pipelines served as industry-specific forecast inputs.
The model holds under stable semiconductor supply allocation and consistent reimbursement code expansion for remote interpretation services; deviation in wafer supply disruption or EU AI Act enforcement intensity would shift trajectory. Forecasts reflect documented assumptions regarding specialist shortage persistence in tier-two cities and spectrum prioritization policy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
Ultrasound Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Europe Digital Radiology Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Image-Guided Biopsy Market