
 Intraoral Dental Sensors Market | 2026-2036
Intraoral Dental Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Intraoral Dental Sensors Market Insights
CE marking under the EU Medical Device Regulation is reorganizing competitive access across European distribution channels. Dentsply Sirona leverages its vertically integrated manufacturing footprint to sustain pricing power in premium sensor tiers. Carestream Dental anchors its position through dense service networks across North American dental service organizations. Planmeca Oy differentiates via proprietary imaging software paired with its hardware platforms.
Intraoral dental sensors are solid-state photodetectors, typically employing CMOS or CCD pixel arrays on ceramic or glass substrates, that convert X-ray energy into digital images with spatial resolutions reaching 20+ line pairs per millimeter for caries and periodontal diagnostics. Digital sensors and intraoral cameras together constitute the core revenue pool, with CMOS technology displacing legacy CCD architectures due to lower power draw and reduced unit production costs. Dental clinics represent the dominant end-user channel, while hospital-based dentistry and research institutions concentrate demand for cone beam CT configurations at the premium tier.
FDA 510(k) clearance timelines and ISO 13485 quality system certification govern market entry in the United States and international markets respectively, with MDR technical documentation requirements in Europe now extending conformity assessment periods for new sensor platforms. Japan's PMDA and South Korea's MFDS impose additional electromagnetic compatibility and radiation safety testing that shapes regional product configuration strategies. Stakeholders must monitor how AI-enabled diagnostic overlays trigger new software-as-medical-device classifications across multiple jurisdictions.
Market Dynamics
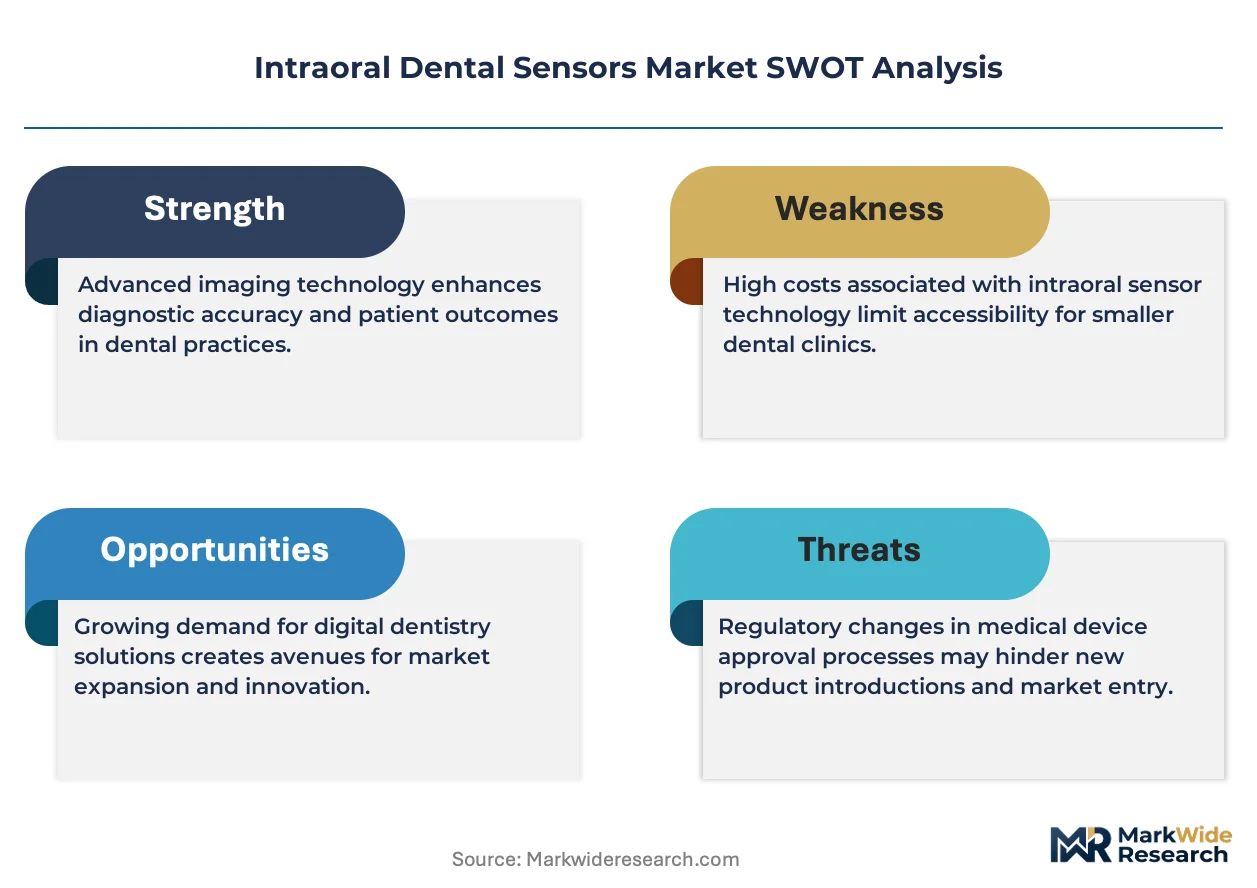
CMOS photodetector arrays are displacing legacy CCD architectures across dental imaging procurement, compressing unit economics while elevating resolution benchmarks for caries detection. This technology transition concentrates manufacturing advantage among vertically integrated sensor fabricators with captive semiconductor foundry relationships.
Growth Catalysts
- CMS Reimbursement Realignment:United States dental clinics accelerate digital sensor procurement as Medicare Advantage and commercial payers expand radiographic diagnostic coverage while reducing film-based alternative compensation.
- EU MDR CE Marking Pathway:Extended conformity assessment timelines for new sensor platforms create first-mover advantages for manufacturers with established notified body relationships and technical documentation libraries.
- CMOS Wafer Cost Curves:Semiconductor foundry scale economies in Taiwan and South Korea reduce per-pixel production costs, enabling price accessibility for mid-tier dental service organizations.
Market Restraints
- Ceramic Substrate Supply Concentration:Japanese and German specialty glass-ceramic suppliers control substrate feedstock for high-resolution sensors, exposing procurement to single-source risk.
- PMDA Electromagnetic Compatibility Testing:Japan's radiation safety and EMC certification requirements extend market entry timelines by 8-14 months for non-domestic manufacturers.
- Intraoral Camera Convergence:Multifunctional imaging devices combining photographic and radiographic capture threaten standalone sensor volume in premium clinic segments.
Strategic Opportunities
- Brazil's SUS Digital Dentistry Initiative:Public health system modernization programs create tender opportunities for cost-optimized CMOS sensor configurations in municipal dental clinics.
- AI Diagnostic Overlay Integration:Software-as-medical-device classifications for caries detection algorithms open recurring revenue streams through subscription licensing to sensor hardware platforms.
- Dental Service Organization Consolidation:North American DSO roll-ups generate fleet-standardization contracts favoring vendors with dense field service networks and remote calibration capabilities.
Industry Challenges
- ISO 13485 Quality System Maintenance:Multi-site manufacturing audits and supplier qualification documentation impose recurring compliance overhead on mid-cap sensor producers.
- Legacy Practice Management Integration:Proprietary imaging software protocols from incumbent vendors create data interoperability friction for new sensor market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraoral Dental Sensors Market |
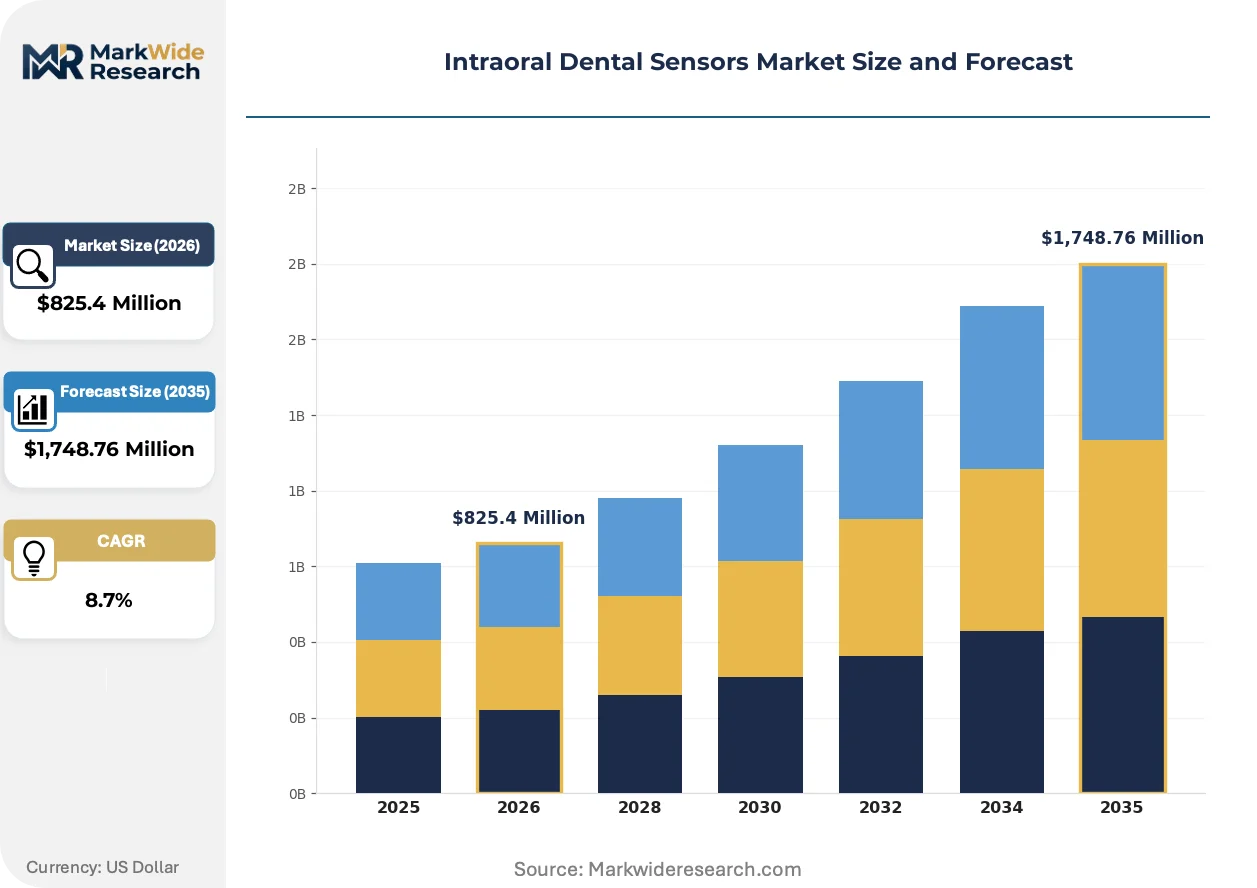
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,748.76 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Cameras, Digital Sensors, X-Ray Sensors, Cone Beam CT End User: Dental Clinics, Hospitals, Research Institutions, Private Practices Technology: Ceramic-Based, CMOS, CCD, Hybrid Application: Diagnostics, Treatment Planning, Patient Education, Imaging |
| Companies Covered | Dentsply Sirona, Carestream Dental, Planmeca Oy, VATECH, DEXIS, Owandy Radiology, Acteon Group, FONA Dental, Midmark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraoral Dental Sensors Market Trends and Innovations
Active sensor development concentrates on three vectors: semiconductor architecture evolution, regulatory classification expansion for AI-augmented diagnostics, and procurement model restructuring among consolidated dental service organizations.
CMOS active-pixel sensor technology is displacing charge-coupled device architectures in new dental imaging procurement. Dental service organizations and multi-location clinic chains in Germany and Japan now specify CMOS-native systems for fleet standardization. This displacement compresses CCD component supply chains while elevating performance expectations for dynamic range and low-dose sensitivity.
EU Medical Device Regulation technical documentation requirements now extend conformity assessment periods for sensor platforms incorporating AI-enabled diagnostic overlays. Manufacturers must demonstrate algorithm validation across diverse patient demographics to satisfy notified body scrutiny. Premium-tier sensor vendors with established quality management systems are accelerating MDR certification to capture delayed competitor market entry.
Subscription-based equipment procurement is replacing capital purchase models among North American dental service organizations. Sensor-as-a-service arrangements bundle hardware, calibration, and software updates into per-procedure fees. This restructuring is most visible in Texas and Florida DSO networks, where fleet standardization contracts favor vendors with captive financing arms.
Intraoral Dental Sensors Market Segmentation
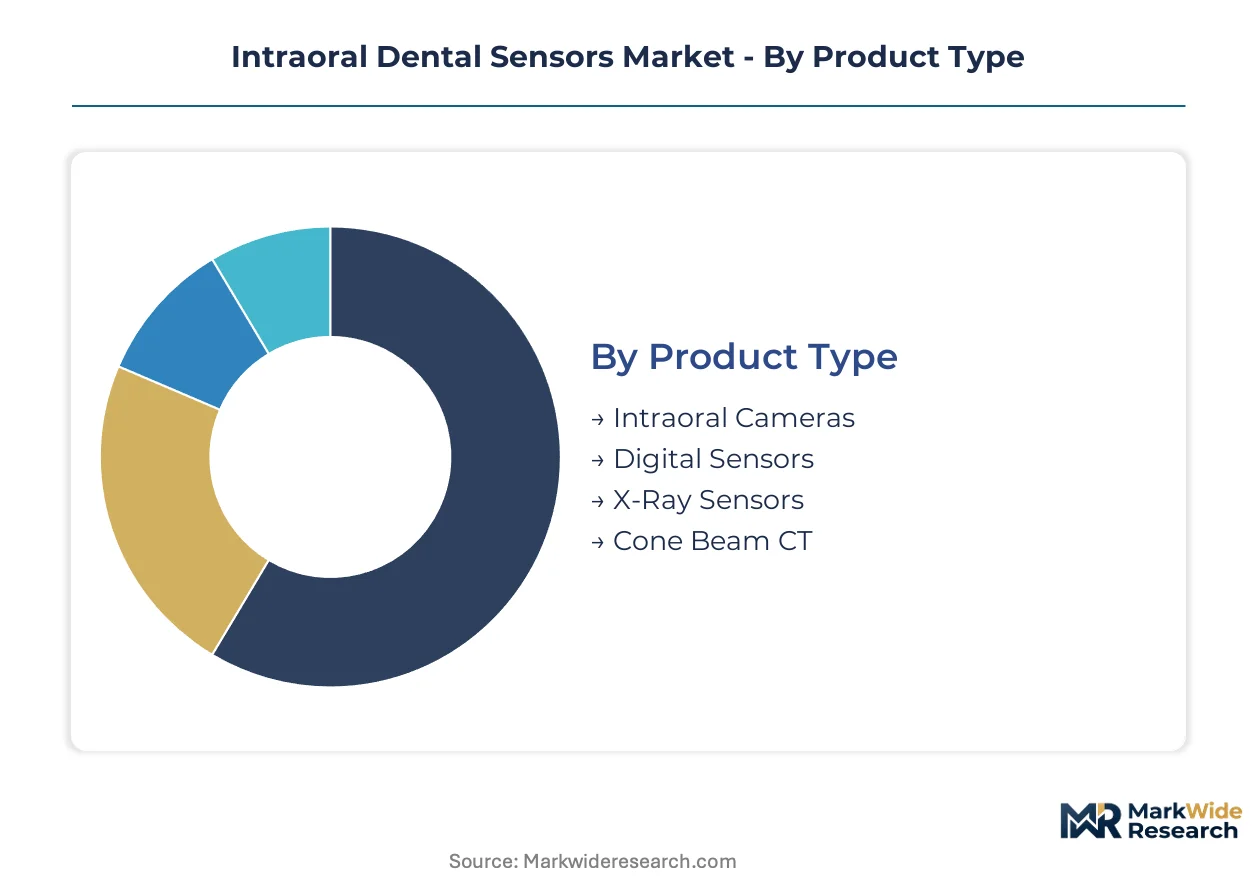
Segmentation in the intraoral dental sensors market reveals how technology substitution pressures and procurement consolidation reshape competitive priorities across hardware categories. Understanding these divisions exposes where CMOS displacement of legacy architectures concentrates margin pressure and where service bundling creates defensible revenue streams.
Product Type:
Digital Sensors face the most acute substitution threat from multifunctional imaging platforms, while legacy X-Ray Sensors confront accelerating CMOS-based displacement across clinic procurement cycles.
- Digital Sensors:Solid-state CMOS or CCD photodetector arrays on ceramic substrates convert X-ray energy directly into digital images with spatial resolutions exceeding 20 line pairs per millimeter. Demand concentrates in United States dental service organizations modernizing fleets under CMS reimbursement realignment favoring radiographic diagnostics over film-based alternatives.
- Intraoral Cameras:Optical capture devices employing LED illumination and CMOS image sensors document surface conditions, restorations, and soft-tissue pathology for patient communication and insurance documentation. German and Japanese dental clinics specify these for patient education workflows, though convergence with radiographic functions threatens standalone procurement volumes in premium segments.
- X-Ray Sensors:Legacy analog-to-digital conversion hardware bridging film-based radiography with practice management software, now relegated to cost-sensitive replacement cycles in smaller private practices.
- Cone Beam CT:Volumetric imaging systems generating three-dimensional reconstructions of maxillofacial anatomy for implant planning and endodontic assessment, concentrated in hospital-based dentistry and research institutions with capital equipment budgets.
Digital Sensors retain volume leadership; Cone Beam CT holds the steepest expansion curve among capital-intensive configurations.
End User:
Procurement concentration among consolidated dental service organizations creates tiered demand patterns where fleet standardization contracts override individual clinic preferences.
- Dental Clinics:Independent and group practice settings performing routine restorative, periodontal, and diagnostic procedures, representing the dominant channel for CMOS sensor procurement. Brazil's municipal SUS modernization programs and Texas DSO networks drive volume through standardized digital imaging mandates.
- Hospitals:Academic medical centers and community hospital dental departments integrating imaging with surgical suites and emergency departments, prioritizing interoperability with enterprise radiology information systems.
- Research Institutions:Universities and clinical trial centers requiring calibrated, reproducible imaging for longitudinal studies and device validation protocols.
- Private Practices:Solo practitioner settings with legacy equipment amortization cycles and limited capital reserves, delaying CMOS migration until reimbursement differentials force conversion.
Dental Clinics command procurement volume; Hospitals demonstrate the most rapid technology refresh rates as enterprise integration requirements accelerate replacement cycles.
Technology:
Semiconductor architecture choices determine manufacturing cost curves and resolution performance ceilings, with foundry scale economies concentrating advantage among vertically integrated producers.
- CMOS:Active-pixel sensor technology employing in-pixel amplification and on-chip analog-to-digital conversion, delivering lower power consumption and reduced per-unit production costs through Taiwan and South Korean foundry scale. German and Japanese clinic chains now specify CMOS-native systems exclusively for fleet standardization.
- CCD:Charge-coupled device architectures with superior dynamic range but higher power requirements and fabrication complexity, now relegated to niche applications requiring extreme low-light sensitivity.
- Ceramic-Based:Scintillator-substrate combinations employing rare-earth phosphors deposited on structured ceramics for indirect conversion applications in specialized high-dose imaging.
- Hybrid:Mixed-signal architectures combining CMOS readout circuits with optimized scintillator layers for specific wavelength conversion efficiencies.
CMOS technology captures procurement volume leadership; Hybrid configurations pursue the most aggressive expansion trajectory as manufacturers optimize layer-stack performance for specific clinical indications.
Application:
Software integration requirements and AI diagnostic overlay capabilities increasingly differentiate application segments, triggering new software-as-medical-device classifications across FDA and EU MDR jurisdictions.
- Diagnostics:Caries detection, periodontal assessment, and periapical pathology identification using standardized exposure protocols and calibrated grayscale rendering. United States clinics deploy these under expanded Medicare Advantage radiographic coverage.
- Treatment Planning:Preoperative imaging for implant positioning, endodontic access, and orthodontic appliance design requiring measurement accuracy and cross-sectional reconstruction.
- Patient Education:Chairside visualization of conditions and proposed interventions to secure informed consent and case acceptance, concentrated in cosmetic and elective procedure practices.
- Imaging:General radiographic documentation for insurance claims, legal records, and referral communication with minimal diagnostic interpretation requirements.
Diagnostics dominates current procurement volume; Treatment Planning applications expand most quickly as implant dentistry and guided surgery protocols proliferate through dental service organization standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement realignment in the United States accelerates digital sensor procurement as Medicare Advantage plans expand radiographic diagnostic coverage. European CE marking under MDR extends conformity timelines, favoring manufacturers with established notified body relationships. Japanese PMDA electromagnetic compatibility requirements shape regional product configurations.
United States
Dental service organizations in Texas and Florida drive fleet-standardization contracts bundling hardware, calibration, and software updates into per-procedure fee structures. FDA 510(k) clearance timelines govern market entry for new sensor platforms incorporating AI diagnostic overlays. Greater Boston hosts research institutions validating algorithm performance across diverse patient demographics for software-as-medical-device classifications.
Germany
CMOS-native systems now dominate procurement specifications from clinic chains modernizing imaging fleets under statutory health insurance digitization mandates. EU MDR technical documentation requirements extend conformity assessment periods, creating first-mover advantages for manufacturers with captive semiconductor foundry relationships. Bavaria concentrates precision manufacturing clusters supplying ceramic substrate feedstock for high-resolution sensor fabrication.
Japan
PMDA electromagnetic compatibility and radiation safety testing extends market entry timelines by 8-14 months for non-domestic manufacturers, shaping product configuration strategies. METI industrial policy supports domestic sensor fabrication through semiconductor supply chain resilience initiatives. Kansai region dental clinics specify CMOS-native systems exclusively for patient education workflows integrating chairside visualization.
Brazil
SUS digital dentistry initiative public health modernization programs create tender opportunities for cost-optimized CMOS sensor configurations in municipal clinics. ANVISA medical device registration requirements govern importation and distribution of foreign-manufactured imaging hardware. São Paulo state dental service organizations concentrate demand for fleet-standardization contracts favoring vendors with remote calibration capabilities.
South Korea
MFDS electromagnetic compatibility and radiation safety certification shapes regional product configuration strategies for sensor platforms targeting domestic and export markets. Semiconductor foundry scale economies in Taiwan and South Korean fabrication facilities reduce per-pixel production costs for CMOS photodetector arrays. Seoul Capital Area dental clinics drive procurement volume for mid-tier sensor configurations as reimbursement frameworks favor digital over film-based alternatives.
Intraoral Dental Sensors Market Competitive Landscape
Player mix skews toward vertically integrated multinational manufacturers with captive semiconductor supply chains and dense field service networks. The vendor base concentrates around three strategic archetypes: premium-tier incumbents with proprietary imaging software ecosystems, mid-cap specialists leveraging foundry partnerships for CMOS cost optimization, and regional assemblers serving cost-sensitive public health tenders. Dominant competitive moves include M&A-driven portfolio diversification into AI diagnostic software and geographic expansion through dental service organization fleet-standardization contracts.
Among North American and European incumbents, Dentsply Sirona and Carestream Dental exemplify the premium-tier archetype through vertically integrated manufacturing footprints and dense service networks across dental service organizations. Planmeca Oy occupies a position within the software-hardware integration specialist tier, differentiating through proprietary imaging software paired with hardware platforms. These three anchors demonstrate how established quality management systems and notified body relationships accelerate MDR certification to capture delayed competitor market entry.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Carestream Dental |
| Planmeca Oy |
| VATECH |
| DEXIS |
| Owandy Radiology |
| Acteon Group |
| FONA Dental |
| Midmark Corporation |
| Others |
Pricing and Supply Chain Analysis
CMOS photodetector arrays displacing legacy CCD architectures simultaneously concentrate semiconductor sourcing in Taiwan and South Korean foundries while compressing per-unit production costs. This substitution dynamic enables mid-tier dental service organizations to access premium-resolution imaging at standard-tier price points, reshaping procurement economics across United States and German clinic networks.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared platforms and economy-grade alternatives lacking ISO 13485 documentation. Three-tier pricing structure across premium, standard, and economy levels segments by after-sales service bundling and software integration depth. Cost compression in standard tiers intensifies because Taiwanese foundry scale economies flood mid-market CMOS supply. Independent private practices in Brazil demonstrate highest price sensitivity, while North American dental service organizations prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan port corridors fluctuate with container availability, adding unpredictability to ceramic substrate shipments from Japanese and German specialty glass suppliers. Manufacturing draws from Taiwan and South Korea for CMOS wafer fabrication, Japan and Germany for ceramic scintillator substrates, and China for cable assembly and housing components. Single-source vulnerability concentrates in high-purity rare-earth phosphor supply. Distribution runs through authorized dealer networks with field service technicians for calibration-dependent hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental service organization consolidation across Texas and Florida has shifted procurement leverage toward standardized fleet contracts, fragmenting vendor pricing power. This buyer-power concentration demands differentiated strategic responses across incumbent, entrant, and investor archetypes.
For Market Incumbents: Fortify notified body relationships to accelerate EU MDR certification timelines before competitors establish technical documentation libraries. Deepen backward integration into CMOS foundry partnerships to defend margin position against mid-cost specialists. Channel control through captive financing arms locks in dental service organization fleet-standardization contracts against software-hardware bundling threats.
For New Entrants and Emerging Players: Remote calibration service gaps among incumbent vendors create entry pathways for cloud-connected sensor platforms with automated quality assurance. Target Brazil's SUS municipal tender programs where cost-optimized CMOS configurations face limited domestic competition. Go-to-market leverage through dental equipment distributors with established ANVISA registration accelerates market access without direct regulatory burden.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap sensor specialists lacking AI diagnostic software capabilities. Long-term viability hinges on software-as-medical-device revenue streams recurring across hardware replacement cycles. Watch FDA software guidance evolution as inflection signal for AI-overlay classification risk and platform valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Extended conformity timelines favor incumbents with established notified body relationships in Germany. |
| AI Diagnostic Software Development | Algorithm validation for caries detection triggers software-as-medical-device recurring revenue streams. |
| Dental Service Organization Partnership | Fleet-standardization contracts in Texas and Florida lock in multi-year hardware-service bundles. |
| CMOS Foundry Supply Agreement | Taiwanese and South Korean wafer scale economies reduce per-pixel production costs for mid-tier sensors. |
| Remote Calibration Capability Buildout | Cloud-connected quality assurance differentiates service offerings for distributed clinic networks. |
Research Methodology
Operator-level perspectives from dental clinic procurement managers, biomedical equipment technicians, GPO contract specialists, and dental service organization operations directors anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, CMS reimbursement databases, EU MDR technical documentation libraries, and ANVISA registration records. Bottom-up sensor shipment estimates triangulated against top-down dental equipment expenditure models.
Sensitivity analysis tested forecast outputs against semiconductor foundry capacity expansion scenarios and reimbursement policy discontinuities. Segmentation dimensions modeled include technology architecture, end-user channel, application workflow, and regional regulatory cluster. CAGRs derived from unit volume trajectories and average selling price evolution across the projection horizon. CMOS wafer cost curves and dental service organization consolidation rates served as key forecast inputs.
Forecasts assume regulatory continuity in FDA, EU MDR, and PMDA regimes; material policy shifts would require re-modeling. Algorithm classification changes for AI diagnostic overlays and ceramic substrate supply disruptions represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Acrylic Teeth Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
China Dental Implants Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Digital Facebow Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Gingivitis Treatment Market