
 Mexico Digital Radiology Market | 2026-2036
Mexico Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Digital Radiology Market Foresight
Project finance and equipment leasing is narrowing the competitive gap between multinational vendors and regional service providers in Mexico's imaging sector. Siemens Healthineers leverages its installed base of MRI machines to sustain long-term service contracts across public hospital networks. GE Healthcare anchors its position through backward integration into refurbished equipment channels that serve cost-sensitive clinics in secondary cities. FUJIFILM competes by specializing in compact digital X-ray systems tailored for high-volume outpatient settings.
Digital radiology encompasses the acquisition, processing, storage, and transmission of diagnostic images using electronic detectors and picture archiving systems, with spatial resolution typically exceeding 2.5 line pairs per millimeter in modern flat-panel detectors. Its primary purpose is to replace analog film-based workflows with real-time, network-distributed imaging that supports faster clinical decision-making and remote consultation. CT scanners command the largest capital allocation among product types due to their indispensability in trauma and oncology staging protocols. Direct Radiography technology leads technology segment growth as hospitals retire computed radiography cassettes in favor of cassette-less detector panels. Diagnostic centers represent the fastest-expanding end-user channel, driven by physician-entrepreneurs establishing independent imaging facilities in underserved metropolitan zones.
COFEPRIS, Mexico's national health regulator, enforces medical device registration under NOM-240 standards that mandate clinical evidence for Class III imaging equipment, creating compliance barriers for new market entrants. The Secretariat of Health's INSABI procurement frameworks shape demand concentration by centralizing tenders for public hospital radiology upgrades, while ISO 13485 certification requirements filter out uncertified component suppliers. Stakeholders must monitor whether domestic assembly incentives in the federal medical device manufacturing program redirect capital toward local production of digital detector panels versus continued import dependence.
Market Dynamics
Hospital procurement centralization under INSABI frameworks is consolidating purchasing power across Mexico's public health network, compressing vendor margins while accelerating equipment standardization in tertiary care facilities.
Growth Catalysts
- INSABI tender centralization:Federal procurement frameworks aggregate radiology equipment demand from state hospital networks, creating volume incentives for manufacturers to establish domestic service infrastructure.
- Computed radiography retirement:Public hospitals are systematically replacing cassette-based systems with direct radiography panels, generating replacement demand across existing installed bases.
- Cardiology referral concentration:Diagnostic centers in Mexico City and Guadalajara are expanding cardiac CT and MRI capacity to capture patient flows from private cardiology practices.
Market Restraints
- COFEPRIS Class III registration timelines:Clinical evidence requirements for high-risk imaging equipment extend approval cycles, delaying market entry for novel detector technologies.
- Import dependency for flat-panel detectors:Domestic manufacturing capacity for amorphous silicon detector substrates remains undeveloped, exposing procurement costs to currency volatility and shipping constraints.
- Specialized biomedical engineering scarcity:Training pipelines for MRI and CT service technicians lag equipment deployment rates, constraining uptime guarantees in secondary cities.
Strategic Opportunities
- Monterrey manufacturing zone:Federal medical device production incentives are positioning Nuevo León for assembly operations, potentially reducing import duties on finished digital radiology systems.
- Mobile imaging unit deployment:Trailer-mounted CT and X-ray systems are penetrating rural municipalities underserved by fixed diagnostic infrastructure, creating new channel economics.
- Artificial intelligence integration:FDA-cleared and CE-marked radiology AI tools are entering Mexican private networks through distributor partnerships, enabling workflow automation in high-volume screening programs.
Industry Challenges
- DICOM-PACS interoperability gaps:Legacy hospital information systems in regional public facilities require costly middleware development to integrate with modern imaging archives.
- ISO 13485 certification bottlenecks:Domestic component suppliers face extended audit timelines, limiting their qualification for multinational OEM supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Digital Radiology Market |
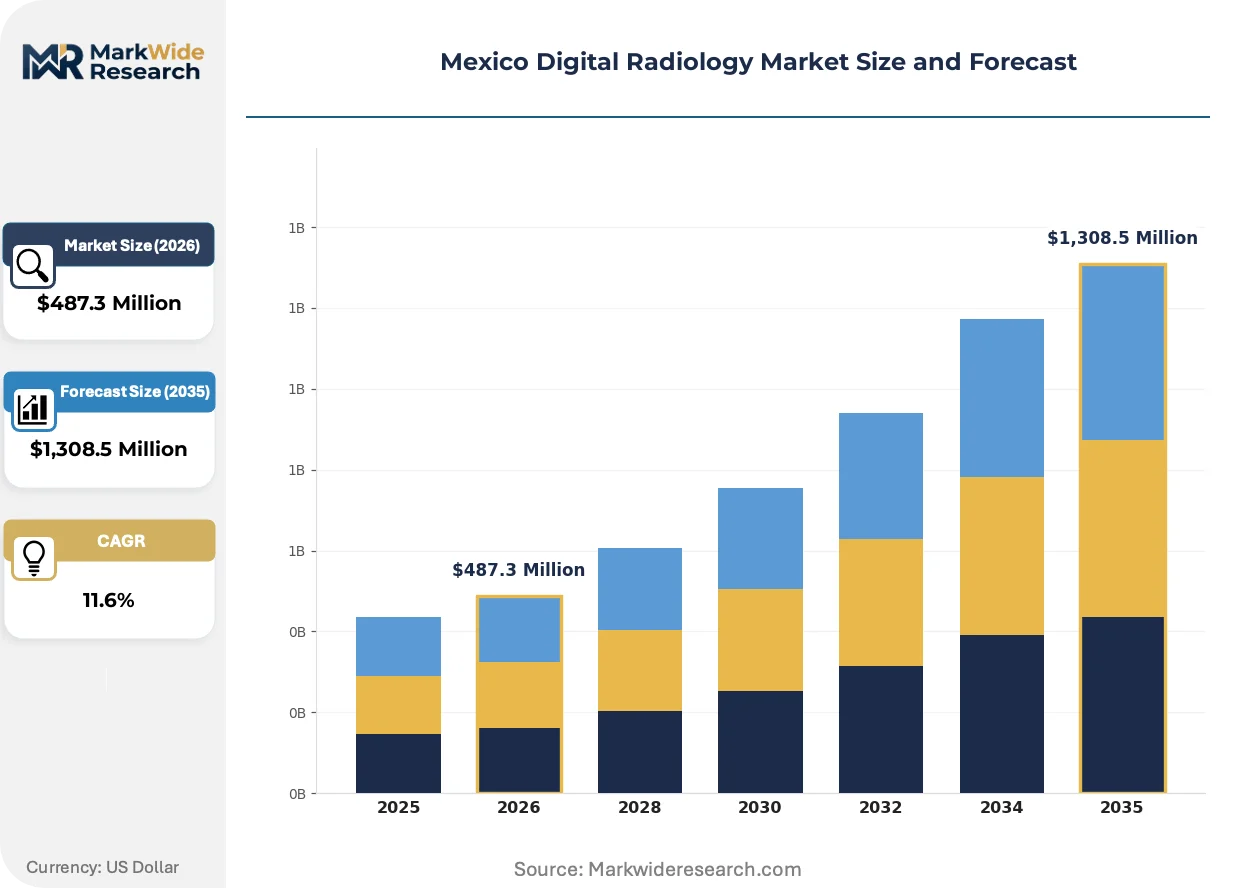
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, MRI Machines, CT Scanners, Ultrasound Devices End User: Hospitals, Clinics, Diagnostic Centers, Research Institutes Technology: Direct Radiography, Computed Radiography, Mobile Radiography, PACS Application: Oncology, Orthopedics, Cardiology, Pediatrics |
| Companies Covered | Siemens Healthineers, GE Healthcare, FUJIFILM, Canon Medical Systems, Carestream Health, Koninklijke Philips, Agfa Healthcare, Hologic, Hitachi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Digital Radiology Market Shifts & Advancements
Artificial intelligence workflow integration and detector material advances are compressing examination times while expanding the clinical utility of point-of-care imaging across Mexican healthcare networks.
Photon-counting CT detector technology is hybridizing spectral imaging capabilities with conventional anatomical scanning, enabling simultaneous material decomposition and high-resolution structural assessment. Private oncology centers in Mexico City are piloting these systems for chemotherapy response monitoring. The convergence is compressing the competitive window for conventional energy-integrating detectors in premium hospital segments.
COFEPRIS alignment with FDA breakthrough device designation pathways is accelerating conditional approvals for AI-assisted diagnostic software, reducing pre-market evidence requirements for algorithms targeting specific pathologies. Radiology groups are responding by establishing clinical validation partnerships with software vendors prior to regulatory submission. Diagnostic chains with centralized quality control infrastructure capture disproportionate benefit from streamlined registration.
Independent diagnostic entrepreneurs are consolidating previously fragmented outpatient imaging capacity into multi-modality centers, displacing single-machine clinic economics. Physician-investors in Guadalajara and Puebla are pooling capital to acquire MRI and CT assets, then contracting directly with private insurers for bundled episode payments. This concentration is most visible in metropolitan zones where specialist referral density supports volume guarantees.
Mexico Digital Radiology Market Segmentation
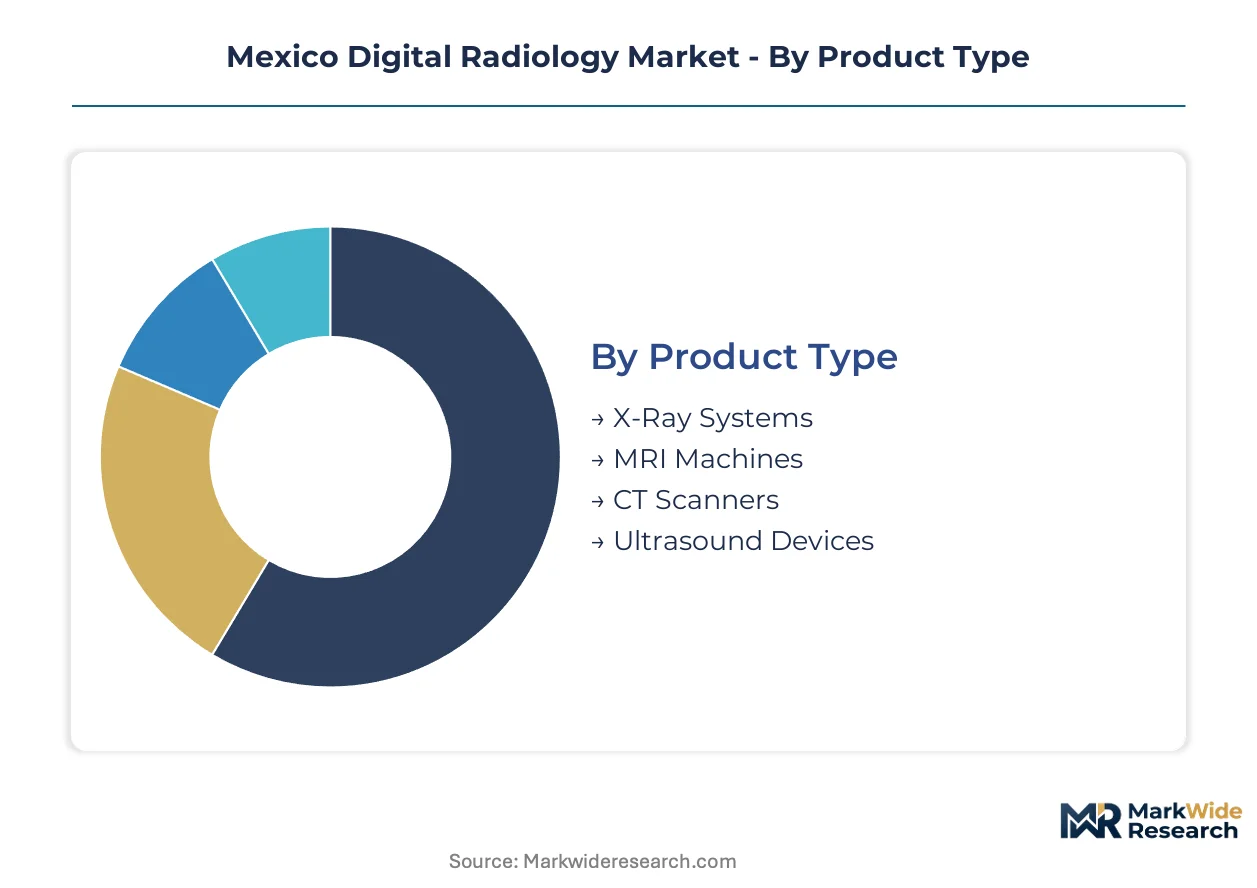
Segmentation in Mexico's digital radiology market reveals distinct service intensity patterns across equipment categories. Each segment demands specialized technical support infrastructure that shapes vendor profitability and customer retention strategies.
Product Type:
After-sales service intensity varies dramatically across imaging modalities, with MRI and CT systems requiring dedicated field engineering teams while X-ray platforms sustain leaner support models.
- CT Scanners:Multi-detector arrays with 64-slice to 256-slice configurations generate the highest service contract attach rates in Mexican hospital networks. Public sector procurement under INSABI frameworks concentrates demand in Mexico City and Monterrey tertiary facilities, where uptime guarantees drive 15-year total cost of ownership calculations.
- MRI Machines:Superconducting magnet systems operating at 1.5T and 3.0T field strengths command premium service margins through cryogen management and coil replacement programs. Guadalajara's private cardiology groups are expanding MRI capacity to capture direct-to-patient diagnostic workflows.
- X-Ray Systems:Fixed and portable configurations with flat-panel detectors dominate unit volume in cost-sensitive clinic segments.
- Ultrasound Devices:Cart-based and handheld systems serve point-of-care expansion in maternal health programs.
CT Scanners holds the largest share; momentum sits with MRI Machines.
End User:
Customer type determines procurement authority structures, with centralized hospital networks negotiating enterprise contracts while independent diagnostic centers prioritize financing flexibility.
- Diagnostic Centers:Physician-entrepreneur facilities in Mexico City, Guadalajara, and Puebla aggregate multi-modality capacity to contract directly with private insurers. These independent operators are expanding most quickly as bundled episode payment models mature in metropolitan zones.
- Hospitals:Public network centralization under INSABI tenders compresses capital equipment margins while standardizing imaging protocols across state health systems. Tertiary facilities in Monterrey anchor regional referral patterns.
- Clinics:Secondary city outpatient facilities prioritize refurbished equipment channels and mobile imaging partnerships.
- Research Institutes:Academic medical centers in Mexico City drive early adoption of photon-counting CT and AI-assisted reconstruction algorithms.
Hospitals retains dominant procurement volume; Diagnostic Centers are gaining share fastest.
Technology:
Technology maturity curves determine replacement cycle timing, with cassette-based systems approaching end-of-life retirement while detector material advances reshape premium segments.
- Direct Radiography:Amorphous silicon and cesium iodide scintillator panels eliminate chemical processing workflows while delivering sub-millimeter spatial resolution. Public hospital replacement programs across central Mexico are accelerating cassette-to-detector conversions.
- PACS:Vendor-neutral archive architectures with cloud redundancy are penetrating mid-tier diagnostic chains as DICOM interoperability standards mature.
- Computed Radiography:Cassette-based phosphor plate systems face systematic retirement as DR panel costs decline.
- Mobile Radiography:Battery-powered detector panels mounted on motorized drives serve ICU and emergency department workflows.
Computed Radiography retains installed base dominance; Direct Radiography shows the steepest expansion trajectory.
Application:
Clinical use case specialization shapes equipment configuration requirements, with oncology and cardiology demanding spectral imaging capabilities while orthopedics prioritizes throughput volume.
- Oncology:Staging protocols require contrast-enhanced CT and multiparametric MRI with diffusion-weighted imaging sequences. Private cancer centers in Mexico City are piloting photon-counting detectors for chemotherapy response assessment.
- Cardiology:Cardiac CT angiography and stress MRI protocols drive 256-slice CT and 1.5T MRI procurement in Guadalajara specialist networks.
- Orthopedics:Weight-bearing X-ray and musculoskeletal MRI configurations serve trauma and sports medicine volumes.
- Pediatrics:Low-dose CT protocols and size-appropriate coil designs address radiation exposure minimization requirements.
Oncology commands premium equipment allocation; Cardiology demonstrates the strongest volume growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal medical device manufacturing incentives are redirecting capital toward Nuevo León assembly operations while INSABI procurement centralization reshapes demand geography across Mexican metropolitan zones.
Mexico City Metro
Public hospital networks under INSABI tender frameworks concentrate CT and MRI procurement in tertiary facilities serving 22 million metropolitan residents. COFEPRIS Class III registration requirements filter equipment imports through established distributor channels. The Tlalpan and Cuauhtémoc hospital clusters anchor regional referral patterns for oncology and cardiology imaging protocols.
Nuevo León
Monterrey's manufacturing corridor attracts assembly investment through federal medical device production incentives targeting amorphous silicon detector panel operations. The state's industrial infrastructure supports component suppliers seeking ISO 13485 certification for multinational OEM qualification. Apodaca and Santa Catarina industrial parks host emerging domestic production facilities.
Jalisco
Guadalajara's private cardiology groups drive MRI capacity expansion to capture direct-to-patient diagnostic workflows from specialist referral networks. Physician-entrepreneurs consolidate outpatient imaging capacity into multi-modality centers contracting with private insurers. The metropolitan zone's diagnostic center density exceeds national averages by significant margins.
Bajío Region
Querétaro and Guanajuato industrial corridors leverage automotive electronics expertise to diversify into medical device component supply. Mobile imaging units penetrate rural municipalities underserved by fixed diagnostic infrastructure. León and Irapuato serve as distribution hubs for refurbished equipment channels reaching secondary city clinics.
Northern Border States
Baja California and Chihuahua maquiladora operations facilitate cross-border service logistics for US-based imaging equipment manufacturers. Tijuana medical device parks specialize in detector panel assembly and calibration operations. Ciudad Juárez hosts refurbishment facilities serving cost-sensitive clinic segments across northern Mexico.
Mexico Digital Radiology Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Mexico's imaging sector, creating a tiered structure where service infrastructure depth separates sustained performers from transactional vendors. Siemens Healthineers leverages installed base scale to sustain long-term service contracts across public hospital networks. GE Healthcare anchors position through backward integration into refurbished equipment channels serving secondary cities. Three archetypes dominate: full-system multinationals, refurbished equipment specialists, and compact-system niche players. Competitive moves concentrate on financing flexibility expansion and AI software partnership formation.
Among full-system multinationals, Siemens Healthineers and GE Healthcare exemplify the service-contract archetype, anchoring long-term relationships through cryogen management and uptime guarantee programs. FUJIFILM occupies a position within the compact-system specialization tier, representing the outpatient-focused configuration strategy. These three entities collectively illustrate how vendor positioning maps to end-user procurement authority structures across Mexico's centralized public networks and fragmented private diagnostic channels.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| FUJIFILM |
| Canon Medical Systems |
| Carestream Health |
| Koninklijke Philips |
| Agfa Healthcare |
| Hologic |
| Hitachi |
| Others |
Supply & Pricing Matrix
Amorphous silicon detector substrate manufacturing concentrates in South Korea and Japan, anchoring margin capture upstream while Mexican distributors and service providers compete on financing terms and installation speed downstream. This geographic concentration of critical component supply creates pricing power asymmetries that equipment assemblers in Nuevo León must navigate through tariff engineering and inventory positioning.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared systems and economy-tier alternatives lacking international accreditation. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 compliance status, after-sales service bundling, and cryogen management inclusion. Cost compression in the standard tier is intensifying because INSABI tender centralization aggregates purchasing power and compresses vendor margins. Secondary city clinics exhibit highest price sensitivity, while tertiary hospital networks in Mexico City prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Contract manufacturing for detector panel assembly concentrates in Tijuana maquiladora operations and Apodaca industrial parks, with calibration and testing distributed across Monterrey facilities. Finished systems draw from amorphous silicon substrates sourced in South Korea, Japan, and Taiwan, plus rare earth magnet materials for MRI superconducting coils. Single-source vulnerability in flat-panel detector supply exposes procurement timelines to shipping constraints and currency volatility. Distribution runs through authorized distributor networks holding COFEPRIS import licenses, with direct-to-hospital contracting emerging in large INSABI tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's digital radiology sector is approaching a platform-economics inflection as DICOM-PACS interoperability standards mature and AI-assisted diagnostic tools create new layer-cake revenue models. Vendor-neutral archive architectures are displacing proprietary imaging networks, forcing equipment manufacturers to compete on software integration depth rather than hardware specifications alone.
For Market Incumbents: Pre-empt service contract erosion by embedding AI workflow tools into existing MRI and CT installed bases before independent software vendors capture the diagnostic layer. Cryogen management and coil replacement programs anchor long-term relationships, yet photon-counting CT pilots in Mexico City private oncology centers threaten conventional energy-integrating detector margins. Backward integration into refurbished equipment channels defends position in cost-sensitive secondary city segments.
For New Entrants and Emerging Players: Pursue mobile imaging unit deployment in rural municipalities of the Bajío Region and northern border states, where fixed diagnostic infrastructure remains underserved. Trailer-mounted CT and X-ray systems penetrate municipalities outside the Mexico City-Guadalajara-Monterrey triangle with minimal incumbent competition. Direct contracting with state health departments bypasses INSABI tender complexity for smaller equipment footprints.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with physician-entrepreneur diagnostic chains in Guadalajara and Puebla that have consolidated multi-modality capacity but lack capital for AI software partnerships. Long-term viability hinges on whether these independent operators can secure bundled episode payment contracts with private insurers before hospital networks centralize outpatient imaging. Monitor COFEPRIS conditional approval velocity for AI-assisted diagnostic software as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Class III Registration Acceleration | Streamlined pathways for AI-assisted algorithms reduce pre-market evidence burdens for diagnostic software vendors targeting Mexican private networks. |
| Domestic Detector Panel Assembly | Nuevo León federal incentives position local manufacturing to capture value from amorphous silicon substrate imports while reducing finished system duties. |
| Hospital System Partnership Formation | INSABI tender centralization rewards vendors with established service infrastructure across Mexico City, Monterrey, and Guadalajara tertiary networks. |
| Software Companion Development | FDA-cleared and CE-marked radiology AI tools enter through distributor partnerships, enabling workflow automation in high-volume screening programs. |
| Reimbursement Strategy Alignment | Diagnostic centers contracting directly with private insurers for bundled episode payments require equipment configurations supporting episode-based clinical protocols. |
Research Methodology
A standing panel of hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and COFEPRIS regulatory consultants provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against hospital procurement databases, GPO contract filings, and INSABI tender documentation. Bottom-up equipment shipment analysis triangulated against top-down healthcare infrastructure spending estimates to anchor market sizing.
Scenario-bracketing framed analytical approaches across the projection horizon, with base, optimistic, and conservative cases reflecting differential assumptions about INSABI centralization pace and domestic manufacturing incentive uptake. Segmentation dimensions modeled include product modality, end-user procurement authority structure, technology maturity tier, and clinical application specialization. CAGRs derived from equipment replacement cycle analysis and public health infrastructure budget trajectories, with photon-counting CT adoption curves and AI software penetration rates serving as industry-specific forecast inputs.
Sensitivities concentrate around COFEPRIS registration timeline revisions, currency volatility effects on import-dependent detector procurement, and INSABI tender participation thresholds that could reshape vendor competitive dynamics. Forecasts reflect documented assumptions regarding public health infrastructure modernization pace and private diagnostic center consolidation momentum. Quarterly review of INSABI tender award patterns and COFEPRIS conditional approval grants is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
Canada Mammography Market
Medical Imaging
United Kingdom Nuclear Imaging Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
South America CT Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
France Mammography Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Cephalometric X-Ray System Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Europe Nuclear Imaging Market
Medical Imaging
Quantitative Pathology Imaging Market