
 Global Dental Panoramic Radiography Market | 2026-2036
Global Dental Panoramic Radiography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Panoramic Radiography Market Intelligence
Radiological technologist shortages across developed markets is rotating investment toward automated positioning and AI-assisted image capture. Planmeca Oy leverages its Nordic manufacturing base to sustain premium positioning in digital panoramic systems. Dentsply Sirona anchors North American distribution through its integrated dental workflow platform. J. Morita Corporation dominates Asian markets with localized service networks and region-specific regulatory registrations.
Dental panoramic radiography denotes extraoral imaging systems that rotate an X-ray source and detector around a patient's head to produce a two-dimensional tomographic slice of the entire maxillofacial region, typically operating at 60-90 kVp tube voltage with exposure times under 20 seconds. These systems serve primary diagnostic screening, orthodontic treatment planning, and pre-surgical assessment in dental practices. Digital panoramic X-ray equipment leads installed base expansion due to immediate image availability and reduced radiation dose compared with analog predecessors, while 3D imaging capabilities embedded within hybrid panoramic-CT systems command the fastest growth trajectory and highest margin pools. Dental clinics represent the most mature end-user channel with replacement-driven demand, whereas orthodontic centers are emerging as the highest-growth segment fueled by adolescent treatment volume and aligner therapy planning requirements.
FDA 510(k) premarket notification and EU MDR Class IIa certification govern commercial access for panoramic radiography systems in the United States and European markets, with ISO 13485 quality management serving as the baseline for multinational manufacturers. Japan's PMDA and South Korea's MFDS impose additional country-specific electromagnetic compatibility and radiation safety testing that extends registration timelines for new entrants. Stakeholders must monitor convergence between conventional panoramic imaging and cone-beam computed tomography as equipment purchasing committees recalibrate capital allocation toward multifunctional platforms.
Market Dynamics
The convergence of panoramic radiography with cone-beam computed tomography is compressing capital equipment purchasing cycles as dental practices consolidate imaging modalities onto single platforms rather than maintaining separate devices.
Growth Catalysts
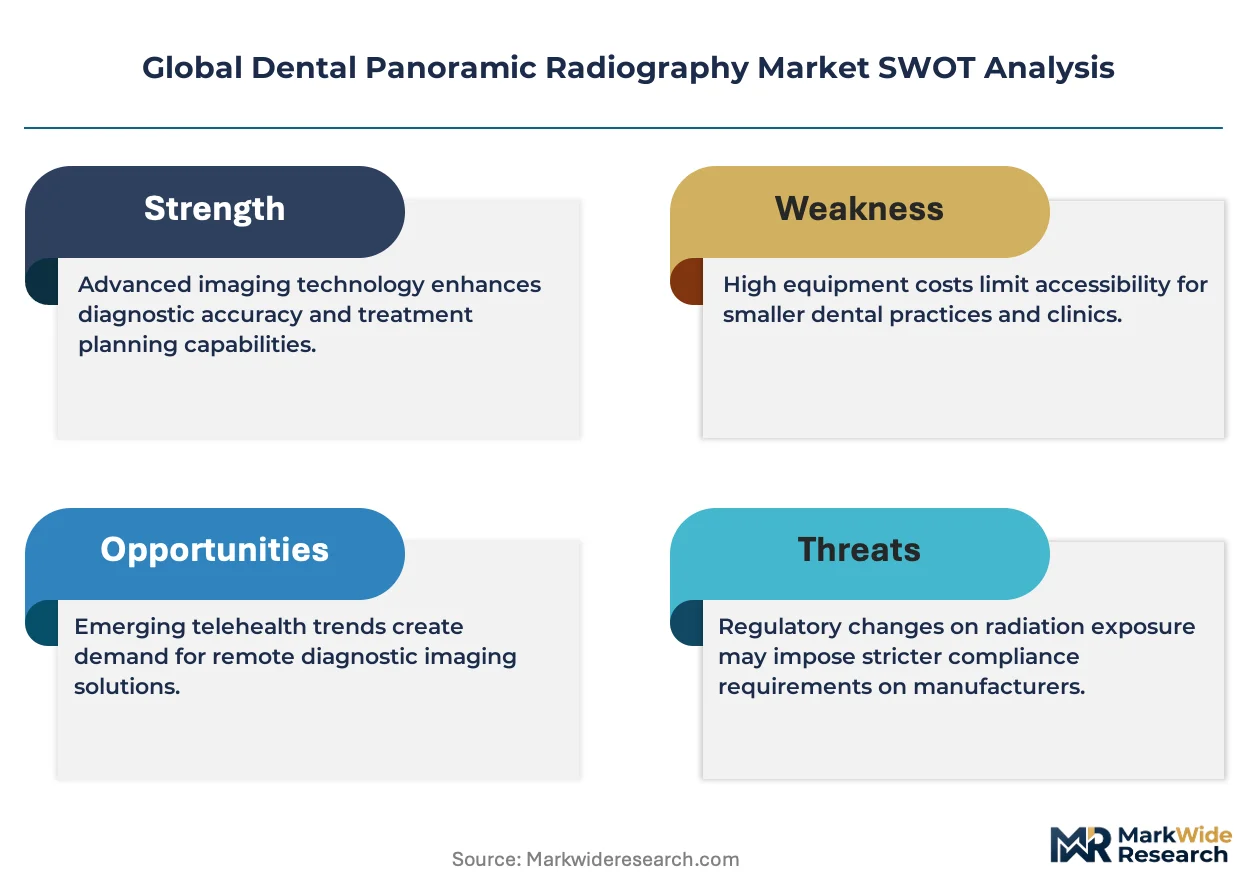
- EU MDR Class IIa Certification:Harmonized quality benchmarks across European markets reduce duplicate testing costs for manufacturers and accelerate cross-border commercialization.
- Orthodontic Treatment Planning:Adolescent aligner therapy volume drives cephalometric imaging demand, particularly in Germany and Japan where orthodontic specialist density is highest.
- Automated Patient Positioning:AI-assisted image capture mitigates radiological technologist shortages in the United States and reduces retake rates.
Market Restraints
- High-Voltage Tube Replacement Cycles:X-ray source degradation at 60-90 kVp operating parameters creates recurring maintenance cost burdens for clinic operators.
- MFDS Electromagnetic Testing:South Korea's radiation safety protocols extend registration timelines by 8-14 months for new market entrants.
- Hybrid CBCT Substitution:Multifunctional platforms with 3D reconstruction capabilities cannibalize standalone panoramic system demand in premium-tier purchasing.
Strategic Opportunities
- India's Dental Infrastructure Modernization:CDSCO streamlined medical device registration creates entry pathways for digital panoramic systems in tier-2 cities.
- Tele-diagnostics Integration:Cloud-based image sharing enables remote orthodontic consultation workflows, opening subscription revenue models.
- ISO 13485 Alignment:Quality management standardization supports manufacturer expansion into Middle Eastern markets lacking domestic production.
Industry Challenges
- Radiation Dosimetry Expertise Gap:Clinic staff training on ALARA principles lags behind equipment sophistication, exposing practices to liability risk.
- Legacy Analog System Interoperability:Film-based archive migration to DICOM standards requires capital outlay that delays digital upgrade decisions.
- PMDA Localization Requirements:Japan's service network mandates impose operational overhead on foreign manufacturers seeking national distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Panoramic Radiography Market |
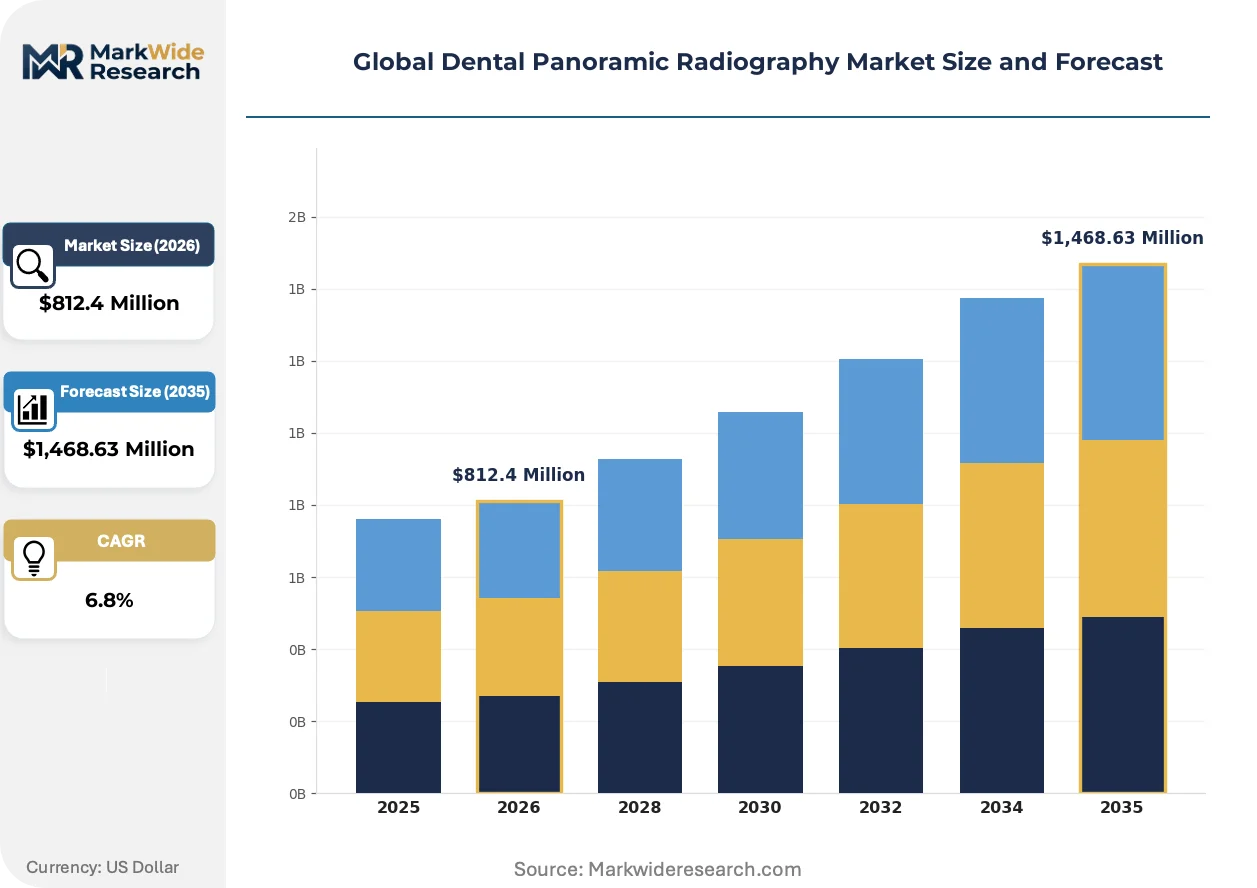
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,468.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cephalometric X-ray, Digital Panoramic X-ray, Analog Panoramic X-ray, Hybrid Panoramic X-ray End User: Dental Clinics, Hospitals, Orthodontic Centers, Research Institutions Technology: Computed Tomography, Ultrasound, Conventional Radiography, 3D Imaging Application: Diagnosis, Treatment Planning, Oral Surgery, Dental Education |
| Companies Covered | Envista Holdings Corporation, DÜRR DENTAL SE, Dentsply Sirona, J. Morita Corporation, Carestream Dental, Planmeca Oy, Acteon, Owandy Radiology, VATECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Panoramic Radiography Market Strategic Shifts & Innovations
Artificial intelligence is penetrating image acquisition workflows, reducing operator dependency while regulatory frameworks tighten radiation safety verification protocols across major commercial jurisdictions.
Direct-conversion CMOS sensors are decomposing the market for indirect scintillator-based detectors in panoramic radiography. Orthodontic centers in Germany and Japan are adopting these sensors at twice the rate of general dental clinics. The technology is decomposing price premiums previously commanded by premium-tier equipment manufacturers.
EU MDR post-market surveillance requirements now mandate systematic clinical follow-up data for Class IIa imaging devices. Manufacturers must establish periodic safety update reports that track device performance across installed bases. Panoramic system vendors with limited European clinical footprint face disproportionate compliance cost burdens relative to incumbents with established vigilance infrastructure.
After-sales service unbundling is emerging as a procurement pattern among large dental group practices. Equipment purchasers in the United States increasingly separate hardware acquisition from maintenance contracts, pressuring OEM service margin structures. Independent service organizations are capturing calibration and tube replacement volumes previously retained by manufacturers.
Global Dental Panoramic Radiography Market Segmentation
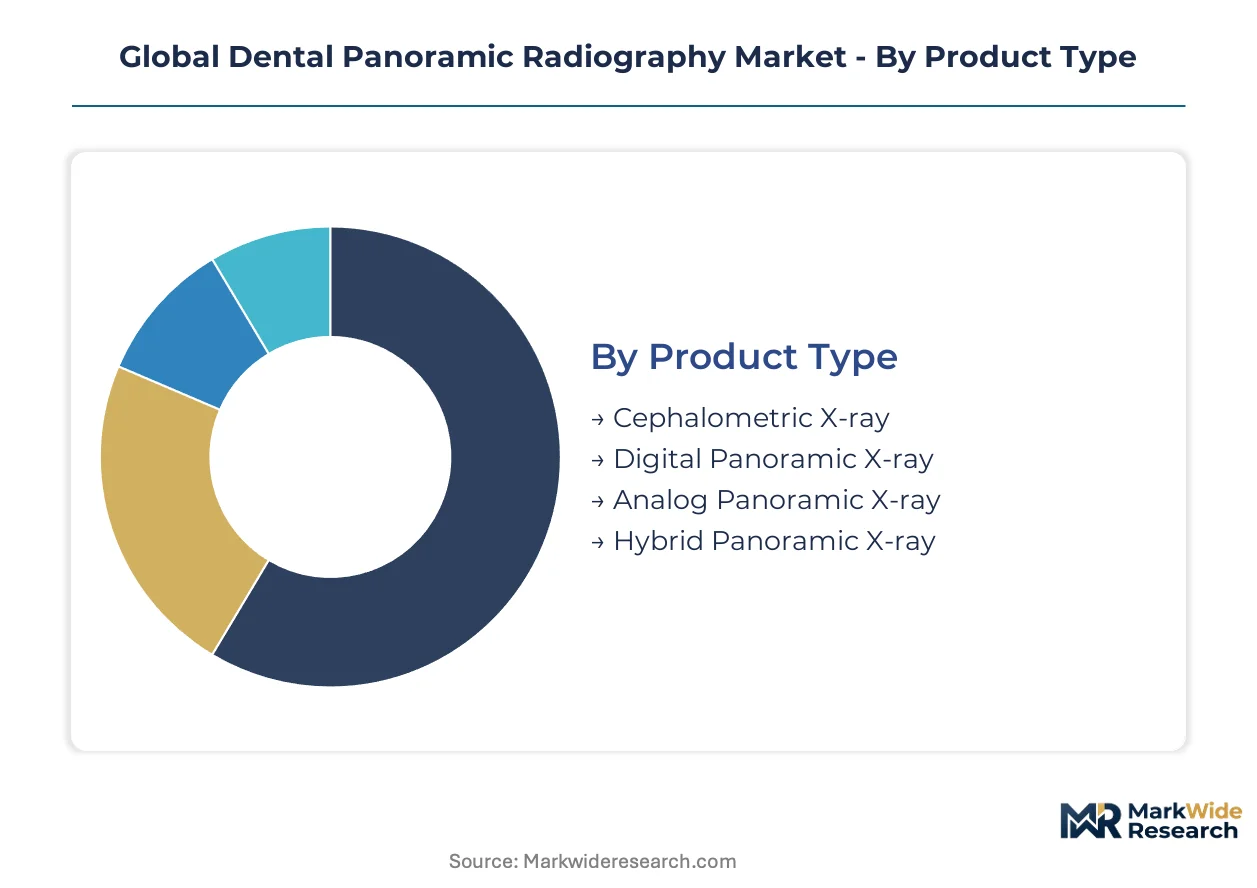
Segmentation in dental panoramic radiography reveals how equipment specifications align with distinct clinical workflows and capital constraints. Product configurations, end-user settings, and imaging modalities each command separate procurement channels and service ecosystems.
Product Type:
Digital systems flow through dental distributors with integrated software packages, while analog and hybrid units reach price-sensitive buyers through secondary equipment channels.
- Digital Panoramic X-ray:Direct-conversion CMOS sensors capture maxillofacial anatomy at 60-90 kVp with immediate DICOM output. Demand concentrates in orthodontic centers across Germany and Japan where aligner therapy planning requires cephalometric precision and rapid image turnaround.
- Hybrid Panoramic X-ray:Embedded cone-beam CT capability consolidates 2D panoramic and 3D volumetric imaging on single platforms. Dental group practices in the United States favor these systems to reduce per-clinic equipment counts and unify maintenance contracts under single vendors.
- Cephalometric X-ray:Specialized lateral skull projection systems serve orthodontic analysis with standardized magnification ratios.
- Analog Panoramic X-ray:Film-based systems persist in emerging markets with limited digital infrastructure and lower electricity reliability.
By volume, Digital Panoramic X-ray leads installed base expansion. By growth pace, Hybrid Panoramic X-ray is gaining share fastest as practices consolidate imaging modalities.
End User:
Procurement authority varies sharply across settings, with hospitals running centralized capital committees and dental clinics making owner-operator purchase decisions.
- Dental Clinics:Independent and small-group practices drive replacement demand for aging analog systems, prioritizing compact footprints and minimal renovation requirements. Clinic operators in tier-2 Indian cities are accelerating digital upgrades following CDSCO registration streamlining.
- Orthodontic Centers:Adolescent treatment volume and aligner therapy planning fuel cephalometric imaging procurement. Centers in Japan face PMDA service network mandates that favor established vendors with localized technical support.
- Hospitals:Maxillofacial surgery departments integrate panoramic systems into broader radiology suites with PACS connectivity requirements.
- Research Institutions:Academic dental schools require systems with research-grade calibration and phantom-based quality assurance protocols.
Orthodontic Centers command the highest equipment specification tiers. Dental Clinics represent the largest absolute unit volume.
Technology:
Technology selection determines regulatory pathway complexity, with 3D reconstruction capabilities triggering additional radiation safety verification.
- 3D Imaging:Cone-beam computed tomography embedded within panoramic platforms generates volumetric reconstructions for implant planning. FDA 510(k) clearance timelines extend for these systems due to software algorithm validation requirements.
- Conventional Radiography:Standard panoramic tomography remains the workhorse for general dental screening with established reimbursement codes and lower training burdens.
- Computed Tomography:Medical-grade CT integration serves complex craniofacial anomaly assessment in hospital settings.
- Ultrasound:Emerging soft-tissue imaging adjunct for salivary gland assessment, not yet replacing radiographic standards.
Conventional Radiography holds the largest installed base. 3D Imaging shows the steepest expansion trajectory as hybrid platforms displace standalone units.
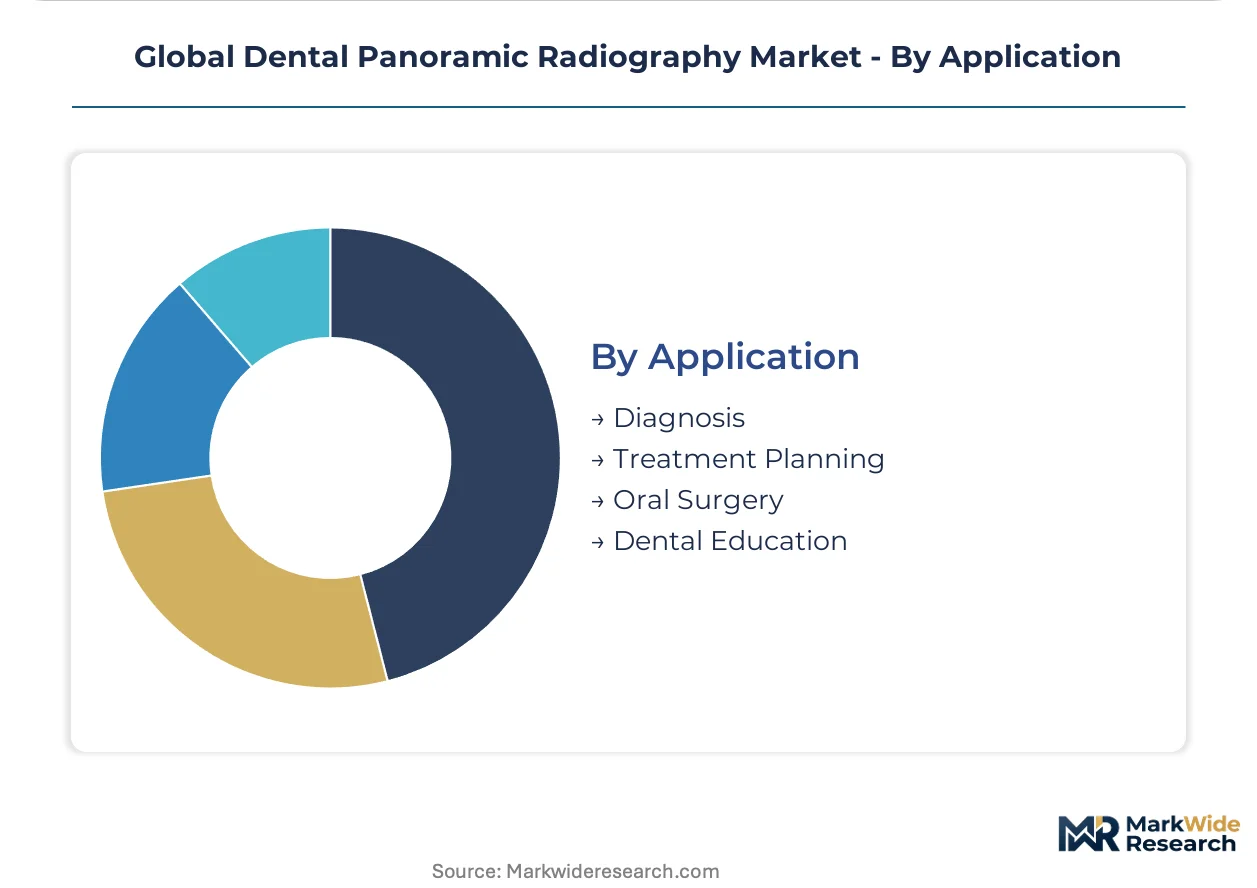
Application:
Application focus determines software feature prioritization, with diagnostic screening emphasizing workflow speed and surgical planning requiring measurement accuracy tools.
- Treatment Planning:Orthodontic and implant workflows demand cephalometric analysis software with automated landmark detection. EU MDR Class IIa certification now mandates clinical performance data for these algorithm-driven features.
- Diagnosis:General screening applications prioritize rapid image acquisition under 20 seconds to maintain patient throughput in high-volume clinics.
- Oral Surgery:Pre-surgical assessment requires cross-sectional visualization and nerve canal tracing capabilities.
- Dental Education:Training institutions need systems with dose simulation modes and multiple exposure parameter settings for student instruction.
Diagnosis dominates current utilization hours. Treatment Planning is climbing fastest as aligner therapy volume expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant geography, with EU MDR harmonization and Japan's PMDA service mandates creating divergent compliance environments across major commercial jurisdictions.
United States
Orthodontic group practices drive hybrid panoramic-CBCT procurement for aligner therapy workflows. FDA 510(k) premarket notification requirements extend clearance timelines for AI-assisted positioning algorithms. Dallas-Fort Worth and Houston dental service organizations concentrate capital equipment purchasing authority.
Germany
Orthodontic specialist density fuels cephalometric system demand among adolescent treatment providers. EU MDR Class IIa certification harmonizes quality benchmarks across member states, reducing duplicate testing for manufacturers. Baden-Württemberg and Bavaria host dense clusters of dental technology distributors with integrated software capabilities.
Japan
Aging demographic dental needs sustain replacement cycles for digital panoramic systems in general practice. PMDA service network mandates impose operational overhead on foreign manufacturers seeking national distribution. Tokyo and Osaka orthodontic centers adopt direct-conversion CMOS sensors at elevated rates.
India
Tier-2 city dental infrastructure modernization accelerates digital system adoption beyond metropolitan cores. CDSCO streamlined medical device registration creates entry pathways for multinational equipment vendors. Gujarat and Karnataka manufacturing corridors develop domestic assembly capabilities for imaging components.
South Korea
MFDS electromagnetic compatibility testing extends registration timelines for panoramic radiography entrants. Seoul capital area dental clinics consolidate toward multifunctional hybrid platforms to optimize floor space utilization. Busan-Ulsan region hosts specialized service organizations capturing calibration and tube replacement volumes.
Global Dental Panoramic Radiography Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with Nordic and Japanese manufacturers anchoring premium positioning through captive distribution. The structure consolidates around workflow-integrated platforms rather than standalone hardware. Three archetypes dominate: full-suite dental equipment conglomerates, regional imaging specialists with localized service networks, and component-focused sensor technology providers. Competitive moves concentrate on portfolio diversification into hybrid CBCT capabilities and geographic expansion through distributor acquisition.
Among Nordic-based manufacturers, Planmeca Oy exemplifies the premium-tier integrated archetype with manufacturing concentration in Helsinki. Dentsply Sirona occupies a position representing North American workflow platform consolidation. J. Morita Corporation anchors the Asia-Pacific specialist tier with Japanese regulatory registration depth. These three entities represent divergent strategic postures: Nordic manufacturing precision, North American distribution scale, and Asian service localization.
| Leading Market Players |
|---|
| Envista Holdings Corporation |
| DÜRR DENTAL SE |
| Dentsply Sirona |
| J. Morita Corporation |
| Carestream Dental |
| Planmeca Oy |
| Acteon |
| Owandy Radiology |
| VATECH |
| Others |
Cost & Logistics Intelligence
Long-term service bundling contracts lock in panoramic system supply access while stabilizing maintenance revenue visibility for manufacturers navigating EU MDR compliance costs. Equipment purchasers in Germany and the United States increasingly unbundle hardware from service agreements, compressing OEM margin structures and redirecting calibration volumes toward independent service organizations.
Pricing Analysis
Equipment price spreads between Germany and India exceed threefold for equivalent digital panoramic specifications, reflecting certification grade differentials and localized service network requirements. Three-tier pricing structure across premium, standard, and economy levels separates hybrid CBCT-enabled systems from conventional digital units and aging analog alternatives. Cost compression in the economy tier intensifies as Chinese component suppliers expand CMOS sensor manufacturing. Dental clinics in tier-2 Indian cities exhibit highest price sensitivity, whereas Japanese orthodontic centers prioritize cephalometric precision over acquisition cost.
Supply Chain Analysis
Component lead times for high-voltage X-ray tubes extend 16-24 weeks, constraining manufacturer capacity to respond to demand surges in orthodontic segments. Manufacturing concentration centers on Finland, Japan, and the United States for complete system assembly, with South Korea and Taiwan supplying direct-conversion CMOS sensors and scintillator materials. Supply chain vulnerability rests on single-source dependencies for precision rotating anode assemblies. Distribution runs through dental equipment distributors with integrated software capabilities in developed markets, while direct manufacturer relationships dominate emerging economy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards manufacturers possessing ISO 13485-certified quality infrastructure and established PMDA service networks, assets that require years to replicate and currently concentrate among Nordic and Japanese incumbents. New entrants face structural barriers in regulatory registration depth and clinical follow-up data collection mandated by EU MDR post-market surveillance.
For Market Incumbents: Consolidate hybrid CBCT capabilities through targeted sensor technology acquisitions before direct-conversion CMOS prices erode premium-tier positioning. Deepen service localization in Japan to defend against PMDA network mandate compliance costs that disadvantage foreign competitors. Prioritize backward integration into X-ray tube refurbishment to capture recurring maintenance volumes unbundling from hardware sales. For New Entrants and Emerging Players: CDSCO streamlined registration pathways for India tier-2 cities offer the most penetrable geographic entry point, with digital panoramic demand accelerating ahead of localized service infrastructure. Target orthodontic centers in Germany seeking cephalometric analysis upgrades without full hybrid CBCT capital commitment. Pursue software-as-a-service tele-diagnostics partnerships to bypass upfront equipment distribution barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform providers with captive sensor technology and regulatory registration depth across multiple jurisdictions. Long-term viability hinges on hybrid imaging convergence and AI-assisted positioning algorithm development. Monitor FDA 510(k) clearance timelines for AI-enabled systems as an inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid CBCT Capability Integration | Consolidates 2D and 3D imaging workflows, reducing per-clinic equipment counts for US dental service organizations. |
| Direct-Conversion CMOS Sensor Development | Decomposes price premiums previously commanded by premium-tier panoramic equipment manufacturers in German orthodontic markets. |
| EU MDR Class IIa Certification Investment | Harmonizes quality benchmarks across European member states, accelerating cross-border commercialization for compliant manufacturers. |
| Tele-Diagnostics Platform Launch | Enables remote orthodontic consultation workflows, opening subscription revenue models beyond hardware transaction economics. |
| India Service Network Localization | Addresses CDSCO registration opportunities in tier-2 cities where digital infrastructure modernization accelerates ahead of technical support capacity. |
Research Approach
The analysis maps digital panoramic, hybrid CBCT-enabled, and analog system sub-sectors, each validated through primary interviews with equipment procurement managers at dental service organizations, biomedical engineers at hospital radiology departments, and regulatory affairs specialists at imaging manufacturers. Secondary validation draws from FDA 510(k) premarket notification databases, EU MDR Class IIa certification registries, PMDA approval documentation, and ISO 13485 audit disclosures. Bottom-up unit economics triangulate against top-down market sizing across product configurations, end-user settings, and geographic regulatory clusters.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, technology tier, and application focus, with additional granularity on regulatory pathway complexity and service bundling preferences. CAGRs derive from installed base replacement cycles, adolescent orthodontic treatment volume trajectories, and aligner therapy adoption patterns. Forecast inputs incorporate radiological technologist shortage severity indices and AI-assisted positioning algorithm regulatory clearance timelines.
Underlying assumptions cover stable reimbursement codes for panoramic imaging, with deviation risk concentrated in hybrid CBCT substitution rates and EU MDR post-market surveillance cost escalation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Mammography Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Spain Mammography Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Echocardiography Market