
 Veterinary Equipment and Supplies Market | 2026-2036
Veterinary Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Equipment and Supplies Market Insights
Companion animal hospitals are redrawing procurement priorities across the veterinary equipment landscape, shifting capital allocation from basic surgical tables toward integrated anesthesia workstations and advanced imaging modalities. Covetrus leverages its distribution network to anchor supply chain efficiency across North American veterinary clinics. B. Braun SE sustains competitive positioning through specialized infusion therapy systems calibrated for veterinary physiology. Shenzhen Mindray Animal Medical Technology Co., Ltd. dominates the diagnostic imaging segment with ultrasound platforms engineered specifically for companion and production animal applications.
Veterinary equipment and supplies encompass electromechanical diagnostic apparatus, precision surgical instruments, inhalation anesthesia delivery systems, and consumable treatment materials manufactured to species-specific physiological tolerances. These products enable clinical intervention, disease monitoring, and surgical procedures across companion, production, and exotic animal populations. Diagnostic equipment leads revenue contribution due to persistent upgrade cycles in digital radiography and point-of-care laboratory analyzers, while mobile veterinary services represent the fastest-growing end-user channel as fleet-based practitioners demand portable, battery-operated devices. Surgical instruments retain mature margin pools through instrument sterilization compliance requirements that drive replacement frequency.
The FDA Center for Veterinary Medicine enforces device safety and efficacy standards that shape product development timelines and market access pathways for equipment manufacturers. ISO 13485 quality management systems and the EU Medical Device Regulation, enforced by notified bodies across European member states, impose parallel conformity requirements that filter market participation. Stakeholders must monitor evolving telemedicine reimbursement policies and species-specific regulatory carve-outs that will determine which technology platforms achieve scalable clinical deployment.
Market Dynamics
Companion animal referral hospitals are consolidating purchasing power through group procurement organizations, compressing margins for mid-tier equipment vendors while elevating technical service requirements across diagnostic imaging and anesthesia platforms.
Growth Catalysts
- Specialty Referral Network Densification:Metropolitan corridor expansion of multi-disciplinary veterinary hospitals in the United States, Germany, and Japan is accelerating capital expenditure on CT and MRI suites calibrated for companion animal physiology.
- FDA Center for Veterinary Medicine Guidance:Elevated device safety documentation requirements are filtering out subscale manufacturers, concentrating market access among ISO 13485-certified producers with dedicated veterinary regulatory affairs functions.
- Point-of-Care Diagnostics:Chemistry analyzers and immunoassay platforms engineered for veterinary-specific reference ranges are displacing centralized laboratory send-out workflows in mixed animal practices.
Market Restraints
- Supply Concentration in Precision Optics:German and Japanese optical component suppliers control critical lens assemblies for endoscopic and imaging equipment, exposing veterinary device assemblers to extended lead times and minimum order quantity pressures.
- EU Medical Device Regulation Transition Costs:Notified body capacity constraints and enhanced clinical evidence requirements for Class IIa and above devices are extending time-to-market by 18-24 months for European market entrants.
- Veterinary Anesthesia Machine Longevity:Extended service intervals and rebuild programs for legacy inhalation systems are compressing replacement cycles in cost-sensitive production animal segments.
Strategic Opportunities
- Telemedicine Reimbursement Evolution:State-level veterinary practice acts in the United States are progressively clarifying remote diagnostic interpretation billing codes, enabling platform-as-a-service models for radiology and cardiology overreads.
- Battery-Operated Portable Imaging:Wireless ultrasound probes and handheld radiography units are converging with fleet-based mobile veterinary service expansion across suburban and exurban United States markets.
- Exotic and Avian Species Equipment Gap:Underserved zoological and wildlife rehabilitation channels present white space for species-specific anesthesia circuits, microsurgical instruments, and physiological monitoring calibrated for non-mammalian metabolisms.
Industry Challenges
- Veterinary Biomedical Engineering Talent Scarcity:Cross-trained professionals capable of servicing electromechanical diagnostic platforms, maintaining species-specific calibration protocols, and managing ISO 13485 quality systems command premium compensation and limited geographic mobility.
- Legacy PACS Integration Complexity:Digital imaging equipment from multiple vendors requires middleware development for seamless integration with existing hospital information management systems, extending deployment timelines and elevating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Equipment and Supplies Market |
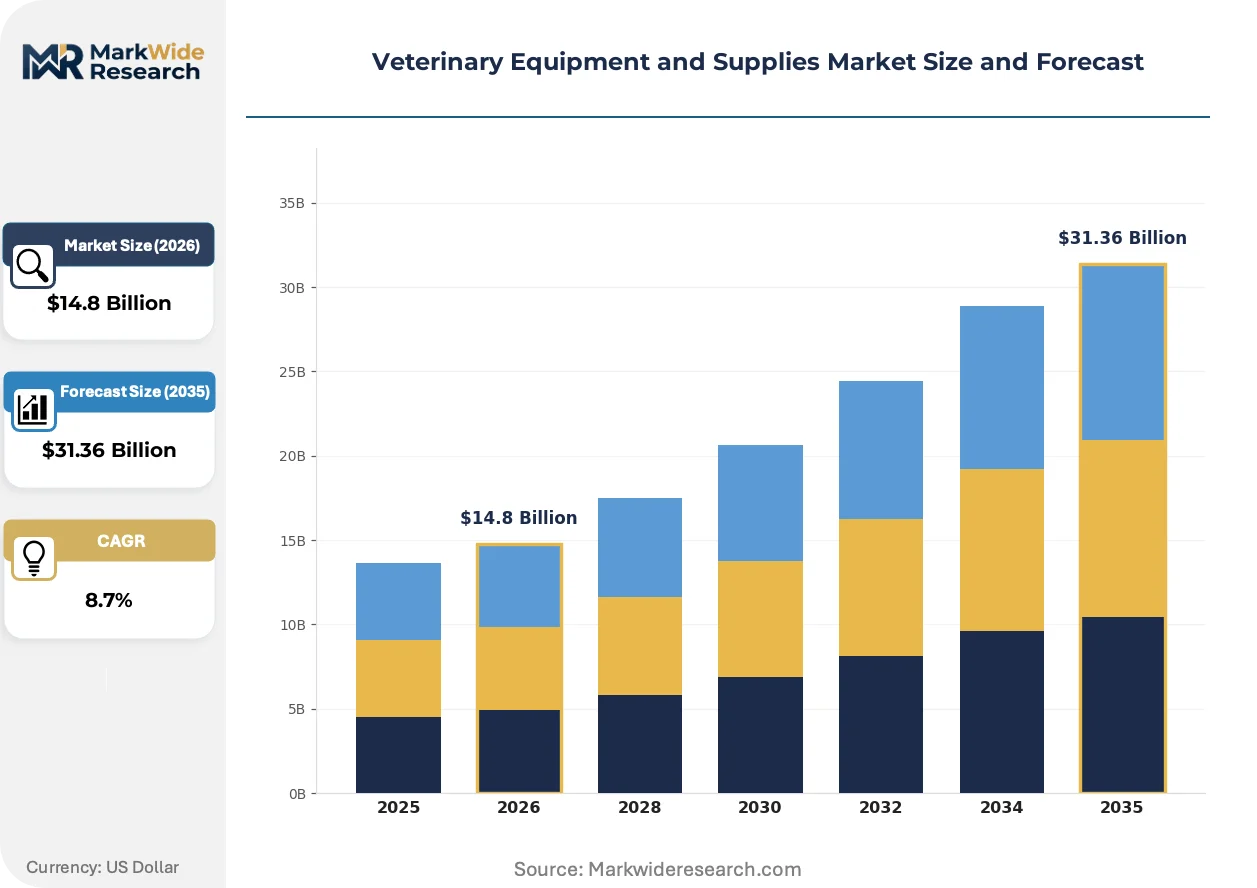
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Anesthesia Equipment, Treatment Supplies End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Veterinary Services Application: Canine Care, Feline Care, Equine Care, Exotic Animal Care Distribution Channel: Direct Sales, Online Retail, Wholesale, Veterinary Distributors |
| Companies Covered | Covetrus, B. Braun SE, Midmark Corporation, BD, Cardinal Health, Shenzhen Mindray Animal Medical Technology Co., Ltd., Masimo, ICU Medical, Neogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Equipment and Supplies Market Trends and Innovations
Digital pathology workflows and artificial intelligence-assisted diagnostic interpretation are compressing specialist veterinarian labor constraints while elevating case throughput expectations across referral networks.
Wireless, tablet-connected ultrasound transducers are miniaturizing point-of-care imaging deployment. Emergency and critical care departments in United States companion animal hospitals are adopting these platforms for rapid thoracic and abdominal triage. The technology is miniaturizing capital barriers for independent practitioners and mobile service operators, expanding addressable market penetration beyond traditional hospital-based radiology suites.
ISO 14155 clinical investigation standards are extending evidentiary requirements for veterinary device manufacturers seeking CE marking under the EU Medical Device Regulation. European notified bodies are demanding species-specific safety and performance documentation that parallels human medical device rigor. High-risk implantable devices and active therapeutic equipment face the steepest compliance trajectory, favoring established manufacturers with dedicated veterinary clinical affairs infrastructure.
Subscription-based equipment access models are displacing outright capital purchase arrangements across United States veterinary practice groups. Corporate consolidators and multi-site hospital networks are negotiating all-inclusive per-procedure pricing for imaging and anesthesia platforms, transferring obsolescence risk and maintenance liability to original equipment manufacturers. This restructuring concentrates most visibly in metropolitan markets where specialty referral density supports predictable utilization forecasting.
Veterinary Equipment and Supplies Market Segmentation
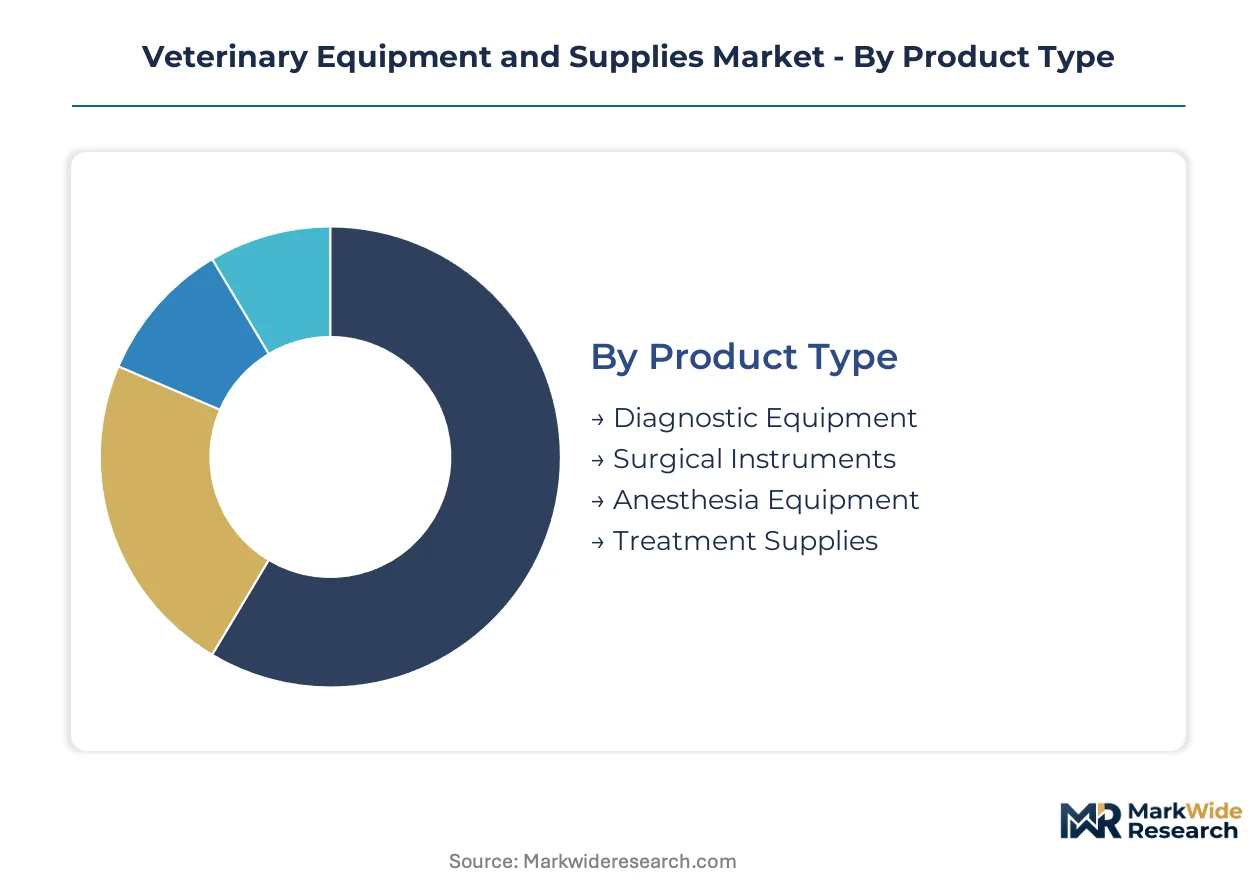
Segmentation in veterinary equipment reveals how procurement patterns diverge across clinical settings and species applications. Understanding these fault lines exposes where substitution pressures and margin compression concentrate most intensely.
Product Type:
Diagnostic equipment faces the most acute substitution threat as point-of-care platforms displace centralized laboratory workflows and legacy imaging systems.
- Diagnostic Equipment:Digital radiography systems, ultrasound platforms, and in-house chemistry analyzers enable rapid disease detection at the point of care. Demand concentrates in United States metropolitan referral hospitals where specialty veterinarians require CT and MRI suites calibrated for companion animal physiology. The FDA Center for Veterinary Medicine's elevated documentation requirements favor ISO 13485-certified manufacturers with dedicated clinical affairs infrastructure.
- Surgical Instruments:Precision scalpels, forceps, retractors, and sterilization trays manufactured to species-specific anatomical tolerances support soft-tissue and orthopedic procedures. Procurement is shifting toward single-use disposable instrument kits in emergency settings where sterilization turnaround constraints limit instrument reuse.
- Anesthesia Equipment:Inhalation delivery systems and physiological monitoring apparatus engineered for veterinary respiratory patterns.
- Treatment Supplies:Consumable wound care materials, infusion sets, and catheterization products with species-calibrated sizing.
Diagnostic equipment retains volume leadership; mobile-compatible imaging platforms hold the steepest expansion curve.
End User:
Customer type determines service intensity requirements and capital deployment cycles, with corporate consolidators rewriting procurement economics.
- Veterinary Clinics:Small-scale mixed animal practices serving companion and production animals with limited procedure volumes.
- Animal Hospitals:Multi-disciplinary referral centers with 24-hour emergency capabilities and specialty surgical suites. These facilities in United States metropolitan corridors anchor demand for advanced imaging and anesthesia workstations as group purchasing organizations consolidate vendor relationships.
- Research Institutions:Academic veterinary medical centers and contract research organizations conducting species-specific pharmacology studies. Procurement concentrates on physiological monitoring equipment meeting Institutional Animal Care and Use Committee protocols.
- Mobile Veterinary Services:Fleet-based practitioners delivering house-call and rural large-animal care. Battery-operated portable ultrasound and radiography units are gaining share fastest as suburban and exurban United States markets expand fleet coverage.
Animal hospitals command the highest per-site equipment expenditure; mobile veterinary services are climbing the fastest.
Application:
Species-specific physiological variation dictates equipment calibration requirements and creates distinct vendor specialization pockets.
- Canine Care:Orthopedic surgical instruments and weight-bearing imaging platforms sized for large-breed dogs. Demand concentrates in United States specialty referral networks where cruciate ligament repair and hip replacement procedures drive anesthesia workstation utilization.
- Feline Care:Miniaturized anesthesia circuits and low-volume laboratory analyzers calibrated for feline metabolic parameters. Feline-exclusive practices in Japan and Germany are adopting point-of-care diagnostic platforms to reduce sample volume requirements.
- Equine Care:Portable radiography and ultrasound systems for field-based lameness evaluation.
- Exotic Animal Care:Microsurgical instruments and non-mammalian physiological monitoring for avian and reptile patients.
Canine care retains volume leadership; exotic animal care holds the steepest expansion curve.
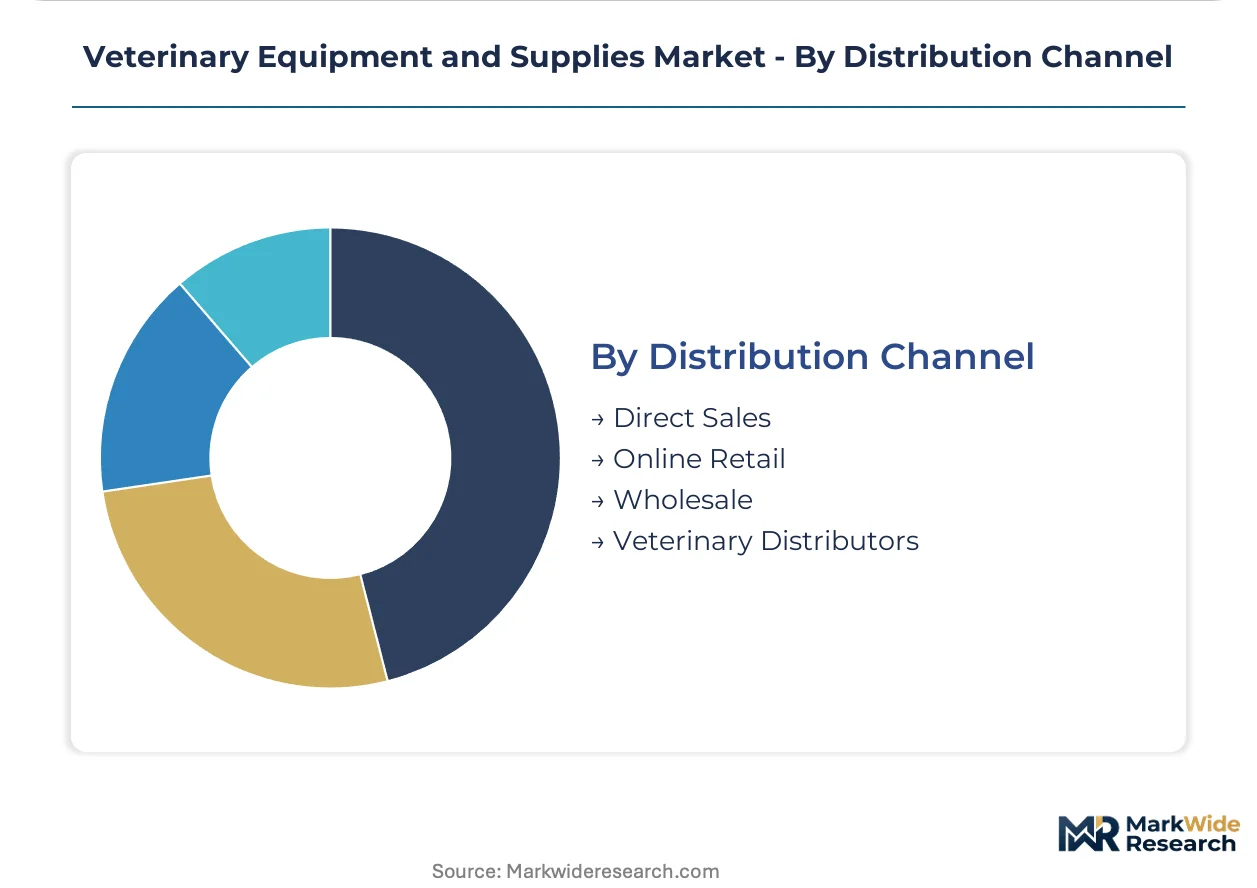
Distribution Channel:
Channel structure determines technical service attachment rates and inventory carrying cost allocation between manufacturers and end users.
- Direct Sales:Manufacturer-employed clinical specialists supporting complex imaging and anesthesia platform installation. United States corporate veterinary consolidators negotiate direct relationships for multi-site equipment standardization.
- Online Retail:E-commerce platforms for consumable supplies and replacement parts with next-day logistics coverage.
- Wholesale:Regional distributors serving independent practices with consolidated product baskets.
- Veterinary Distributors:Specialized intermediaries like Covetrus providing inventory management, equipment financing, and field service networks across North American veterinary clinics.
Veterinary distributors retain volume leadership; direct sales channels are expanding most quickly among consolidated practice groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate consolidators in the United States concentrate procurement power through group purchasing organizations, while specialty referral networks in Germany and Japan drive comparable capital intensity for advanced diagnostic suites.
United States
Metropolitan corridor expansion of multi-disciplinary veterinary hospitals accelerates capital expenditure on CT and MRI suites calibrated for companion animal physiology. FDA Center for Veterinary Medicine guidance elevates device safety documentation requirements, filtering subscale manufacturers from market access. Corporate consolidators in Texas and Florida negotiate direct equipment relationships for multi-site standardization.
Germany
Specialty veterinary referral networks in Bavaria and North Rhine-Westphalia densify procurement demand for anesthesia workstations and digital radiography systems. EU Medical Device Regulation notified body requirements impose parallel conformity standards that extend time-to-market for European entrants. Precision optics suppliers in Baden-Württemberg control critical lens assemblies for endoscopic equipment.
Japan
Feline-exclusive practices in Tokyo and Osaka metropolitan areas adopt point-of-care diagnostic platforms to reduce sample volume requirements. METI standards alignment with ISO 13485 quality management systems shapes product development timelines for device manufacturers. Kanto region veterinary medical centers anchor demand for physiological monitoring equipment.
China
Shenzhen-based diagnostic imaging manufacturers engineer ultrasound platforms specifically for companion and production animal applications. NMPA veterinary device registration pathways parallel human medical device rigor for high-risk implantable equipment. Yangtze River Delta production clusters concentrate electromechanical diagnostic apparatus assembly capacity.
United Kingdom
Independent veterinary practice groups in London and Southeast England negotiate subscription-based equipment access models transferring obsolescence risk to manufacturers. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements. Midlands region specialty referral hospitals drive replacement cycles for legacy inhalation anesthesia systems.
Veterinary Equipment and Supplies Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with dedicated veterinary divisions alongside specialized animal health equipment pure-plays. Market structure concentrates around ISO 13485-certified manufacturers with established clinical affairs infrastructure capable of navigating FDA Center for Veterinary Medicine and EU MDR compliance pathways. Three archetypes dominate: diversified human medical device companies with veterinary product lines, specialized animal health equipment manufacturers, and regional distributors with integrated service networks. Competitive dynamics center on M&A consolidation of specialty referral hospital procurement relationships and geographic expansion of technical service coverage.
Among diversified medical technology conglomerates, B. Braun SE and BD occupy positions exemplifying the infusion therapy and surgical instrumentation archetype. Shenzhen Mindray Animal Medical Technology Co., Ltd. anchors the specialized diagnostic imaging tier with China-based engineering capabilities. Covetrus represents the distribution-centric model with North American field service network integration.
| Leading Market Players |
|---|
| Covetrus |
| B. Braun SE |
| Midmark Corporation |
| BD |
| Cardinal Health |
| Shenzhen Mindray Animal Medical Technology Co., Ltd. |
| Masimo |
| ICU Medical |
| Neogen Corporation |
| Others |
Pricing and Supply Chain Analysis
Disposable instrument kits displacing reusable surgical trays in emergency settings are redrawing procurement economics across veterinary supply chains, compressing unit economics for sterilization service providers while elevating logistics complexity for single-use consumable distributors.
Pricing Analysis
Cost-plus contracts with optical component indexation dominate anesthesia workstation and endoscopic equipment procurement between United States group purchasing organizations and German-Japanese lens assembly suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified imaging platforms with full clinical affairs support from basic diagnostic units and refurbished legacy systems. Pricing pressure stems from corporate consolidator volume aggregation in metropolitan Texas and Florida corridors. Mobile veterinary services exhibit highest price sensitivity due to fleet-based capital constraints, while specialty referral hospitals prioritize technical service attachment over unit cost.
Supply Chain Analysis
Inbound logistics costs through congested trans-Pacific trade lanes elevate landed costs for precision optical components sourced from Baden-Württemberg and Osaka manufacturing clusters. Critical lens assemblies for endoscopic equipment draw from German and Japanese suppliers, while electromechanical diagnostic apparatus feeds from Yangtze River Delta production centers. Single-source vulnerability concentrates in specialized anesthesia circuit manufacturing. Distribution runs through veterinary-specific intermediaries with integrated field service networks across North American metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against point-of-care diagnostic platforms displacing centralized laboratory send-out workflows, as chemistry analyzer miniaturization threatens legacy equipment installed bases.
For Market Incumbents: Shield diagnostic imaging margins by embedding subscription-based equipment access models with full maintenance liability transfer. Secure captive supply of precision optical components through backward integration into Baden-Württemberg lens assembly partnerships. ISO 13485 certification investment remains essential as FDA Center for Veterinary Medicine documentation requirements filter subscale competitors.
For New Entrants and Emerging Players: Differentiate on species-specific physiological monitoring for exotic and avian applications where established vendors lack calibrated product lines. Target zoological and wildlife rehabilitation channels with microsurgical instruments sized for non-mammalian metabolisms. Pursue fleet-based mobile veterinary services in exurban United States markets with battery-operated portable ultrasound bundling.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed veterinary practice consolidators seeking equipment standardization across multi-site networks. Five-to-ten year viability hinges on telemedicine reimbursement clarification enabling platform-as-a-service radiology overread models. Monitor state-level veterinary practice act evolution as inflection signal for remote diagnostic billing code expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | FDA Center for Veterinary Medicine documentation requirements favor certified manufacturers with dedicated clinical affairs infrastructure. |
| Subscription-Based Equipment Access Models | Corporate consolidators in Texas and Florida negotiate all-inclusive per-procedure pricing transferring obsolescence risk to manufacturers. |
| Species-Specific Diagnostic Platform Development | Underserved exotic animal care channels present white space for anesthesia circuits calibrated to avian and reptilian metabolisms. |
| Telemedicine Reimbursement Strategy | State-level veterinary practice acts clarifying remote diagnostic interpretation billing codes enable scalable platform-as-a-service deployment. |
| Backward Integration into Precision Optics | German and Japanese optical component suppliers control critical lens assemblies exposing assemblers to extended lead time pressures. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with veterinary equipment procurement directors, biomedical engineers at specialty referral hospitals, GPO contracts managers, and field service technicians; and secondary validation against FDA Center for Veterinary Medicine guidance documents, EU Medical Device Regulation notified body filings, hospital procurement databases, and corporate consolidator capital expenditure disclosures. Bottom-up equipment unit economics triangulated against top-down market size estimates across the projection horizon.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, end-user channel, species application, and geographic regulatory cluster. CAGRs derived from equipment replacement cycle analysis, referral network densification rates, and mobile service fleet expansion patterns. Species-specific calibration requirements and telemedicine reimbursement evolution served as veterinary-specific forecast inputs.
Material uncertainties — regulatory divergence between MHRA post-Brexit pathways and EU MDR, notified body capacity constraints extending CE marking timelines, and state-level telemedicine billing code fragmentation — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Cattle Vaccines Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Canine Arthritis Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Global Animal Intestinal Health Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Global Swine Vaccines Market
Veterinary
Veterinary Vaccines Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Mastitis Market
Veterinary
Veterinary Healthcare Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Global Canine Atopic Dermatitis Market