
 Argentina Digital X-Ray Market | 2026-2036
Argentina Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Digital X-Ray Market Outlook
Flat-panel detector technology is broadening the clinical utility of digital radiography beyond conventional film replacement. Siemens Healthineers leverages its installed base in Argentine public hospitals to sustain service revenue streams. Canon Medical Systems Corporation anchors its position through specialized cardiovascular imaging configurations. Koninklijke Philips NV competes on integrated diagnostic workflow platforms that connect radiology to hospital information systems.
Argentina Digital X-Ray systems employ solid-state detectors—typically amorphous silicon or selenium arrays—that convert X-ray photons directly into digital signals, eliminating chemical processing and enabling immediate image review for diagnostic decision-making. Portable X-Ray systems are gaining share fastest among product types as emergency departments and intensive care units prioritize bedside imaging to reduce patient transport risks. Flat-panel detector technology captures the dominant margin pool due to superior dose efficiency and spatial resolution compared to legacy computed radiography plates, while oncology applications drive premium system configurations.
ANMAT, Argentina's national medical device regulator, enforces post-market surveillance and Good Manufacturing Practice alignment for imported imaging equipment, directly shaping product registration timelines and commercial entry strategies. The Argentine Ministry of Health's procurement frameworks for public sector radiology infrastructure dictate technical specifications that filter which detector technologies qualify for institutional tenders. Stakeholders must monitor ANMAT's convergence with Mercosur harmonized standards and provincial budget cycles to time capital deployment effectively.
Market Dynamics
Flat-panel detector technology is displacing computed radiography across Buenos Aires Province public hospital networks, compressing procurement cycles and forcing equipment vendors to restructure service revenue models around detector replacement rather than film-based consumables.
Growth Catalysts
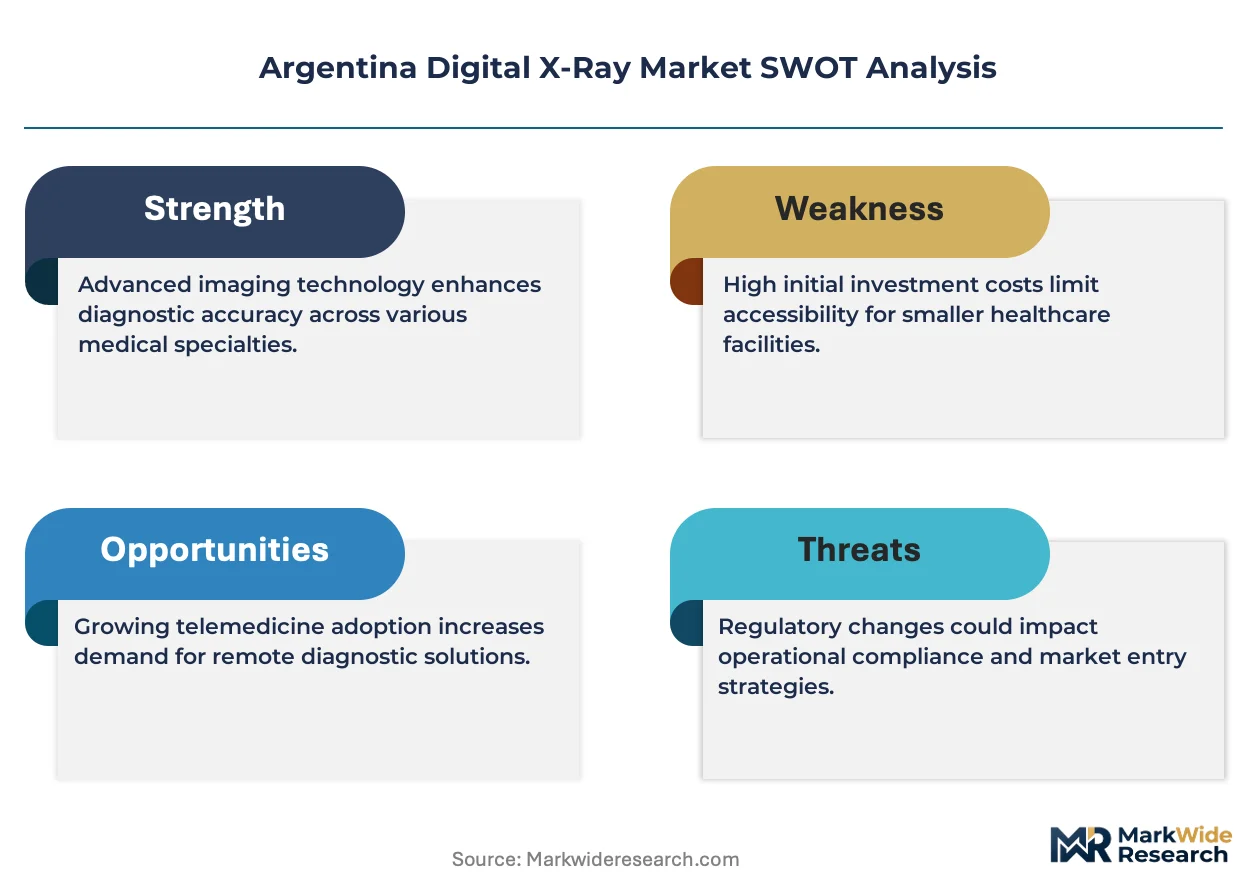
- ANMAT Streamlined Registration:Argentina's national medical device regulator has reduced import clearance timelines for advanced imaging equipment, accelerating commercial entry for flat-panel detector systems.
- Oncology Imaging Demand:Metropolitan Buenos Aires healthcare networks are expanding radiotherapy planning capabilities, creating institutional pull for high-resolution digital radiography in tumor localization workflows.
- Portable System Prioritization:Intensive care units across Córdoba are prioritizing bedside X-ray deployment to eliminate patient transport risks, favoring mobile detector configurations over fixed-room installations.
Market Restraints
- Import Dependency:Solid-state detector arrays rely entirely on foreign manufacturing, exposing procurement budgets to peso-dollar exchange volatility and international logistics disruptions.
- Capital Intensity:Flat-panel detector systems require upfront investment multiples above legacy computed radiography plates, straining provincial health ministry budget allocations.
- Technical Obsolescence Risk:Rapid detector resolution improvements threaten depreciation cycles for installed base equipment before full cost recovery.
Strategic Opportunities
- Telemedicine Integration:Remote diagnostic platforms are converging with cloud-based image archiving, enabling teleradiology services to penetrate underserved Patagonian provinces.
- Orthopedic Trauma Applications:Emergency departments are expanding intraoperative imaging capabilities, creating demand for surgical C-arm configurations with digital flat-panel detectors.
- Provincial Procurement Aggregation:Buenos Aires Province's centralized purchasing frameworks are consolidating hospital demand, favoring vendors with service infrastructure scale.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Flat-panel detector calibration and maintenance requires specialized technician training that Argentine technical institutes have not scaled to meet.
- Legacy System Interoperability:Hospital information system integration with new digital radiography platforms demands custom middleware development, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Digital X-Ray Market |
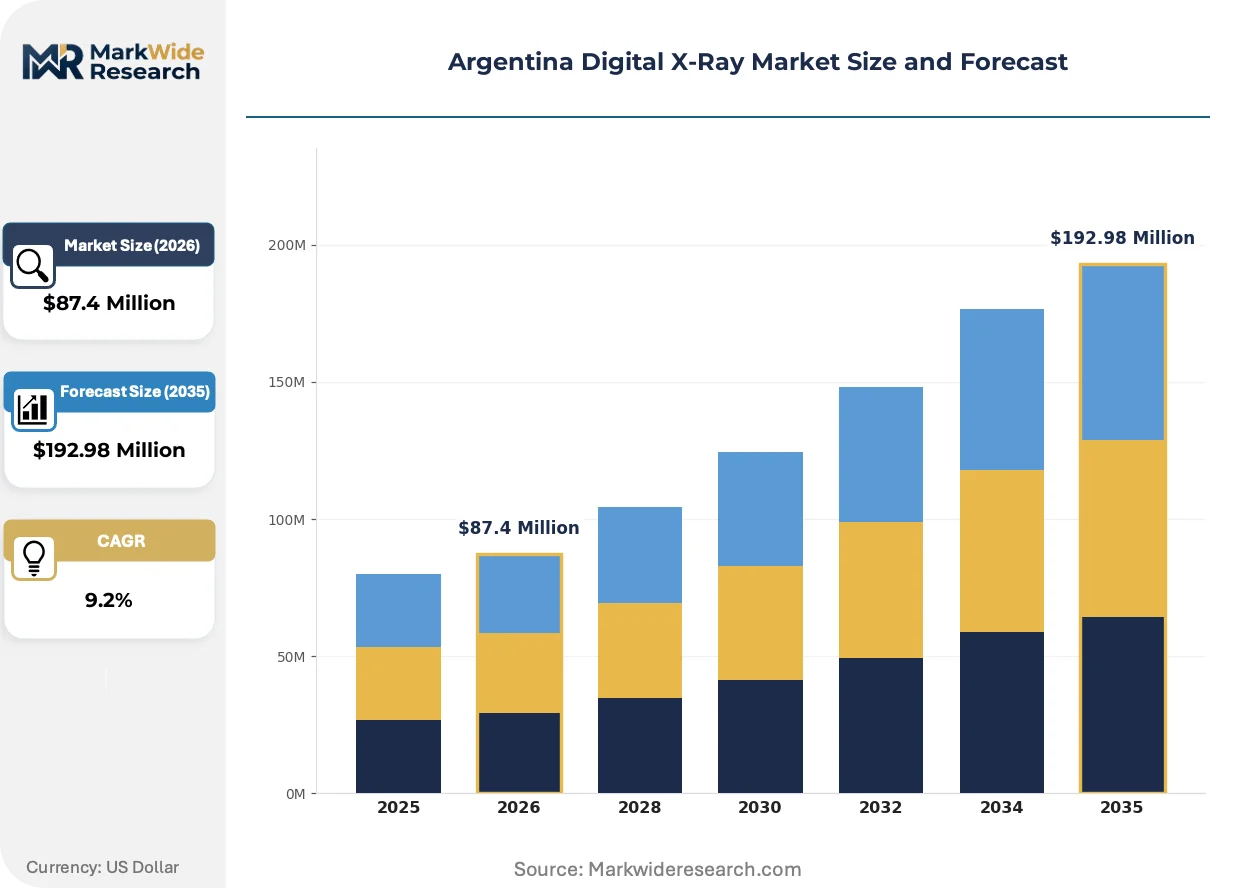
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $192.98 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary X-Ray, Portable X-Ray, Handheld X-Ray, Digital Fluoroscopy End User: Hospitals, Diagnostic Centers, Outpatient Facilities, Research Laboratories Technology: Charge-Coupled Device, Flat-Panel Detector, Image Intensifier, Computed Radiography Application: Oncology, Orthopedics, Cardiology, Gastroenterology |
| Companies Covered | Siemens Healthineers, Canon Medical Systems Corporation, Koninklijke Philips NV, Shimadzu Corporation, Carestream Health, GE Healthcare, Fujifilm Holdings Corporation, Agfa-Gevaert NV, Hitachi Medical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Digital X-Ray Market Strategic Shifts
Detector technology evolution and regulatory pathway adjustments are restructuring how Argentine healthcare providers acquire and deploy radiography systems, with implications for vendor business models and hospital capital planning.
Artificial intelligence-assisted image reconstruction is converging with flat-panel detector hardware to reduce radiation dose requirements while maintaining diagnostic clarity. Oncology departments in Buenos Aires are piloting these configurations for pediatric and repeat-imaging protocols. The convergence is compressing the performance gap between premium and mid-tier system tiers, forcing price repositioning across product lines.
ANMAT's alignment with Mercosur harmonized medical device standards is simplifying cross-border registration for imaging equipment originally certified in Brazil or Uruguay. Argentine importers are leveraging this regulatory convergence to accelerate product introduction timelines. Provincial procurement offices are responding by tightening technical specifications to favor systems with existing Mercosur certification over newly registered alternatives.
Public hospital buying committees are unbundling equipment purchase from long-term service contracts, treating detector replacement and software maintenance as separately tendered line items. This pattern disrupts vendor strategies built on captive service revenue streams. The unbundling is most advanced in Córdoba's centralized health administration, where multi-hospital maintenance pools are displacing single-site service agreements.
Argentina Digital X-Ray Market Segmentation
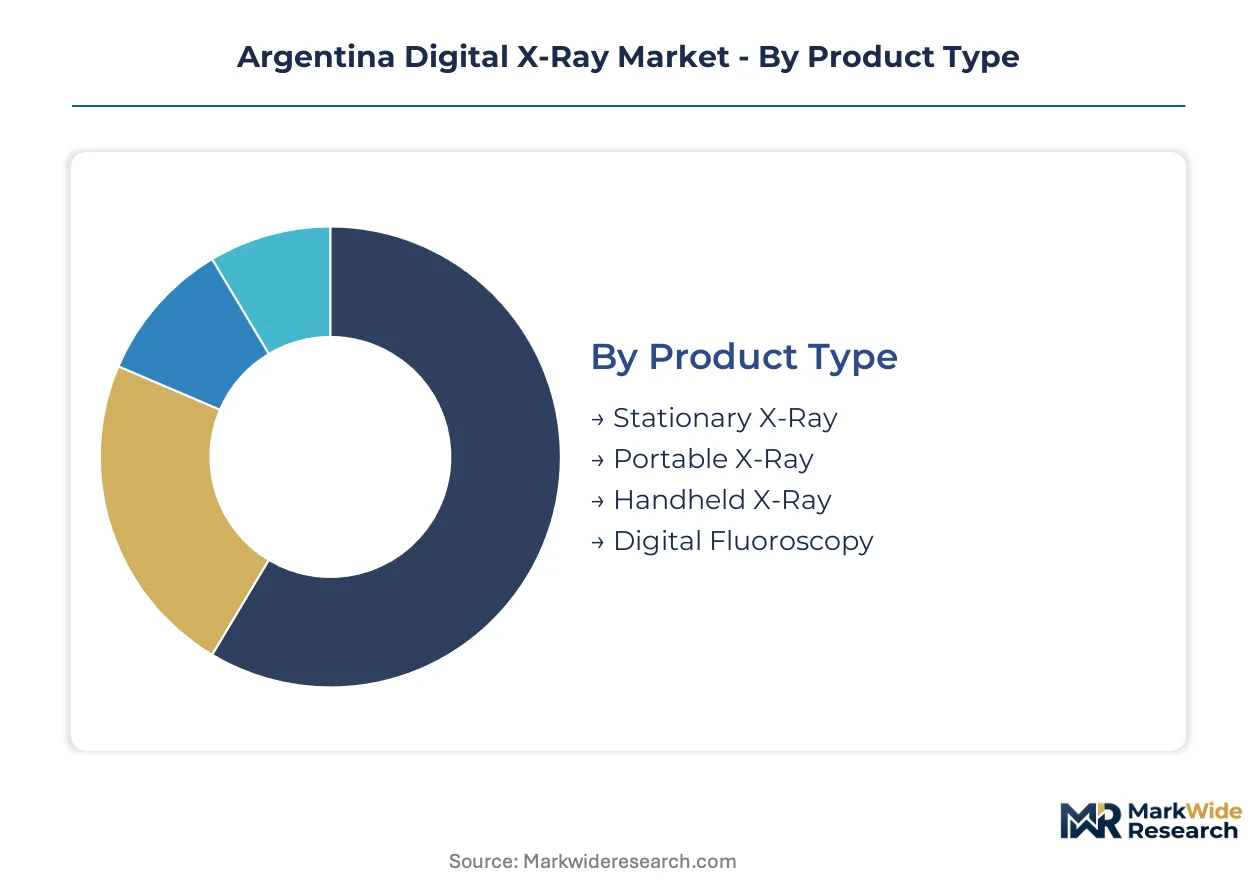
Digital X-Ray segmentation in Argentina reflects distinct procurement patterns across public hospital networks and private diagnostic chains. Technology choices and product configurations vary sharply between high-volume metropolitan centers and resource-constrained provincial facilities.
Product Type:
Standalone installations dominate Buenos Aires Province public tenders, while embedded portable units penetrate intensive care workflows through bedside deployment models.
- Stationary X-Ray:Fixed-room installations with ceiling-suspended tube assemblies and integrated flat-panel detector tables. Buenos Aires metropolitan hospitals prioritize these for high-throughput trauma and emergency departments, though capital intensity limits replacement cycles.
- Portable X-Ray:Mobile detector configurations on wheeled chassis with battery-powered operation. Córdoba's intensive care units favor bedside deployment to eliminate patient transport risks, accelerating procurement timelines.
- Handheld X-Ray:Compact battery-operated units for extremity imaging in confined spaces.
- Digital Fluoroscopy:Real-time imaging systems with continuous X-ray exposure capability for interventional procedures.
Stationary X-Ray leads volumes today; Portable X-Ray is gaining share fastest.
End User:
Procurement authority concentration shapes segment dynamics, with provincial health ministries controlling capital allocation for institutional buyers.
- Hospitals:Public sector networks in Buenos Aires Province drive bulk tender volumes through centralized purchasing frameworks. These facilities demand integrated PACS connectivity and ANMAT-registered service infrastructure.
- Diagnostic Centers:Private imaging chains in metropolitan Buenos Aires specialize in high-margin elective procedures. These operators prioritize throughput optimization and rapid turnaround protocols.
- Outpatient Facilities:Smaller clinics with limited capital budgets favor refurbished or mid-tier system configurations.
- Research Laboratories:Academic medical centers requiring specialized phantom calibration and protocol development capabilities.
Hospitals dominate installed base; Diagnostic Centers show steepest expansion trajectory.
Technology:
Detector architecture determines dose efficiency, spatial resolution, and total cost of ownership across Argentine healthcare networks.
- Flat-Panel Detector:Amorphous silicon or selenium arrays converting X-ray photons directly into digital signals. Oncology departments in Buenos Aires specify these for radiotherapy planning workflows demanding sub-millimeter spatial resolution.
- Computed Radiography:Photostimulable phosphor plates requiring laser scanning digitization. Legacy installations persist in provincial hospitals with constrained replacement budgets, though ANMAT registration requirements favor digital-native alternatives.
- Charge-Coupled Device:Optical coupling systems for specialized dental and extremity imaging applications.
- Image Intensifier:Vacuum tube technology retained in select surgical C-arm configurations for fluoroscopy.
Flat-Panel Detector anchors revenue; Computed Radiography faces accelerated displacement.
Application:
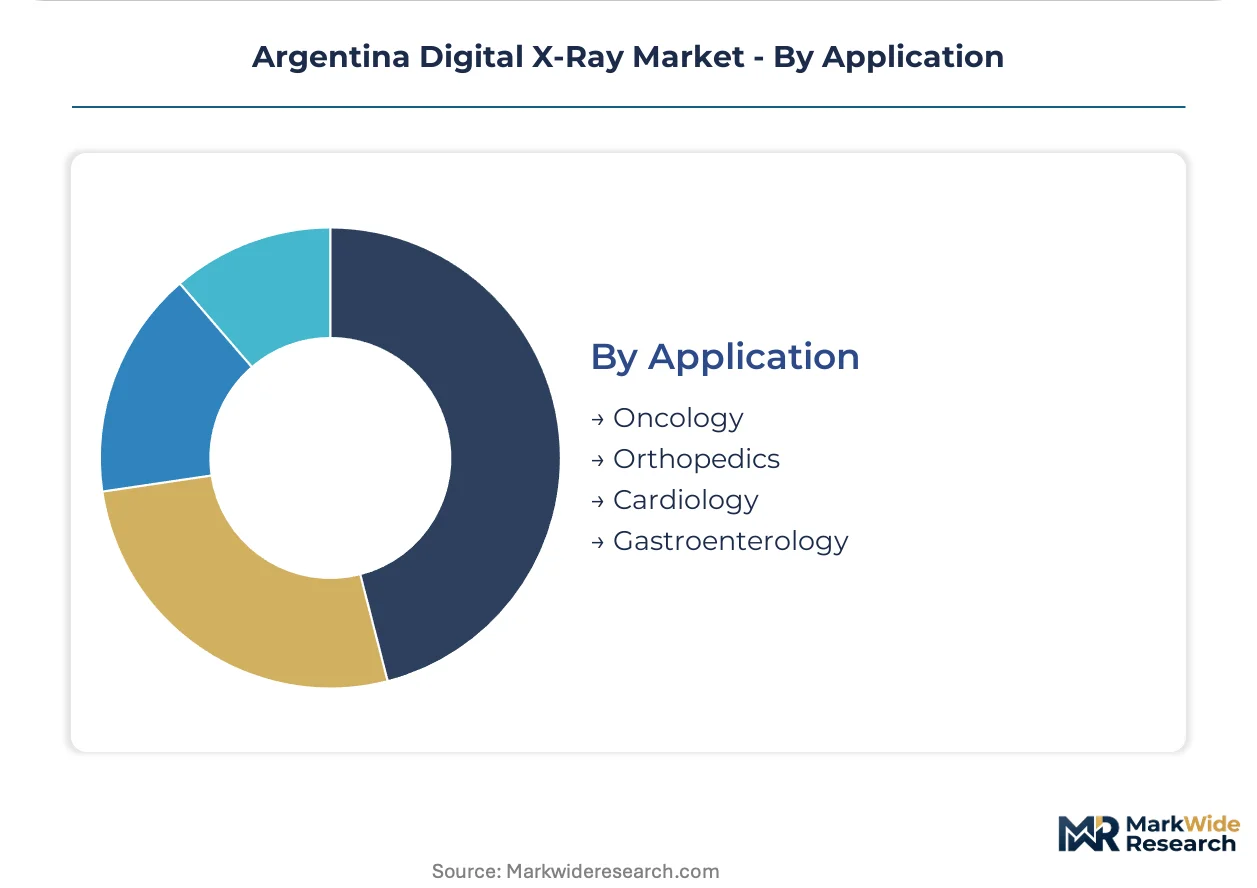
Clinical workflow requirements dictate system specifications, with tumor localization and trauma imaging driving premium configurations.
- Oncology:High-resolution digital radiography for tumor localization and radiotherapy planning. Buenos Aires healthcare networks expanding radiotherapy capabilities pull demand for premium flat-panel detector systems with specialized acquisition software.
- Orthopedics:Weight-bearing extremity imaging and intraoperative C-arm fluoroscopy. Emergency departments across Córdoba prioritize surgical configurations with digital flat-panel detectors for trauma intervention workflows.
- Cardiology:Diagnostic and interventional procedures requiring rapid frame-rate fluoroscopy.
- Gastroenterology:Contrast studies and motility assessments using fluoroscopic guidance.
Oncology commands premium pricing; Orthopedics shows climbing volume contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Buenos Aires concentrates Argentina's digital radiography procurement activity through centralized public hospital networks and private diagnostic chains. Provincial health ministries in Córdoba and Santa Fe are accelerating flat-panel detector adoption through aggregated tender frameworks. The country's medical imaging infrastructure displays sharp geographic stratification between capital-intensive metropolitan centers and equipment-constrained interior provinces.
Metropolitan Buenos Aires
Oncology departments drive premium system demand as healthcare networks expand radiotherapy planning capabilities. ANMAT's streamlined registration pathways accelerate import clearances for advanced flat-panel detector configurations. Public hospital procurement programs in Buenos Aires Province compress replacement cycles for legacy computed radiography systems.
Córdoba Province
Intensive care units prioritize portable X-ray deployment to eliminate patient transport risks in critical care workflows. Provincial health administration unbundles equipment purchase from long-term service contracts, disrupting captive revenue models. Córdoba's centralized health administration pools multi-hospital maintenance contracts.
Santa Fe Province
Rosario's healthcare network anchors demand for orthopedic trauma imaging systems in emergency department configurations. Provincial procurement offices tighten technical specifications to favor Mercosur-certified equipment over newly registered alternatives. Public hospital buying committees treat detector replacement as separately tendered line items.
Mendoza Province
Diagnostic centers in Greater Mendoza specialize in high-margin elective procedures requiring throughput optimization. The province's constrained capital budgets favor refurbished or mid-tier system configurations over premium installations. Private imaging chains compete on rapid turnaround protocols for outpatient services.
Patagonian Provinces
Telemedicine platforms converge with cloud-based image archiving to penetrate underserved diagnostic markets. Remote diagnostic services reduce dependency on patient transport to metropolitan imaging centers. Provincial budget volatility delays capital deployment for fixed-room installations.
Argentina Digital X-Ray Market Competitive Environment
Global majors compete with regional champions across procurement channel access and service infrastructure scale. Siemens Healthineers leverages its installed base in Argentine public hospitals to sustain service revenue streams. The vendor landscape organizes around three archetypes: integrated diagnostic workflow providers, specialized cardiovascular imaging configurators, and detector technology specialists. Dominant competitive moves include provincial procurement aggregation partnerships and unbundled service contract restructuring.
Within the integrated systems tier, Siemens Healthineers and Koninklijke Philips NV exemplify vendors competing on hospital information system connectivity. Canon Medical Systems Corporation occupies a position among specialized imaging configurators. These three companies anchor the premium segment through differentiated workflow platform architectures rather than detector hardware specifications alone.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Shimadzu Corporation |
| Carestream Health |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Agfa-Gevaert NV |
| Hitachi Medical Corporation |
| Others |
Value Chain & Pricing Dynamics
ANMAT's convergence with Mercosur harmonized standards gates qualified supply for premium-tier flat-panel detector systems, restricting vendor eligibility to manufacturers with existing Brazilian or Uruguayan certification while compressing procurement timelines for compliant equipment. Provincial health ministries exploit this regulatory filter to extract price concessions from vendors locked out of accelerated registration pathways.
Pricing Analysis
Input-cost pass-through from amorphous silicon detector arrays and solid-state electronics components anchors pricing dynamics for flat-panel systems in Argentine public tenders. Three-tier pricing structure across premium, standard, and economy levels separates oncology-configured systems with sub-millimeter resolution from portable units and legacy computed radiography replacements. Pricing pressure stems from peso-dollar exchange volatility eroding procurement budgets, with Buenos Aires Province hospitals most price-sensitive due to bulk tender volumes while private diagnostic centers in metropolitan Buenos Aires exhibit lower sensitivity for premium configurations.
Supply Chain Analysis
Argentina's medical device import regulations contain implicit local-content preferences through ANMAT service infrastructure requirements that favor vendors with established biomedical engineering presence. Solid-state detector arrays draw from manufacturing concentrated in Germany, Japan, and the United States, with amorphous silicon substrates and selenium deposition equipment as critical inputs. Single-source vulnerability pervades the flat-panel detector tier where two manufacturers control global production. Distribution runs through Buenos Aires-based import agents holding ANMAT registrations, with provincial procurement offices increasingly demanding direct manufacturer relationships to bypass intermediary markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's digital X-ray market represents a late-cycle quality story where flat-panel detector specifications are displacing computed radiography regardless of price point, rewarding vendors with superior dose efficiency and PACS integration capabilities.
For Market Incumbents: Acquire service infrastructure assets in Córdoba and Santa Fe provinces to defend against unbundling of maintenance contracts from equipment sales. Siemens Healthineers and Koninklijke Philips NV should consolidate multi-hospital maintenance pools before provincial health administrations complete centralization. Backward integration into detector refurbishment capabilities insulates margin pressure from OEM replacement part pricing. For New Entrants and Emerging Players: Launch via teleradiology platform partnerships targeting Patagonian provinces where cloud-based image archiving reduces capital barriers to market entry. Portable X-ray configurations for intensive care units in Córdoba present the most penetrable segment given procurement acceleration and lower incumbent service density. Pursue ANMAT registration through Mercosur harmonization to compress commercial entry timelines relative to direct registration pathways. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists because provincial procurement aggregation is consolidating maintenance demand across hospital networks while biomedical engineering talent scarcity constrains organic scaling. Acquisition targets should combine ANMAT-registered import licenses with established technician training pipelines. Watch ANMAT's alignment with ISO 13485 quality management standards as the inflection signal for regulatory barrier reduction.| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT Registration Acceleration | Mercosur harmonization reduces commercial entry timelines for Brazilian-certified flat-panel detector systems. |
| Provincial Service Infrastructure Buildout | Córdoba's unbundled maintenance pools reward vendors with multi-hospital technician deployment capabilities. |
| Portable System Configuration Focus | Bedside imaging demand in intensive care units bypasses fixed-room installation capital constraints. |
| Telemedicine Platform Integration | Cloud-based PACS connectivity penetrates Patagonian provinces lacking fixed radiography infrastructure. |
| Detector Refurbishment Capability Investment | In-house flat-panel array restoration reduces dependency on OEM replacement pricing and extends asset life. |
Study Parameters
Coverage spans metropolitan Buenos Aires, Córdoba Province, Santa Fe Province, and Patagonian provinces, with primary inputs from each regional cluster triangulated against secondary validation. Interviews with hospital purchasing committees, biomedical engineering directors, ANMAT regulatory affairs specialists, and GPO contracts managers combined with ANMAT registration databases, provincial procurement tender records, and Mercosur harmonization documentation. Bottom-up equipment unit analysis and top-down healthcare expenditure modeling cross-validated market sizing across the analysis window.
Rate-of-change decomposition across technology transitions, regulatory pathway adjustments, and procurement framework evolutions structured the analytical framework. Segmentation dimensions modeled include product type, end user category, detector technology, and clinical application with provincial budget cycle phasing as an Argentina-specific overlay. CAGRs derived from replacement cycle compression for computed radiography systems and penetration curve analysis for flat-panel detector adoption in oncology and orthopedics workflows.
Forecast precision tightens around the base case; tail outcomes carry wider variance under peso devaluation scenarios exceeding historical volatility bands and international logistics disruptions affecting solid-state detector imports. Forecasts reflect assumptions on ANMAT registration timeline stability and provincial health ministry budget execution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
Ultrasound Market
Medical Imaging
Italy Digital Radiology Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
Global Portable Magnetic Resonance Imaging Market