
 Global Mobile Medical Imaging Services Market | 2026-2036
Global Mobile Medical Imaging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Medical Imaging Services Market Foresight
Hospital procurement is consolidating around multi-year service contracts with large mobile imaging fleets. DMS Health leverages its fleet density across the Midwest to lock in exclusive provider agreements. TridentCare anchors its position through deep penetration of skilled nursing facility contracts. RAYUS Radiology differentiates via subspecialty reads bundled with mobile MRI deployment.
Mobile medical imaging services encompass diagnostic imaging modalities—X-ray, CT, MRI, ultrasound, mammography, and PET—delivered via vehicle-mounted or transportable systems to patient locations rather than fixed radiology departments. These services operate through self-contained units housing shielded equipment, onboard power systems, and digital connectivity for teleradiology transmission, enabling point-of-care diagnosis without facility infrastructure investment. CT scan and MRI service types command premium pricing due to equipment costs and specialist interpretation requirements, while ultrasound maintains volume leadership in sports medicine and emergency response applications. Subscription-based and contractual deployment models are gaining preference over pay-per-use structures as health systems seek predictable operating expenditures.
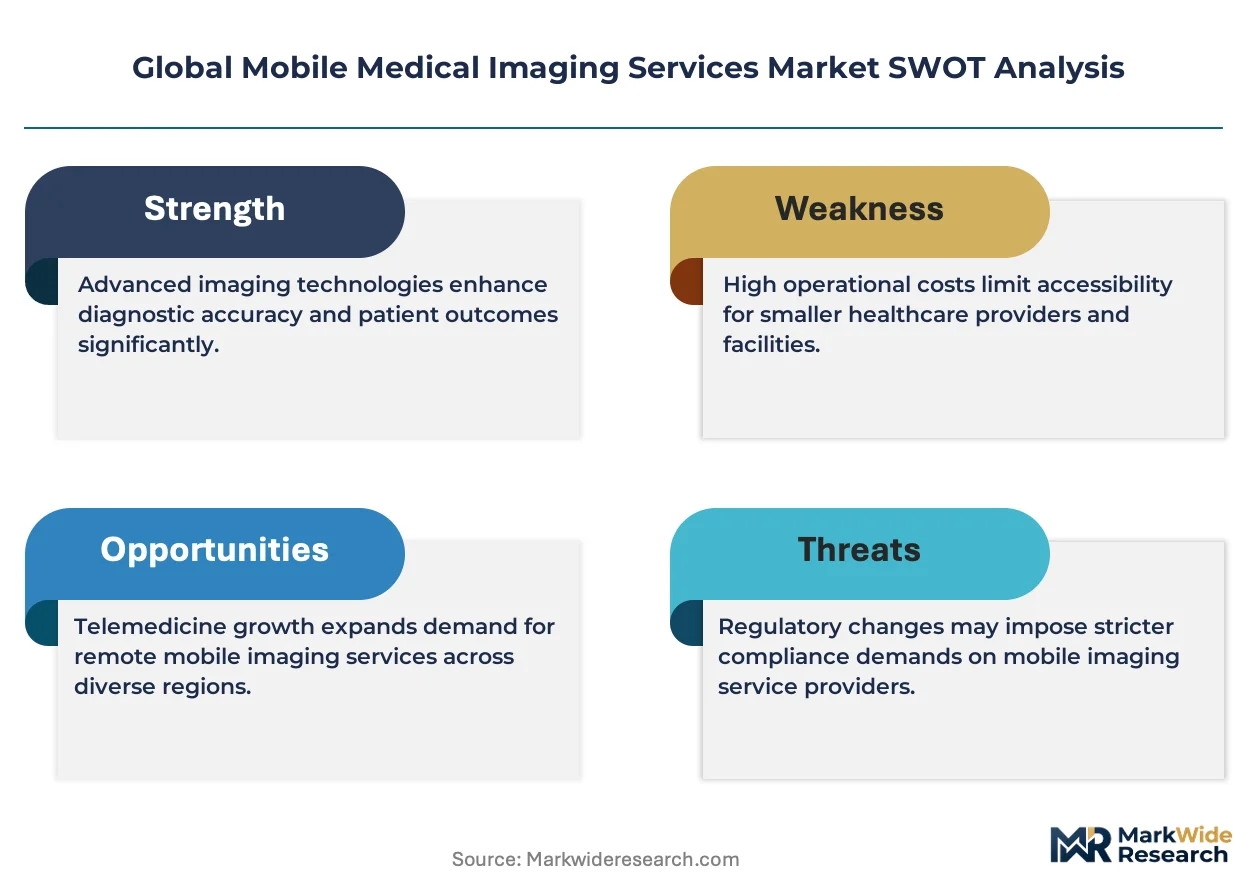
The FDA oversees diagnostic imaging quality standards and equipment performance testing in the United States, while the EU Medical Device Regulation imposes conformity assessment burdens on mobile imaging operators across Europe. ISO 13485 certification and Joint Commission accreditation increasingly function as gatekeepers for hospital contract eligibility. Stakeholders must monitor reimbursement parity between mobile and fixed-site imaging as Medicare and commercial payers recalibrate site-of-service payment differentials.
Market Dynamics
Hospital capital discipline is compressing radiology departments into asset-light service contracts, redirecting equipment ownership risk toward mobile fleet operators who amortize MRI and CT scanners across multiple health system clients.
Growth Catalysts
- Site-neutral payment parity:Medicare's reimbursement alignment between mobile and fixed-site imaging removes financial disincentives for hospital outsourcing. The policy accelerates contractual fleet deployment in rural service areas.
- EU Medical Device Regulation:MDR conformity assessment requirements for mobile imaging equipment create competitive moats for accredited providers. Operators with ISO 13485 certification capture exclusive hospital agreements.
- Skilled nursing facility expansion:Post-acute care networks in the United States deploy mobile X-ray and ultrasound to reduce preventable emergency transfers. Bedside diagnostic capability cuts transport liability exposure.
Market Restraints
- Helium supply concentration:MRI magnet cooling depends on helium sourced from Qatar and the United States. Geopolitical disruption or export constraints raise operating costs for mobile fleet operators.
- Shielding weight penalties:Lead and tungsten radiation shielding in mobile CT units approach federal highway weight limits. Transport logistics constrain equipment specification flexibility.
- Substitution by point-of-care ultrasound:Handheld ultrasound devices from Butterfly Network and Philips reduce demand for mobile van-based echocardiography in emergency departments.
Strategic Opportunities
- India's tier-2 city penetration:Diagnostic imaging access gaps in Lucknow, Jaipur, and Indore favor mobile deployment over fixed infrastructure investment. The country's PLI scheme for medical devices lowers equipment import costs.
- AI-augmented teleradiology:Machine learning triage tools integrated with mobile imaging transmission compress report turnaround times. Subspecialty reads become economically viable in remote deployments.
- Japan's aging population clusters:METI incentives for rural healthcare access support mobile mammography and bone density screening. Prefecture-level contracts offer stable revenue streams.
Industry Challenges
- Radiologist workforce scarcity:Teleradiology networks struggle to staff overnight coverage for mobile fleet transmissions. Interpretation bottlenecks extend report delivery windows.
- Joint Commission accreditation timelines:Mobile imaging providers face 12-18 month certification cycles for hospital contract eligibility. Delayed accreditation blocks revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Medical Imaging Services Market |
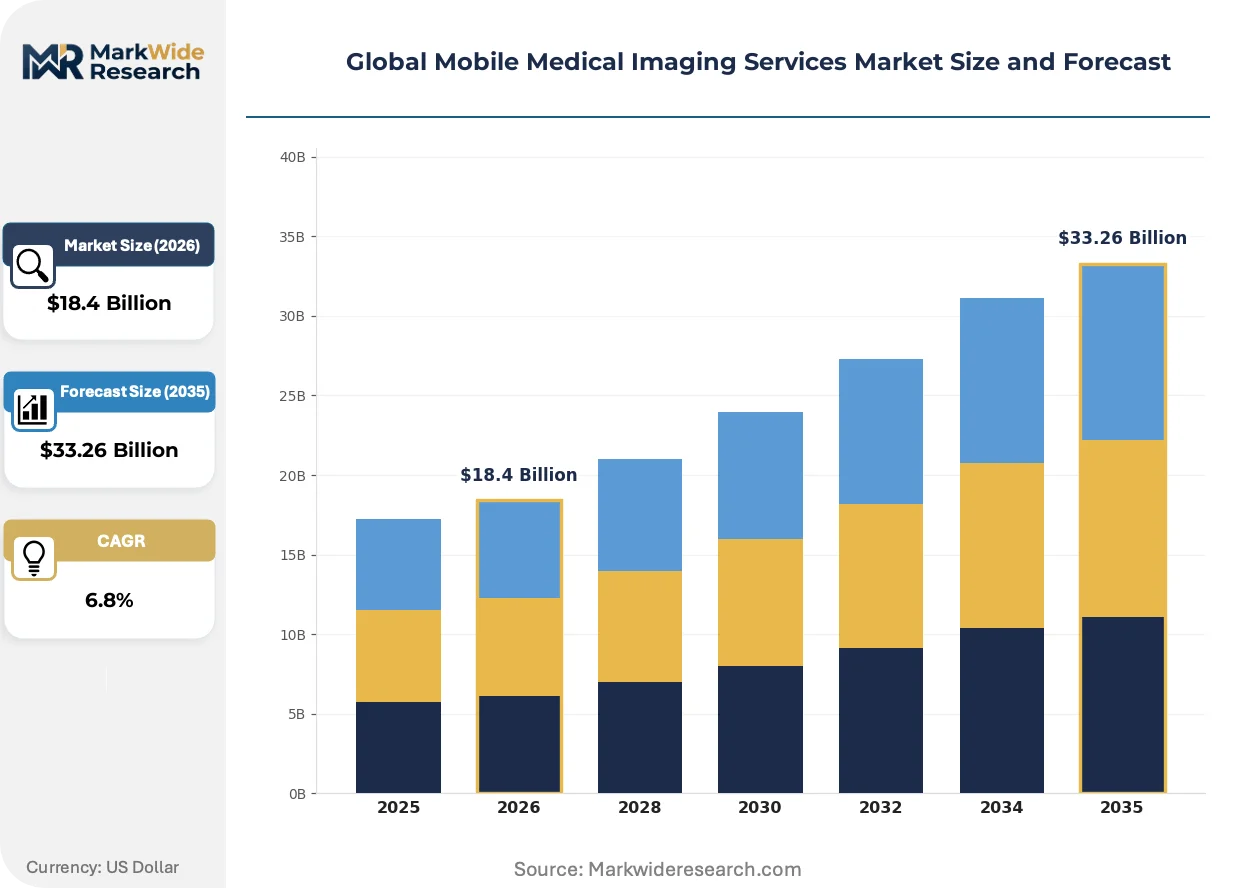
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: X-ray, Ultrasound, MRI, CT Scan, Mammography, PET Scan Application: Emergency Response, Sports Medicine, Orthopedics, Oncology, Cardiology, Neurology End User: Hospitals, Diagnostic Centers, Rehabilitation Clinics, Surgical Centers, Home Healthcare Providers Deployment Model: On-Demand, Subscription-Based, Pay-Per-Use, Contractual, Fleet Ownership |
| Companies Covered | DMS Health, Akumin Inc., TridentCare, Cobalt Health, Front Range Mobile Imaging, Accurate Imaging Diagnostics, RAYUS Radiology, Atlantic Mobile Imaging, InHealth Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Medical Imaging Services Market Shifts & Advancements
Digital connectivity infrastructure and artificial intelligence are compressing the diagnostic workflow from image acquisition to clinical decision, reshaping how mobile services integrate with hospital electronic health records.
Portable MRI systems utilizing permanent magnets and advanced cryocooler designs are absorbing clinical applications previously reserved for fixed 1.5T and 3T scanners. Community hospitals in the United States are piloting these units for stroke protocol imaging. The technology is absorbing emergency department throughput that conventional mobile CT fleets previously captured.
The EU AI Act's risk classification framework for medical device software imposes conformity documentation burdens on mobile imaging operators deploying automated image analysis. European fleet providers must revalidate algorithm performance across diverse patient populations. Mobile mammography services in Germany and France face the steepest compliance adaptation costs.
Subscription-based fleet access contracts are displacing per-scan pricing in United States health system procurement. Risk-bearing accountable care organizations in Texas and Arizona prefer fixed monthly fees for guaranteed mobile MRI availability. The model concentrates purchasing power with multi-hospital networks that negotiate exclusive regional agreements.
Global Mobile Medical Imaging Services Market Segmentation
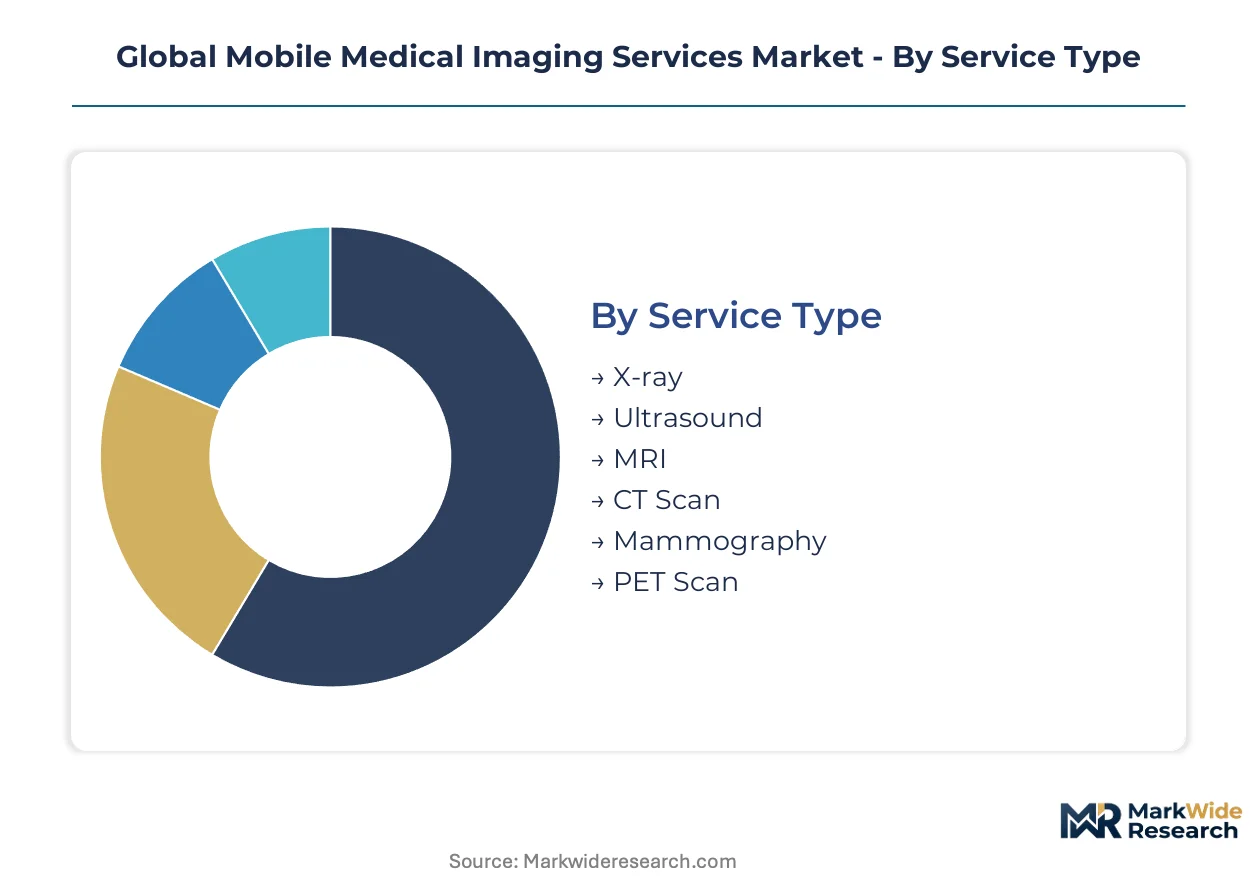
Mobile medical imaging services fragment across equipment cost tiers, clinical workflows, and capital ownership structures. Procurement patterns diverge sharply between emergency response networks seeking on-demand flexibility and health systems optimizing multi-year fleet contracts.
Service Type:
Equipment specifications and shielding requirements separate premium modalities from high-volume portable units.
- CT Scan:Mobile units incorporate lead-shielded gantries and onboard power systems weighing near federal highway limits. Demand concentrates in United States stroke protocol networks where bedside imaging eliminates patient transport risks.
- MRI:Superconducting magnet systems require helium cooling infrastructure and specialized transport logistics. Germany and Japan lead deployment for rural oncology staging where fixed 1.5T scanner installation costs prove prohibitive.
- X-ray:Lightweight digital radiography dominates skilled nursing facility contracts.
- Ultrasound:Cardiac and musculoskeletal applications absorb volume in sports medicine.
- Mammography:Prefecture-level screening programs in Japan drive fleet specialization.
- PET Scan:Radiopharmaceutical logistics constrain mobile deployment to major metropolitan corridors.
Volume sits with X-ray and ultrasound; growth tilts toward MRI as permanent-magnet portable systems reduce helium dependency.
Application:
Clinical urgency and reimbursement parity determine whether mobile deployment substitutes for fixed-site imaging or fills access gaps.
- Emergency Response:Mobile CT units stationed at trauma centers compress door-to-imaging intervals for stroke and head injury protocols. United States hospital networks in Texas and Arizona deploy dedicated fleets for 24/7 availability.
- Oncology:Staging and treatment monitoring require subspecialty radiologist interpretation bundled with mobile PET-CT deployment. India's tier-2 cities favor mobile models over fixed infrastructure investment.
- Sports Medicine:Sideline concussion assessment and musculoskeletal imaging absorb portable MRI and ultrasound volume.
- Orthopedics:Post-operative monitoring drives contractual fleet arrangements.
- Cardiology:Mobile echocardiography faces substitution from handheld point-of-care devices.
- Neurology:Epilepsy monitoring and dementia staging concentrate in academic medical center catchments.
Emergency response commands the steepest pricing premiums; oncology represents the fastest-expanding application as value-based care contracts extend to rural networks.
End User:
Capital constraints and patient throughput shape whether facilities own imaging assets or outsource to fleet operators.
- Hospitals:Asset-light strategies redirect MRI and CT ownership risk toward mobile vendors. Multi-year service contracts with guaranteed availability clauses dominate United States health system procurement.
- Diagnostic Centers:Independent imaging facilities deploy mobile units to extend service radius without facility expansion. India's PLI scheme for medical devices lowers equipment import barriers for tier-2 city operators.
- Rehabilitation Clinics:Post-acute monitoring contracts favor subscription-based X-ray and ultrasound access.
- Surgical Centers:Pre-operative screening drives on-demand CT deployment.
- Home Healthcare Providers:Portable X-ray for bedbound patients concentrates in Medicare Advantage networks.
Hospital systems anchor current revenue; diagnostic centers are gaining share fastest as independent operators exploit equipment cost subsidies.
Deployment Model:
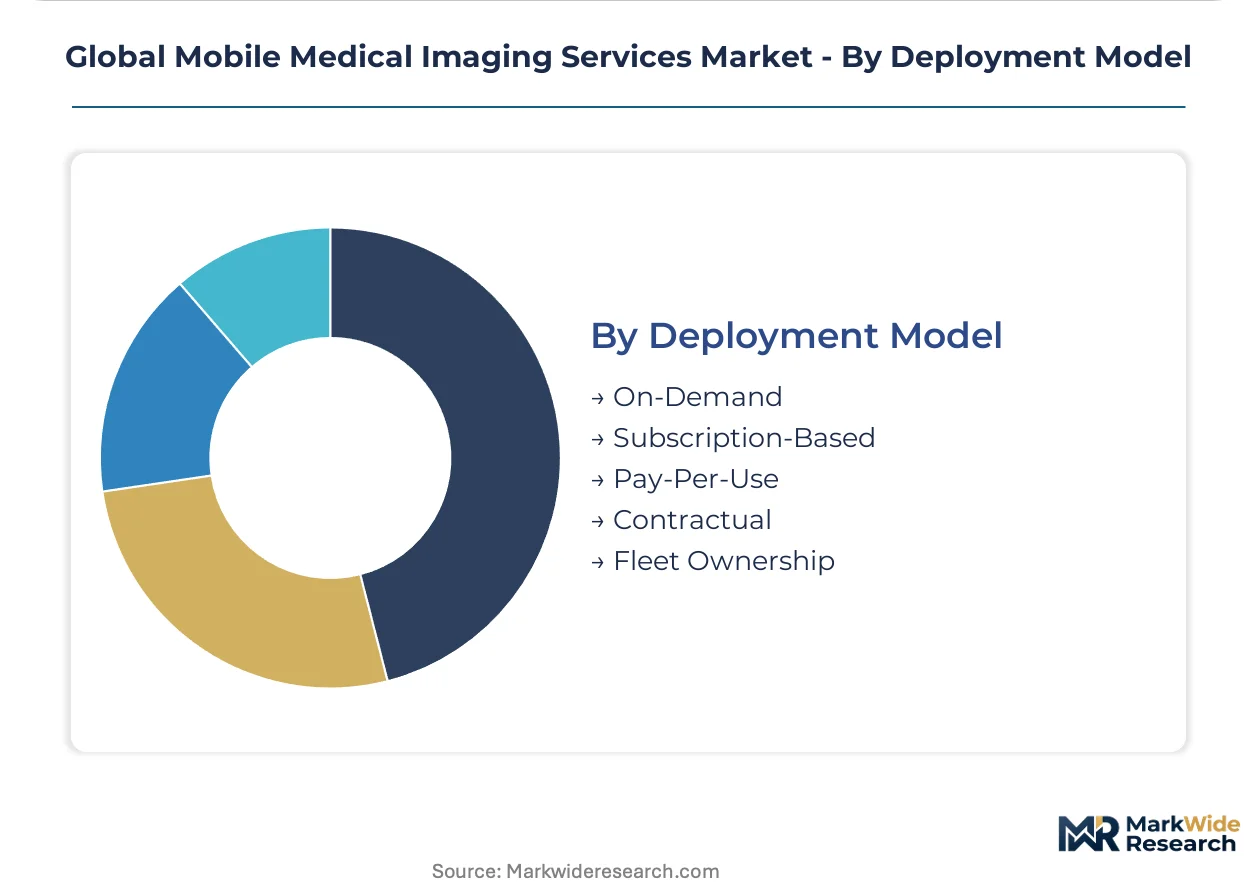
Payment structure alignment with organizational risk tolerance separates contractual commitments from transactional usage.
- Subscription-Based:Fixed monthly fees for guaranteed equipment availability align with accountable care organization budgeting. Texas and Arizona risk-bearing entities negotiate exclusive regional agreements locking out competitor access.
- Contractual:Multi-year fleet service agreements transfer equipment maintenance and regulatory compliance to mobile operators. United States hospital procurement consolidates around three-to-five-year terms with performance guarantees.
- On-Demand:Unscheduled emergency deployment commands premium per-scan rates.
- Pay-Per-Use:Transactional pricing persists in smaller diagnostic centers with irregular volume.
- Fleet Ownership:Health systems with sufficient throughput maintain captive mobile units.
Contractual arrangements dominate hospital procurement; subscription models are expanding most quickly as value-based payment structures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium extraction from Qatar's North Field and the US Hugoton-Panhandle complex anchors mobile MRI logistics chains. These feedstock localities determine fleet deployment economics across radiology outsourcing networks.
United States
Rural hospital closures in Texas and Arizona drive contractual fleet procurement for stroke protocol imaging. Medicare's site-neutral payment parity removes reimbursement disincentives for mobile deployment. The Dallas-Fort Worth corridor concentrates DMS Health fleet density serving multi-hospital networks.
Germany
Bavarian oncology networks favor mobile PET-CT for rural staging where fixed scanner installation costs prove prohibitive. The EU Medical Device Regulation imposes conformity assessment burdens that ISO 13485-certified operators leverage for exclusive agreements. Berlin-Brandenburg clusters academic medical center catchments demanding subspecialty teleradiology.
Japan
METI incentives for rural healthcare access subsidize mobile mammography and bone density screening in aging prefectures. The PMDA oversees diagnostic imaging quality standards for fleet operators. Kansai region contracts offer stable revenue streams for bone density screening fleets.
India
Tier-2 cities including Lucknow, Jaipur, and Indore exhibit diagnostic imaging access gaps favoring mobile over fixed infrastructure. The PLI scheme for medical devices lowers equipment import costs for independent operators. Maharashtra's diagnostic centers exploit subsidies to extend service radius without facility expansion.
United Kingdom
NHS capital constraints compress radiology departments into asset-light service contracts. The Care Quality Commission regulates mobile imaging quality standards for hospital eligibility. London-Southeast procurement consolidates around multi-year agreements with guaranteed availability clauses.
Global Mobile Medical Imaging Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-augmented teleradiology integration. The vendor base stratifies across fleet-scale operators, subspecialty interpretation networks, and regional diagnostic contractors. Three archetypes dominate: multi-hospital contract holders, skilled nursing facility specialists, and academic medical center partners. Competitive positioning hardens through exclusive regional agreements and accreditation-driven credentialing.
Among US-based fleet operators, DMS Health exemplifies the density-driven contract holder archetype across Midwest hospital networks. TridentCare represents the post-acute care specialist model with deep penetration of skilled nursing facility agreements. RAYUS Radiology occupies the subspecialty bundling position, linking mobile MRI deployment with academic-tier interpretation capabilities.
| Leading Market Players |
|---|
| DMS Health |
| Akumin Inc. |
| TridentCare |
| Cobalt Health |
| Front Range Mobile Imaging |
| Accurate Imaging Diagnostics |
| RAYUS Radiology |
| Atlantic Mobile Imaging |
| InHealth Group |
| Others |
Supply & Pricing Matrix
Radiologist workforce scarcity in the United States Midwest and Northeast widens labor-cost differentials between premium subspecialty reads and standard teleradiology interpretations, compressing pricing-tier spreads as mobile fleet operators absorb interpretation overhead into bundled service contracts.
Pricing Analysis
Volume sits with X-ray and ultrasound deployments; margins concentrate in MRI and PET-CT services where helium logistics and radiopharmaceutical cold-chain requirements erect cost barriers. Three-tier pricing structure across premium subspecialty, standard accredited, and economy teleradiology tiers separates Joint Commission-certified providers from regional independents. Cost compression in the economy tier intensifies as handheld point-of-care ultrasound from Butterfly Network and Philips displaces van-based echocardiography. Accountable care organizations in Texas and Arizona exhibit lowest price sensitivity, locking in subscription contracts for guaranteed MRI availability; independent diagnostic centers in India's tier-2 cities face acute price pressure under equipment import subsidy schemes.
Supply Chain Analysis
Dual-sourcing requirements for helium cooling systems now dominate procurement protocols as mobile MRI fleet operators qualify both Qatar and United States Hugoton-Panhandle feedstock suppliers to mitigate geopolitical disruption risk. Superconducting magnet fabrication concentrates in Germany, Japan, and the United States; digital radiography panels source predominantly from South Korea and Japan. Supply chain risk centers on helium export constraints from Qatar's North Field, where regulatory restrictions or regional instability would cascade through magnet cooling logistics. Distribution runs through hospital GPO contracts and exclusive regional service agreements that lock fleet capacity into multi-year commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive teleradiology networks and helium logistics infrastructure is reshaping competitive positioning as fleet operators seek margin defense against interpretation bottlenecks and raw material volatility.
For Market Incumbents: Hedge against radiologist workforce scarcity by acquiring accredited teleradiology practices in underserved time zones, and deepen backward integration into helium reclamation infrastructure to offset Qatar supply concentration risk. Defensive consolidation around ISO 13485-certified maintenance capabilities protects contract renewals as EU MDR conformity timelines extend. For New Entrants and Emerging Players: Skilled nursing facility networks in the United States Southeast represent the most penetrable buyer archetype, with post-acute care operators seeking bedside X-ray and ultrasound to cut emergency transport liability. India's tier-2 diagnostic centers offer white-space expansion under PLI equipment subsidies. A direct-to-facility subscription model bypasses hospital GPO gatekeepers. For Investors and Strategic Acquirers: The window for entry favors mid-scale fleet operators with existing Joint Commission accreditation and locked helium supply contracts. Long-term viability hinges on interpretation network density rather than equipment scale alone. Watch for Medicare site-neutral payment parity expansion into additional modalities as the inflection signal for accelerated outsourcing adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Supply Diversification | Dual-qualifying Qatar and US feedstock sources insulates MRI fleet operators from export disruption. |
| AI-Augmented Teleradiology Integration | Machine learning triage tools compress report turnaround for stroke protocol networks in Texas and Arizona. |
| Joint Commission Accreditation Investment | Twelve-to-eighteen month certification cycles function as competitive moats for hospital contract eligibility. |
| Subscription-Based Fleet Contracts | Fixed monthly fees align with accountable care organization budgeting and concentrate purchasing power. |
| Portable MRI Platform Deployment | Permanent-magnet systems reduce helium dependency and absorb emergency department throughput from CT fleets. |
Research Methodology
Independent corroboration across mobile fleet operators, hospital procurement committees, and teleradiology network executives underwrites the qualitative findings, validated against FDA quality assurance filings, CMS Medicare reimbursement databases, EU MDR conformity assessment records, and GPO contract repositories. Primary interviews with biomedical engineers, skilled nursing facility administrators, and radiologist staffing agencies combined with secondary triangulation across hospital capital expenditure disclosures and medical device import trade data. Bottom-up equipment deployment counts and top-down health system outsourcing expenditure estimates were reconciled.
Comparable-period anchoring to historical mobile imaging adoption curves in the United States rural hospital sector and Japan's prefecture-level screening programs informed the projection framework across the analysis window. Segmentation modeling incorporated service type, deployment model, end-user capital constraints, and regional reimbursement parity dimensions. CAGRs derived from equipment cost amortization schedules, fleet utilization rates, and contractual pricing escalation clauses. Forecast inputs included helium spot price volatility bands and radiologist workforce pipeline data from ACGME residency placement statistics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Medicare site-of-service payment recalibration and EU AI Act algorithm validation requirements for automated image analysis. Deviation in helium export policy from Qatar or United States strategic reserve release protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Europe Nuclear Imaging Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Ga 68 DOTATOC Market