
 Orthopedic Imaging Market | 2026-2036
Orthopedic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Imaging Market Analytics
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote system monitoring. GE Healthcare leverages its Edison AI platform to sustain recurring software income from installed imaging bases. Siemens Healthineers anchors European service penetration through region-specific technical support networks. Philips differentiates via integrated performance guarantees that tie uptime metrics to contract renewal terms.
Orthopedic imaging encompasses diagnostic systems that visualize musculoskeletal structures using ionizing radiation, magnetic fields, or acoustic waves, with spatial resolutions ranging from sub-millimeter CT slices to high-field MRI at 3.0 Tesla, primarily to guide surgical planning and monitor degenerative conditions. X-Ray systems occupy the largest installed base due to capital efficiency and throughput in emergency settings, while MRI captures premium margins from soft-tissue contrast requirements in sports medicine and arthritic assessment. Artificial Intelligence represents the fastest-expanding technology segment as algorithms automate fracture detection and pre-surgical templating, reducing radiologist interpretation time.
The FDA's software-as-a-medical-device pathway and the EU MDR's clinical evidence requirements for imaging software shape product development timelines and market access costs on both sides of the Atlantic. ISO 13485 quality management standards govern manufacturing consistency across all major production sites, with notified body audits intensifying for AI-integrated systems. Stakeholders must weigh regulatory capital requirements against the pace of algorithmic innovation when allocating R&D budgets across geographic markets.
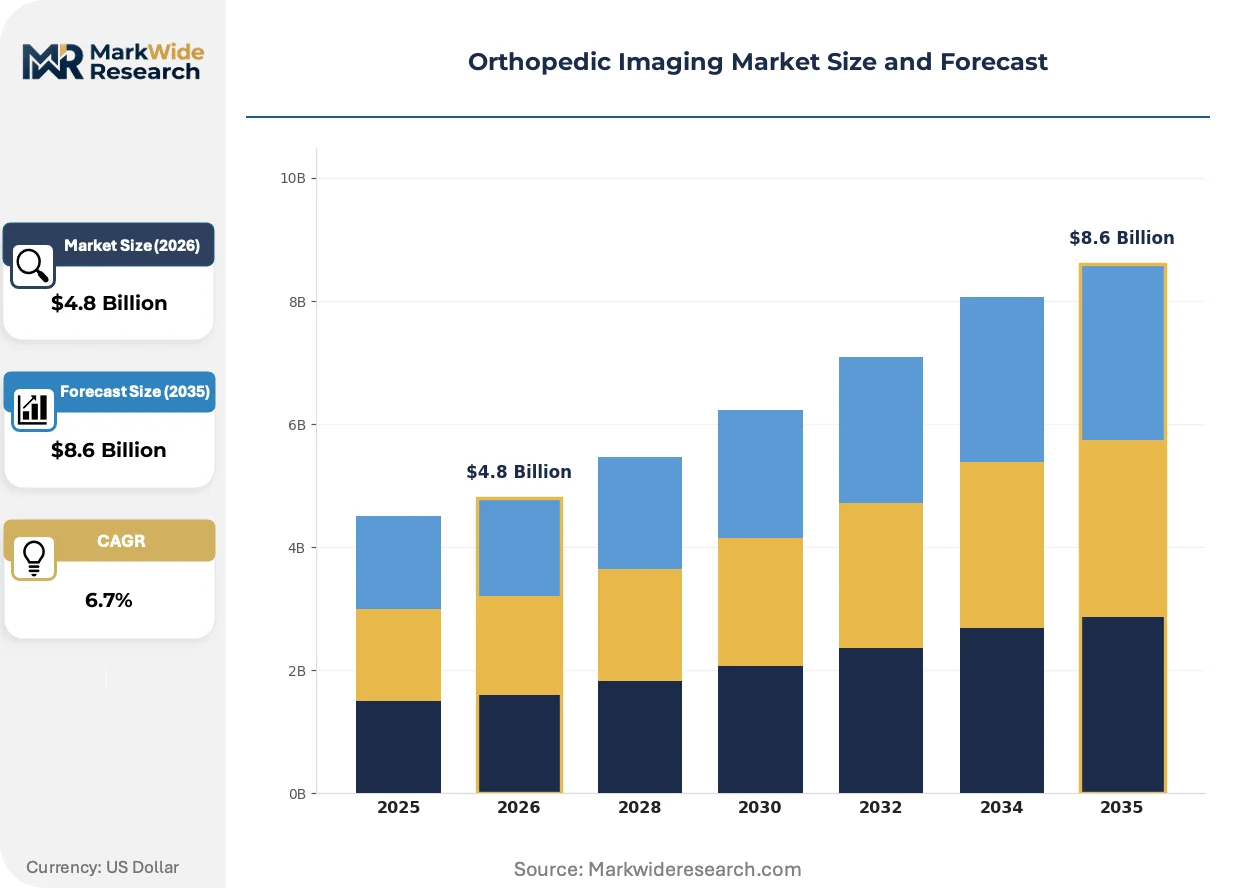
Market Dynamics
The orthopedic imaging market is undergoing a structural reconfiguration as AI-enhanced diagnostic tools compress interpretation workflows and reshape capital allocation toward software-integrated hardware suites.
Growth Catalysts
- FDA Software-as-a-Medical-Device Framework:The United States regulator accelerates clearance pathways for machine-learning diagnostic tools, reducing time-to-market for algorithm developers and encouraging venture deployment into orthopedic applications.
- Hospital Procurement of AI-Enhanced Suites:Acute care facilities prioritize integrated imaging ecosystems that combine hardware acquisition with predictive analytics subscriptions, locking in recurring revenue streams for vendors.
- German R&D Cluster Density:Siemens Healthineers anchors a concentrated network of orthopedic imaging research and manufacturing in Bavaria and Baden-Württemberg, drawing component suppliers and clinical validation partners into geographic proximity.
Market Restraints
- EU MDR Clinical Evidence Requirements:The European Union's Medical Device Regulation imposes extensive clinical validation burdens on imaging software, extending development timelines and inflating regulatory capital requirements for market access.
- Helium Supply Concentration:High-field MRI systems depend on helium for superconducting magnet cooling, with extraction concentrated in Qatar, Russia, and the United States, exposing equipment manufacturers to input price volatility and supply disruption.
- Substitute Modalities in Point-of-Care Settings:Portable ultrasound systems advance into musculoskeletal assessment, displacing low-acuity X-ray volume in emergency departments and sports medicine clinics where immediate diagnosis suffices.
Strategic Opportunities
- Remote Monitoring Service Contracts:Predictive maintenance algorithms applied to installed imaging bases enable vendors to convert episodic repair revenue into recurring subscription income, with GE Healthcare deploying its Edison AI platform across North American hospital networks.
- India Diagnostic Infrastructure Expansion:Government health schemes and private hospital chains drive demand for capital-efficient digital radiography systems in tier-two and tier-three cities, creating white space for mid-range equipment suppliers.
- Convergence of 3D Printing and Pre-Surgical Templating:AI-generated anatomical models integrate directly with additive manufacturing workflows, enabling orthopedic surgeons to validate implant sizing prior to operative intervention.
Industry Challenges
- Radiologist-AI Collaboration Workflows:Healthcare systems struggle to redesign clinical pathways that position algorithmic outputs as decision support rather than replacement, requiring change management investment and staff retraining.
- ISO 13485 Notified Body Audit Intensification:Quality management certification for AI-integrated systems demands expanded documentation of algorithm training data, validation protocols, and post-market surveillance, stretching compliance timelines.
- Legacy PACS Integration Complexity:New imaging platforms must interface with heterogeneous picture archiving and communication systems deployed across hospital networks, fragmenting deployment resources and delaying go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Imaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, MRI, CT Scan, Ultrasound Technology: Digital Imaging, Fluoroscopy, 3D Imaging, Artificial Intelligence Application: Trauma, Sports Injuries, Arthritis, Fractures End User: Hospitals, Diagnostic Centers, Orthopedic Clinics, Research Institutions |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Carestream Health, Hologic Inc., Esaote SpA, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Imaging Market Evolving Landscape
Three active forces are compressing traditional value chains in orthopedic imaging: algorithmic automation of diagnostic tasks, regulatory frameworks accelerating software clearance, and procurement models shifting toward performance-guaranteed service relationships.
Photon-counting CT detectors are collapsing the dose-resolution tradeoff that has constrained musculoskeletal CT applications. Academic medical centers in the United States and university hospitals in Germany are adopting these systems at replacement cycle points, enabling sub-millimeter bone detail at reduced radiation exposure. The technology is collapsing the historical preference for MRI in pediatric and repeat-scan orthopedic populations.
Europe's AI Act risk classification system is creating tiered compliance obligations for diagnostic algorithms. High-risk orthopedic applications—including fracture detection and surgical planning software—face mandatory conformity assessment, third-party auditing, and post-market monitoring. German and French notified bodies are expanding capacity to handle imaging software submissions, while developers restructure quality management systems to satisfy both EU MDR and AI Act requirements simultaneously.
Integrated performance guarantees are displacing traditional break-fix service contracts in hospital procurement. Siemens Healthineers ties contract renewal terms to system uptime metrics across its European installed base, while Philips bundles imaging throughput benchmarks into multi-year agreements. This shift is most visible in the United States, where health system consolidation has concentrated purchasing power and standardized vendor evaluation criteria around total cost of ownership rather than capital expenditure alone.
Orthopedic Imaging Market Segmentation
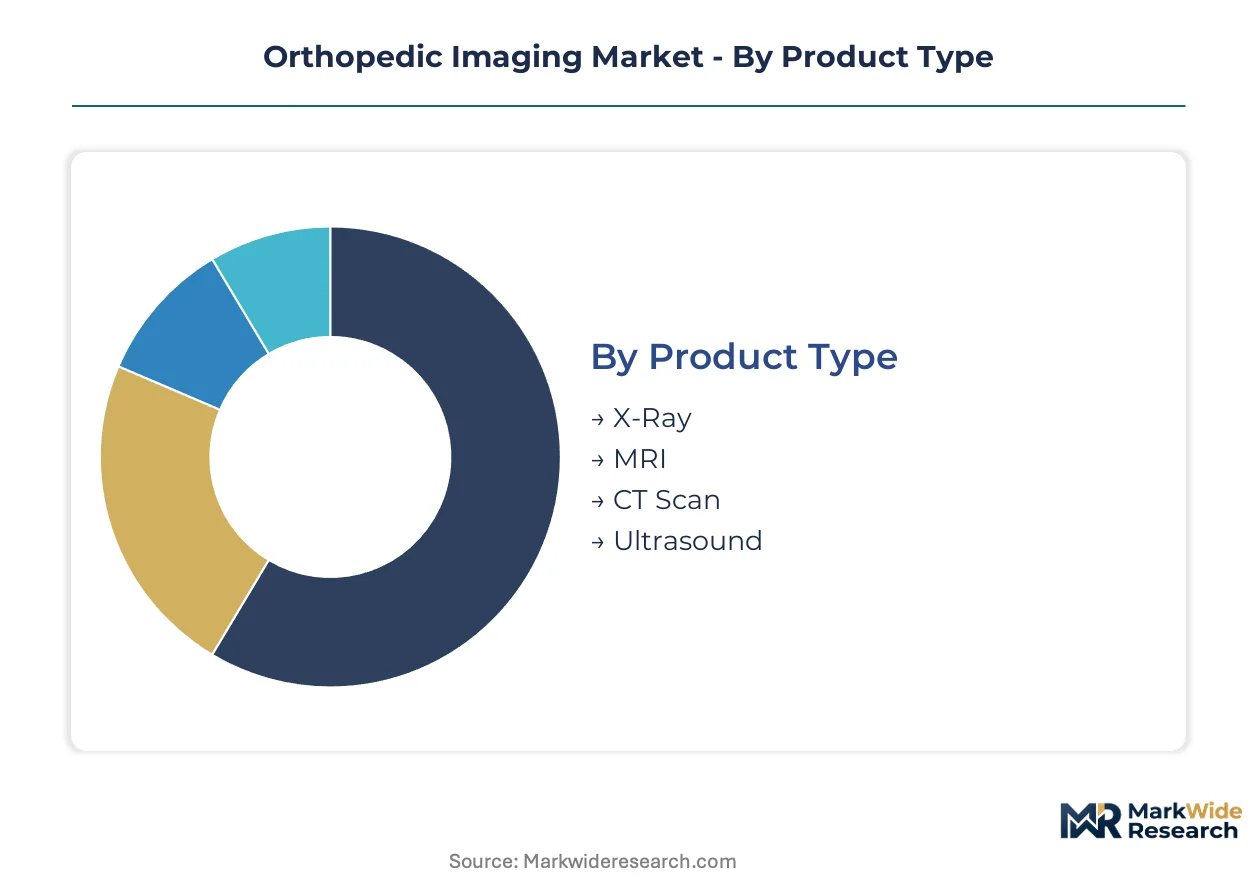
Orthopedic imaging equipment segments exhibit divergent replacement cycles that reshape vendor revenue predictability and hospital capital planning. Product type determines physical asset longevity while technology segments turn over at algorithmic speed.
Product Type:
X-Ray systems rotate through hospital networks fastest due to modular component upgrades, while MRI platforms endure decade-long depreciation schedules anchored by magnet infrastructure investments.
- X-Ray:Digital radiography and fluoroscopy systems deliver sub-millimeter bone visualization at capital costs one-tenth of cross-sectional modalities. Emergency departments in the United States and Germany deploy these systems at highest throughput, with procurement concentrated in hospital systems prioritizing trauma volume.
- MRI:High-field systems at 1.5 Tesla and 3.0 Tesla generate soft-tissue contrast essential for ligament and cartilage assessment in sports medicine. Bavarian university hospitals anchor European demand for research-grade installations, while Japanese academic centers drive adoption of ultra-high-field prototypes.
- CT Scan:Photon-counting detector technology is collapsing dose-resolution tradeoffs for musculoskeletal applications.
- Ultrasound:Portable systems displace low-acuity X-ray volume in point-of-care settings where immediate diagnosis suffices.
X-Ray anchors the volume base while Artificial Intelligence gains share at the steepest rate across all product categories.
Technology:
Technology segments stratify by development velocity, with hardware-dependent modalities requiring multi-year R&D cycles while software layers iterate quarterly.
- Digital Imaging:Flat-panel detectors and computed radiography systems dominate installed bases across mid-tier hospitals in India and Brazil. Government health schemes in tier-two Indian cities drive procurement of cost-efficient digital suites.
- Artificial Intelligence:Machine-learning algorithms for fracture detection and pre-surgical templating compress radiologist interpretation time by automating measurement workflows. FDA software-as-a-medical-device clearance pathways accelerate deployment timelines for algorithm developers targeting United States hospital networks.
- Fluoroscopy:Real-time imaging guides interventional orthopedic procedures with continuous radiation exposure monitoring.
- 3D Imaging:Cone-beam CT and tomosynthesis enable volumetric bone assessment for complex joint reconstruction planning.
Digital Imaging captures the broadest installed footprint while Artificial Intelligence climbs the fastest as hospitals prioritize workflow automation.
Application:
Application demand concentrates in acute trauma settings with highest procedure volume, while chronic condition monitoring generates recurring imaging episodes at lower per-scan revenue.
- Trauma:Emergency department protocols mandate rapid fracture identification and displacement assessment under time pressure. Level I trauma centers in the United States deploy dedicated CT suites with sub-minute scan-to-diagnosis workflows.
- Fractures:Pediatric and geriatric populations drive repeat imaging volume where radiation dose minimization dictates modality selection. German pediatric hospitals increasingly substitute photon-counting CT for traditional MRI in growth plate assessment.
- Sports Injuries:Soft-tissue damage in professional and amateur athletics requires MRI contrast for ligament and meniscus evaluation.
- Arthritis:Degenerative joint disease monitoring generates longitudinal imaging series tracking cartilage loss progression.
Trauma commands the highest throughput volume while Sports Injuries expands most quickly as athletic participation rates climb in emerging markets.
End User:
End user procurement patterns diverge by capital availability and utilization intensity, with consolidated health systems extracting volume discounts unavailable to standalone facilities.
- Hospitals:Acute care facilities integrate imaging suites into surgical service lines with direct revenue attribution to orthopedic departments. United States health system consolidation concentrates purchasing power, standardizing vendor evaluation around total cost of ownership metrics.
- Diagnostic Centers:Independent imaging facilities in India and Southeast Asia compete on turnaround time and price transparency for elective musculoskeletal assessments.
- Orthopedic Clinics:Specialist practices deploy compact MRI and extremity imaging systems for same-day diagnosis.
- Research Institutions:Academic medical centers validate novel imaging biomarkers and AI algorithms through prospective clinical trials.
Hospitals dominate capital expenditure flows while Diagnostic Centers gain share fastest as outpatient imaging migrates from inpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic imaging consumption varies sharply by geography: the United States prioritizes AI-integrated workflow automation, Germany anchors high-field MRI manufacturing density, while India expands digital radiography access through government health infrastructure schemes.
United States
Hospital systems consolidate procurement around total cost-of-ownership metrics, favoring multi-year service contracts with uptime guarantees. FDA software-as-a-medical-device clearances accelerate deployment of fracture-detection algorithms. The Greater Boston corridor hosts dense clusters of AI diagnostic startups collaborating with Massachusetts General and Brigham and Women's for clinical validation.
Germany
Bavarian university hospitals drive demand for research-grade 3.0 Tesla MRI installations, while Baden-Württemberg anchors Siemens Healthineers' manufacturing and R&D headquarters. EU MDR clinical evidence requirements extend software development timelines but create regulatory expertise concentration in Berlin-Brandenburg notified bodies. The Munich-Stuttgart axis draws component suppliers and orthopedic clinical trial networks into geographic proximity.
India
Government health schemes and private hospital chains expand digital radiography procurement into tier-two and tier-three cities. CDSCO medical device regulations govern import and local manufacturing compliance for imaging equipment. Maharashtra and Karnataka host the densest concentrations of diagnostic center chains competing on turnaround time and price transparency for elective musculoskeletal assessments.
Japan
Academic medical centers in Kanto and Kansai regions drive adoption of ultra-high-field MRI prototypes for cartilage biomarker research. PMDA regulatory frameworks emphasize post-market surveillance for AI-integrated diagnostic tools. The Nagoya-Osaka industrial corridor maintains specialized manufacturing capabilities for precision detector components supplying domestic and export markets.
United Kingdom
NHS England procurement frameworks standardize imaging equipment evaluation around interoperability with legacy PACS infrastructure. MHRA regulations align with EU MDR requirements while maintaining distinct UKCA marking obligations post-Brexit. The Oxford-Cambridge-London triangle concentrates academic research institutions validating novel imaging biomarkers and surgical planning algorithms.
Orthopedic Imaging Market Competitive Landscape
Capability concentration sits with integrated imaging-systems manufacturers; scale advantage sits with diversified health-technology conglomerates. The market structure reflects a tiered hierarchy where premium-tier vendors bundle hardware with predictive analytics subscriptions, mid-tier suppliers compete on capital efficiency, and regional specialists dominate service-intensive aftermarket relationships. Strategic archetypes include AI-platform integrators, photon-counting CT specialists, and emerging-market cost optimizers. Dominant competitive moves encompass predictive maintenance contract conversion and 3D surgical-templating software integration.
Among diversified health-technology conglomerates, GE Healthcare, Siemens Healthineers, and Koninklijke Philips N.V. occupy positions that exemplify the integrated-systems archetype. GE Healthcare anchors North American service penetration through AI-enabled remote monitoring platforms. Siemens Healthineers represents European manufacturing density and regulatory expertise concentration. Koninklijke Philips N.V. sits within the premium-tier vector where performance-guaranteed contracts displace traditional break-fix service relationships. These three entities collectively illustrate how vendor strategy converges on recurring revenue models rather than episodic capital equipment sales.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Hologic Inc. |
| Esaote SpA |
| Shimadzu Corporation |
| Others |
Value Network & Pricing Analysis
Bavarian manufacturing clusters anchor global MRI magnet production, concentrating superconducting coil fabrication in Erlangen and Forchheim. This geographic density grants Siemens Healthineers substantial pricing leverage on high-field systems, while helium supply volatility from Qatar and Russia feeds cost uncertainty into long-term service contracts.
Pricing Analysis
Long-term service contracts with performance-guaranteed uptime clauses now dominate hospital procurement, displacing spot-equipment purchases. Three-tier pricing structure across premium AI-integrated suites, standard digital radiography, and economy refurbished systems differentiates by software capability and ISO 13485 certification tier. Pricing pressure stems from portable ultrasound displacing low-acuity X-ray volume in emergency departments. Diagnostic centers in India exhibit highest price sensitivity, while United States health systems prioritize total cost-of-ownership metrics over capital expenditure.
Supply Chain Analysis
Contract manufacturing for flat-panel detectors concentrates in Japan and South Korea, with Shimadzu and Canon Medical Systems retaining in-house production of precision scintillator crystals. Rare earth elements for MRI magnets draw from Chinese separation facilities, while helium extraction rests on Qatari and United States gas fields. Single-source vulnerability in superconducting wire supply from Japanese specialty metal producers threatens magnet production continuity. Distribution runs through authorized service networks rather than direct hospital relationships, with regional technical support hubs determining aftermarket capture rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FDA-cleared AI diagnostic algorithms for fracture detection and surgical planning creates asymmetric returns for developers who navigate 510(k) pathways successfully. The capability gap sits between algorithm training expertise and clinical validation infrastructure.
For Market Incumbents: Insulate installed base revenue through predictive maintenance contract conversion, leveraging remote monitoring platforms to lock in recurring software income. Backward integration into photon-counting detector manufacturing reduces dependency on Japanese component suppliers. Prioritize ISO 13485 quality management certification for AI-integrated systems ahead of EU MDR audit intensification. For New Entrants and Emerging Players: Establish a beachhead in tier-two Indian cities where government health schemes expand digital radiography access and incumbent service networks remain underdeveloped. Target compact extremity MRI systems for orthopedic clinics seeking same-day diagnosis capabilities without hospital capital commitments. Pursue CDSCO regulatory clearance as a faster pathway to commercial presence than FDA or EU MDR routes. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI-platform vendors with FDA software-as-a-medical-device clearances and hospital system integration partnerships. Long-term viability favors developers with proprietary training datasets and post-market surveillance infrastructure. Watch FDA enforcement discretion letters on AI diagnostic algorithms as an inflection signal for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm FDA Clearance | FDA software-as-a-medical-device pathway accelerates time-to-market for fracture detection tools. |
| Predictive Maintenance Platform | GE Healthcare's Edison AI platform converts episodic repair revenue into subscription income across North American networks. |
| Photon-Counting CT Deployment | Academic medical centers in Germany and the United States adopt sub-millimeter bone detail at reduced radiation exposure. |
| India Diagnostic Infrastructure Partnership | Private hospital chains in Maharashtra and Karnataka expand digital radiography procurement into underserved tier-two cities. |
| 3D Surgical Templating Integration | AI-generated anatomical models connect directly to additive manufacturing workflows for pre-operative implant validation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and orthopedic surgeons; and secondary validation against FDA 510(k) filings, CDSCO medical device registrations, hospital procurement databases, and CMS Medicare imaging utilization data. Bottom-up equipment unit economics triangulated against top-down health system capital expenditure surveys.
Forecast inputs span product type replacement cycles, technology adoption curves for AI integration, application volume growth in trauma and sports medicine, and end-user procurement consolidation patterns across the analysis window. Segmentation modeling incorporates modality type, field strength tier, software capability level, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to historical adoption data and elasticity-adjusted price trajectories.
Stress conditions across helium supply disruption, EU MDR audit delays, and portable ultrasound substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory clearance timelines and hospital capital availability. Quarterly review of FDA AI diagnostic tool enforcement patterns and notified body capacity expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Teleradiology Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
X-Ray Film Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Global Veterinary Radiography System Market