
 Robotic Angiography Systems Market | 2026-2036
Robotic Angiography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Angiography Systems Market Analytics
High-definition 3D rotational angiography is rotating toward the center of purchasing criteria for new system installations. Siemens Healthineers leverages its ARTIS pheno platform to dominate premium hybrid OR deployments across Western Europe. GE HealthCare Technologies Inc anchors its competitive stance through deep backward integration into detector manufacturing and proprietary image reconstruction software. Canon Medical Systems Corporation differentiates via specialized vascular imaging protocols optimized for neurointerventional workflows.
Robotic angiography systems integrate motorized C-arm positioning, digital flat-panel detectors, and real-time 3D roadmapping to enable minimally invasive catheter-based diagnosis and treatment of vascular disease. Cath lab systems command the largest installed base but hybrid OR configurations capture the fastest replacement cycle as hospitals consolidate interventional and surgical capabilities into single suites. Digital imaging technology leads current revenue contribution while optical coherence tomography integration represents the emerging functional layer for intravascular plaque characterization during coronary procedures.
FDA 510(k) clearance requirements and IEC 60601-1 third-edition electrical safety standards shape hardware design timelines and software validation burdens for manufacturers seeking US market access. The EU Medical Device Regulation enforces stricter clinical evidence thresholds for robotic positioning subsystems, extending conformity assessment durations for European launches. Stakeholders must monitor how reimbursement parity between robotic-assisted and conventional angiography procedures evolves across Medicare Administrative Contractors and national health technology assessment bodies.
Market Dynamics
Hybrid operating room configurations are compressing replacement cycles across the installed base as hospitals consolidate interventional cardiology and surgical capabilities into single-suite environments, forcing vendors to reconfigure service architectures around integrated workflow demands.
Growth Catalysts
- FDA 510(k) Streamlining:Expedited clearance pathways for Class II robotic positioning subsystems are accelerating product introductions for US hospital systems seeking cath lab upgrades.
- Minimally Invasive Procedure Volume:Transcatheter aortic valve replacement and neurointerventional thrombectomy growth is driving installed base expansion at academic medical centers.
- German University Hospital Procurement:Bundled purchasing consortia in Bavaria and Baden-Württemberg are anchoring European volume for integrated angiography suites.
Market Restraints
- Flat-Panel Detector Supply Concentration:Amorphous silicon substrate manufacturing concentrates in East Asian foundries, exposing OEMs to single-source input risk.
- EU MDR Conformity Burden:Stricter clinical evidence thresholds for robotic positioning subsystems extend European launch timelines by 12-18 months.
- Fixed C-Arm Substitution:Conventional biplane angiography systems retain cost advantage for high-volume coronary centers not requiring surgical integration.
Strategic Opportunities
- Optical Coherence Tomography Convergence:Intravascular imaging integration with robotic positioning enables real-time plaque characterization during PCI procedures.
- India Private Hospital Expansion:Corporate hospital chains in Mumbai and Delhi are deploying first-generation robotic systems for cardiac and peripheral interventions.
- Outcome-Based Equipment Leasing:Procedure-volume guarantees are displacing capital purchase models at US health systems managing balance sheet constraints.
Industry Challenges
- Interventionalist Training Bottleneck:Robotic catheter manipulation requires specialized credentialing pathways that academic programs have not standardized.
- Legacy PACS Integration:DICOM connectivity with hospital imaging archives demands custom middleware development for each enterprise deployment.
- Electrical Safety Recertification:IEC 60601-1 third-edition updates force hardware redesigns mid-product-cycle for manufacturers with multi-year validation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Angiography Systems Market |
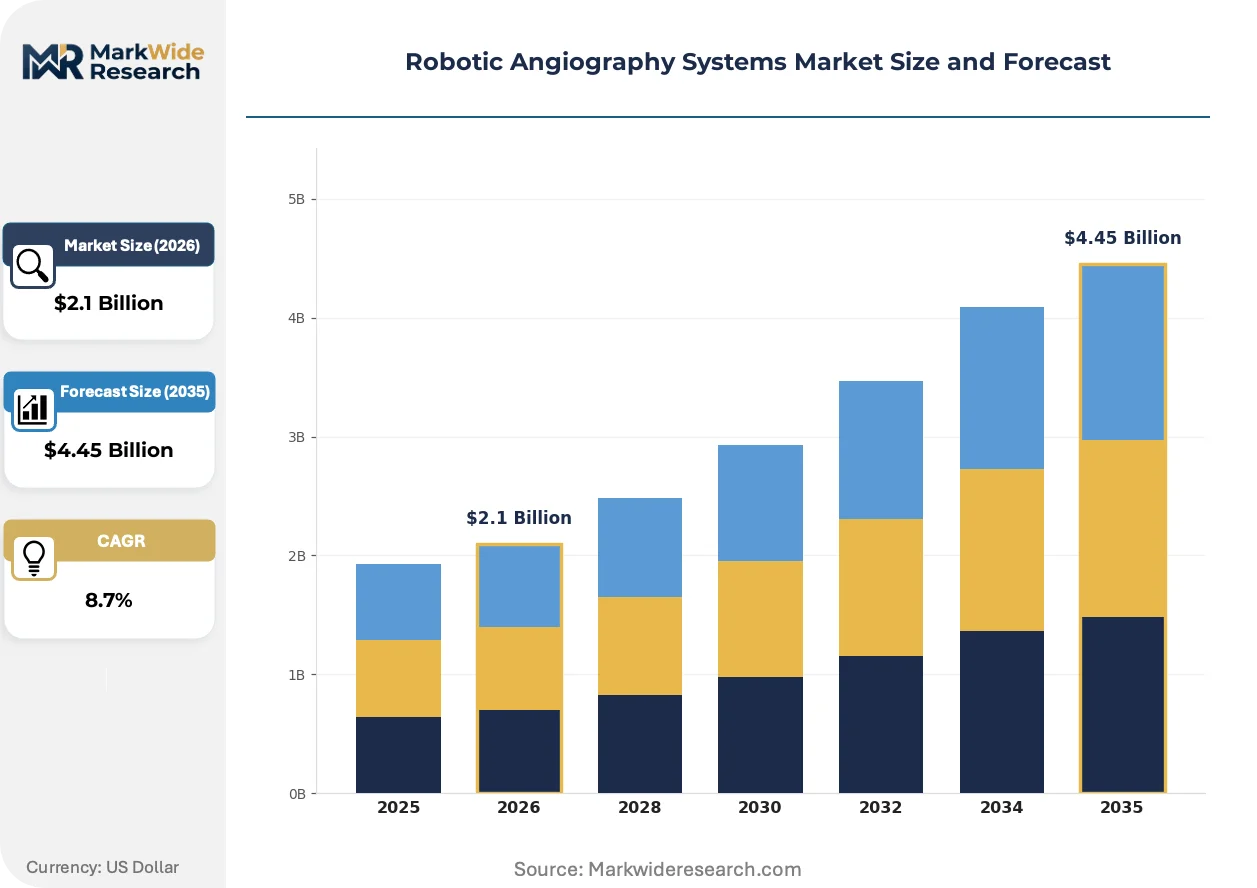
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cath Lab Systems, Hybrid OR Systems, Fluoroscopy Systems, Interventional Radiology Systems Technology: Digital Imaging, 3D Imaging, Optical Coherence Tomography, Ultrasound Imaging End User: Cardiology Centers, Diagnostic Imaging Centers, Hospitals, Outpatient Surgical Centers Application: Coronary Angiography, Neuroangiography, Peripheral Angiography, Interventional Procedures |
| Companies Covered | GE HealthCare Technologies Inc, Siemens Healthineers, Koninklijke Philips N.V., Medtronic Plc, Boston Scientific Corporation, Canon Medical Systems Corporation, Abbott Laboratories, Shimadzu Corporation, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Angiography Systems Market Evolving Landscape
Artificial intelligence is penetrating image reconstruction and catheter navigation workflows, compressing the boundary between diagnostic imaging and therapeutic intervention while forcing vendors to rearchitect software stacks around real-time inference capabilities.
High-definition 3D rotational angiography is decomposing the traditional separation between pre-procedural planning and intra-procedural guidance. Cardiac catheterization laboratories at US academic medical centers are adopting this modality for complex congenital and structural heart interventions. The technology is decomposing standalone CT angiography volumes by delivering comparable spatial resolution without patient transfer.
The EU Medical Device Regulation is enforcing stricter post-market surveillance for robotic positioning subsystems with motorized patient positioning. Manufacturers must now submit periodic safety update reports and maintain clinical evidence registries beyond initial CE marking. German notified bodies are experiencing backlog delays that compress synchronized launch windows across European markets.
After-sales service unbundling is fragmenting vendor-customer relationships as hospital procurement teams negotiate component-level maintenance contracts. Third-party clinical engineering firms are capturing detector calibration and tube replacement volumes previously held by OEM service organizations. This pattern is most visible in the United States where independent service organizations have secured ISO 13485 certification for robotic C-arm repair.
Robotic Angiography Systems Market Segmentation
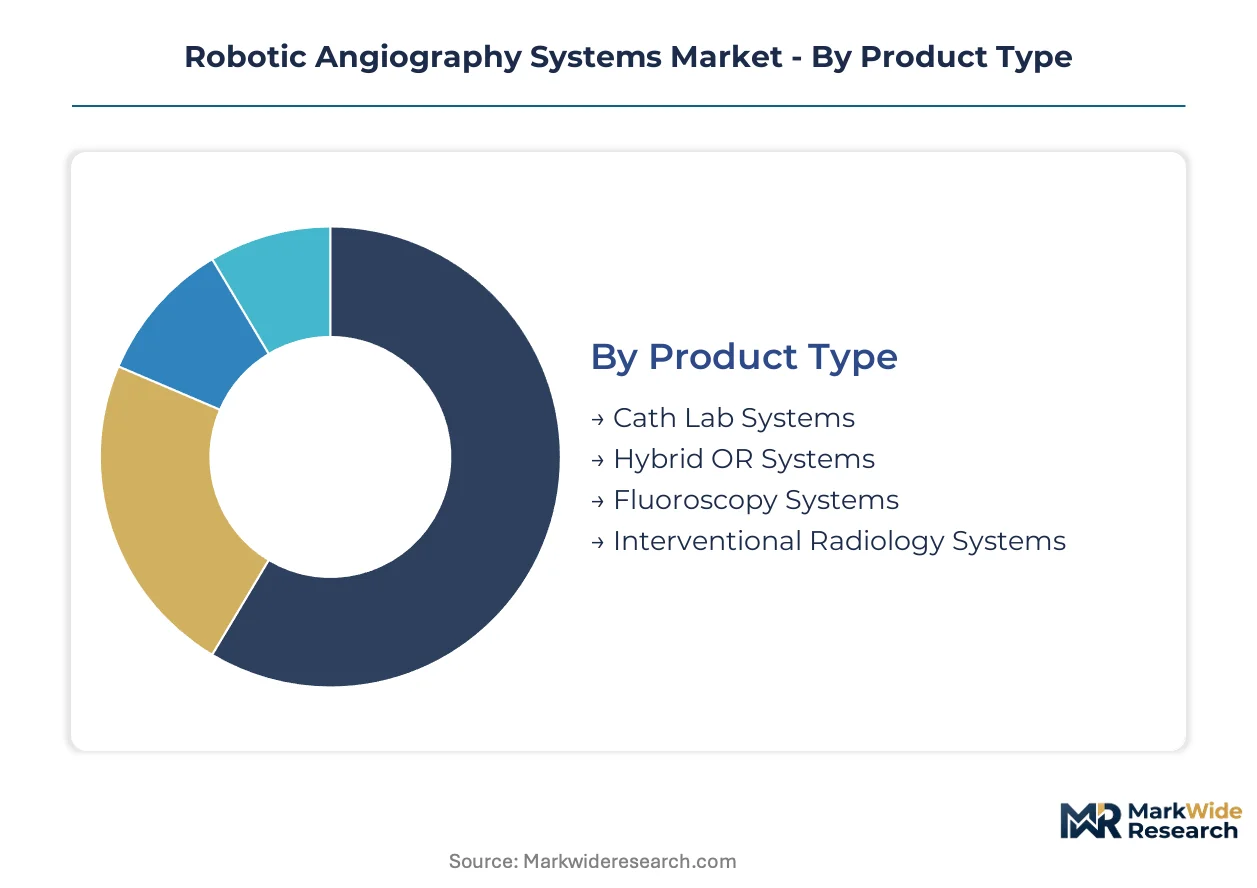
Segmentation in robotic angiography systems reveals how procurement priorities diverge between high-volume coronary centers and integrated surgical suites. Understanding these splits enables vendors to align service architectures with distinct workflow, reimbursement, and infrastructure constraints.
Product Type:
Domestic procurement concentrates in cath lab and hybrid OR configurations across German university hospitals and US academic medical centers, while fluoroscopy and interventional radiology systems serve export markets with constrained capital budgets.
- Cath Lab Systems:Motorized C-arm positioning with digital flat-panel detectors supports high-throughput coronary and peripheral interventions. Demand clusters at US community hospitals and Indian corporate chains where procedure volume justifies dedicated suites but surgical integration remains unnecessary.
- Hybrid OR Systems:Consolidated interventional cardiology and surgical capabilities in single-suite environments with premium imaging chains. German procurement consortia in Bavaria and Baden-Württemberg anchor European adoption, compressing replacement cycles as hospitals consolidate service lines.
- Fluoroscopy Systems:Mobile C-arm configurations for orthopedic and pain management procedures.
- Interventional Radiology Systems:Specialized platforms for oncologic embolization and vascular access.
Cath lab systems hold the largest share; momentum sits with hybrid OR configurations.
Technology:
Cost tier differentiation separates premium 3D imaging and OCT integration from standard digital imaging deployments, with ultrasound occupying mid-tier positioning for vascular access guidance.
- Digital Imaging:Amorphous silicon flat-panel detectors with real-time subtraction angiography. US hospitals prioritize this baseline capability for Medicare-reimbursed coronary procedures, though flat-panel supply concentration in East Asian foundries exposes OEMs to input risk.
- 3D Imaging:High-definition rotational angiography delivering CT-comparable spatial resolution without patient transfer. Academic medical centers adopt this modality for complex congenital and structural heart interventions, decomposing standalone CT angiography volumes.
- Optical Coherence Tomography:Intravascular plaque characterization during PCI with micron-level resolution.
- Ultrasound Imaging:Intravascular and transesophageal guidance for structural heart procedures.
Digital imaging commands current revenue contribution; 3D imaging is expanding most quickly.
End User:
Customer type determines capital intensity and service bundling, with hospitals demanding integrated workflow support while outpatient centers prioritize equipment leasing flexibility.
- Hospitals:Integrated cath lab and hybrid OR deployments with enterprise PACS connectivity and 24/7 clinical engineering coverage. US health systems negotiate outcome-based equipment leasing with procedure-volume guarantees to manage balance sheet constraints.
- Cardiology Centers:Dedicated coronary intervention facilities with high fixed-casing volume.
- Diagnostic Imaging Centers:Peripheral vascular and screening angiography services.
- Outpatient Surgical Centers:Lower-acuity interventions with compressed capital cycles.
Hospitals hold the largest share; momentum sits with cardiology centers.
Application:
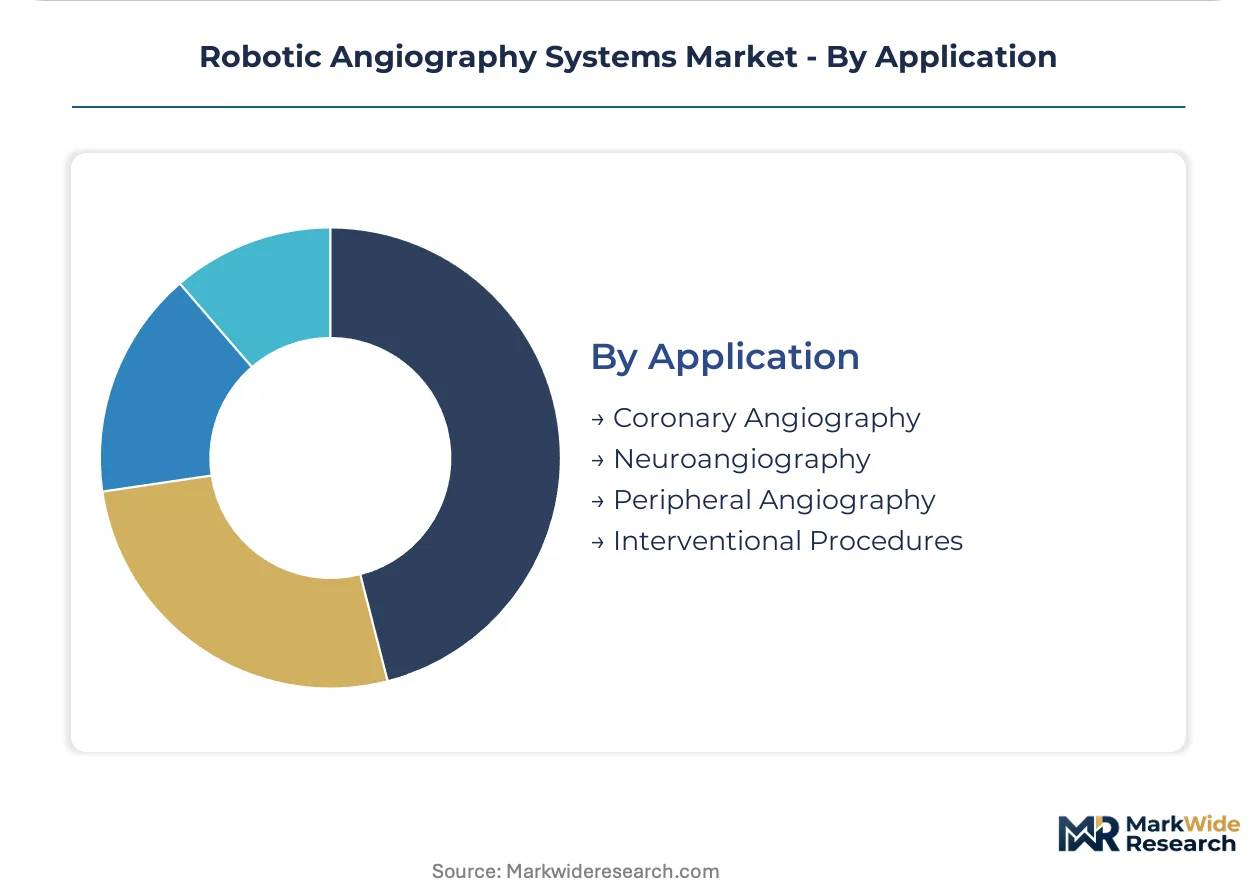
Maturity differentiation separates established coronary procedures from emerging neurointerventional and peripheral vascular workflows, each with distinct regulatory and reimbursement pathways.
- Coronary Angiography:Diagnostic catheterization and percutaneous coronary intervention with established CPT coding and Medicare reimbursement. US centers anchor volume, though transcatheter valve replacement growth is expanding structural heart applications.
- Neuroangiography:Cerebral aneurysm coiling and thrombectomy for acute stroke with specialized biplane imaging requirements. German university hospitals and US comprehensive stroke centers drive adoption as mechanical thrombectomy becomes standard of care.
- Peripheral Angiography:Lower-extremity runoff and renal artery interventions.
- Interventional Procedures:Oncologic embolization and non-vascular applications.
Coronary angiography holds the largest share; neuroangiography is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across geographies. German university hospitals absorb premium pricing for hybrid OR configurations, while Indian private chains negotiate aggressively on first-generation system costs.
United States
Academic medical centers in Boston and Houston drive demand for 3D rotational angiography integration with robotic positioning. FDA 510(k) clearance pathways for Class II robotic positioning subsystems accelerate cath lab upgrade cycles. Hybrid OR deployments concentrate at Cleveland Clinic and Mayo Clinic campuses where surgical and interventional consolidation justifies capital intensity.
Germany
Bavaria and Baden-Württemberg procurement consortia anchor European volume for integrated angiography suites. EU MDR conformity assessments for robotic positioning subsystems extend launch timelines through notified body backlogs. University hospitals in Munich and Heidelberg compress replacement cycles as bundled purchasing consolidates service line integration.
India
Corporate hospital chains in Mumbai and Delhi deploy first-generation robotic systems for cardiac and peripheral interventions. CDSCO medical device registration requirements shape import timelines for foreign OEMs. Apollo Hospitals and Fortis Healthcare anchor private sector adoption in metropolitan clusters where procedure volume growth outpaces public infrastructure.
China
Provincial hospital networks in Shanghai and Beijing prioritize domestic robotic angiography alternatives amid import substitution policies. NMPA Class III medical device registration enforces clinical trial requirements for robotic positioning features. Local manufacturers capture mid-tier municipal hospital procurement through cost positioning against established multinationals.
Japan
Comprehensive stroke centers in Tokyo and Osaka drive neurointerventional system upgrades for thrombectomy standardization. PMDA pre-market approval processes for motorized C-arm subsystems align with IEC 60601-1 third-edition electrical safety standards. University hospitals in the Kanto region anchor premium hybrid OR adoption for structural heart procedure consolidation.
Robotic Angiography Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the installed base. Premium hybrid OR configurations concentrate among integrated imaging conglomerates with captive detector manufacturing and proprietary reconstruction software. Mid-tier cath lab systems fragment across regional specialists with modular positioning architectures and third-party detector sourcing. Dominant competitive moves include backward integration into flat-panel substrate manufacturing and outcome-based equipment leasing with procedure-volume guarantees.
Among diversified health technology conglomerates, GE HealthCare Technologies Inc and Siemens Healthineers occupy positions defined by imaging chain integration and hybrid OR workflow optimization. Canon Medical Systems Corporation exemplifies the specialized vascular imaging archetype with neurointerventional protocol differentiation. Koninklijke Philips N.V. sits within the interventional systems tier where intravascular imaging convergence with robotic positioning drives portfolio architecture.
| Leading Market Players |
|---|
| GE HealthCare Technologies Inc |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Medtronic Plc |
| Boston Scientific Corporation |
| Canon Medical Systems Corporation |
| Abbott Laboratories |
| Shimadzu Corporation |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance requirements and IEC 60601-1 third-edition electrical safety standards gate both supplier qualification and price differentiation simultaneously, compressing vendor margins for mid-tier cath lab configurations while amplifying premium capture for hybrid OR systems with integrated robotic positioning subsystems.
Pricing Analysis
After-sales service contracts and extended warranty tiers now drive lifetime value beyond initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates integrated hybrid OR suites from modular cath lab configurations and refurbished legacy installations. Cost compression in the mid-tier is intensifying because third-party clinical engineering firms have secured ISO 13485 certification for detector calibration and tube replacement. Community hospital procurement committees exhibit the highest price sensitivity, while German university hospital consortia absorb premium positioning for surgical integration capabilities.
Supply Chain Analysis
Inventory buffers for amorphous silicon flat-panel detectors have compressed to twelve-to-sixteen-week lead times, exposing OEMs to demand volatility. Manufacturing concentrates in Japan, South Korea, and Taiwan for detector substrates, while precision motor assemblies source from Germany and Switzerland. Single-source vulnerability in East Asian foundry capacity for amorphous silicon substrates threatens production continuity for mid-tier system vendors. Distribution runs through direct OEM sales teams for hospital systems and specialized medical device distributors for regional clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity: detector calibration contracts and tube replacement agreements are expanding faster than hardware unit shipments as third-party clinical engineering firms fragment the aftermarket.
For Market Incumbents: Secure captive supply of amorphous silicon detector substrates through backward integration or long-term offtake agreements with East Asian foundries. Lock hospital system relationships through outcome-based equipment leasing with procedure-volume guarantees to defend against third-party service unbundling. FDA 510(k) clearance pathway acceleration represents the critical regulatory lever for compressing competitor launch windows. For New Entrants and Emerging Players: Differentiate on optical coherence tomography integration with robotic positioning for real-time plaque characterization during PCI procedures. Target Indian corporate hospital chains in Mumbai and Delhi deploying first-generation systems for cardiac interventions. Pursue CDSCO registration partnerships with established import distributors to bypass direct regulatory infrastructure investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across outcome-based equipment leasing models as procedure-volume guarantees displace capital purchase structures. Acquisition targets should cluster around third-party clinical engineering firms with ISO 13485 certification for robotic C-arm repair and detector calibration capabilities. Monitor Medicare Administrative Contractor reimbursement parity determinations between robotic-assisted and conventional angiography procedures as the signal for hardware demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Manufacturing | Captive supply of amorphous silicon substrates insulates GE HealthCare and Siemens Healthineers from East Asian foundry concentration risk. |
| Outcome-Based Equipment Leasing | Procedure-volume guarantees at US health systems displace capital purchase models and compress competitor access to hospital procurement committees. |
| OCT-Robotic Convergence Development | Real-time intravascular plaque characterization during PCI differentiates Canon Medical Systems in neurointerventional workflow optimization. |
| Third-Party Service Organization Certification | ISO 13485 accreditation for independent clinical engineering firms fragments OEM aftermarket revenue and compresses service attach rates. |
| EU MDR Clinical Evidence Registry Investment | Periodic safety update report infrastructure extends conformity assessment capabilities for robotic positioning subsystem launches across German notified bodies. |
Research Methodology
Operator-level perspectives from cath lab directors, hospital purchasing committee chairs, biomedical engineering managers, and GPO contracts specialists anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary sources including FDA 510(k) clearance databases, CMS Medicare reimbursement filings, hospital procurement contract registries, and EU MDR notified body conformity assessment records. Bottom-up installed base modeling and top-down healthcare capital equipment spending analysis converged on volume and value estimates.
Sensitivity analysis across regulatory approval timelines, reimbursement parity scenarios, and supply chain disruption probabilities tested forecast robustness. Segmentation dimensions modeled include product configuration, imaging technology tier, end-user facility type, and clinical application area. CAGRs were derived from procedure volume growth trajectories, replacement cycle compression patterns, and technology adoption S-curve positioning across the projection horizon. Forecast inputs incorporated transcatheter procedure volume expansion at academic medical centers and EU MDR conformity assessment backlog durations.
Material uncertainties — reimbursement policy reversals, single-source detector substrate supply interruptions, and interventionalist training pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and hospital capital budget continuity. Revision becomes warranted when Medicare Administrative Contractor coverage determinations for robotic-assisted procedures cross threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Lacrimal Devices Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
France Ultrasound Devices Market
Medical Devices
Global Surgical Polypropylene Mesh Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Hip Kits Market
Medical Devices
Global Blood Banking Devices Market