
 Global Cardiac Imaging Software Market | 2026-2036
Global Cardiac Imaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Imaging Software Market Foresight
Hospital procurement channels for cardiovascular diagnostics is rewriting vendor access dynamics across developed markets. Siemens Healthineers leverages direct enterprise sales teams to sustain installed-base loyalty across integrated delivery networks. GE HealthCare anchors its position through embedded AI workflows within CT and MRI hardware ecosystems. Philips competes via subscription-based cloud deployment models that reduce upfront capital barriers for mid-sized cardiology clinics.
Cardiac imaging software encompasses computational platforms that reconstruct, quantify, and visualize anatomical and functional cardiac data from modalities including echocardiography, computed tomography angiography, magnetic resonance imaging, and nuclear medicine, typically processing DICOM-standard datasets through proprietary algorithms to generate ejection fraction measurements, strain curves, perfusion maps, and coronary plaque characterizations for clinical decision support. CT angiography software dominates current revenue pools due to widespread coronary artery disease screening protocols, while 3D echocardiography and strain imaging represent the fastest-expanding segments as transcatheter structural heart procedures demand precise pre-procedural planning. Deployment mode analysis reveals cloud-based architectures capturing disproportionate new-install growth by enabling remote interpretation workflows and multi-site image sharing without on-premise infrastructure investments.
FDA premarket notification requirements, EU MDR technical documentation mandates, and Japan PMDA software-as-medical-device classifications collectively elevate compliance costs but simultaneously filter out undercapitalized entrants unable to sustain clinical validation studies. ISO 13485 quality management certification has become table stakes for OEM partnerships, with IEC 62304 software lifecycle standards governing development protocols for algorithm-driven diagnostic outputs. Stakeholders must monitor evolving FDA guidance on machine learning-enabled devices and EU AI Act risk classifications to anticipate validation burden shifts.
Market Dynamics
Cloud-native deployment architectures are compressing sales cycles and forcing incumbents to rebuild licensing frameworks around subscription economics rather than perpetual seat sales.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for AI-enabled diagnostic modules reduce time-to-revenue for algorithm developers targeting coronary CT angiography workflows.
- Integrated delivery networks:Hospital consolidation in the United States creates集中采购 power that favors enterprise-wide software contracts over point solutions.
- Strain imaging algorithms:3D echocardiography analysis tools enable precise left atrial appendage occlusion planning, driving replacement of manual volumetric assessment in structural heart programs.
Market Restraints
- EU MDR technical documentation:Expanded clinical evidence requirements for software-as-medical-device classifications extend validation timelines and burn capital for mid-stage vendors.
- GPU supply concentration:Dependence on NVIDIA data center accelerators for real-time CT reconstruction creates input cost volatility and allocation risk.
- On-premise infrastructure lock-in:Legacy PACS installations in German university hospitals resist cloud migration, constraining addressable market for SaaS-native entrants.
Strategic Opportunities
- China NMPA green channel:Priority review pathways for AI diagnostic software accelerate market entry for coronary plaque characterization tools in tier-1 city hospital networks.
- Remote interpretation networks:Teleradiology platforms enable cross-border cardiac CT reads from India to Gulf Cooperation Council states, opening new service revenue pools.
- Japan PMDA software classification:Explicit guidance on machine learning-enabled device categories reduces regulatory uncertainty for predictive analytics modules.
Industry Challenges
- Interoperability standards fragmentation:DICOM-RT, HL7 FHIR, and proprietary vendor formats create integration friction with existing cardiovascular information systems.
- Clinical validation workforce:Shortage of imaging informaticists capable of structuring ground-truth datasets for FDA algorithm training stalls product development pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Imaging Software Market |
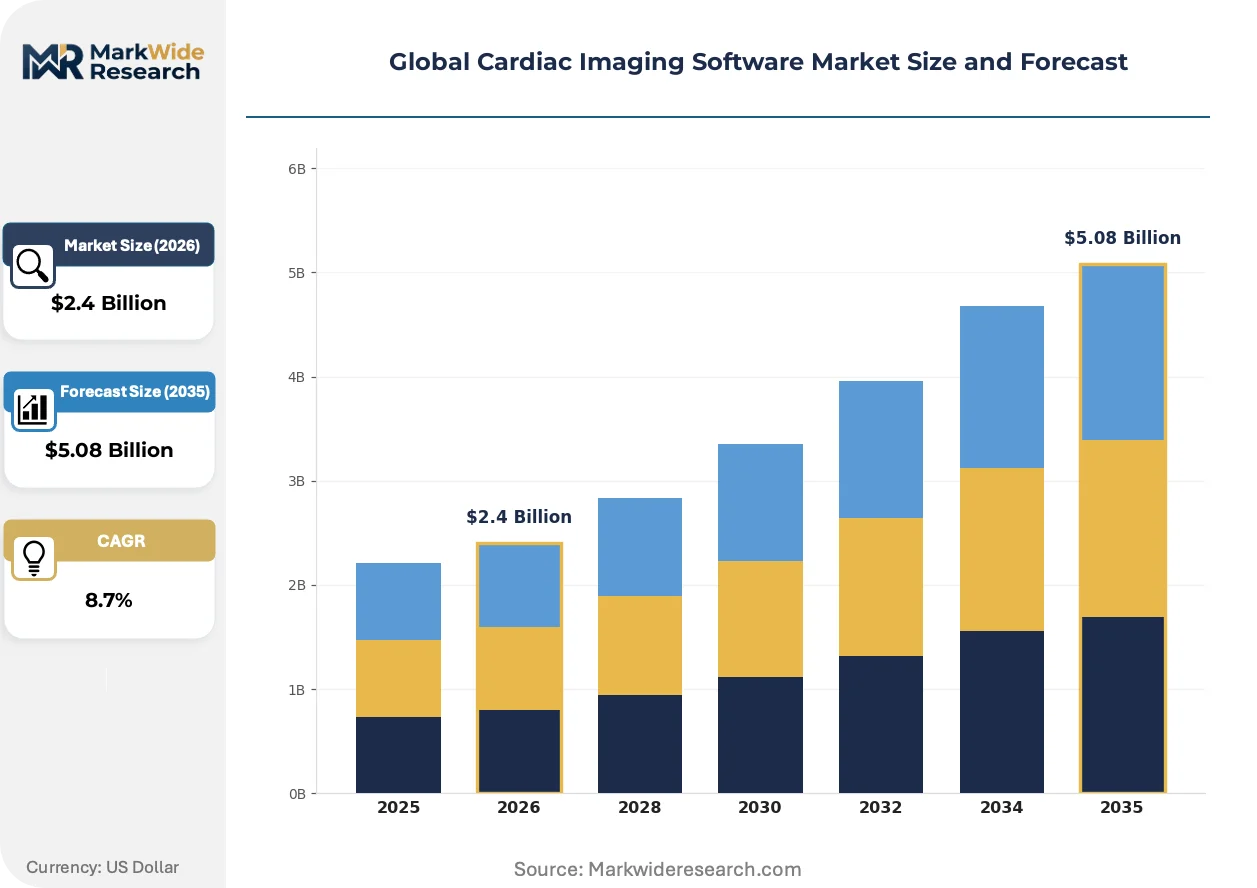
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: 2D Echocardiography, 3D Echocardiography, CT Angiography Software, MRI Cardiac Analysis, Nuclear Imaging Software, Strain Imaging Application: Myocardial Viability Assessment, Cardiac Function Evaluation, Coronary Artery Disease, Congenital Heart Defects, Arrhythmia Detection, Valvular Disease Analysis End User: Cardiology Clinics, Diagnostic Imaging Centers, Research Organizations, Academic Institutions, Telemedicine Providers, Cardiac Rehabilitation Centers Deployment Mode: On-Premise, Cloud-Based, Hybrid, Web-Based, Mobile Application, Enterprise Software |
| Companies Covered | Siemens Healthineers AG, GE HealthCare, Koninklijke Philips N.V, FUJIFILM Holdings Corporation, CANON MEDICAL SYSTEMS CORPORATION, Circle Cardiovascular Imaging Inc., Pie Medical Imaging B.V., Medis Medical Imaging Systems B.V., NeoSoft LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Imaging Software Market Shifts & Advancements
Algorithmic automation is compressing the diagnostic workflow from image acquisition to structured reporting, collapsing roles that previously required specialized operator intervention.
Deep learning-based fractional flow reserve (FFR-CT) calculation from static CT datasets is rendering obsolete invasive catheterization for intermediate-risk coronary lesions. Cardiology service lines at US academic medical centers are adopting FFR-CT as gatekeeping protocol before scheduling diagnostic angiography. This compression eliminates the interventionalist's traditional role in lesion severity confirmation, redistributing decision authority to non-invasive imagers.
EU AI Act risk classification tiers are forcing algorithm developers to restructure quality management systems around conformity assessment procedures. High-risk cardiac diagnostic software faces mandatory third-party auditing and post-market performance monitoring obligations. Vendors targeting EU-27 markets are rearchitecting development pipelines to embed explainability requirements from initial algorithm design phases.
Subscription-based deployment is displacing capital-intensive perpetual licenses across mid-sized cardiology practices in Germany and the United Kingdom. Cloud-native vendors capture these buyers through per-study pricing that aligns costs with procedure volume rather than upfront software investment. This shift is most visible in private cardiology clinic chains seeking to preserve working capital for transcatheter device inventory.
Global Cardiac Imaging Software Market Segmentation
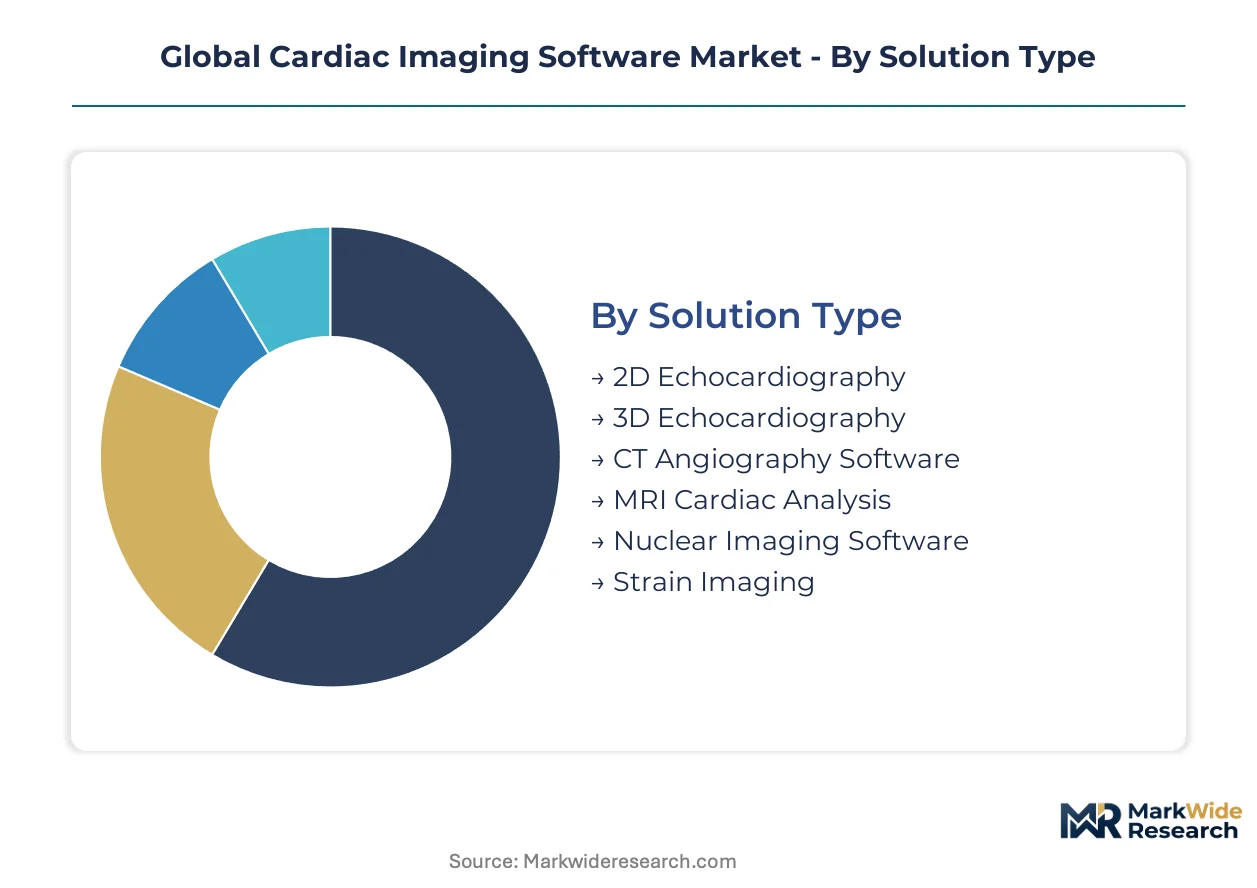
Segmentation in cardiac imaging software reveals how procurement priorities diverge across clinical workflows and infrastructure maturity. Solution architecture, clinical application, and deployment economics each reshape vendor access and pricing power in distinct ways.
Solution Type:
Cost tier stratification separates established hardware-integrated platforms from emerging algorithm-native modules competing on per-study economics.
- CT Angiography Software:Coronary plaque characterization and stenosis quantification algorithms process DICOM datasets from multi-slice CT scanners. Siemens Healthineers and GE HealthCare dominate installed bases at US academic medical centers where FFR-CT gatekeeping protocols displace diagnostic catheterization volumes.
- Strain Imaging:Speckle-tracking echocardiography algorithms compute myocardial deformation curves for left ventricular function assessment. Demand concentrates at German university hospitals and US structural heart programs where transcatheter procedure planning requires precise volumetric pre-assessment.
- 2D Echocardiography:Conventional volumetric and Doppler analysis tools for ejection fraction and valve gradient calculations.
- 3D Echocardiography:Real-time volumetric reconstruction platforms enabling left atrial appendage occlusion and mitral valve intervention planning.
- MRI Cardiac Analysis:Late gadolinium enhancement and perfusion mapping software for myocardial scar and viability assessment.
- Nuclear Imaging Software:SPECT and PET quantification tools for myocardial perfusion and metabolic imaging interpretation.
CT Angiography Software commands the established base. The steepest expansion runs through Strain Imaging.
Application:
Clinical application segmentation tracks how reimbursement pathways and procedure volume shape software procurement intensity across service lines.
- Coronary Artery Disease:CT angiography and FFR-CT workflows for obstructive lesion detection and functional significance assessment. Medicare reimbursement for non-invasive coronary evaluation in the United States drives enterprise contract consolidation at integrated delivery networks.
- Cardiac Function Evaluation:Ejection fraction, strain, and hemodynamic parameter quantification from echocardiography and MRI. China's tier-1 city hospitals deploy AI-enabled automated measurements to manage echocardiography backlogs amid cardiologist workforce constraints.
- Myocardial Viability Assessment:Late enhancement and perfusion analysis for revascularization candidacy determination.
- Congenital Heart Defects:3D reconstruction and flow quantification tools for pediatric and adult congenital intervention planning.
- Arrhythmia Detection:Cardiac MRI and CT integration with electroanatomic mapping systems for ablation substrate characterization.
- Valvular Disease Analysis:Planimetry and hemodynamic simulation software for transcatheter valve replacement candidacy.
Coronary Artery Disease anchors current procurement budgets. Cardiac Function Evaluation is expanding most quickly as automation reduces interpretation labor.
End User:
Customer type segmentation exposes divergent purchasing authority between capital-equipped hospital systems and asset-light service providers.
- Cardiology Clinics:Outpatient diagnostic facilities performing echocardiography and stress testing with PACS-integrated reporting. Subscription pricing from Philips and cloud-native vendors penetrates mid-sized German and UK clinic chains seeking to preserve working capital.
- Diagnostic Imaging Centers:Independent radiology facilities offering cardiac CT and MRI on referral. Teleradiology platforms enable cross-border interpretation networks from India to Gulf Cooperation Council states, opening service revenue pools for software-enabled remote reads.
- Academic Institutions:University hospitals with research mandates and training responsibilities driving algorithm validation partnerships.
- Research Organizations:CROs and pharmaceutical sponsors utilizing imaging biomarkers for clinical trial endpoints.
- Telemedicine Providers:Virtual care platforms integrating remote echocardiography interpretation and consultation workflows.
- Cardiac Rehabilitation Centers:Post-acute facilities tracking functional recovery through serial imaging assessment.
Diagnostic Imaging Centers command the established base. Cardiology Clinics show the steepest expansion trajectory as subscription models displace perpetual licenses.
Deployment Mode:
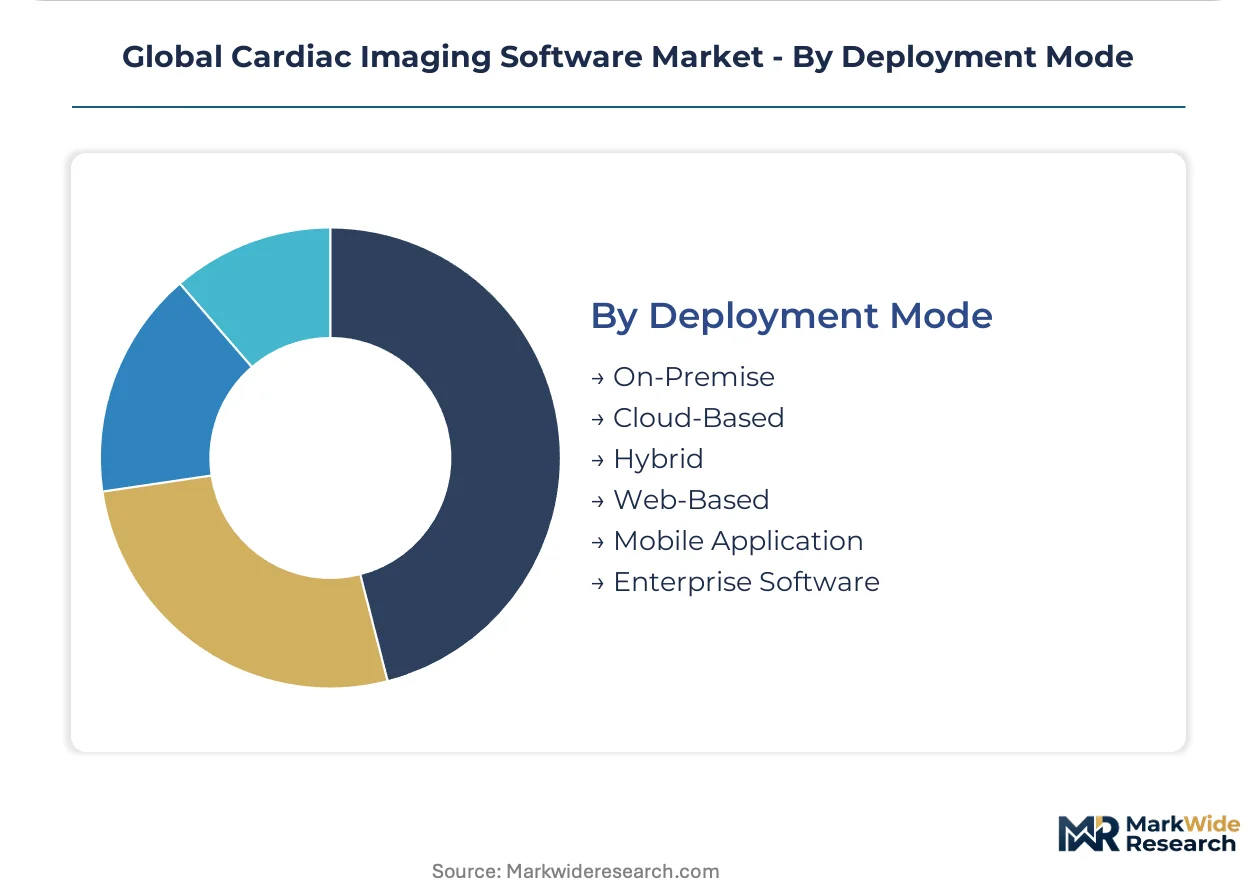
Infrastructure maturity across end-user sites determines deployment feasibility and vendor margin structure.
- Cloud-Based:SaaS architectures enabling multi-site image sharing and remote interpretation without on-premise server investment. NMPA green channel priority review accelerates market entry for AI diagnostic software in China's tier-1 city hospital networks.
- On-Premise:Local server installations maintaining data sovereignty and integration with legacy PACS infrastructure. German university hospitals resist migration due to institutional data governance policies and embedded CT-MRI hardware ecosystems.
- Hybrid:Mixed architectures buffering local processing with cloud analytics for peak load management.
- Web-Based:Browser-accessible platforms for occasional users and teleradiology workflows.
- Mobile Application:Tablet and smartphone viewers for point-of-care echocardiography and emergency department triage.
- Enterprise Software:Hospital-wide contracts spanning multiple modalities and service lines under single vendor relationships.
On-Premise retains the installed base. Cloud-Based deployment is gaining share fastest as procurement shifts from capital to operational expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany, where reimbursement density for non-invasive cardiac diagnostics exceeds tier-1 Chinese hospital networks by substantial margins. This asymmetry shapes vendor resource allocation and product localization priorities across the analysis window.
United States
Medicare reimbursement codes for coronary CT angiography and FFR-CT gatekeeping protocols drive enterprise procurement at integrated delivery networks. FDA 510(k) clearance pathways accelerate AI-enabled diagnostic module commercialization. The Cleveland Clinic and Mayo Clinic anchor algorithm validation partnerships in Ohio and Minnesota.
Germany
EU MDR technical documentation mandates elevate compliance costs for software-as-medical-device classifications while filtering undercapitalized entrants. Strain imaging demand concentrates at Charité Berlin and Heidelberg University Hospital for transcatheter structural heart planning. Bavarian medical device clusters around Munich sustain ISO 13485 certification infrastructure.
China
Tier-1 city hospital networks in Beijing and Shanghai deploy AI-enabled echocardiography automation to manage cardiologist workforce constraints. NMPA green channel priority review accelerates market entry for coronary plaque characterization tools. Yangtze River Delta medical centers lead cloud-native deployment adoption.
Japan
PMDA software-as-medical-device classifications provide explicit guidance on machine learning-enabled device categories, reducing regulatory uncertainty for predictive analytics modules. Academic medical centers in Tokyo and Osaka drive FFR-CT adoption for intermediate-risk lesion assessment. Kanto region hospitals anchor embedded AI workflow integration.
United Kingdom
Subscription-based cloud deployment models penetrate private cardiology clinic chains seeking working capital preservation for transcatheter device inventory. NHS England reimbursement frameworks for non-invasive cardiac diagnostics mature in London and Manchester. Midlands hospital networks resist on-premise infrastructure migration.
Global Cardiac Imaging Software Market Competitive Landscape
Hardware-integrated incumbents and algorithm-native specialists split the market between capital-intensive enterprise contracts and per-study SaaS economics. Siemens Healthineers, GE HealthCare, and Philips anchor the consolidated tier through direct sales teams and embedded AI workflows. Mid-stage vendors compete via cloud-native architectures that reduce upfront barriers for mid-sized cardiology clinics. Dominant competitive moves include strategic partnerships with integrated delivery networks and portfolio diversification into strain imaging modules.
Within the hardware-integrated tier, Siemens Healthineers AG and GE HealthCare exemplify installed-base loyalty strategies across academic medical centers. Koninklijke Philips N.V. occupies a position representing subscription-based cloud deployment models that align vendor revenue with procedure volume. These three entities collectively anchor the competitive structure, with Philips sitting within the SaaS-native vector while Siemens Healthineers and GE HealthCare exemplify perpetual-license and embedded-workflow archetypes.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE HealthCare |
| Koninklijke Philips N.V |
| FUJIFILM Holdings Corporation |
| CANON MEDICAL SYSTEMS CORPORATION |
| Circle Cardiovascular Imaging Inc. |
| Pie Medical Imaging B.V. |
| Medis Medical Imaging Systems B.V. |
| NeoSoft LLC |
| Others |
Supply & Pricing Matrix
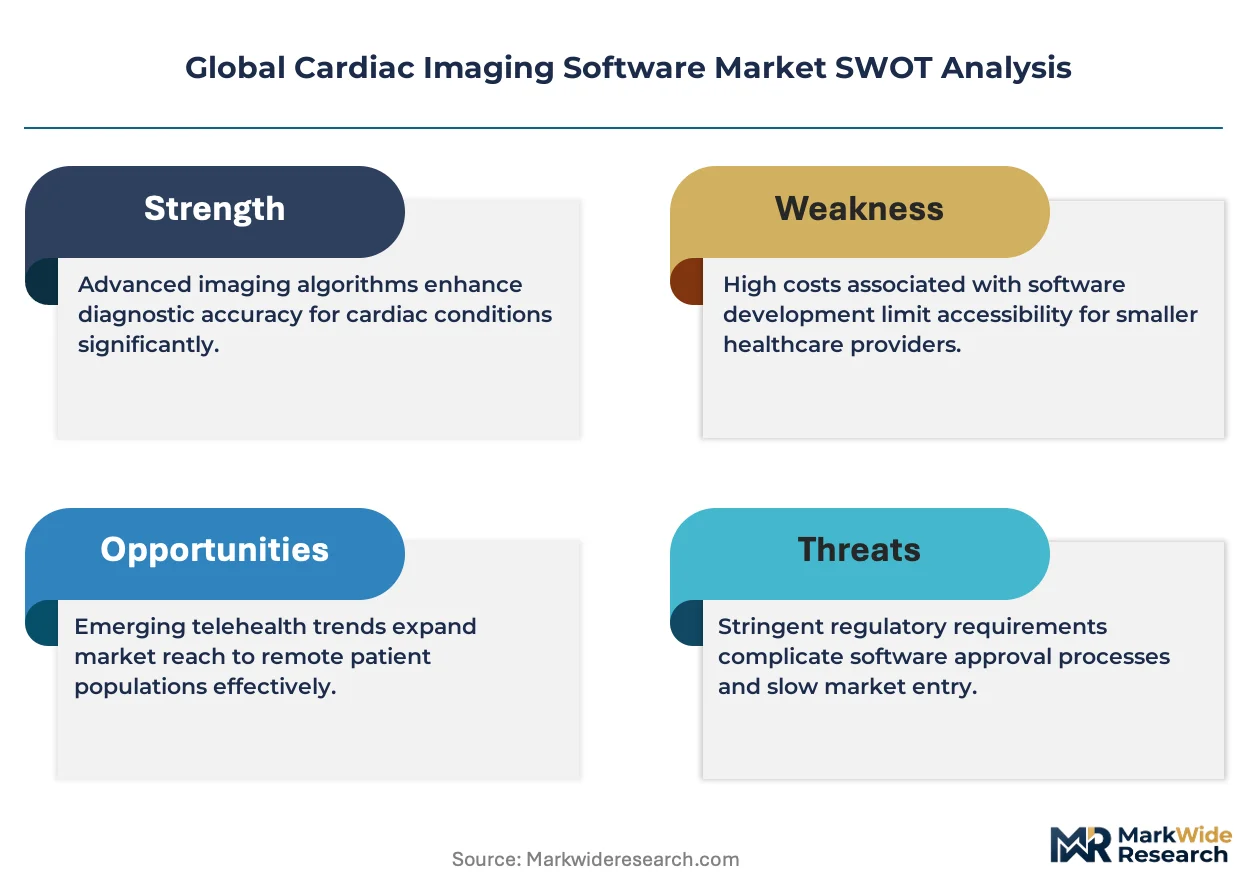
GPU supply concentration at NVIDIA data center accelerators generates input cost volatility that compresses mid-tier vendor margins while simultaneously widening the premium-to-standard pricing spread across deployment modes. This single-source dependency for real-time CT reconstruction hardware forces algorithm-native vendors toward subscription economics and incumbents toward bundled hardware-software contracts.
Pricing Analysis
The customization-premium spread separates enterprise-configured CT angiography platforms from off-the-shelf strain imaging modules. Three-tier pricing structure across premium, standard, and economy levels aligns with FDA 510(k) clearance tier and ISO 13485 certification status. Pricing pressure stems from cloud-native entrants offering per-study SaaS economics that undercut perpetual license models. Mid-sized cardiology clinics in Germany and the United Kingdom exhibit highest price sensitivity, while US academic medical centers prioritize workflow integration over cost.
Supply Chain Analysis
Supplier-financing facilities from NVIDIA and cloud hyperscalers extend payment terms for GPU allocation commitments, easing working capital constraints for algorithm developers. Hardware component sourcing concentrates in Taiwan, South Korea, and the United States for semiconductor fabrication. Software development draws from India and Eastern Europe for imaging informaticist talent. Single-source vulnerability at NVIDIA A100/H100 accelerators creates allocation risk during demand surges. Distribution runs through direct enterprise sales teams at integrated delivery networks and OEM hardware partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software maintenance and algorithm update subscriptions expand faster than hardware replacement cycles, transforming cardiac imaging into a service-attach business where recurring revenue multiples exceed capital equipment valuations.
For Market Incumbents: Insulate installed-base loyalty by embedding AI workflows within CT and MRI hardware ecosystems and accelerating ISO 13485 certification investments to filter cloud-native challengers. Siemens Healthineers and GE HealthCare should deepen CT angiography platform integration to defend against per-study pricing erosion from SaaS entrants. For New Entrants and Emerging Players: Cloud deployment gaps at German university hospitals resisting PACS migration present the most penetrable white-space target for hybrid architecture vendors. China's tier-1 city hospital networks offer secondary entry through NMPA green channel priority review. Target teleradiology service providers with remote interpretation workflows as the anchor go-to-market angle. For Investors and Strategic Acquirers: Algorithm-native specialists with FDA-cleared FFR-CT modules and cloud-native deployment architectures represent the priority acquisition archetype. Long-term viability hinges on recurring revenue share exceeding perpetual license dependence. Monitor EU AI Act high-risk classification implementation as the inflection signal for compliance cost escalation and vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | SaaS architectures enable per-study pricing that aligns vendor revenue with procedure volume at mid-sized clinics. |
| FDA 510(k) Clearance Acceleration | Streamlined pathways for AI-enabled CT angiography modules reduce time-to-revenue for algorithm developers. |
| EU MDR Compliance Investment | Technical documentation capabilities filter undercapitalized entrants and consolidate market share among certified vendors. |
| Strain Imaging Module Expansion | 3D echocardiography algorithms capture structural heart procedure planning demand at German university hospitals. |
| China NMPA Green Channel Entry | Priority review pathways accelerate commercialization for coronary plaque characterization tools in tier-1 city networks. |
Research Methodology
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and algorithm development leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Demand-supply-balance framing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include solution type, clinical application, end-user category, and deployment mode. CAGRs derived from procedure volume trajectories, reimbursement pathway maturation, and algorithm adoption curves. Cloud deployment penetration rates and AI-enabled diagnostic module clearance timelines served as industry-specific forecast inputs.
Practitioners should monitor EU AI Act enforcement patterns, NMPA green channel expansion, and GPU supply allocation shifts for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global MRI Scanner Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
UK Digital Radiology Market