
 Image Guided Therapy Market | 2026-2036
Image Guided Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Image Guided Therapy Market Insights
European imaging equipment manufacturers is recalibrating production schedules to address backlogs in MRI-guided surgical system deliveries. Siemens Healthineers leverages its installed base of magnetic resonance platforms to cross-sell navigation software bundles. Medtronic anchors its competitive stance through deep integration of intraoperative imaging with robotic surgical ecosystems.
Image guided therapy encompasses real-time visualization technologies that combine anatomical imaging with instrument tracking to steer minimally invasive interventions, typically operating at sub-millimeter spatial resolution with refresh rates exceeding 30 frames per second for cardiac catheter navigation. The primary purpose is to reduce procedural complications while enabling tissue-sparing approaches in previously inaccessible anatomical regions. MRI systems command premium positioning in neurosurgical suites where soft-tissue contrast proves indispensable for tumor margin delineation. Real-time navigation technology is gaining fastest traction in electrophysiology labs as catheter ablation volumes expand. Outpatient facilities represent an emerging margin pool as ambulatory surgical centers invest in compact fluoroscopy systems for orthopedic spine procedures.
FDA premarket notification pathways and EU MDR conformity assessment frameworks impose stringent clinical evidence requirements on software-as-medical-device components embedded in navigation platforms. The EPA and state-level radioactive materials licensing bodies regulate fluoroscopy system deployment through equipment registration and operator certification mandates. Stakeholders must monitor evolving reimbursement codes for image-guided procedures across Medicare and commercial payers to calibrate capital investment cycles against procedure volume trajectories.
Market Dynamics
Real-time navigation platforms are compressing procedural timelines in minimally invasive oncology, forcing capital equipment vendors to bundle software subscriptions with hardware sales rather than monetize through perpetual licenses.
Growth Catalysts
- EU MDR conformity acceleration:Streamlined clinical evidence pathways for software-as-medical-device components embedded in navigation platforms are shortening time-to-market for AI-enhanced imaging systems across German university hospitals.
- Electrophysiology lab expansion:Catheter ablation volume trajectories are pulling real-time navigation technology into cardiac suites at sub-millimeter spatial resolution requirements.
- Fluoroscopy system miniaturization:Compact designs are unlocking ambulatory surgical center procurement for orthopedic spine procedures previously confined to inpatient settings.
Market Restraints
- Helium supply volatility:MRI-guided surgical system production schedules face input cost pressure from constrained superconducting magnet coolant availability.
- FDA premarket notification stringency:Software-enabled medical device pathways impose clinical evidence burdens that extend clearance timelines for navigation algorithm updates.
- Fluoroscopy substitution risk:Intraoperative CT and cone-beam alternatives are displacing traditional C-arm systems in hybrid operating suite configurations.
Strategic Opportunities
- Outpatient facility penetration:Ambulatory surgical centers in the United States represent underexploited demand for compact image-guided systems with lower footprint requirements.
- Image fusion convergence:Hybrid operating suites are integrating MRI-fluoroscopy overlay capabilities that combine soft-tissue contrast with real-time instrument tracking.
- Medicare reimbursement code expansion:New procedural codes for image-guided interventions are creating payment tailwinds for capital investment in navigation platforms.
Industry Challenges
- Interventional radiologist training pipelines:Subspecialty fellowship slots are failing to match deployment velocity of navigation-enabled procedures.
- Legacy PACS integration friction:Proprietary data formats from robotic surgical ecosystems are creating interoperability barriers with hospital IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image Guided Therapy Market |
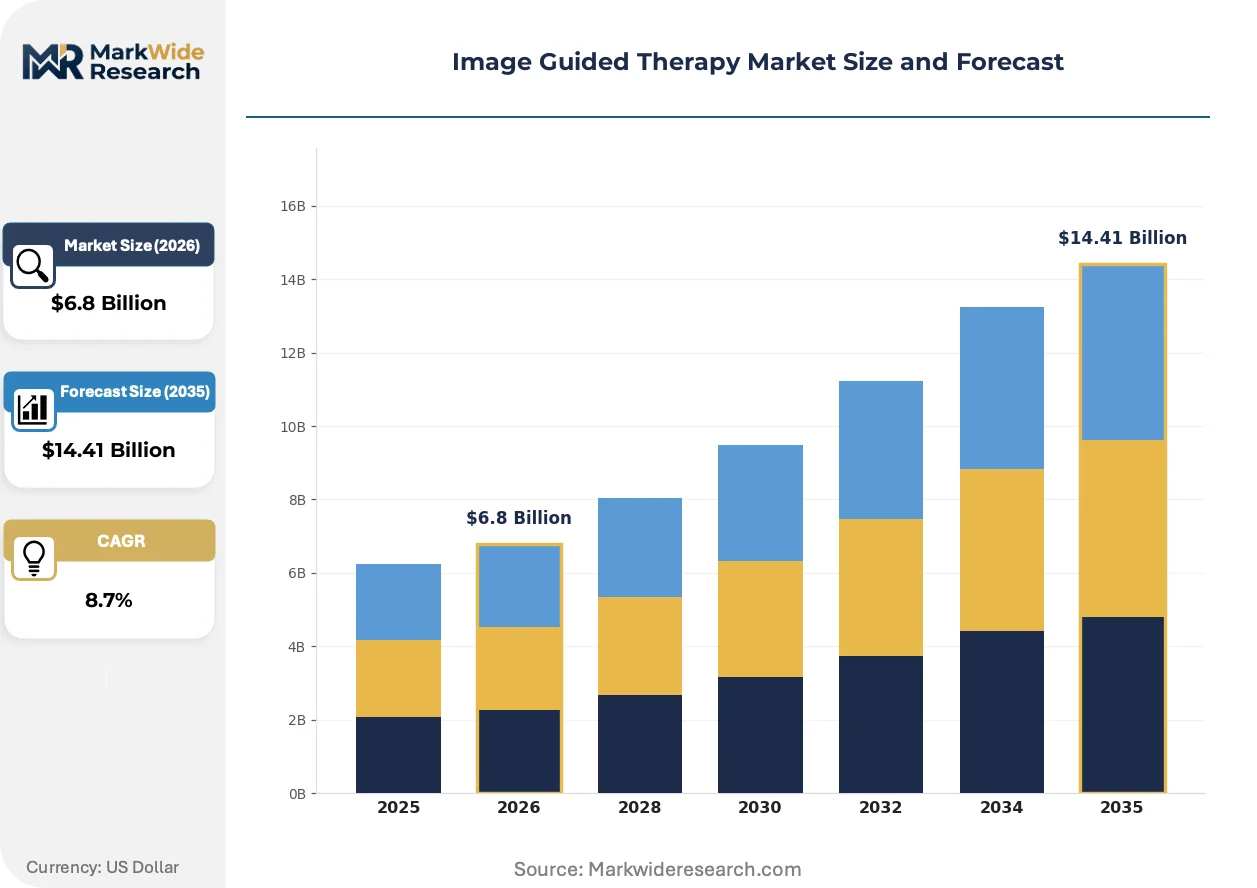
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Systems, MRI Systems, CT Scanners, Fluoroscopy Systems End User: Hospitals, Imaging Centers, Academic Institutions, Outpatient Facilities Technology: 3D Imaging, 4D Imaging, Real-Time Navigation, Image Fusion Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | Koninklijke Philips N.V., Medtronic, Siemens Healthineers, GE Healthcare, Stryker Corporation, Brainlab AG, Olympus Corporation, Varian Medical Systems, Inc., Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image Guided Therapy Market Trends and Innovations
Navigation software architectures are pivoting from standalone workstations to embedded modules within robotic surgical platforms, compressing vendor business models toward recurring revenue streams.
AI-enhanced imaging systems are expanding into real-time tumor margin delineation workflows, delivering automated segmentation at refresh rates exceeding 30 frames per second. Neurosurgical suites in Germany and the United States are adopting these platforms for previously inaccessible anatomical regions. The technology is expanding into procedure categories where manual navigation previously limited tissue-sparing approaches.
FDA premarket approval pathways for software-enabled medical devices are accelerating clearance timelines through streamlined clinical evidence requirements for algorithm updates. Medical device manufacturers are restructuring quality management systems to accommodate iterative deployment cycles. AI-enhanced imaging systems face the most significant regulatory adaptation pressure in the United States market.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, compressing vendor margin pools toward discrete software maintenance agreements. Academic medical centers are leading this shift through centralized biomedical engineering staffing. The United States exhibits the most pronounced procurement model evolution as health systems consolidate purchasing authority.
Image Guided Therapy Market Segmentation
Procurement committees in hospital systems evaluate image guided therapy platforms through four distinct lenses: imaging modality, care setting, visualization capability, and clinical application. Each segmentation axis reveals divergent margin structures, regulatory pathways, and competitive intensity that vendors must navigate.
Product Type:
Capital allocation decisions hinge on procedure volume throughput versus tissue contrast requirements.
- MRI Systems:Superconducting magnets deliver sub-millimeter soft-tissue resolution indispensable for neurosurgical tumor margin delineation. German university hospitals anchor demand for intraoperative MRI suites where helium supply contracts determine total cost of ownership.
- Fluoroscopy Systems:C-arm configurations with flat-panel detectors achieve 30+ frames per second refresh rates for cardiac catheter navigation. Compact miniaturization variants are penetrating ambulatory surgical centers in the United States for orthopedic spine interventions.
- Ultrasound Systems:Portable cart-based platforms with linear and phased array probes serve point-of-care biopsy guidance in community hospital settings.
- CT Scanners:Cone-beam and intraoperative CT alternatives displace traditional fluoroscopy in hybrid operating suite configurations requiring bony detail.
Volume sits with fluoroscopy installations; growth tilts toward MRI-guided surgical ecosystems.
End User:
Reimbursement environment and capital depreciation schedules vary sharply across care delivery settings.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing authority for navigation platform bundles spanning multiple service lines. Academic medical centers lead procurement of image fusion technology for hybrid operating suites.
- Outpatient Facilities:Ambulatory surgical centers invest in compact fluoroscopy systems with lower footprint requirements as Medicare reimbursement codes expand for image-guided spine procedures.
- Imaging Centers:Independent diagnostic facilities prioritize throughput-optimized CT and ultrasound platforms for interventional radiology referral volumes.
- Academic Institutions:University hospitals in Germany function as early adoption sites for AI-enhanced imaging systems undergoing EU MDR conformity assessment.
Capital concentration remains with hospital systems; steepest expansion trajectory belongs to outpatient facilities.
Technology:
Software architecture choices determine recurring revenue potential and regulatory recertification burdens.
- Real-Time Navigation:Electromagnetic and optical tracking systems achieve sub-millimeter instrument localization at 30+ frames per second for catheter ablation workflows. Electrophysiology labs in the United States are pulling this capability into cardiac suites at accelerating pace.
- Image Fusion:MRI-fluoroscopy overlay combines soft-tissue contrast with live instrument tracking, enabling tissue-sparing approaches in previously inaccessible anatomical regions. German university hospitals are integrating this capability into hybrid operating suites at scale.
- 3D Imaging:Volumetric reconstruction from rotational angiography and CT supports pre-procedural planning in orthopedic and neurological interventions.
- 4D Imaging:Time-resolved volumetric acquisition captures cardiac and respiratory motion for dynamic procedure guidance.
Installed base dominance belongs to 3D imaging; capability investment flows toward real-time navigation.
Application:
Procedure volume trajectories and reimbursement density determine platform utilization rates.
- Oncology:Minimally invasive tumor ablation and biopsy procedures demand MRI and CT guidance for soft-tissue lesion targeting. Navigation-enabled interventions are compressing procedural timelines while reducing complication rates.
- Cardiology:Electrophysiology catheter ablation volumes are expanding fastest among image-guided procedure categories, pulling real-time navigation technology into cardiac suites.
- Neurology:Deep brain stimulation and tumor resection require sub-millimeter spatial resolution that MRI systems command in neurosurgical suites.
- Orthopedics:Spine and joint interventions utilize fluoroscopy and cone-beam CT for instrument placement verification, with ambulatory migration driving compact system demand.
Procedure density centers on cardiology; technology upgrade intensity concentrates in oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium extraction from the Hugoton Natural Gas Area in Kansas anchors North American superconducting magnet supply chains for MRI-guided surgical systems. This feedstock concentration shapes procurement timelines across hospital systems deploying intraoperative imaging platforms.
United States
Academic medical centers in Boston and Houston are consolidating purchasing authority for navigation platform bundles spanning cardiology and oncology service lines. FDA premarket notification pathways impose clinical evidence requirements on software-as-medical-device components. The Mayo Clinic in Rochester anchors early adoption of AI-enhanced imaging systems for neurosurgical workflows.
Germany
University hospitals in Munich and Heidelberg are integrating image fusion technology into hybrid operating suites at scale. EU MDR conformity assessment frameworks streamline clearance timelines for navigation algorithm updates. The Baden-Württemberg medical technology cluster around Tübingen concentrates MRI-guided surgical system manufacturing and R&D activity.
Japan
Electrophysiology labs in Tokyo and Osaka are pulling real-time navigation technology into cardiac suites as catheter ablation volumes expand. PMDA regulatory frameworks govern software-enabled medical device approvals with structured quality management requirements. The Kansai region anchors domestic production of compact fluoroscopy systems for orthopedic applications.
China
Tier-3 hospitals in Shanghai and Beijing are expanding procurement of intraoperative CT alternatives displacing traditional C-arm configurations. NMPA approval pathways for imported navigation platforms require localized clinical trial data. The Yangtze River Delta medical device manufacturing corridor concentrates domestic assembly of ultrasound-guided biopsy systems.
India
Corporate hospital chains in Mumbai and Delhi-NCR are investing in image-guided therapy platforms for minimally invasive oncology procedures. CDSCO medical device regulations mandate registration and import licensing for navigation software components. The Karnataka medical technology corridor around Bangalore hosts contract manufacturing for portable fluoroscopy equipment.
Image Guided Therapy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enhanced imaging modules and outpatient-focused compact systems. The vendor base organizes around three archetypes: diversified imaging equipment conglomerates with installed base leverage, pure-play navigation software specialists, and robotic surgical platform integrators. M&A activity concentrates on tuck-in acquisitions of algorithm developers, while strategic partnerships between hardware OEMs and cloud infrastructure providers reshape service delivery models.
Among diversified imaging conglomerates, Koninklijke Philips N.V. and Siemens Healthineers occupy positions defined by cross-selling navigation software bundles against established MRI and fluoroscopy installed bases. Medtronic exemplifies the robotic surgical integrator archetype, anchoring competitive stance through deep ecosystem embedding. These three entities represent distinct strategic postures without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic |
| Siemens Healthineers |
| GE Healthcare |
| Stryker Corporation |
| Brainlab AG |
| Olympus Corporation |
| Varian Medical Systems, Inc. |
| Canon Medical Systems Corporation |
| Others |
Pricing and Supply Chain Analysis
EU MDR conformity assessment timelines gate qualified supply access for navigation software vendors, compressing premium-tier pricing to manufacturers with established quality management systems while excluding emergent algorithm developers from high-margin hospital procurement cycles.
Pricing Analysis
Warranty and service contract unbundling from capital equipment purchases is reshaping vendor margin structures. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier and installed base leverage. Cost compression in the standard tier is intensifying because hospital procurement committees centralize purchasing authority. Academic medical centers exhibit lowest price sensitivity; ambulatory surgical centers face acute capital constraints.
Supply Chain Analysis
Helium supply for superconducting magnets rests on extraction from the Hugoton Natural Gas Area in Kansas and Qatar's liquefaction facilities. MRI system production draws from niobium-titanium superconducting wire, liquid helium, and rare earth magnet components. Single-source vulnerability concentrates in helium refining capacity. Distribution runs through authorized dealer networks with biomedical engineering service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as FDA premarket notification stringency forces weaker algorithm developers toward strategic exit, favoring diversified imaging conglomerates with regulatory affairs infrastructure.
For Market Incumbents: Hedge against fluoroscopy substitution risk by deepening image fusion capabilities for hybrid operating suites. Acquire electromagnetic tracking specialists to secure real-time navigation component supply. Prioritize backward integration into helium storage and recycling systems to stabilize MRI system total cost of ownership. For New Entrants and Emerging Players: Begin with compact fluoroscopy systems for United States ambulatory surgical centers where Medicare reimbursement code expansion is creating procurement tailwinds. Target outpatient spine procedure workflows with lower footprint requirements. Pursue hospital-at-home partnerships as a de-risked go-to-market channel. For Investors and Strategic Acquirers: FDA premarket approval acceleration for AI-enhanced imaging systems is the leading indicator that algorithm-enabled navigation modules will command sustained premium positioning. Frame long-term viability around software-as-medical-device recurring revenue streams rather than perpetual license models. Target tuck-in acquisitions of electromagnetic tracking algorithm developers with EU MDR technical documentation already filed.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR streamlined assessments accelerate German university hospital adoption timelines. |
| Hospital System Partnership | Integrated delivery network bundling secures multi-service line navigation platform deployment. |
| Software Companion Development | Embedded AI-enhanced modules shift vendor economics toward recurring subscription revenue. |
| Reimbursement Strategy | Medicare code expansion for image-guided spine procedures unlocks ambulatory facility procurement. |
| Backward Integration | In-house helium recycling capabilities stabilize MRI system production cost structures. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases, complemented by interviews with biomedical engineers, electrophysiology lab directors, GPO contracts managers, and navigation platform product managers. Secondary validation drew from CMS reimbursement schedules, SEC 10-K equipment revenue disclosures, and helium market trade data. Bottom-up procedure volume modeling triangulated against top-down capital equipment shipment estimates.
Market sizing outputs reflect segmentation across imaging modality, care setting, technology architecture, and clinical application, with neurosurgical and cardiac procedure categories receiving distinct modeling treatment. CAGRs were derived from weighted average of historical procurement trajectories and reimbursement-driven demand elasticity. Forecast inputs incorporated catheter ablation volume projections and ambulatory surgical center certification expansion rates.
Underlying measurement precision varies by segment; fluoroscopy system volumes carry tighter precision than AI-enhanced imaging adoption curves. Forecasts reflect assumptions regarding FDA clearance timeline stability and helium supply contract renewal patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mobile Tomography Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Medical Holography Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Perfusion Radiology Market