
 Enterprise Medical Image Viewers Market | 2026-2036
Enterprise Medical Image Viewers Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Medical Image Viewers Market Analysis
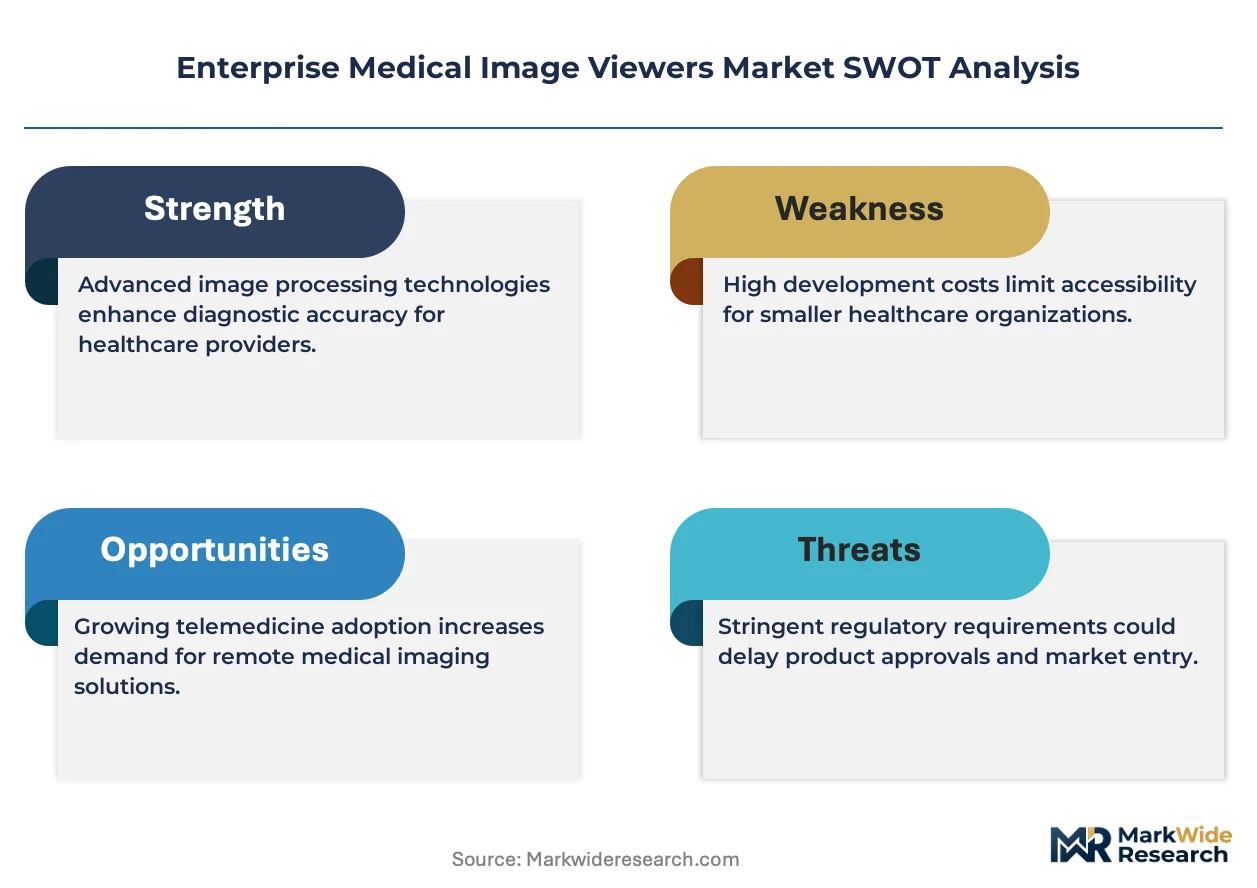
Cloud-native architecture is restructuring enterprise medical image viewer economics as on-premises infrastructure gives way to subscription-based SaaS offerings. GE HealthCare Technologies Inc. leverages its installed base of imaging modalities to bundle viewer software with hardware service contracts. Sectra AB sustains premium positioning through vertical integration into diagnostic workflow orchestration. Philips Healthcare anchors its enterprise footprint with hybrid deployment options that bridge legacy PACS and modern cloud architectures.
Enterprise medical image viewers are software platforms that render, manipulate, and distribute DICOM-compliant medical images across healthcare networks, typically supporting multi-modality integration with sub-second latency for diagnostic-grade displays. Cloud-based Solutions now capture the fastest expansion as health systems prioritize capital-expense reduction and remote access resilience, while Desktop Viewers retain dominance in high-volume radiology reading rooms where local processing guarantees performance. AI-enhanced Tools represent the emerging margin pool, with diagnostic labs and research institutes driving specialized demand for algorithm-integrated viewing environments.
FDA premarket review pathways for AI-enabled radiology devices shape product development timelines, while HIPAA mandates govern data architecture decisions for any viewer handling protected health information across hospital networks. The EU AI Act introduces conformity requirements that will filter which AI-enhanced viewer modules enter European clinical use. Stakeholders must weigh regulatory compliance velocity against cloud migration timelines when selecting enterprise platform vendors.
Market Dynamics
Cloud-native architectures are compressing deployment timelines and collapsing capital expenditure barriers for health systems consolidating multi-site imaging networks.
Growth Catalysts
- FDA AI Guidance:The FDA's premarket review pathway for AI-enabled radiology devices accelerates enterprise platform upgrades as hospitals seek algorithm-integrated viewing environments.
- Health System Consolidation:United States-based hospital networks are standardizing on single-vendor enterprise viewers to unify radiology workflows across acquired facilities.
- Hybrid Cloud Architectures:Health systems deploy cloud-hosted viewers with on-premises edge nodes to balance remote access resilience with diagnostic-grade latency requirements.
Market Restraints
- Legacy PACS Lock-in:Decade-old on-premises archives create data migration friction and switching costs that delay enterprise viewer replacements.
- HIPAA Compliance Burden:Protected health information handling requirements constrain cloud architecture choices and extend vendor evaluation cycles.
- Radiologist Workflow Disruption:Sub-second latency thresholds for diagnostic-grade displays limit which cloud configurations qualify for primary interpretation.
Strategic Opportunities
- EU AI Act Conformity:European Union conformity requirements for AI-enhanced medical devices will filter market entrants and reward early-compliant vendors.
- Research Institute Demand:Academic medical centers seek algorithm-integrated viewing environments for clinical trial imaging and multi-site research consortia.
- Point-of-Care Expansion:Emergency departments and surgical suites require enterprise viewer access outside traditional radiology reading rooms.
Industry Challenges
- Interoperability Complexity:DICOM-compliant image exchange across heterogeneous vendor environments demands continuous interface maintenance.
- Cybersecurity Certification Burden:Health systems require SOC 2 Type II and HITRUST certification timelines that delay vendor onboarding.
- Radiologist Retraining Requirements:Cloud-based viewer interfaces differ sufficiently from legacy PACS to necessitate structured proficiency programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Medical Image Viewers Market |
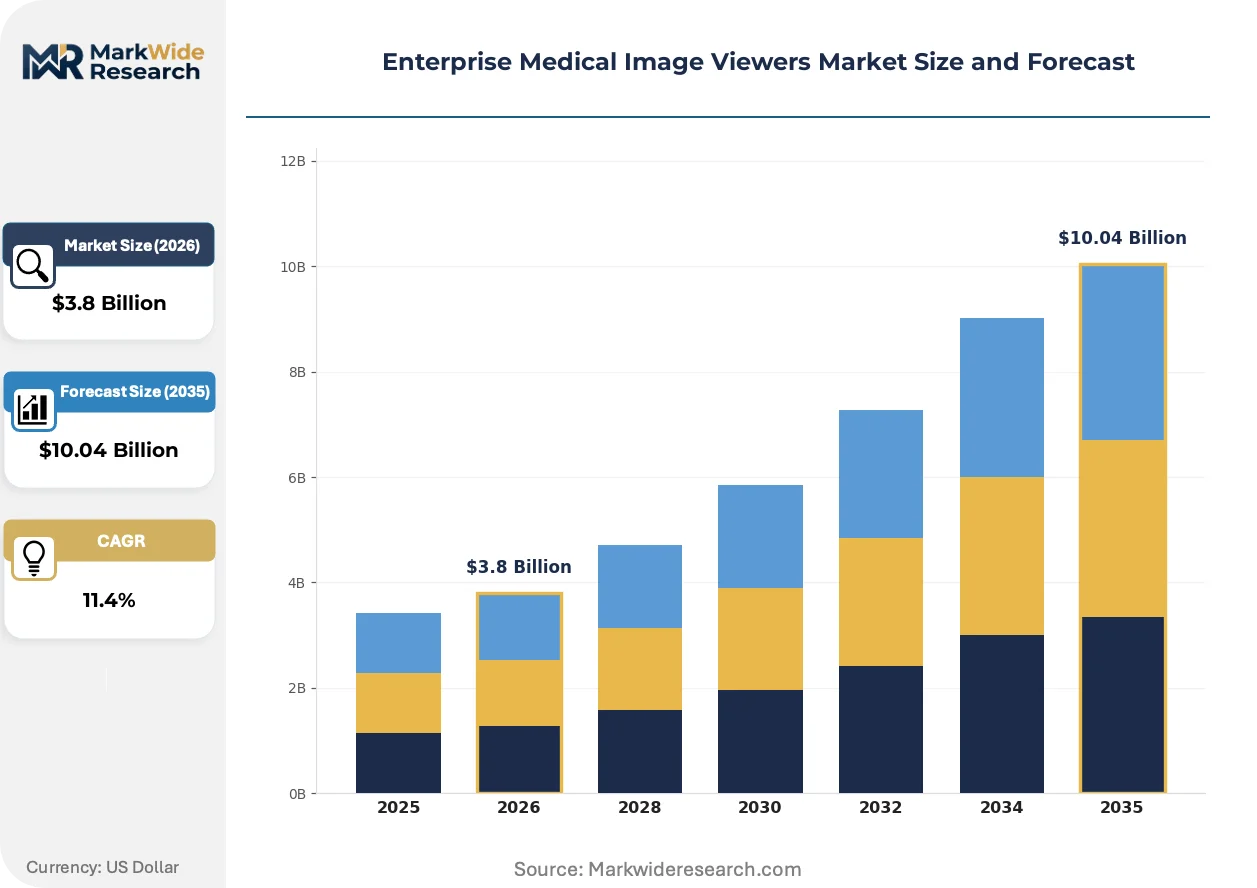
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-based Viewers, Mobile Viewers, Desktop Viewers, Cloud-based Solutions End User: Hospitals, Imaging Centers, Research Institutes, Diagnostic Labs Technology: 3D Reconstruction, DICOM Compatibility, Radiology Solutions, AI-enhanced Tools Deployment: On-premises, Cloud-hosted, Hybrid Solutions, SaaS Offerings |
| Companies Covered | Pro Medicus Limited, Sectra AB, Agfa HealthCare N.V., Mach7 Technologies Pty Ltd, Infinitt Healthcare Co., Ltd., GE HealthCare Technologies Inc., Intelerad Medical Systems Inc., Hyland Software, Inc., Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Medical Image Viewers Market Emerging Trajectories
Artificial intelligence integration is restructuring how diagnostic images are rendered, annotated, and routed across enterprise networks.
Serverless GPU orchestration is electrifying enterprise viewer economics by decoupling compute scaling from hardware ownership. Large United States health systems are adopting pay-per-study cloud rendering to eliminate peak-load infrastructure overprovisioning. This architecture is electrifying competitive positioning for vendors with native cloud engineering depth versus legacy PACS incumbents.
The EU AI Act introduces conformity assessment requirements for AI-enhanced radiology modules entering European clinical use. Medical device manufacturers must document algorithm performance across defined patient populations to secure CE marking. European diagnostic labs are prioritizing viewer vendors with established notified body relationships and pre-validated algorithm integration frameworks.
Enterprise procurement teams are unbundling viewer software from modality hardware service contracts. Health system value analysis committees now evaluate standalone viewer platforms on total cost of ownership metrics spanning five-year horizons. This pattern is most pronounced in United States integrated delivery networks with centralized IT governance and standardized vendor qualification processes.
Enterprise Medical Image Viewers Market Segmentation
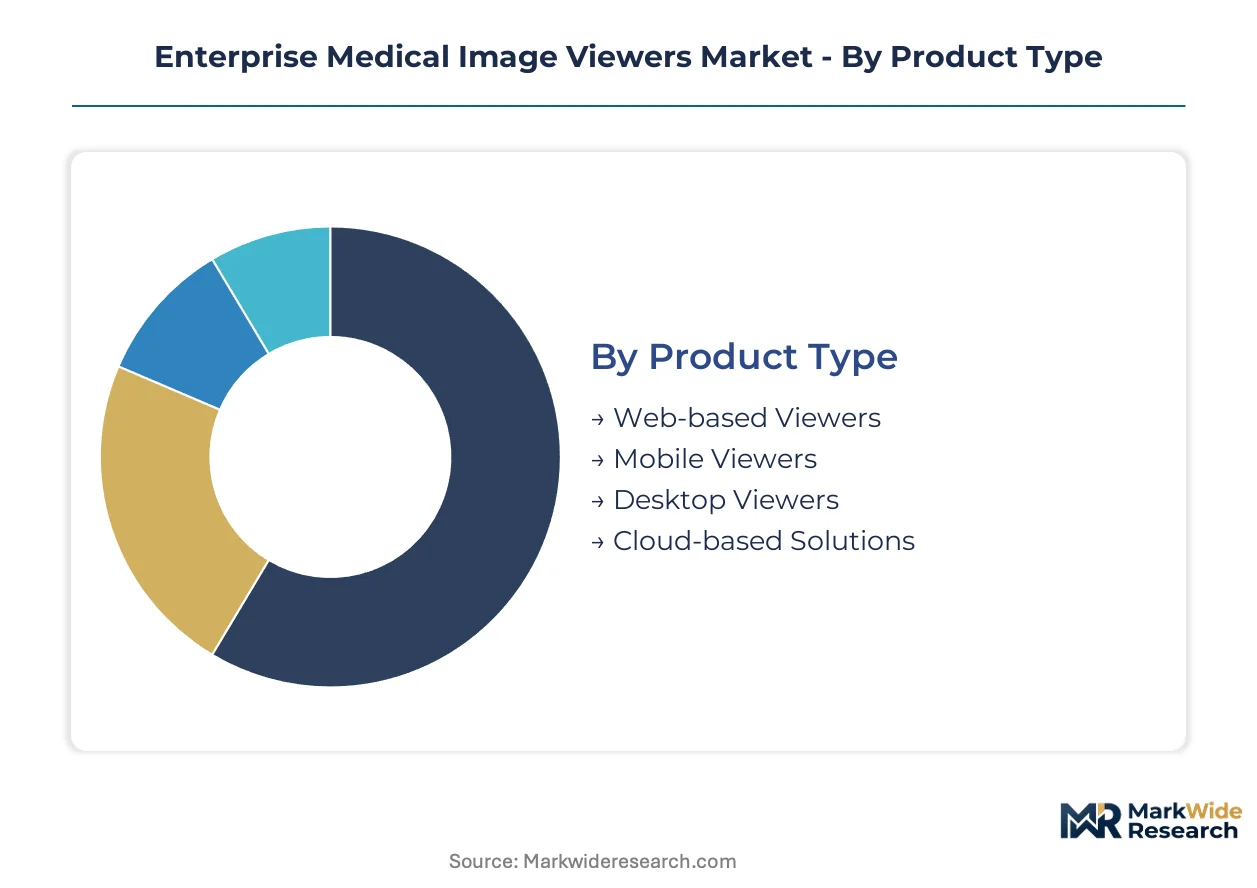
Enterprise medical image viewer procurement pivots on integration depth, with standalone deployments demanding different technical specifications than embedded systems within broader imaging workflows. Health systems evaluate segments through total cost of ownership lenses spanning hardware refresh cycles, cloud migration timelines, and AI module licensing.
Product Type:
Integration depth varies sharply across product architectures, with browser-rendered solutions serving distributed clinical staff while thick-client applications anchor diagnostic interpretation workflows.
- Web-based Viewers:Browser-rendered platforms using HTML5 and WebGL for zero-install access across hospital networks. Demand concentrates in multi-site United States health systems prioritizing remote physician access and reduced IT support burden.
- Mobile Viewers:iOS and Android applications optimized for tablet diagnostic displays with touch-based measurement tools. Emergency departments and surgical suites drive specialized demand for point-of-care image consultation outside radiology departments.
- Desktop Viewers:Thick-client software leveraging local GPU acceleration for sub-second latency in high-volume reading rooms. High-throughput radiology groups in academic medical centers maintain preference for dedicated workstations with calibrated diagnostic monitors.
- Cloud-based Solutions:Fully managed SaaS platforms with server-side rendering and elastic compute scaling. Research institutes and mid-sized imaging centers adopt these to eliminate capital expenditure on on-premises infrastructure.
Volume placements concentrate in Desktop Viewers; the faster expansion belongs to Cloud-based Solutions.
End User:
Customer type dictates purchasing authority structures, with centralized IT governance in hospital networks contrasting against principal-investigator-driven procurement at research institutions.
- Hospitals:Integrated delivery networks standardizing enterprise viewers across acquired facilities to unify radiology workflows and reduce interface maintenance burden.
- Imaging Centers:Independent diagnostic facilities prioritizing standalone viewer platforms with rapid deployment timelines and pay-per-study pricing models.
- Research Institutes:Academic medical centers requiring algorithm-integrated viewing environments for clinical trial imaging and multi-site research consortia with specialized DICOM tagging needs.
- Diagnostic Labs:High-volume pathology and radiology laboratories seeking AI-enhanced tools for quantitative image analysis and automated report generation.
Procurement volume clusters in Hospitals; Research Institutes are climbing the fastest as algorithm-integrated environments gain priority.
Technology:
Functional capability tiers separate basic visualization from advanced manipulation, with AI integration representing the emerging margin pool requiring specialized engineering investment.
- 3D Reconstruction:Volume rendering and multi-planar reconstruction engines for surgical planning and complex anatomy visualization. Orthopedic and cardiovascular service lines drive concentrated demand in tertiary care hospitals.
- DICOM Compatibility:Native support for DICOM standards including storage, query-retrieve, and modality worklist integration. This foundational capability underpins all enterprise deployments regardless of sophistication tier.
- Radiology Solutions:Purpose-built toolsets for diagnostic interpretation including hanging protocols, prior comparison, and measurement calibration. High-volume radiology groups in the United States maintain preference for specialized workflow optimization.
- AI-enhanced Tools:Algorithm-integrated viewing environments with FDA-cleared detection and quantification modules. Diagnostic labs and research institutes lead adoption as premarket review pathways mature.
Deployment breadth favors DICOM Compatibility; AI-enhanced Tools show steepest expansion trajectory as regulatory pathways clarify.
Deployment:
Infrastructure ownership models determine capital allocation patterns, with subscription economics displacing perpetual licensing in health systems prioritizing operational flexibility.
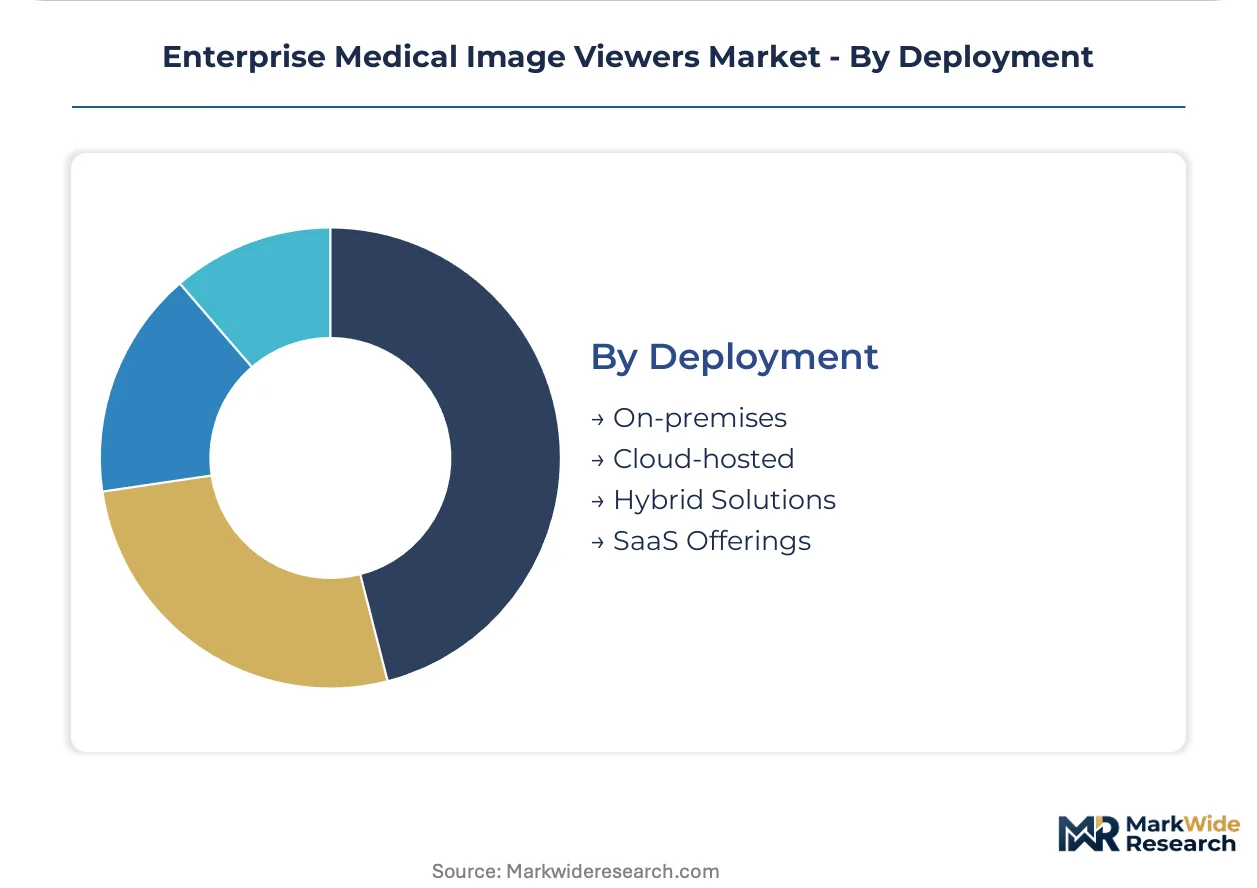
- On-premises:Viewer software deployed within hospital data centers with direct storage area network connectivity. Legacy PACS replacement cycles sustain demand among security-sensitive institutions with established infrastructure teams.
- Cloud-hosted:Fully externalized infrastructure with health system data residing in vendor-managed environments. HIPAA business associate agreement negotiations extend procurement timelines for these configurations.
- Hybrid Solutions:Architectures combining on-premises edge nodes for latency-sensitive interpretation with cloud archives for long-term storage and disaster recovery. Large United States health systems adopt this model to balance performance with remote access resilience.
- SaaS Offerings:Subscription-based licensing with usage-based pricing and automatic feature updates. Imaging centers and emerging market hospitals prioritize this model to eliminate upfront capital expenditure.
Current infrastructure stock concentrates in On-premises; Hybrid Solutions are gaining share fastest as health systems navigate cloud migration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health system consolidation and FDA guidance on AI-enabled radiology devices concentrate demand for enterprise viewer platforms. Cloud migration timelines vary sharply across national regulatory environments and infrastructure maturity. Procurement patterns in each major market reflect distinct compliance burdens and radiologist workflow preferences.
United States
Integrated delivery networks in Texas and California drive enterprise viewer standardization across multi-site acquisitions. FDA premarket review pathways for AI-enhanced radiology devices accelerate platform upgrade cycles. The Boston-Cambridge corridor anchors algorithm development partnerships between academic medical centers and viewer vendors.
Germany
University hospitals in Bavaria and North Rhine-Westphalia prioritize diagnostic workflow orchestration with sub-second latency guarantees. The EU AI Act introduces conformity assessment requirements that filter AI-enhanced viewer modules entering clinical use. Berlin-based research consortia demand specialized DICOM tagging for multi-site clinical trials.
United Kingdom
NHS England's imaging network consolidation creates procurement scale for cloud-hosted enterprise viewers. GDPR mandates govern protected health information handling across hospital networks and extend vendor qualification timelines. London's academic medical centers lead adoption of algorithm-integrated viewing environments for research applications.
Japan
Metropolitan Tokyo hospitals balance legacy PACS infrastructure with hybrid cloud architectures for disaster resilience. PMDA regulatory frameworks shape AI-enabled radiology device approval timelines and clinical validation requirements. Osaka-Kobe medical device clusters concentrate domestic viewer vendor engineering capabilities.
Australia
State-based health departments in New South Wales and Victoria consolidate radiology workflows across regional hospital networks. TGA conformity requirements govern software-as-a-medical-device classifications for cloud-hosted viewers. Melbourne's biomedical research precincts drive demand for algorithm-integrated environments in clinical trial imaging.
Enterprise Medical Image Viewers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with imaging modality OEMs bundling viewer software alongside hardware service contracts while standalone vendors compete on workflow specialization. The vendor base clusters around three strategic archetypes: legacy PACS incumbents with installed base leverage, cloud-native specialists with subscription economics, and vertical integrators controlling diagnostic workflow orchestration. Dominant competitive moves include unbundling viewer software from modality hardware contracts and establishing notified body relationships for EU AI Act pre-validation.
Among the modality-integrated tier, GE HealthCare Technologies Inc. and Philips Healthcare exemplify hardware-service bundling strategies that leverage installed imaging equipment bases. Sectra AB occupies a distinct position as a European specialist emphasizing diagnostic workflow depth over breadth. Cloud-native competition intensifies around Intelerad Medical Systems Inc. and Mach7 Technologies Pty Ltd, representing vendors with engineering architectures purpose-built for elastic compute scaling rather than legacy infrastructure migration.
| Leading Market Players |
|---|
| Pro Medicus Limited |
| Sectra AB |
| Agfa HealthCare N.V. |
| Mach7 Technologies Pty Ltd |
| Infinitt Healthcare Co., Ltd. |
| GE HealthCare Technologies Inc. |
| Intelerad Medical Systems Inc. |
| Hyland Software, Inc. |
| Philips Healthcare |
| Others |
Supply Flow & Price Mechanics
GPU compute capacity in cloud regions flows through subscription tiers to health system procurement committees, with serverless orchestration costs determining SaaS pricing floors against perpetual-license legacy alternatives.
Pricing Analysis
High-volume radiology groups anchor the volume tier through perpetual desktop licenses, while research institutes and mid-sized imaging centers drive margin expansion via AI-enhanced SaaS subscriptions. Price differentiation rests on FDA clearance tier and cloud deployment architecture, with HIPAA-compliant hybrid configurations commanding premiums over standard cloud-hosted tiers. Pricing pressure stems from unbundling trends as health systems separate viewer software from modality hardware service contracts. Imaging centers exhibit highest price sensitivity due to capital constraint, whereas academic medical centers prioritize algorithm integration over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for GPU semiconductor supply, with additional concentration in United States cloud infrastructure regions for HIPAA-compliant data residency. Raw material dependencies span high-performance computing chips, diagnostic-grade display panels, and DICOM middleware libraries. Tariff exposure on semiconductor imports creates procurement timeline uncertainty for on-premises hardware configurations. Distribution runs through direct enterprise sales teams for hospital networks, complemented by channel partnerships serving independent imaging centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise medical image viewers operate as a cost-of-compliance market where FDA premarket review pathways for AI-enabled radiology devices erect regulatory moats favoring vendors with established 510(k) track records.
For Market Incumbents: To counter cloud-native specialists with serverless GPU economics, legacy PACS vendors should deepen backward integration into diagnostic workflow orchestration and accelerate hybrid deployment certifications. Sustaining installed base leverage requires unbundling viewer software from hardware contracts before health system value analysis committees complete vendor standardization. For New Entrants and Emerging Players: EU AI Act conformity requirements in Europe open a window for algorithm-integrated viewing environments with pre-validated CE marking pathways. White-space concentration sits with research institutes requiring specialized DICOM tagging for multi-site clinical trials, best approached through academic medical center partnerships rather than hospital IT procurement. For Investors and Strategic Acquirers: FDA 510(k) clearance for AI-enhanced radiology modules is the leading indicator that a viewer vendor has crossed the regulatory barrier-to-entry threshold for sustainable market participation. Acquisition targets should display hybrid cloud engineering depth and established notified body relationships, with long-term viability hinging on algorithm integration velocity rather than legacy PACS migration capability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance validates algorithm performance for health system procurement committees evaluating AI-enhanced modules. |
| CE Marking Pathway | EU AI Act conformity enables market entry into German university hospitals and research consortia. |
| Hospital System Partnership | Integrated delivery network standardization contracts lock out competing vendors across multi-site acquisitions. |
| Software Companion Development | FDA-cleared detection algorithms differentiate viewer platforms in diagnostic lab procurement evaluations. |
| Reimbursement Strategy | CPT code alignment for AI-assisted interpretation accelerates hospital finance committee approval timelines. |
Methodological Framework
Document review covered FDA 510(k) filings, hospital procurement databases, and GPO contracts, complemented by interviews with radiology department chairs, biomedical engineers, health system CIOs, and GPO contracts managers. Secondary sources included CMS Medicare reimbursement data, DICOM standard committee documentation, and SEC filings from publicly traded imaging modality manufacturers. Bottom-up triangulation across deployment volume estimates and top-down validation against health system IT expenditure surveys anchored market sizing.
Market value outputs reflect cross-segment aggregation across product type, end user, technology tier, and deployment architecture dimensions over the projection horizon. CAGRs were derived from elasticity modeling against health system consolidation velocity and cloud migration adoption curves. Forecast inputs incorporated FDA premarket review timeline distributions and EU AI Act conformity assessment completion rates.
Caveats apply where HIPAA business associate agreement negotiation delays or EU notified body backlogs could materially shift the outlook for cloud-hosted and AI-enhanced module adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Ultrasound Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Portable MRI Market