
 Malaysia Digital Radiography Market | 2026-2036
Malaysia Digital Radiography Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Digital Radiography Market Foresight
Wireless detector integration with cloud-based PACS architecture is tilting procurement specifications toward interoperable, vendor-neutral platforms. GE Healthcare leverages its installed base of analog systems to anchor upgrade pathways across Peninsular Malaysia's public hospital network. Siemens Healthineers competes on detector sensitivity specifications, while Fujifilm Holdings specializes in retrofit kits that extend the service life of existing bucky stands.
Malaysia digital radiography encompasses X-ray imaging systems that convert ionizing radiation into digital signals through amorphous silicon or cesium iodide scintillator arrays, producing diagnostic images at spatial resolutions exceeding 2.5 line pairs per millimeter for immediate display and archival. Flat panel detectors command the dominant share of product type value pools, reflecting their superiority in dose efficiency and throughput speed over computed radiography systems. Mobile radiography units are gaining traction in end user segments where bed-bound patient volumes strain fixed-room capacity, particularly in hospitals managing high emergency department throughput.
Malaysia's Medical Device Authority enforces registration requirements under the Medical Device Act 2012, while the Ministry of Health's Health Technology Assessment Unit evaluates cost-effectiveness before public procurement approval. Compliance with these frameworks shapes vendor qualification timelines and influences hospital capital planning cycles. Stakeholders must monitor how BIS-equivalent standards for electromagnetic compatibility and radiation safety evolve alongside digital health interoperability mandates.
Market Dynamics
Malaysia's public hospital procurement under the Health Technology Assessment framework is compressing vendor qualification timelines and forcing interoperability specifications into every tender document. This centralized purchasing authority is digitizing radiography infrastructure across Peninsular Malaysia's tertiary care cluster faster than private capital cycles permit.
Growth Catalysts
- Health Technology Assessment mandates:Malaysia's Ministry of Health evaluates cost-effectiveness before approving capital expenditure, creating predictable demand pipelines for compliant vendors.
- Flat panel detector superiority:Amorphous silicon arrays deliver dose efficiency gains that Kuala Lumpur's oncology centers prioritize for pediatric and repeat-imaging protocols.
- Mobile radiography expansion:Bed-bound patient volumes in emergency departments are straining fixed-room capacity, driving orders for battery-powered wireless units.
Market Restraints
- Import dependency for scintillator materials:Cesium iodide crystal production concentrates in Japanese and German suppliers, exposing Malaysian buyers to currency volatility and extended lead times.
- Computed radiography installed base lock-in:Legacy phosphor plate systems in district hospitals create sunk-cost resistance despite higher per-exam operating expenses.
- Medical Device Act compliance friction:Malaysia's Medical Device Authority registration requirements extend vendor qualification timelines by 8-14 months for novel detector architectures.
Strategic Opportunities
- East Malaysia connectivity gap:Sabah and Sarawak's dispersed rural clinics lack PACS infrastructure, creating first-mover advantage for cloud-native, low-bandwidth imaging platforms.
- Retrofit kit penetration:Existing bucky stands in private diagnostic chains represent addressable hardware for detector-only upgrade paths.
- AI-assisted radiography integration:Automated exposure control and pathology flagging algorithms are converging with detector hardware, differentiating premium procurement tiers.
Industry Challenges
- Clinical engineer shortage:Malaysia produces fewer than 120 biomedical technicians annually, constraining preventive maintenance capacity for wireless detector fleets.
- Legacy PACS integration complexity:Hospital information systems from disparate vendors require custom DICOM middleware, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Digital Radiography Market |
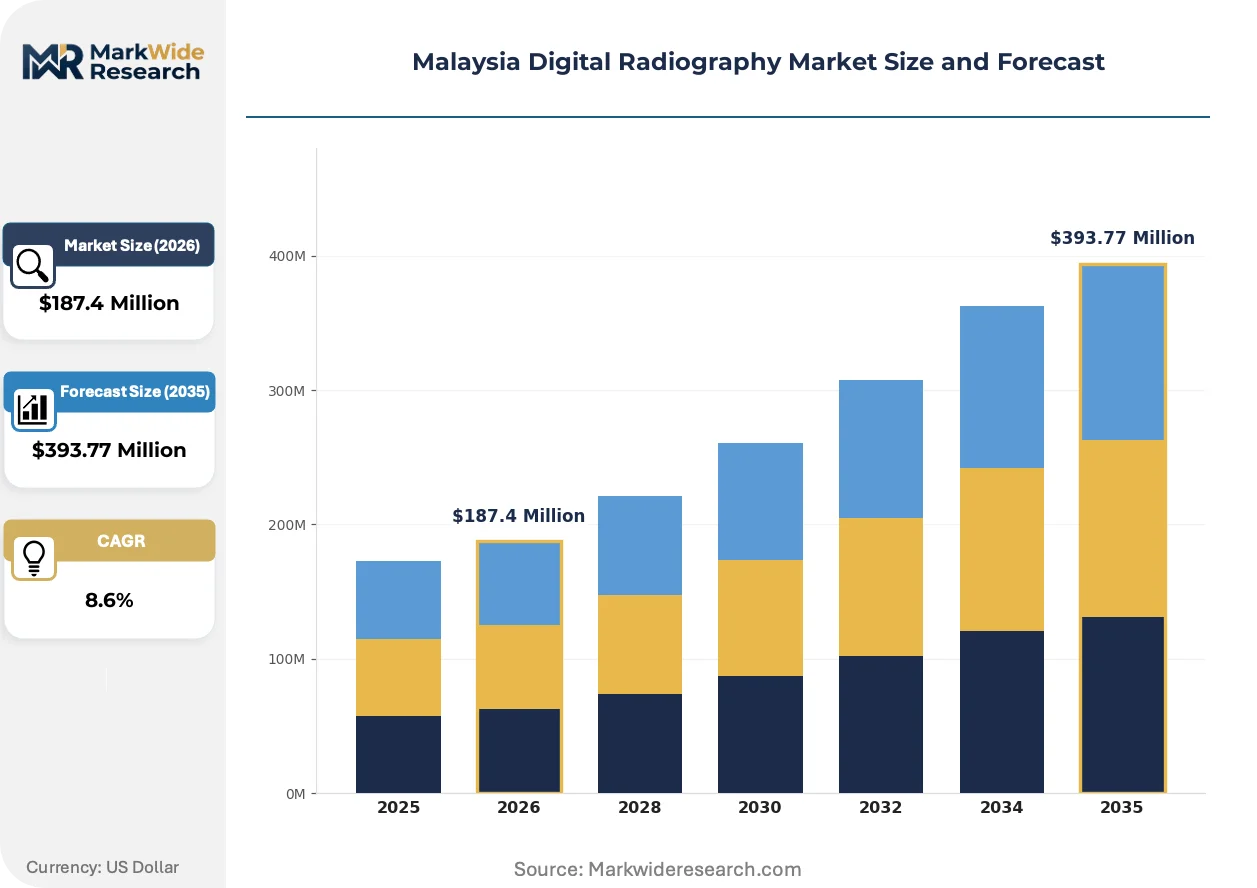
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Computed Radiography Systems, Mobile Radiography Units, Accessories End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Technology: Direct Radiography, Indirect Radiography, Hybrid Systems, Analog to Digital Conversion Application: Orthopedics, Cardiology, Oncology, General Radiography |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, Fujifilm Holdings, Agfa HealthCare, Konica Minolta, Carestream Health, DRGEM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Digital Radiography Market Shifts & Advancements
Wireless detector architectures are compressing the traditional radiography value chain by eliminating cassette handling and enabling point-of-care imaging. Three developments are restructuring competitive positioning in Malaysia's procurement landscape.
Direct radiography flat panels with cesium iodide scintillator layers are digitizing image acquisition workflows in Kuala Lumpur's public hospital network. The Ministry of Health's tertiary referral centers are adopting these systems at replacement-cycle pace, collapsing the distinction between acquisition hardware and diagnostic display infrastructure.
Malaysia's Medical Device Authority is tightening electromagnetic compatibility enforcement under BIS-equivalent standards, forcing detector manufacturers to recertify existing product lines. This regulatory friction most affects mobile radiography units, where battery management systems and wireless transmission modules require redesigned shielding architectures.
Public hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, creating standalone service markets. Private diagnostic chains in Selangor and Johor are responding by negotiating multi-site detector maintenance agreements, shifting vendor relationships from transactional sales to performance-based partnerships.
Malaysia Digital Radiography Market Segmentation
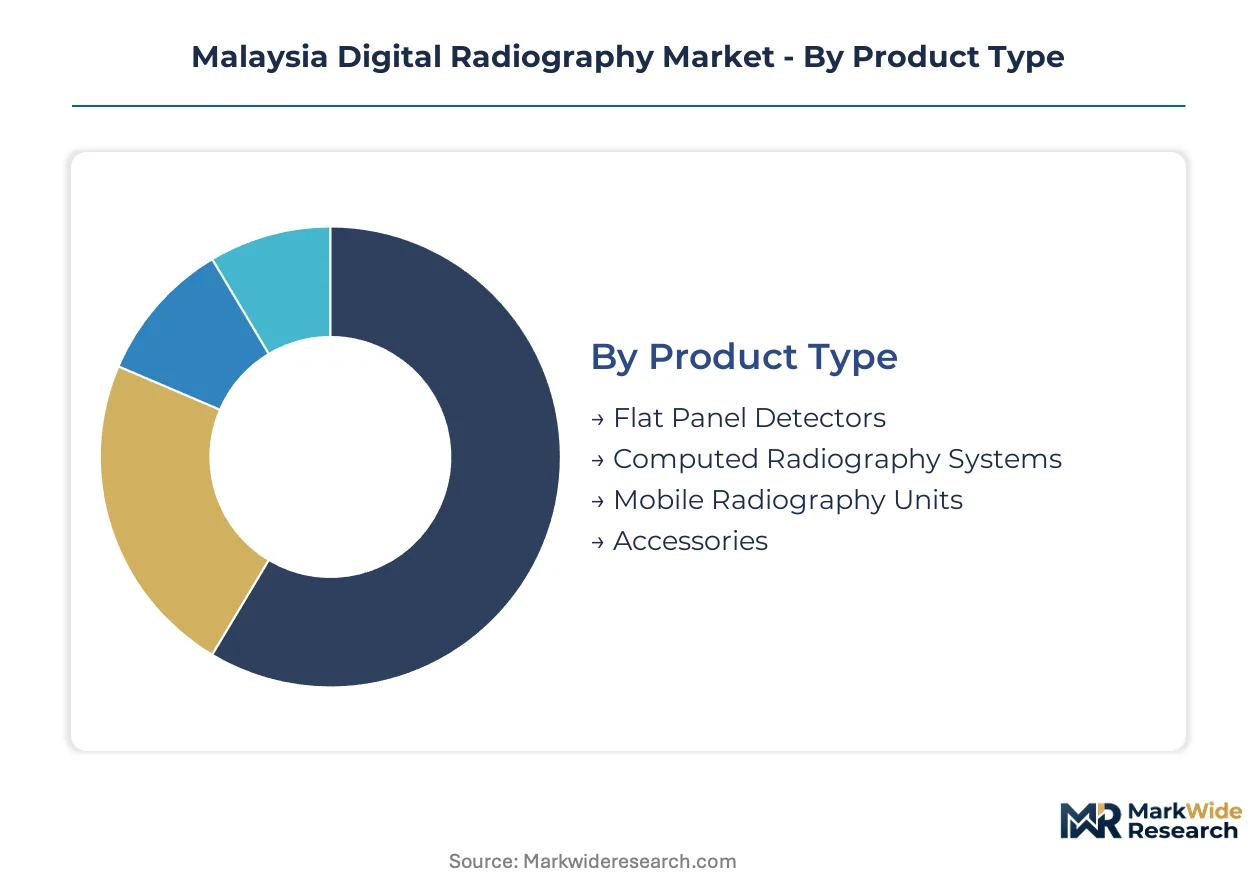
Digital radiography procurement in Malaysia follows distinct replacement cycles across hardware categories, with detector technology turnover accelerating while infrastructure investments stretch across decades. Understanding these cadences reveals where vendor revenue concentrates versus where maintenance contracts generate recurring value.
Product Type:
Replacement cycles vary dramatically: flat panel detectors turn over every 5-7 years as sensitivity thresholds advance, while computed radiography infrastructure persists for 12-15 years despite higher operating costs.
- Flat Panel Detectors:Amorphous silicon arrays with cesium iodide scintillator layers convert X-ray photons directly into electrical signals at spatial resolutions exceeding 2.5 line pairs per millimeter. Kuala Lumpur's tertiary oncology centers prioritize these for pediatric protocols where dose reduction commands premium procurement budgets.
- Mobile Radiography Units:Battery-powered wireless detector systems mounted on motorized chassis enable bedside imaging in emergency departments and intensive care wards. Hospital networks in Selangor and Johor are expanding fleets to address bed-bound patient volumes that strain fixed-room capacity.
- Computed Radiography Systems:Photostimulable phosphor plate technology dominates district hospital installed bases where capital constraints delay digital migration.
- Accessories:Detector protection housings, anti-scatter grids, and calibration phantoms constitute recurring revenue streams tied to detector replacement cycles.
Flat Panel Detectors dominate installed base. Mobile Radiography Units are where expansion concentrates.
End User:
Purchasing authority concentrates differently across settings: public hospitals centralize procurement through the Health Technology Assessment Unit, while private diagnostic chains negotiate multi-site maintenance agreements.
- Hospitals:Malaysia's Ministry of Health operates 145 public hospitals where centralized tendering under the Medical Device Act 2012 compresses vendor qualification timelines. Tertiary referral centers in Kuala Lumpur and Penang drive detector specification standards that cascade to district facilities.
- Diagnostic Centers:Private imaging chains in Selangor and Johor specialize in high-throughput screening workflows, prioritizing throughput speed over dose efficiency in procurement decisions.
- Research Institutions:University medical centers require specialized detectors for protocol development and clinical trial imaging.
- Outpatient Clinics:General practitioner networks in urban corridors are adopting compact retrofit solutions for basic skeletal and chest imaging.
Hospitals anchor procurement volume. Diagnostic Centers are climbing the fastest.
Technology:
Architecture choices determine total cost of ownership: direct radiography eliminates chemical processing entirely, while hybrid approaches preserve legacy infrastructure investments.
- Direct Radiography:Amorphous selenium or cesium iodide detectors capture X-ray energy without intermediate conversion steps, delivering immediate digital output. The Ministry of Health's tertiary care cluster is standardizing on this architecture for new installations.
- Indirect Radiography:Scintillator-based systems with amorphous silicon photodiode arrays balance sensitivity and cost, finding preference in mid-tier hospital upgrades.
- Hybrid Systems:Configurations supporting both cassette-based and wireless detector workflows ease transition paths for facilities with mixed equipment generations.
- Analog to Digital Conversion:Retrofit kits that digitize existing bucky stands extend service life of installed base while deferring full replacement capital.
Direct Radiography dominates installed base. Indirect Radiography is where expansion concentrates.
Application:
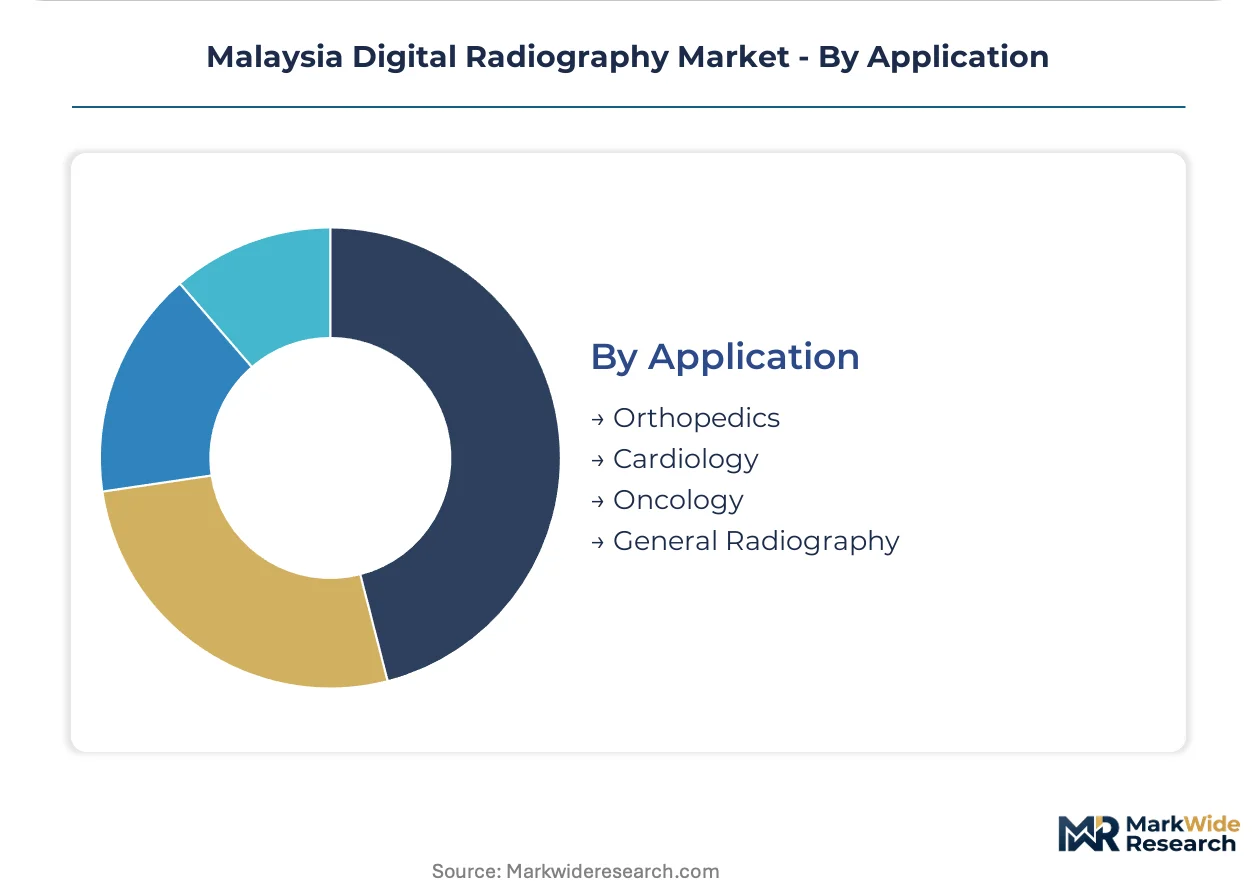
Clinical use cases impose divergent technical requirements: oncology demands sub-millimeter resolution for tumor boundary definition, while general radiography prioritizes throughput velocity.
- Orthopedics:High-resolution imaging of bone microarchitecture requires detectors with enhanced dynamic range to capture both cortical density and soft tissue detail in single exposures. Sports medicine centers in Kuala Lumpur are driving demand for weight-bearing extremity systems.
- Oncology:Pediatric and repeat-imaging protocols in cancer centers mandate the lowest achievable dose, pushing procurement toward direct radiography with optimized detective quantum efficiency.
- Cardiology:Cardiac catheterization suites require rapid frame rates and synchronized acquisition timing.
- General Radiography:Chest and abdominal screening constitute volume workhorse applications where detector durability and workflow integration outweigh incremental sensitivity gains.
General Radiography dominates installed base. Oncology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese detector component suppliers export cesium iodide scintillator arrays and amorphous silicon photodiodes to Malaysian hospital networks and diagnostic chains. These trade corridors concentrate in Kuala Lumpur's tertiary care cluster and radiate outward to Peninsular Malaysia's district hospitals.
Peninsular Malaysia
Centralized procurement through the Ministry of Health's Health Technology Assessment Unit drives detector standardization across 145 public hospitals. The Medical Device Act 2012 compresses vendor qualification timelines for direct radiography systems. Kuala Lumpur's tertiary referral centers anchor specification standards that cascade to district facilities in Selangor and Johor.
Sabah
Dispersed rural clinics in East Malaysia lack PACS infrastructure and rely on mobile radiography units for bed-bound patient imaging. The national broadband initiative targets connectivity gaps for cloud-native imaging platforms. Kota Kinabalu's public hospital network pilots low-bandwidth digital radiography deployments.
Sarawak
Riverine communities and remote interior clinics create demand for battery-powered wireless detector systems. The state's health department prioritizes portable imaging for emergency department throughput. Kuching's specialist hospitals serve as procurement coordination hubs for regional diagnostic networks.
Johor
Private diagnostic chains in this southern state negotiate multi-site maintenance agreements for high-throughput screening workflows. Cross-border patient flows from Singapore influence premium detector specifications. Iskandar Malaysia's medical tourism corridor drives demand for weight-bearing extremity systems in sports medicine centers.
Penang
Island-based tertiary centers compete on detector sensitivity specifications for oncology and pediatric protocols. The state's industrial electronics ecosystem supports local biomedical technician training programs. George Town's hospital cluster standardizes on vendor-neutral PACS architectures for interoperability compliance.
Malaysia Digital Radiography Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Malaysia's procurement landscape. The market structures around three tiers: multinational imaging conglomerates with installed base leverage, detector technology specialists competing on sensitivity specifications, and retrofit kit providers extending legacy equipment service life. Consolidation pressures intensify as public hospital networks unbundle after-sales service contracts from capital purchases. Dominant competitive moves include strategic partnerships with local biomedical service providers and portfolio diversification into AI-assisted radiography modules.
Within the multinational conglomerate tier, GE Healthcare and Siemens Healthineers occupy positions shaped by their respective strengths in upgrade pathway anchoring and detector sensitivity specification competition. Fujifilm Holdings represents the retrofit specialist archetype, exemplifying strategies that preserve existing bucky stand investments while enabling digital migration. These three players collectively illustrate how vendor relationships shift from transactional equipment sales toward performance-based partnerships under Malaysia's centralized procurement framework.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems |
| Fujifilm Holdings |
| Agfa HealthCare |
| Konica Minolta |
| Carestream Health |
| DRGEM |
| Others |
Supply & Pricing Matrix
Overcapacity in Japan's cesium iodide crystal fabrication facilities is compressing scintillator pricing and forcing Malaysian detector vendors to absorb margin erosion while maintaining Health Technology Assessment compliance costs. This utilization slack ripples through procurement negotiations, amplifying buyer leverage in Kuala Lumpur's centralized tendering environment.
Pricing Analysis
Current-generation flat panel detectors command substantial premiums over prior-generation computed radiography systems and emerging next-generation photon-counting architectures. Three-tier pricing structure across premium, standard, and economy levels reflects detector sensitivity specifications and after-sales service bundling. Cost compression in mid-tier indirect radiography is intensifying because private diagnostic chains in Selangor negotiate multi-site volume discounts. Public hospital procurement committees exhibit lowest price sensitivity due to HTA-mandated total cost-of-ownership frameworks, while outpatient clinics demonstrate highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Contract manufacturing for amorphous silicon photodiode arrays concentrates in Taiwan's semiconductor foundries and South Korea's display panel specialists, with final detector assembly distributed across Malaysian and Singaporean facilities. Geographic supply concentration centers on Japan and Germany for cesium iodide scintillator crystals, Taiwan for TFT backplane substrates, and China for anti-scatter grid components. Raw material dependencies rest on rare-earth phosphors, high-purity silicon wafers, and lithium-ion battery cells for mobile units. Single-source vulnerability in Japanese scintillator supply exposes Malaysian buyers to currency volatility and extended lead times. Distribution runs through authorized medical device distributors with Ministry of Health registration credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's digital radiography market functions as a defensive-moat arena where regulatory entrenchment through Medical Device Act compliance creates formidable barriers against unqualified competitors. Switching costs for hospital networks locked into vendor-specific PACS architectures reinforce incumbent positions.
For Market Incumbents: Build certification moats by accelerating Medical Device Authority registration timelines for next-generation detector architectures before emerging Korean manufacturers achieve compliance traction. Deepen backward integration into scintillator supply through long-term offtake agreements with Japanese crystal growers, insulating against currency-driven cost volatility. Anchor upgrade pathways across Peninsular Malaysia's public hospital network by unbundling service contracts from capital sales, converting transactional relationships into performance-based partnerships with predictable recurring revenue streams. For New Entrants and Emerging Players: Establish a beachhead in Sabah and Sarawak's connectivity-constrained rural clinics where cloud-native, low-bandwidth imaging platforms address unmet PACS infrastructure gaps. Target retrofit kit penetration across private diagnostic chains in Johor and Selangor, where existing bucky stands represent addressable hardware for detector-only upgrade paths. Prioritize AI-assisted radiography integration as a go-to-market differentiator, converging automated exposure control algorithms with detector hardware to capture premium procurement tiers in oncology centers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-contract unbundlers with established biomedical technician training pipelines and multi-site maintenance agreements. Long-term viability favors vendors with demonstrated Health Technology Assessment navigation capabilities and vendor-neutral PACS interoperability credentials. Acquisition target archetype: regional detector specialists with existing Medical Device Authority registrations and installed base leverage in East Malaysia. Monitor HTA evaluation criteria shifts toward dose-efficiency metrics as an inflection indicator for technology-generation transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Medical Device Authority Registration Acceleration | Compresses vendor qualification timelines by 8-14 months for novel detector architectures. |
| Cloud-Native PACS Platform Development | Captures first-mover advantage in Sabah and Sarawak's bandwidth-constrained rural networks. |
| AI-Assisted Radiography Module Integration | Differentiates premium procurement tiers through automated exposure control and pathology flagging. |
| Multi-Site Service Contract Unbundling | Shifts revenue mix from transactional equipment sales to performance-based recurring partnerships. |
| Biomedical Technician Training Pipeline Investment | Addresses Malaysia's clinical engineer shortage constraining wireless detector fleet maintenance capacity. |
Research Methodology
Operator-level perspectives from hospital procurement committee members, biomedical engineers, clinical radiologists, and Medical Device Authority registration specialists anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation from Ministry of Health tender databases, GPO contract repositories, and Medical Device Act regulatory filings. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the Malaysian healthcare infrastructure investment landscape.
Scenario-bracketing around HTA approval velocity, scintillator supply disruptions, and public hospital capital allocation priorities bounded forecast uncertainty across the analysis window. Segmentation dimensions modeled include product type, end-user category, technology architecture, and clinical application with regional procurement pattern differentiation. CAGRs derived from replacement cycle analysis, installed base migration trajectories, and detector sensitivity specification evolution. Forecast inputs incorporated Health Technology Assessment framework adoption rates and East Malaysia connectivity infrastructure deployment timelines.
Stress conditions across currency volatility in yen-ringgit cross-rates, cesium iodide supply interruptions, and HTA evaluation criteria shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding public hospital network expansion cadence and private diagnostic chain consolidation patterns. Quarterly review of Medical Device Authority registration queue depths and Ministry of Health tender award frequencies is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
United Kingdom Nuclear Imaging Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
France Mammography Market
Medical Imaging
India Magnetic Resonance Imaging Market