
 Radiation Dose Management Market | 2026-2036
Radiation Dose Management Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Dose Management Market Intelligence
A wide capital-intensity gap between imaging OEMs and software specialists is rotating competitive dynamics across the sector. Siemens Healthcare leverages its installed base of CT and angiography systems to bundle dose management modules directly into modality workflows. Mirion Technologies Inc. sustains leadership in independent hardware dosimetry, competing against integrated platforms from GE Healthcare and Philips Healthcare.
Radiation dose management encompasses software systems, hardware dosimeters, and services that capture, track, and analyze ionizing radiation exposure across medical imaging procedures, typically measuring cumulative dose in millisieverts (mSv) and generating diagnostic reference levels for quality assurance. These systems serve primarily to reduce patient and staff exposure while maintaining diagnostic image quality and ensuring institutional compliance with safety thresholds. Software and analytics platforms now capture the largest revenue share as hospitals prioritize real-time dashboarding and predictive alerting over passive record-keeping. Cloud-based deployment is expanding fastest among mid-sized diagnostic centers seeking lower IT overhead and remote access to multi-site dose registries.
The FDA's 21 CFR Part 1020 regulations mandate performance standards for diagnostic x-ray systems, while the Joint Commission's sentinel event alerts on radiation overdose drive hospital procurement of automated monitoring tools. In Europe, the EURADOS network and national dose registries under the EU BSS Directive shape product requirements for cross-border data portability and standard cumulative dose reporting. Stakeholders must weigh the trade-off between vendor-integrated solutions and best-of-breed analytics platforms as regulatory granularity tightens and hospital procurement shifts toward enterprise-wide exposure governance.
Market Dynamics
AI-enabled analytics platforms are compressing the value chain by embedding predictive alerting directly into imaging workflows, forcing independent software vendors to demonstrate superior interoperability against modality-integrated suites from Siemens Healthcare and GE Healthcare.
Growth Catalysts
- Joint Commission sentinel event alerts:US hospitals face accreditation pressure to deploy automated dose monitoring, accelerating procurement of real-time dashboarding systems across emergency and interventional radiology departments.
- Cloud-based deployment models:Mid-sized diagnostic centers in Germany and the United States are prioritizing software-as-a-service architectures to reduce IT overhead and enable multi-site dose registry access.
- EURADOS exposure benchmarks:European national dose registries under the EU BSS Directive mandate systematic cumulative dose reporting, creating procurement pull for cross-border data portability solutions.
Market Restraints
- Vendor lock-in from integrated modality suites:Siemens Healthcare and Philips Healthcare bundle dose management modules with CT and angiography systems, constraining standalone software penetration.
- IT infrastructure fragmentation:Hospital legacy PACS and RIS architectures require costly middleware development to achieve real-time dose data normalization.
- Specialized clinical informatics talent scarcity:Health systems struggle to recruit personnel capable of configuring predictive alerting rules and interpreting diagnostic reference level deviations.
Strategic Opportunities
- Pediatric imaging specialization:Children's hospitals in the United States require age-adjusted dose protocols and longitudinal exposure tracking, creating demand for niche analytics modules.
- Interventional cardiology expansion:Electrophysiology labs in Germany generate high cumulative staff exposure, driving demand for real-time wearable dosimetry integration with procedure documentation systems.
- FDA 21 CFR Part 1020 enforcement tightening:Enhanced inspection focus on diagnostic x-ray performance standards creates compliance service revenue streams for independent software vendors.
Industry Challenges
- Multi-vendor interoperability certification:Standalone platforms must achieve seamless data exchange with GE Healthcare, Siemens Healthcare, and Philips Healthcare imaging systems, extending sales cycles by 6-12 months.
- Legacy RIS/PACS integration complexity:Hospital IT departments face resource constraints when deploying dose management overlays atop decades-old radiology information infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Dose Management Market |
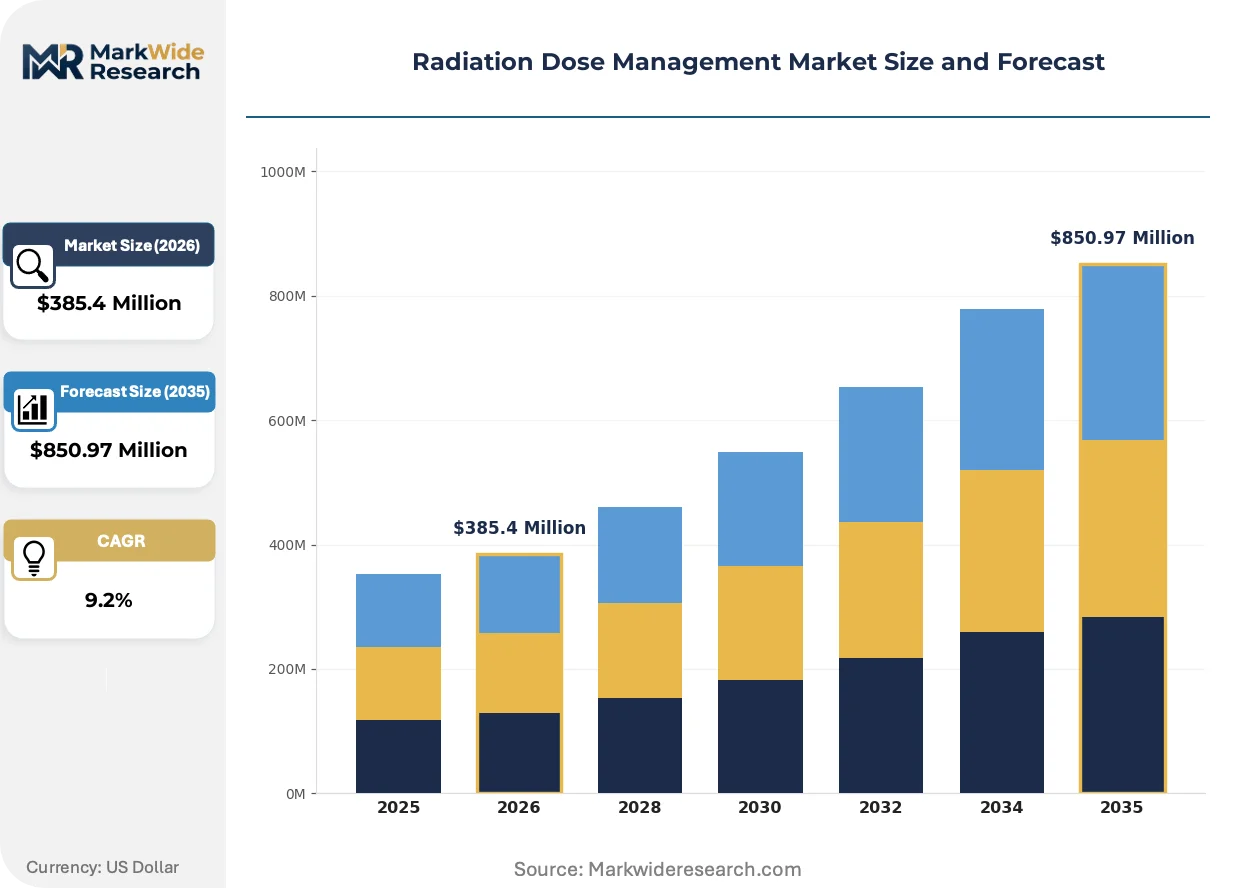
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $850.97 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Analytics Platforms, Compliance Tools Application: Diagnostic Radiology, Interventional Radiology, Nuclear Medicine, Radiation Therapy, Dental Imaging End User: Hospitals, Specialty Clinics, Diagnostic Centers, Ambulatory Surgical Centers, Research Institutes Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Mobile Integration, Web-Based Platforms |
| Companies Covered | Siemens Healthcare, Canon Inc., Bayer AG, Sectra AB, Mirion Technologies Inc., GE Healthcare, FUJIFILM Holdings Corporation, INFINITT Healthcare Co. Ltd., Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Dose Management Market Strategic Shifts & Innovations
Machine learning inference at the edge is compressing latency between exposure capture and clinical alerting, while regulatory granularity tightens around pediatric and interventional use cases. Procurement criteria are pivoting from passive record-keeping toward predictive governance capabilities.
Deep learning algorithms trained on institutional dose archives are displacing rule-based threshold alerting in high-volume CT departments. Academic medical centers in the United States deploy these models to flag outlier protocols before patient discharge. The technology is displacing retrospective quality assurance reviews with real-time intervention loops that intercept non-optimized scan parameters.
The EU BSS Directive's cumulative dose reporting mandates are reshaping product roadmaps toward cross-border registry interoperability. German and French hospitals must now export standardized dose data to national repositories, forcing vendors to adopt HL7 FHIR and DICOM SR formats. European software specialists are responding by pre-certifying cloud architectures for transnational data residency compliance.
Hospital procurement committees now unbundle dose management software from modality purchase decisions, evaluating standalone analytics platforms on predictive accuracy metrics. This pattern is most visible in United States health systems with centralized IT governance, where radiology departments lose autonomy over vendor selection. Third-party specialists gain traction when demonstrating superior interoperability across heterogeneous installed bases.
Radiation Dose Management Market Segmentation
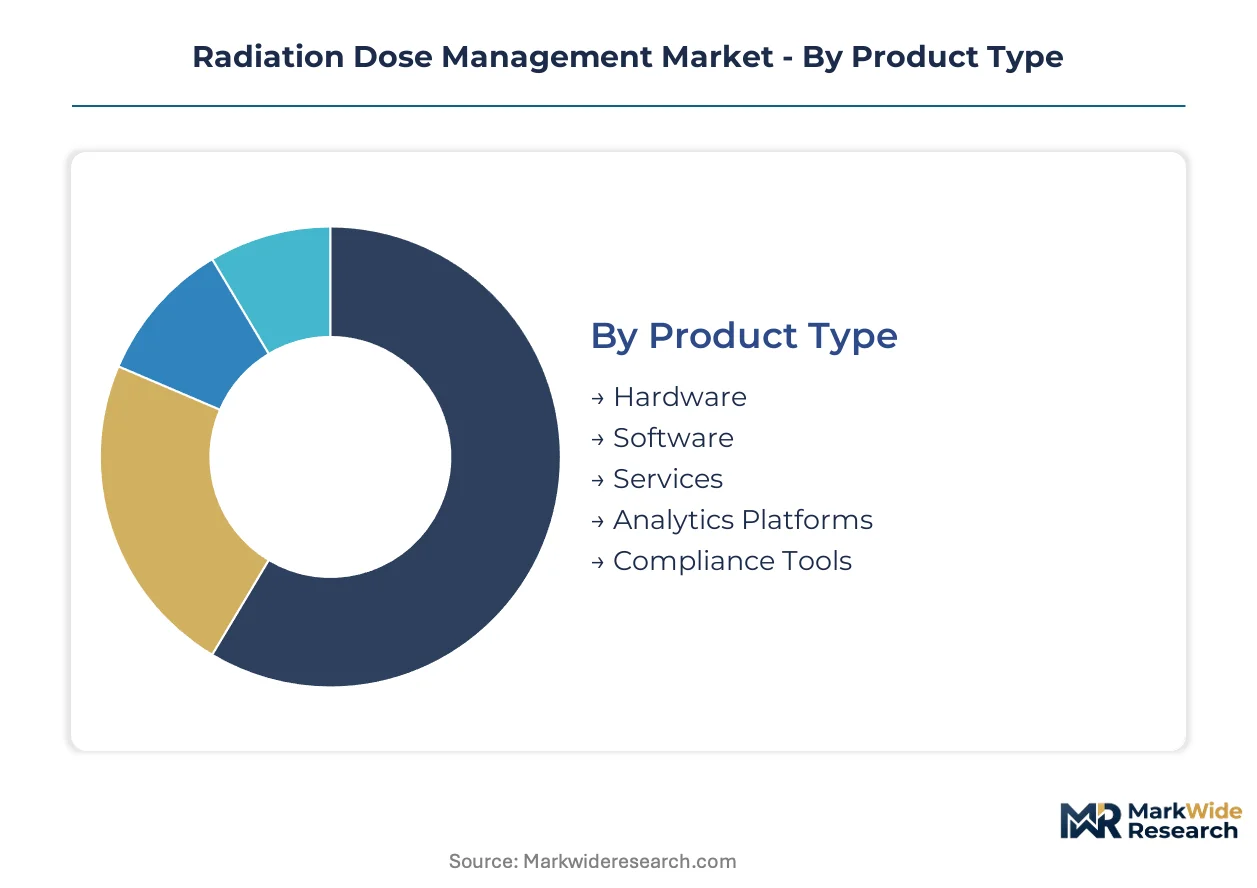
Radiation dose management procurement varies sharply by product architecture and clinical setting. Regulatory mandates from FDA and EURADOS reshape how hospitals prioritize software analytics over hardware dosimetry, while deployment models determine IT resource allocation across facility types.
Product Type:
FDA 21 CFR Part 1020 performance standards and EU BSS Directive cumulative reporting requirements differentiate procurement priorities across product categories, with software platforms capturing disproportionate capital allocation.
- Software:Real-time dashboarding systems capture ionizing exposure data from CT, fluoroscopy, and angiography workflows. Hospitals in Germany and the United States prioritize these platforms to automate Joint Commission compliance and EURADOS benchmark reporting.
- Analytics Platforms:Machine learning inference engines trained on institutional dose archives enable predictive alerting before patient discharge. Academic medical centers in the United States deploy these to flag outlier protocols, displacing retrospective quality assurance reviews.
- Hardware:Wearable dosimeters and area monitors measure staff and patient exposure in millisieverts.
- Services:Implementation consulting and compliance auditing support legacy RIS/PACS integration.
- Compliance Tools:Automated reporting modules format dose data for regulatory submission.
Software handles the majority of throughput; Analytics Platforms are the fastest mover on share.
Application:
Procedure volume and cumulative exposure risk concentrate demand in high-throughput imaging modalities, with pediatric and interventional use cases commanding premium pricing for specialized protocols.
- Diagnostic Radiology:CT departments generate the highest procedure volumes and dose management software penetration. German hospitals deploy these systems to feed standardized data into national dose registries under EURADOS frameworks.
- Interventional Radiology:Electrophysiology labs and angiography suites produce acute staff exposure events requiring real-time wearable dosimetry integration. German catheterization labs drive demand for procedure-linked exposure documentation.
- Nuclear Medicine:PET and SPECT procedures require radiopharmaceutical dose tracking alongside imaging exposure.
- Radiation Therapy:Linear accelerator quality assurance demands precise beam output verification.
- Dental Imaging:Cone-beam CT adoption in orthodontics creates decentralized dose monitoring needs.
Diagnostic Radiology absorbs the largest capital deployment; Interventional Radiology is expanding most quickly as procedural volumes climb.
End User:
IT governance centralization and accreditation pressure stratify procurement authority, with health system headquarters increasingly overriding radiology department vendor preferences.
- Hospitals:Integrated delivery networks in the United States mandate enterprise-wide dose governance platforms spanning emergency, interventional, and pediatric departments. Joint Commission sentinel event alerts drive automated monitoring procurement across these systems.
- Diagnostic Centers:Mid-sized imaging facilities in Germany prioritize cloud-based SaaS architectures to reduce IT overhead and enable multi-site registry access without dedicated informatics staff.
- Specialty Clinics:Cardiology and orthopedic focused facilities require modality-specific dose protocols.
- Ambulatory Surgical Centers:Limited imaging volumes constrain standalone software investment.
- Research Institutes:Clinical trial protocols demand longitudinal exposure tracking for regulatory submission.
Hospitals command the dominant share of vendor revenue; Diagnostic Centers are gaining share fastest through cloud migration.
Deployment:
Data residency requirements under GDPR and FDA cybersecurity guidance fragment cloud adoption patterns, with hybrid architectures emerging as a compliance-driven compromise.
- Cloud-Based:SaaS architectures enable remote access to multi-site dose registries without on-premise server maintenance. German diagnostic centers adopt these models to satisfy EU BSS Directive cross-border data portability mandates.
- On-Premise:Air-gapped installations persist in United States health systems with strict cybersecurity policies or legacy PACS dependencies requiring middleware development.
- Hybrid Solutions:Local caching with cloud analytics balances latency and accessibility.
- Mobile Integration:Tablet-based alerting extends real-time exposure monitoring into procedure rooms.
- Web-Based Platforms:Browser-accessible dashboards reduce client-side software maintenance.
Cloud-Based deployment carries the steepest expansion trajectory; On-Premise retains entrenched positions in security-sensitive installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic centers in Germany exhibit the highest price elasticity, deferring procurement until cloud SaaS models reduce IT overhead, while United States academic medical centers absorb premium analytics pricing for predictive alerting capabilities.
United States
Joint Commission sentinel event alerts drive automated dose monitoring procurement across emergency and interventional radiology departments. FDA 21 CFR Part 1020 enforcement tightening creates compliance service revenue streams for independent software vendors. Academic medical centers in Boston and the Research Triangle deploy machine learning inference engines to flag outlier protocols before patient discharge.
Germany
Mid-sized diagnostic centers prioritize software-as-a-service architectures to reduce IT overhead and enable multi-site registry access. The EU BSS Directive mandates systematic cumulative dose reporting, forcing vendors to adopt HL7 FHIR and DICOM SR formats for cross-border data portability. Catheterization labs in Munich and Heidelberg drive demand for real-time wearable dosimetry integration with procedure documentation systems.
United Kingdom
Health systems with centralized IT governance unbundle dose management software from modality purchase decisions, evaluating standalone analytics platforms on predictive accuracy metrics. The Medicines and Healthcare products Regulatory Agency enforces performance standards for diagnostic x-ray systems. London teaching hospitals concentrate procurement authority for enterprise-wide exposure governance platforms spanning pediatric and interventional departments.
Japan
Metropolitan medical centers adopt hybrid cloud architectures to balance latency and accessibility while satisfying data residency requirements. The Pharmaceuticals and Medical Devices Agency oversees software-as-a-service certification for clinical decision support tools. Osaka and Nagoya clusters concentrate demand for AI-enabled analytics platforms embedding predictive alerting directly into imaging workflows.
France
National dose registries under EURADOS frameworks reshape product roadmaps toward cross-border registry interoperability. The Agence Nationale de Sécurité du Médicament et des Produits de Santé regulates software medical devices for radiation exposure monitoring. Paris and Lyon hospital networks pre-certify cloud architectures for transnational data residency compliance.
Radiation Dose Management Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the radiation dose management sector. Imaging OEMs leverage installed bases to bundle dose management modules directly into modality workflows, while independent software vendors compete on interoperability and predictive analytics accuracy. Three strategic archetypes dominate: integrated modality suites, standalone analytics specialists, and hardware dosimetry manufacturers. Competitive dynamics center on multi-vendor interoperability certification and cloud architecture pre-certification for regulatory compliance.
Within the integrated modality tier, Siemens Healthcare and GE Healthcare exemplify players leveraging captive CT and angiography installed bases to embed dose tracking software. Philips Healthcare occupies a position bridging hardware integration and standalone analytics. Mirion Technologies Inc. anchors the independent hardware dosimetry archetype, competing against bundled solutions through specialized radiation measurement capabilities.
| Leading Market Players |
|---|
| Siemens Healthcare |
| Canon Inc. |
| Bayer AG |
| Sectra AB |
| Mirion Technologies Inc. |
| GE Healthcare |
| FUJIFILM Holdings Corporation |
| INFINITT Healthcare Co. Ltd. |
| Philips Healthcare |
| Others |
Cost & Logistics Intelligence
Long-term SaaS subscription contracts lock in both supply access and price visibility for German diagnostic centers seeking EURADOS-compliant dose registries, while United States health systems negotiate enterprise-wide licensing to secure predictive analytics modules across heterogeneous imaging fleets.
Pricing Analysis
After-sales service and extended compliance consulting contracts drive lifetime value for analytics platform vendors. Pricing stratifies across premium, standard, and economy tiers based on AI inference capability depth and FDA 510(k) clearance status. Cost compression in standard-tier SaaS offerings is intensifying because mid-sized diagnostic centers demand modular procurement without implementation overhead. Pediatric imaging specialists exhibit lowest price sensitivity due to specialized protocol requirements and longitudinal tracking mandates.
Supply Chain Analysis
Germany and the United States anchor software development and cloud infrastructure provisioning for dose management platforms. Component sourcing draws from Taiwan for edge-computing hardware and Ireland for data residency-compliant server architecture. Single-source vulnerability concentrates in DICOM SR parsing engines licensed from specialized medical informatics houses. Distribution runs through direct enterprise sales teams and radiology GPO consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as hospital procurement centralization unbundles dose management from modality purchases, creating niches for interoperability-first specialists.
For Market Incumbents: Compound installed base advantages by embedding predictive alerting deeper into CT and angiography workflows while acquiring cloud-native analytics firms to neutralize interoperability threats. Prioritize HL7 FHIR certification investment to defend against standalone platforms penetrating multi-vendor environments. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for AI-enabled pediatric dose protocols unlock white-space access in children's hospitals requiring age-adjusted cumulative tracking. Target cloud-native deployment in German mid-sized diagnostic centers where IT overhead sensitivity exceeds brand loyalty. Lead with SaaS pricing transparency against opaque bundled contracts. For Investors and Strategic Acquirers: Cloud-architecture specialists with pre-certified EU GDPR compliance represent the priority acquisition archetype for platform consolidation plays. Long-term viability hinges on regulatory data portability mandates expanding beyond EURADOS frameworks. Watch for Joint Commission sentinel event alert expansion into dental imaging as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| HL7 FHIR Pre-Certification | Ensures cross-border data portability for German and French national dose registries. |
| Pediatric Protocol Specialization | Captures premium pricing from United States children's hospitals facing malpractice exposure. |
| Cloud-Native Architecture Migration | Reduces IT overhead for mid-sized diagnostic centers in Germany seeking SaaS deployment. |
| AI Inference Engine Development | Displaces rule-based alerting in academic medical centers with real-time protocol optimization. |
| Enterprise Licensing Expansion | Consolidates procurement authority across United States integrated delivery networks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiology department heads, hospital IT procurement officers, biomedical informatics specialists, and GPO contract managers. Secondary validation drew from FDA 510(k) clearance databases, EURADOS technical reports, hospital procurement RFP archives, and DICOM standards committee publications. Bottom-up facility-level deployment estimates were triangulated against top-down vendor revenue segmentation.
Across the analysis window, forecasts modeled software platform penetration by deployment architecture, end-user facility type, and regulatory compliance tier alongside procedure volume growth in CT and interventional modalities. CAGRs were derived from weighted regression of historical adoption curves against Joint Commission enforcement intensity and EU BSS Directive implementation phases. Cloud migration velocity and AI module attach rates served as key sensitivity inputs.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement and stable hospital capital allocation; material deviation in FDA inspection frequency or EU data residency rulings would warrant model refresh. Recalibration cycles align with material shifts in accreditation pressure and cross-border registry interoperability mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Fluorescence Microscopy Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Italy Magnetic Resonance Imaging Market
Medical Imaging
Contrast Media Market
Medical Imaging
Dental Imaging Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Image Guided Systems Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
US Imaging Services Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
Digital Mammography Market