
 Asia-Pacific Computer-Aided Drug Discovery Market | 2026-2036
Asia-Pacific Computer-Aided Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Computer-Aided Drug Discovery Market Analytics
China's biotech corridor expansion is reshaping regional capacity for structure-based drug design. WuXi AppTec leverages its integrated discovery platform to anchor large-molecule computational workflows across Shanghai and Suzhou sites. Pharmaron sustains R&D intensity through specialized artificial intelligence teams embedded in its medicinal chemistry divisions. Syngene International competes by extending bioinformatics services from its Bangalore hub to Japanese and Australian sponsors seeking cost-efficient target validation.
Computer-aided drug discovery encompasses computational methods that model molecular interactions, predict binding affinities, and optimize lead compounds through algorithms such as molecular dynamics simulations and free energy perturbation calculations. These tools reduce wet-laboratory iterations by prioritizing candidate molecules with favorable pharmacokinetic profiles before synthesis. Machine learning and virtual screening segments lead technology adoption, with cloud-based and software-as-a-service deployment models capturing fastest growth as biotech startups avoid capital-intensive on-premises infrastructure. Contract research organizations represent a concentrated end-user segment where margin pools shift toward integrated consulting services that combine platform access with therapeutic domain expertise.
India's CDSCO and China's NMPA enforce evolving data integrity standards for computational models supporting regulatory submissions, while Japan's PMDA evaluates AI-generated toxicity predictions under revised pharmaceutical consultation frameworks. REACH-aligned substance registration requirements from Europe cascade into Asia-Pacific CRO workflows, compelling vendors to validate in silico predictions against experimental reference sets. Stakeholders must decide whether to build captive algorithm development teams or outsource to specialized platform providers as regulatory scrutiny of computational evidence intensifies.
Market Dynamics
Pharmaceutical sponsors across Asia-Pacific are compressing discovery timelines by embedding machine learning pipelines directly into medicinal chemistry workflows, shifting vendor selection criteria from software licensing toward integrated platform partnerships.
Growth Catalysts
- India's PLI scheme for active pharmaceutical ingredients:Domestic biotechnology parks are expanding computational chemistry infrastructure, reducing reliance on imported discovery tools.
- Cloud-based deployment models:Biotech startups across the region are avoiding capital-intensive on-premises infrastructure, accelerating SaaS adoption for molecular dynamics simulations.
- Shanghai and Suzhou biotech clusters:CROs in these cities integrate AI-driven target identification with high-throughput screening infrastructure, concentrating regional demand.
Market Restraints
- GPU compute cost volatility:Cloud-based training of large molecular models faces input cost swings from semiconductor supply constraints.
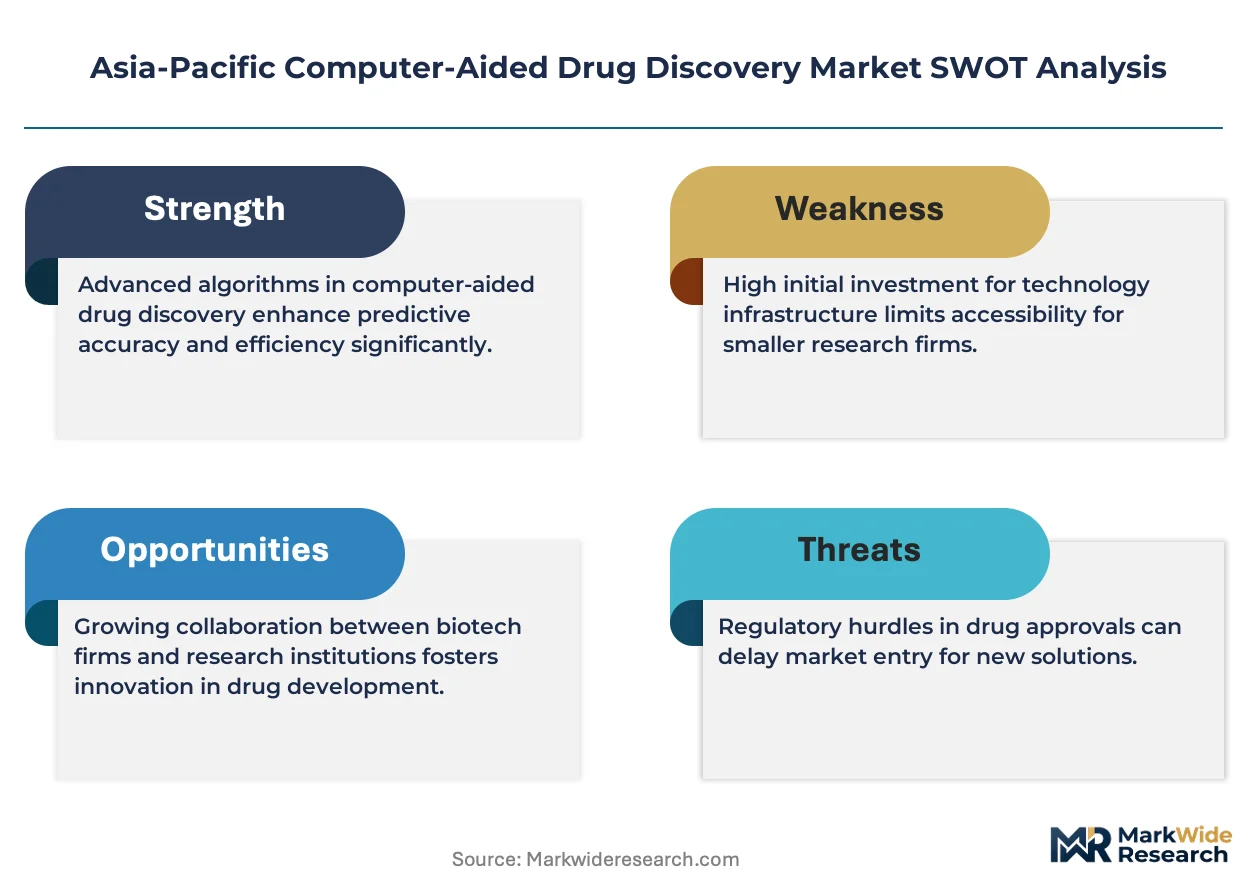
- Regulatory friction from CDSCO and NMPA:Evolving data integrity standards for computational models create submission uncertainty for sponsors.
- Technical limitation in free energy perturbation:Accuracy gaps in predicting protein-ligand binding for disordered targets persist across platforms.
Strategic Opportunities
- Underpenetrated Australian market:Sponsors in Sydney and Melbourne increasingly outsource target validation to Indian bioinformatics providers.
- Japan's PMDA revised consultation frameworks:New pathways for AI-generated toxicity predictions create first-mover advantages for validated platforms.
- Technology convergence of quantum computing and molecular simulation:Early adopters in Singapore and South Korea are piloting hybrid classical-quantum algorithms for conformational sampling.
Industry Challenges
- Computational chemist talent scarcity:Shortages in hybrid skill sets spanning medicinal chemistry and machine learning engineering constrain platform scaling.
- Legacy LIMS integration complexity:Wet-laboratory data systems require costly middleware development to feed structured inputs into AI models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Computer-Aided Drug Discovery Market |
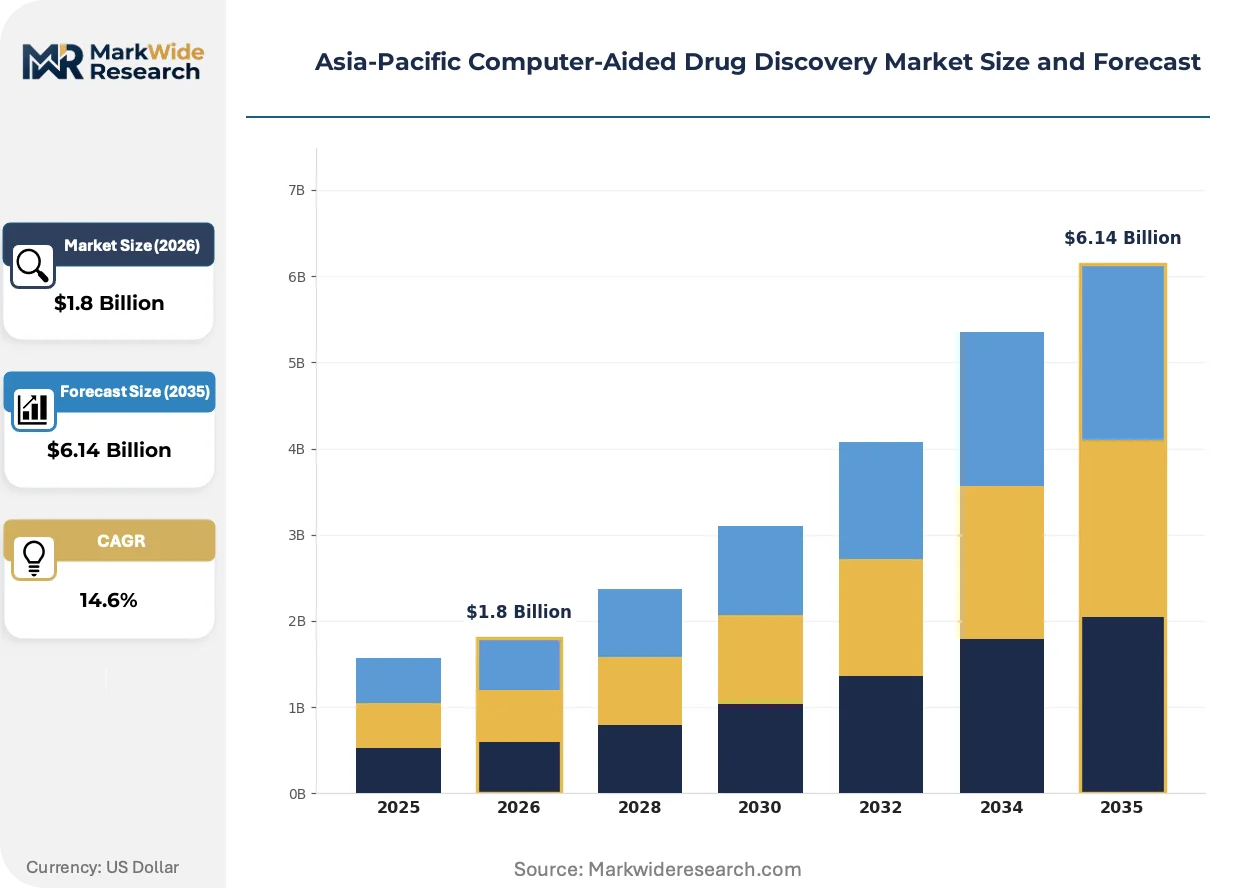
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Molecular Docking, Virtual Screening, Quantitative Structure-Activity Relationship Deployment: On-Premises, Cloud-Based, Hybrid, Software-as-a-Service End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Offering: Software Solutions, Consulting Services, Support Services, Training Services |
| Companies Covered | WuXi AppTec, Pharmaron, Syngene International, REPROCELL, ChemPartner, Sundia MediTech, Viva Biotech, GenScript, Daewoong Pharmaceutical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Computer-Aided Drug Discovery Market Evolving Landscape
Generative chemistry models are restructuring how lead compounds originate, compressing the traditional design-make-test cycle from months to weeks across Asia-Pacific R&D operations.
AlphaFold-derived structure predictions are rendering obsolete template-based homology modeling for target preparation. Mid-sized biotechs in South Korea and Australia adopt these pipelines within twelve-month implementation windows. The shift is compressing early-stage discovery contracts toward fixed-fee platform access rather than per-compound milestone payments.
China's NMPA has issued draft guidance on AI-assisted drug discovery data packages, requiring experimental validation of in silico predictions against reference compound sets. Domestic CROs are building captive wet-laboratory capacity to generate this bridging data. Japanese sponsors filing in both jurisdictions now demand dual-compliant documentation from their platform providers.
Platform unbundling is fragmenting buyer relationships as large pharmas separate software licensing from consulting engagements. Subscription-only vendors lose share to hybrid providers offering therapeutic domain expertise alongside computational tools. This pattern concentrates in China's contract research segment, where margin pools migrate toward integrated service bundles.
Asia-Pacific Computer-Aided Drug Discovery Market Segmentation
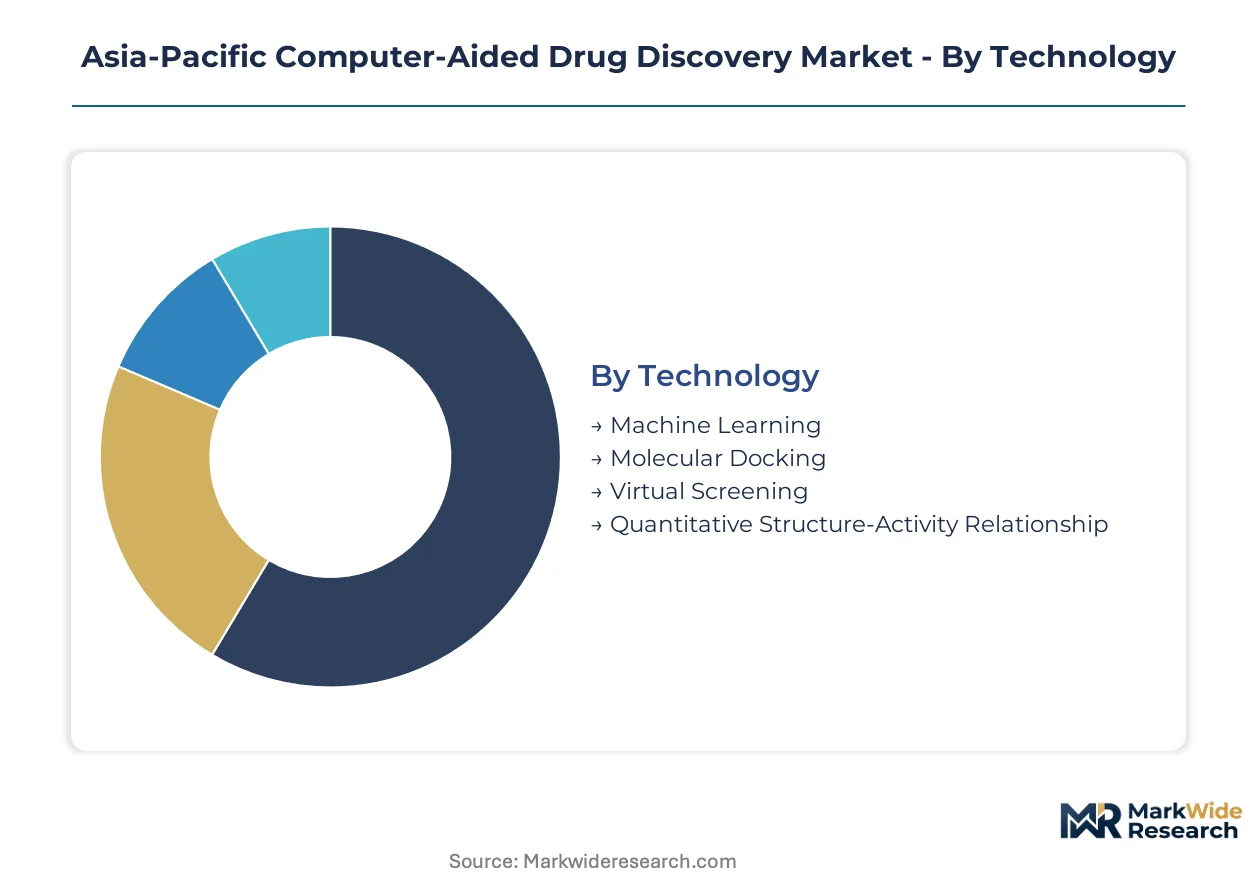
Technology and deployment choices in Asia-Pacific computer-aided drug discovery reflect divergent risk appetites across sponsor types. Biotech startups prioritize capital efficiency while large pharmas invest in captive infrastructure. End-user concentration in Chinese CROs and Indian research institutions creates asymmetric demand patterns across segment categories.
Technology:
Computational methods span predictive modeling, simulation, and statistical correlation techniques with varying data requirements and validation burdens.
- Machine Learning:Algorithms trained on molecular property datasets predict ADMET profiles and generate novel chemical scaffolds through generative architectures. Demand concentrates in Shanghai and Suzhou biotech clusters where CROs embed TensorFlow and PyTorch pipelines directly into medicinal chemistry workflows, constrained by CDSCO and NMPA scrutiny of training data provenance for regulatory submissions.
- Virtual Screening:Systematic evaluation of compound libraries against target structures prioritizes candidates for experimental validation. Bangalore-based providers extend these services to Australian sponsors seeking cost-efficient hit identification, though accuracy gaps persist for disordered protein targets.
- Molecular Docking:Geometry-based prediction of binding poses requires less computational overhead than physics-based methods.
- Quantitative Structure-Activity Relationship:Statistical models correlate molecular descriptors with biological activity for lead optimization.
The dominant share belongs to Machine Learning, while Virtual Screening is closing the gap fastest.
Deployment:
Cost tier and capital intensity shape infrastructure decisions across the sponsor base.
- Cloud-Based:Scalable compute resources eliminate upfront GPU cluster investments. Biotech startups across Singapore and South Korea avoid capital-intensive on-premises infrastructure, though semiconductor supply constraints create input cost volatility for large model training.
- Software-as-a-Service:Subscription access to curated algorithm suites reduces maintenance overhead. Japanese mid-cap pharmas favor SaaS for toxicity prediction modules under PMDA's revised consultation frameworks.
- On-Premises:Captive infrastructure serves sponsors with stringent data sovereignty requirements.
- Hybrid:Mixed architectures balance sensitive target data on local servers with burst compute in public clouds.
Cloud-Based deployment holds the largest installed base, yet SaaS is expanding most quickly among new market entrants.
End User:
Customer type determines contract structure and platform integration depth.
- Contract Research Organizations:Integrated service providers bundle computational tools with wet-laboratory validation. WuXi AppTec and Pharmaron anchor regional capacity through platform partnerships that shift margin pools toward consulting engagements.
- Pharmaceutical Companies:Large sponsors build captive algorithm teams or license enterprise platforms for target-to-lead programs.
- Biotechnology Firms:Venture-backed startups drive SaaS adoption through limited capital reserves.
- Research Institutions:Academic centers in India leverage PLI scheme infrastructure for open-source method development.
CROs command the deepest platform penetration, while Biotechnology Firms are gaining share fastest as venture funding concentrates in precision medicine.
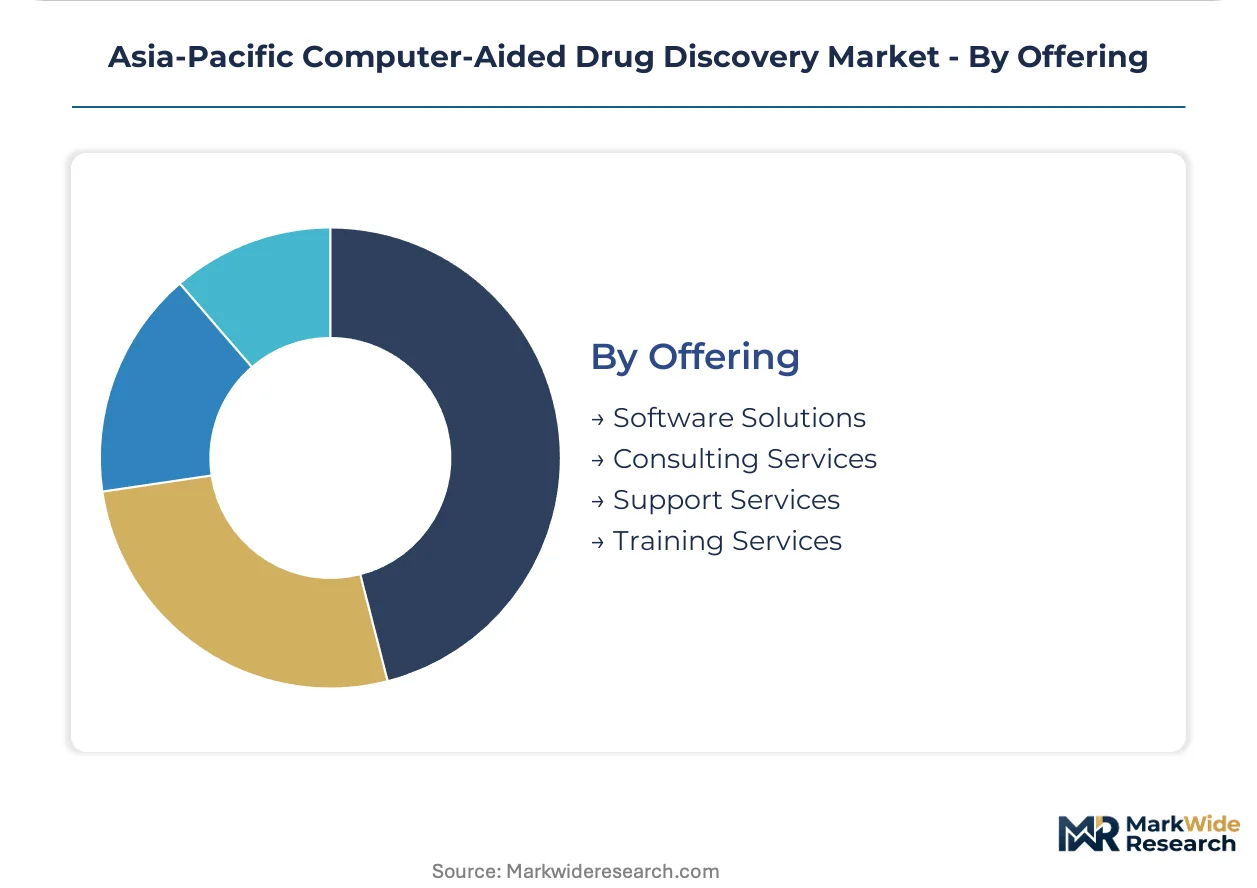
Offering:
Margin structure and customer stickiness vary across product and service bundles.
- Software Solutions:Licensed platforms for molecular dynamics and free energy perturbation calculations. Vendors face unbundling pressure as large pharmas separate tool access from therapeutic expertise.
- Consulting Services:Domain specialists embed computational workflows into sponsor organizations. Chinese CROs capture migrating margin pools through integrated bundles combining platform access with medicinal chemistry judgment.
- Support Services:Technical maintenance and validation assistance for regulatory submissions.
- Training Services:Skill transfer programs addressing computational chemist scarcity across the region.
Software Solutions retain the revenue majority, though Consulting Services are climbing the fastest as buyers prioritize outcome-linked partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computational chemistry infrastructure concentrates in coastal biotech clusters across the Asia-Pacific, with sovereign capability-building programs reshaping vendor selection criteria. CDSCO and NMPA data-integrity standards now govern cross-border platform procurement.
China
Shanghai and Suzhou anchor regional capacity for structure-based drug design through integrated CRO platforms serving multinational sponsors. NMPA draft guidance on AI-assisted discovery data packages requires experimental validation of in silico predictions, compelling domestic providers to build captive wet-laboratory bridging capacity. WuXi AppTec and Pharmaron embed specialized artificial intelligence teams within medicinal chemistry divisions across these cities.
India
Bangalore-based bioinformatics providers extend cost-efficient target validation services to Japanese and Australian sponsors seeking outsourced computational workflows. CDSCO enforcement of evolving data integrity standards for computational models supporting regulatory submissions creates compliance complexity for platform exporters. Domestic biotechnology parks under the PLI scheme for active pharmaceutical ingredients are expanding captive computational chemistry infrastructure.
Japan
Mid-cap pharmaceutical sponsors in Tokyo and Osaka favor SaaS deployment for toxicity prediction modules under PMDA's revised consultation frameworks for AI-generated safety assessments. Regulatory pathways for validated in silico platforms create first-mover advantages for vendors with dual NMPA-PMDA compliance documentation. Sponsors filing in both jurisdictions now demand integrated service bundles combining software access with therapeutic domain expertise.
South Korea
Seoul-based biotech startups pilot hybrid classical-quantum algorithms for conformational sampling, positioning early adopters at the convergence of quantum computing and molecular simulation. MFDS alignment with international standards for computational model validation supports platform export to adjacent markets. Venture-backed firms drive cloud-based adoption to avoid capital-intensive GPU cluster investments amid semiconductor supply volatility.
Australia
Sydney and Melbourne sponsors increasingly outsource target validation to Indian bioinformatics providers, leveraging time-zone advantages and cost differentials for late-stage discovery programs. TGA recognition of overseas computational validation data streamlines regulatory pathways for sponsors using Asia-Pacific CRO platforms. Underpenetrated domestic capacity creates structural reliance on imported computational services.
Asia-Pacific Computer-Aided Drug Discovery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying algorithm modules and curated molecular databases. The vendor base stratifies between full-stack discovery providers bundling computational tools with wet-laboratory validation, and pure-play software vendors facing unbundling pressure from large pharmaceutical sponsors. Three archetypes dominate: integrated CROs capturing consulting-heavy contracts, captive algorithm teams within large pharmas, and SaaS-native startups serving capital-constrained biotechs. Competitive moves concentrate on strategic partnerships anchoring platform access to therapeutic expertise, and geographic expansion into underpenetrated Australian and Southeast Asian markets.
Among China-based integrated service providers, WuXi AppTec and Pharmaron exemplify the platform-anchored archetype, embedding computational workflows within broader discovery service bundles. Syngene International occupies a position representing Indian bioinformatics specialists extending regional reach to Japanese and Australian sponsors. These three companies illustrate how margin pools migrate toward outcome-linked partnerships combining software access with medicinal chemistry judgment, particularly under tightening CDSCO and NMPA regulatory scrutiny.
| Leading Market Players |
|---|
| WuXi AppTec |
| Pharmaron |
| Syngene International |
| REPROCELL |
| ChemPartner |
| Sundia MediTech |
| Viva Biotech |
| GenScript |
| Daewoong Pharmaceutical |
| Others |
Value Network & Pricing Analysis
GPU cluster undercapacity in Shanghai and Suzhou biotech corridors is compressing vendor margins while amplifying pricing power for cloud compute providers serving molecular dynamics workloads. Sponsors face escalating subscription costs for AI-driven discovery platforms as semiconductor supply constraints persist across the region.
Pricing Analysis
NMPA draft guidance on AI-assisted discovery data packages dictates the pricing tier structure for computational validation services, separating premium platforms with captive wet-laboratory bridging capacity from standard SaaS offerings lacking experimental backup. Price differentiation centers on regulatory compliance grade and therapeutic domain expertise depth, with CDSCO-aligned documentation commanding substantial premiums. Pricing pressure stems from GPU rental cost volatility, eroding margins for cloud-native vendors. Biotech startups exhibit highest price sensitivity, while multinational pharmas prioritize outcome-linked partnerships over unit cost.
Supply Chain Analysis
WuXi AppTec and Pharmaron hold concentrated contract-research capacity across China's eastern seaboard, anchoring regional supply for integrated computational-wet laboratory workflows. Geographic supply concentration centers on China, India, and South Korea, with Bangalore-based bioinformatics providers extending reach to Australian sponsors. Raw material dependencies span NVIDIA GPU clusters, specialized molecular databases, and cloud storage infrastructure. Supply chain risk rests on single-source vulnerability for advanced semiconductor components. Distribution runs through direct platform partnerships with CROs and enterprise licensing to large pharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific computer-aided drug discovery sits in early-cycle expansion as generative chemistry models displace template-based homology modeling across mid-sized biotech R&D operations. Cloud-based deployment penetration remains below saturation, creating runway for platform-native vendors.
For Market Incumbents: Insulate consulting-heavy revenue streams by embedding specialized AI teams within medicinal chemistry divisions before pure-play software vendors achieve regulatory validation parity. Build captive wet-laboratory bridging capacity to meet NMPA experimental validation requirements. Lock in long-term GPU supply agreements to neutralize semiconductor cost volatility threatening SaaS margins. For New Entrants and Emerging Players: Australian sponsor outsourcing of target validation to Indian bioinformatics providers represents the most penetrable white-space corridor, with Sydney and Melbourne biotechs seeking cost-efficient late-stage discovery support. Japan's PMDA revised consultation frameworks for AI-generated toxicity predictions create regulatory-first-mover opportunities for validated platforms. Pursue SaaS-native positioning with toxicity prediction modules to capture mid-cap pharma procurement cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid providers bundling platform access with therapeutic domain expertise, as unbundling pressure from large pharmas fragments pure-play software relationships. Long-term viability favors integrated CROs with dual NMPA-PMDA compliance documentation and established wet-laboratory anchoring. Monitor CDSCO enforcement intensity for computational model data integrity standards as inflection indicator for platform exporter compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Investment | NMPA-aligned wet-laboratory bridging capacity secures premium pricing tier access for Chinese CROs. |
| Platform Integration Partnership | TensorFlow and PyTorch pipeline embedding within medicinal chemistry workflows locks in sponsor switching costs. |
| Geographic Expansion | Bangalore-to-Australia bioinformatics service extension captures underpenetrated sponsor outsourcing demand. |
| Quantum Computing Pilot | Hybrid classical-quantum algorithms for conformational sampling position early adopters in Seoul for next-generation capability. |
| Backward Integration | Captive GPU cluster investment insulates margins from cloud compute cost volatility affecting SaaS-native competitors. |
Research Methodology
The analysis maps machine learning platforms, virtual screening services, molecular docking tools, and quantum simulation pilots, each validated through computational chemists, regulatory affairs leads at CDSCO and NMPA, CRO procurement officers, and biotech R&D directors. Primary interviews with platform engineers and medicinal chemistry division heads combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hyperscaler capex disclosures. Bottom-up sponsor spend analysis triangulated against top-down market sizing across deployment models and end-user segments.
Assumptions held fixed include regulatory pathway stability for AI-generated toxicity predictions and sustained venture funding concentration in precision medicine biotechs. Variables modeled encompass technology adoption curves, cloud infrastructure cost trajectories, and computational chemist talent supply elasticity. Segmentation dimensions span deployment architecture, end-user type, and regional regulatory cluster complexity. CAGRs derived from sponsor pipeline expansion rates and platform subscription renewal patterns, with molecular dynamics simulation demand and generative chemistry model integration serving as primary forecast inputs across the projection horizon.
Practitioners should monitor GPU supply chain normalization, CDSCO data integrity enforcement intensity, and PMDA consultation framework finalization for early signals requiring forecast revision. Quarterly review of cloud compute pricing indices, regulatory submission rejection rates for AI-supported packages, and CRO platform partnership announcement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Malaria Vaccine Market
Medical Research
Human Osteoblasts Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
US Academic Medical Centers Market
Medical Research
North America Biobanks Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Global Mice Model Market
Medical Research
Epigenetics Market
Medical Research
PDX Models Market
Medical Research
Epigenomics Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Europe AMH Market
Medical Research
Metabolomics Market
Medical Research
Organoids and Spheroids Market
Medical Research
Cancer Mouse Models Market