
 United Kingdom Mammography Market | 2026-2036
United Kingdom Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Mammography Market Analytics
Digital detector materials, particularly selenium-based direct conversion panels, is realigning unit economics away from legacy amorphous silicon indirect architectures. GE Healthcare leverages its in-house selenium deposition capacity to anchor premium positioning across NHS procurement frameworks. Siemens Healthineers sustains competitive intensity through proprietary photon-counting detector R&D pipelines. Hologic dominates the tomosynthesis segment with integrated 3D imaging workflows that reduce recall rates in screening populations.
Mammography encompasses X-ray breast imaging systems operating at 25-35 kVp tube voltage with molybdenum or rhodium target materials, designed to detect microcalcifications and soft-tissue masses through differential attenuation contrast. The primary commercial purpose centres on population-level breast cancer screening and diagnostic workup of suspicious lesions. Digital mammography occupies the mature revenue base while tomosynthesis captures the fastest expansion trajectory as NHS England mandates 3D-capable replacement cycles. Portable mammography units represent a concentrated margin pool serving mobile screening programmes in rural Scotland and Northern Ireland where fixed infrastructure remains sparse.
The Medicines and Healthcare products Regulatory Agency enforces Medical Devices Regulation 2017/745 conformity requirements for mammography system market access, while NHS England's Quality Assurance Reference Centre sets technical performance standards that shape procurement specifications. The UK National Screening Committee's protocol updates directly determine replacement demand cycles and technology upgrade obligations. Stakeholders must monitor MHRA post-market surveillance data disclosure trends and NHS capital allocation shifts between diagnostic hub consolidation versus distributed imaging network maintenance.
Market Dynamics
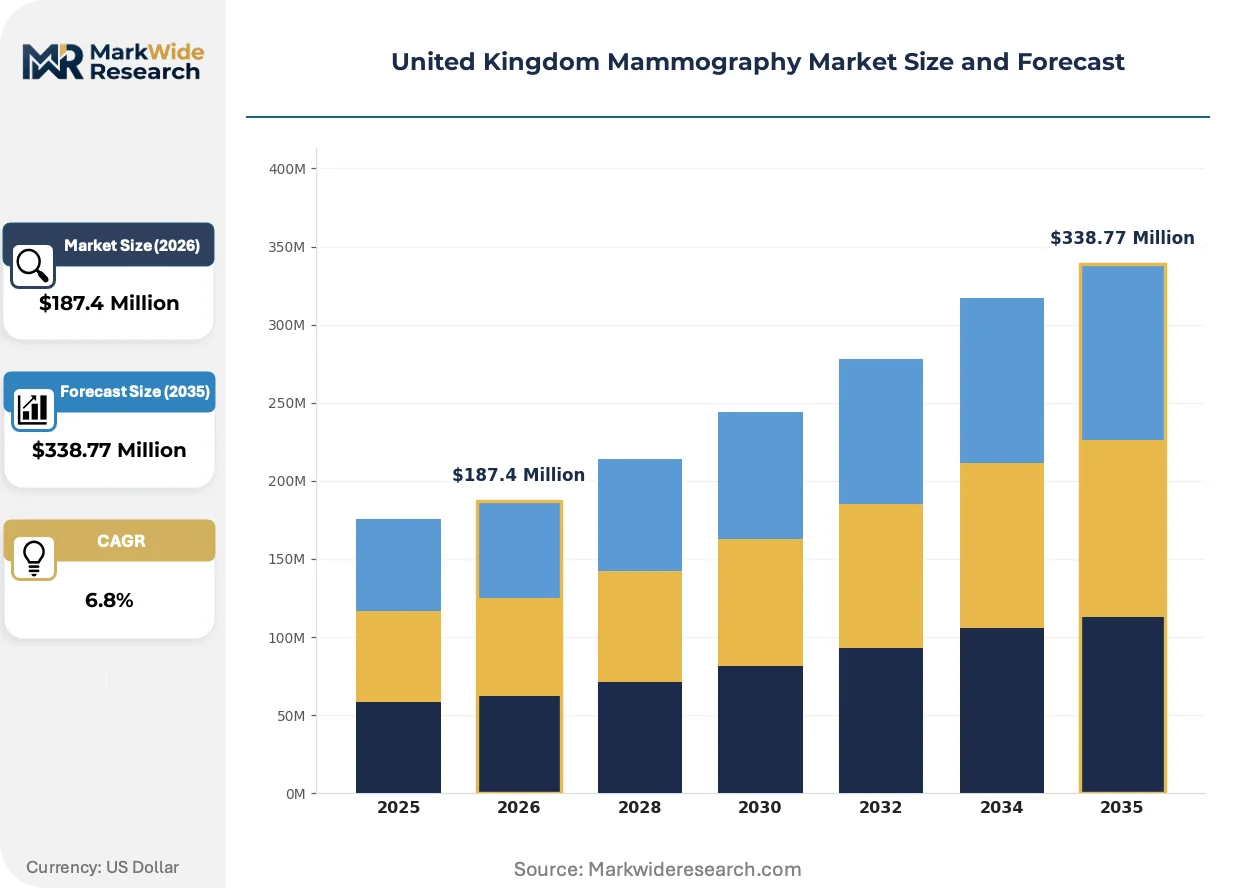
NHS England's mandate for 3D-capable replacement cycles is compressing analogue-to-digital upgrade timelines across regional imaging networks, while MHRA streamlining of tomosynthesis approvals accelerates procurement velocity for consolidated screening hubs.
Growth Catalysts
- Digital detector material advances:Selenium-based direct conversion panels improve dose efficiency and image quality, prompting NHS trusts to prioritize these architectures in capital planning cycles.
- NHS breast screening programme expansion:England's regional hub consolidation creates concentrated demand for high-throughput digital systems capable of serving expanded catchment populations.
- MHRA Medical Devices Regulation 2017/745 alignment:Streamlined conformity pathways reduce time-to-market for next-generation tomosynthesis platforms, incentivizing manufacturers to prioritize UK regulatory submissions.
Market Restraints
- Selenium supply concentration:Deposition-grade selenium sourcing concentrates among limited specialty chemical suppliers, exposing detector manufacturers to input cost volatility and supply security risks.
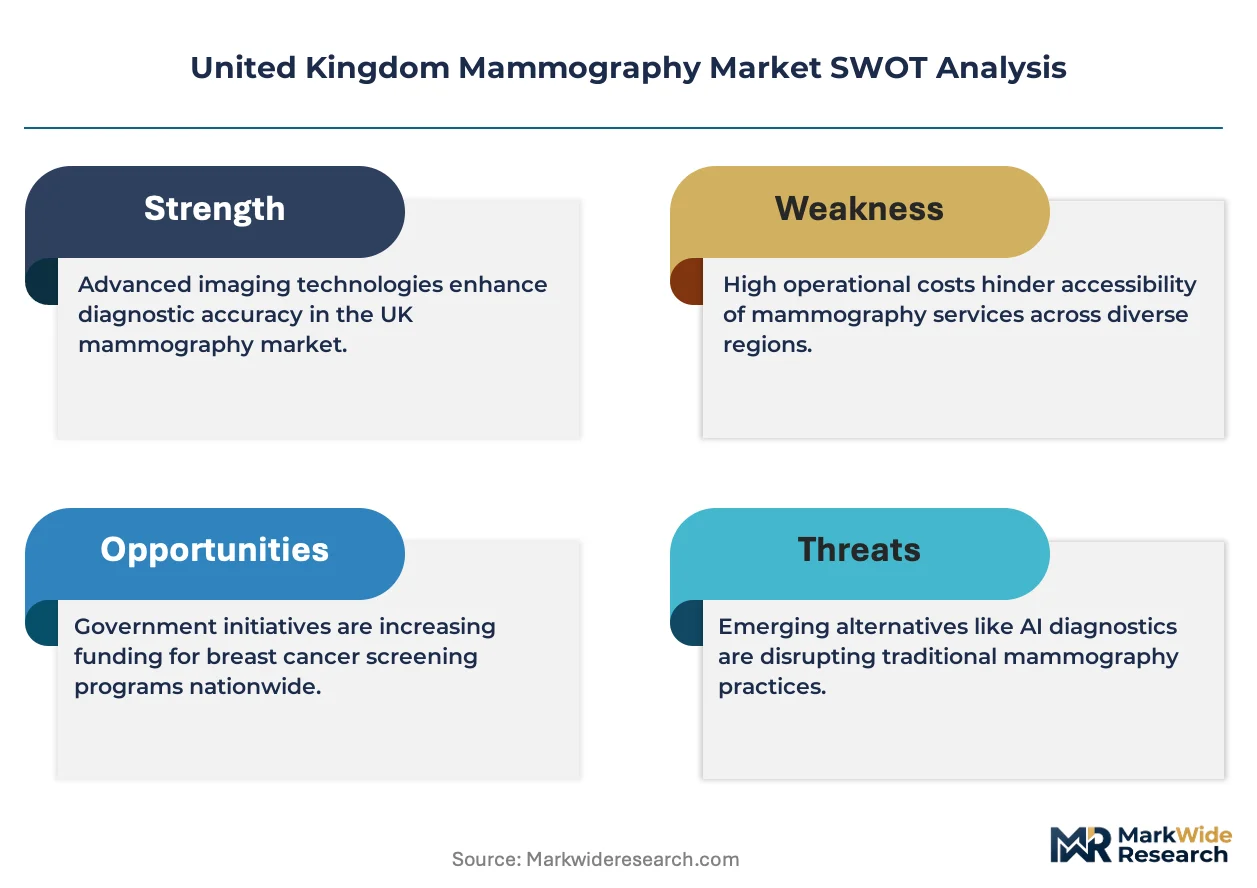
- Capital intensity of hub infrastructure:Fixed-site digital mammography suites require substantial building modification and shielding investment, constraining deployment pace in estate-constrained NHS trusts.
- Rural geography limitations:Sparse population density across Northern Scotland and Welsh valleys undermines the economic case for fixed-unit installation, perpetuating reliance on ageing analogue fleets.
Strategic Opportunities
- Mobile screening programme penetration:Portable digital units address coverage gaps in rural Scotland and Northern Ireland where fixed infrastructure remains economically unviable.
- Photon-counting detector convergence:Integration of photon-counting architectures with tomosynthesis workflows promises dose reduction alongside enhanced spectral imaging capabilities.
- NHS capital allocation prioritization:Quality Assurance Reference Centre technical performance standard updates create procurement preference for integrated 3D-capable systems.
Industry Challenges
- Specialized radiographer workforce scarcity:NHS trusts face recruitment bottlenecks for tomosynthesis-qualified screening personnel, constraining effective utilization of installed 3D capacity.
- Legacy system integration complexity:PACS interoperability requirements impose technical burden on trusts attempting to incorporate new digital units alongside existing radiology infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Mammography Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography, Analog Mammography, Tomosynthesis, Portable Mammography End User: Hospitals, Diagnostic Clinics, Research Institutions, Imaging Centers Technology: Cationic Imaging, Image Processing, Computer-Aided Detection, 3D Imaging Application: Breast Cancer Screening, Diagnostic Imaging, Patient Monitoring, Clinical Research |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Hologic Inc, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Koninklijke Philips NV, Planmed Oy, Carestream Health Inc, Metaltronica SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Mammography Market Evolving Landscape
Detector architecture evolution and procurement model restructuring are redefining competitive advantage in UK breast imaging, with regulatory alignment and workforce constraints shaping implementation velocity.
Photon-counting detector technology is decentralizing dose-performance tradeoffs in screening workflows. NHS trusts in Greater Manchester and London are piloting these architectures for high-volume programmes. The shift is compressing the performance gap between premium fixed installations and mid-tier configurations.
MHRA post-market surveillance data disclosure requirements are intensifying transparency obligations for device manufacturers. Suppliers must now maintain continuous clinical performance documentation across installed bases. This regulatory pressure disproportionately affects smaller vendors lacking dedicated UK regulatory affairs functions.
Consolidated hub procurement is fragmenting previously centralized NHS England acquisition patterns. Regional imaging networks now negotiate directly with manufacturers for fleet replacement, displacing national framework dominance. This behavioral shift is most pronounced in the North West and West Midlands where devolved commissioning authority has accelerated decision cycles.
United Kingdom Mammography Market Segmentation
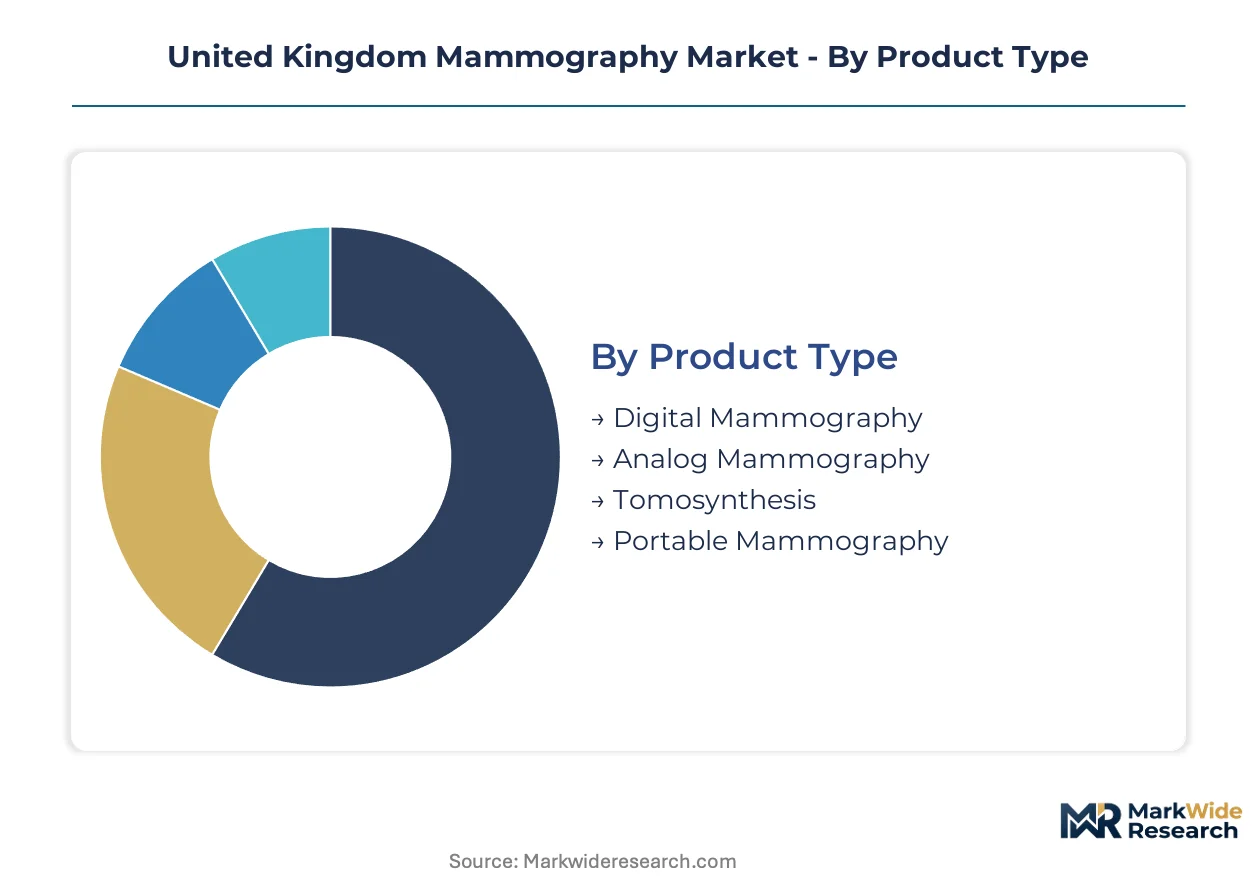
Technology replacement cycles and NHS procurement frameworks reshape demand distribution across product architectures. End-user consolidation and application-specific workflows further fragment the addressable market into distinct investment pools.
Product Type:
Upgrade timelines from analogue to digital architectures concentrate capital deployment in high-throughput screening hubs.
- Digital Mammography:Full-field digital systems employing amorphous silicon or selenium-based detectors capture the mature revenue base across NHS England regional networks. Procurement concentrates in Greater Manchester and London where consolidated screening hubs replace dispersed legacy units.
- Tomosynthesis:Three-dimensional breast tomosynthesis systems integrate multiple low-dose projections into slice-resolved volumetric datasets. NHS England mandates 3D-capable replacement cycles, accelerating demand in high-volume screening populations.
- Analog Mammography:Screen-film systems persist in estate-constrained trusts and rural geographies where capital modification costs delay digital transition.
- Portable Mammography:Mobile digital units serve screening programmes in rural Scotland and Northern Ireland where fixed infrastructure remains economically unviable.
Digital Mammography sits at the top of the volume ranking, with Tomosynthesis climbing the fastest.
End User:
Customer-type concentration determines equipment specification priorities and service contract structures.
- Hospitals:Acute NHS trusts operate integrated diagnostic suites requiring PACS interoperability and multi-modality workflow integration. Capital allocation prioritizes high-throughput systems for symptomatic breast clinics.
- Imaging Centers:Independent diagnostic facilities concentrate tomosynthesis adoption for competitive differentiation in private screening markets. Procurement emphasizes throughput metrics and recall rate performance.
- Diagnostic Clinics:Community-based breast assessment units balance equipment utilization against catchment population density.
- Research Institutions:Academic medical centers deploy specialized configurations for clinical trial imaging and AI validation studies.
Hospitals command the largest installed base, though Imaging Centers demonstrate the steepest expansion trajectory.
Technology:
Detector architecture evolution fragments competitive positioning between dose efficiency and image quality tradeoffs.
- 3D Imaging:Volumetric acquisition protocols reconstruct tomographic slices from multiple angular projections. NHS Quality Assurance Reference Centre standards now incorporate 3D performance benchmarks into procurement specifications.
- Computer-Aided Detection:AI-enhanced image analysis algorithms flag suspicious regions for radiographer review. Integration with tomosynthesis workflows reduces interpretation time in high-volume screening programmes.
- Image Processing:Proprietary reconstruction algorithms differentiate vendor performance in dense breast tissue visualization.
- Cationic Imaging:Specialized contrast-enhanced protocols support diagnostic workup of indeterminate lesions.
3D Imaging leads technology investment, with Computer-Aided Detection gaining share fastest.
Application:
Workflow purpose determines equipment configuration, staffing requirements, and reimbursement pathways.
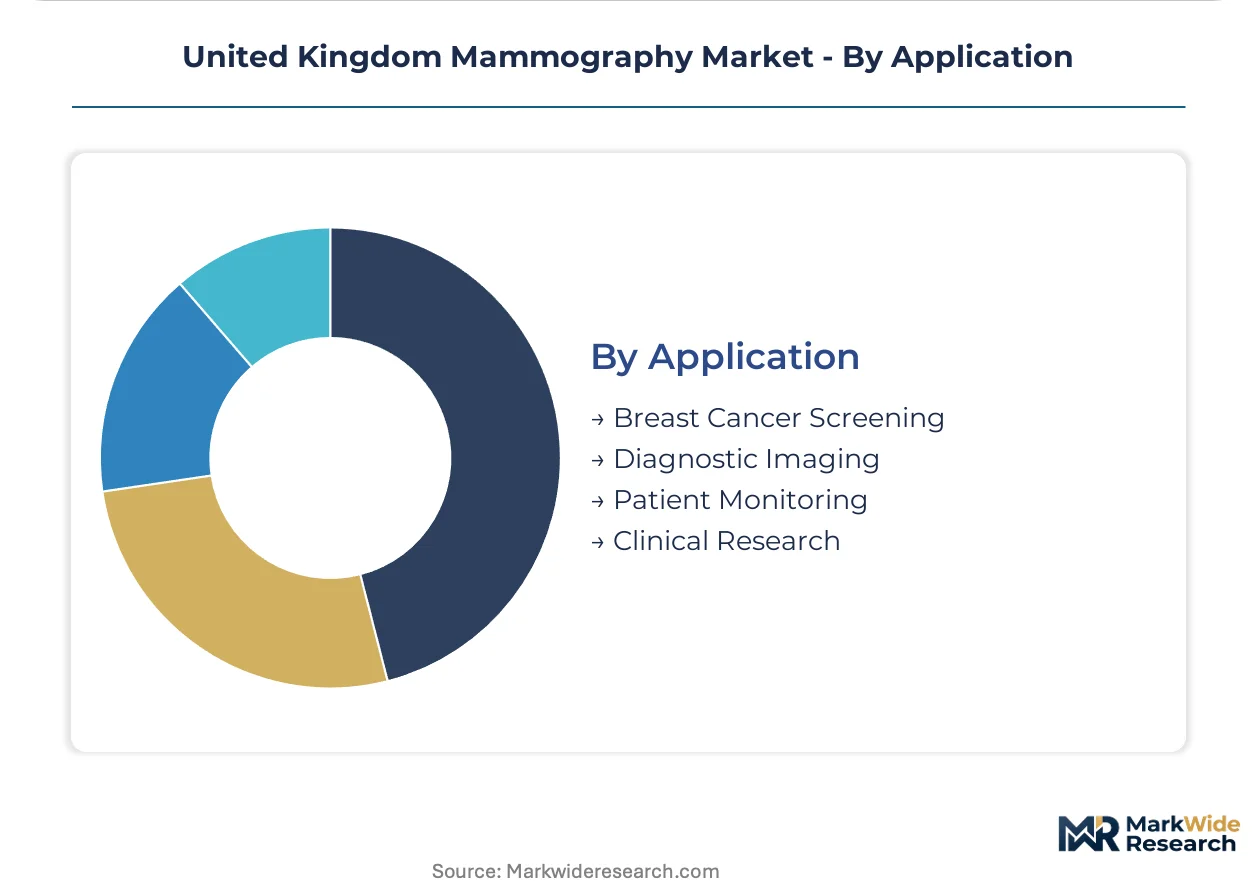
- Breast Cancer Screening:Population-level asymptomatic screening programmes operate under NHS England protocol mandates. Quality assurance standards dictate technical specifications for incident and prevalent round imaging.
- Diagnostic Imaging:Symptomatic and assessment workflows require higher-resolution acquisition modes and biopsy guidance compatibility. Demand concentrates in tertiary referral centers.
- Patient Monitoring:Surveillance imaging for high-risk cohorts and post-treatment follow-up generates recurring volume.
- Clinical Research:Trial-specific imaging protocols require equipment flexibility and data export capabilities for central review.
Breast Cancer Screening dominates procedure volume, while Diagnostic Imaging expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Manchester and London anchor procurement concentration across England's consolidated screening networks. NHS England's hub consolidation strategy redirects capital toward high-throughput installations in these metropolitan clusters.
Greater Manchester
Regional imaging network consolidation drives replacement demand for 3D-capable systems serving expanded catchment populations. The NHS Quality Assurance Reference Centre mandates technical performance standards that shape procurement specifications. Manchester's screening hub replacement program is displacing dispersed analogue units with centralized digital infrastructure.
London and Southeast
Acute NHS trusts and independent diagnostic facilities concentrate tomosynthesis adoption for competitive differentiation. MHRA Medical Devices Regulation 2017/745 alignment streamlines conformity pathways for next-generation platforms. The capital's tertiary referral centers pilot photon-counting detector architectures for high-volume screening workflows.
Midlands
Estate-constrained trusts delay digital transition due to building modification and shielding investment requirements. NHS England capital allocation prioritizes hub consolidation over distributed network maintenance. Birmingham's regional imaging network negotiates directly with manufacturers for fleet replacement cycles.
Scotland
Sparse population density across Northern Scotland perpetuates reliance on mobile screening programmes. Portable digital units address coverage gaps where fixed infrastructure remains economically unviable. NHS Scotland's mobile fleet modernization targets rural Highlands and Islands coverage.
Northern Ireland
Rural geography limitations constrain fixed-unit installation economics across dispersed communities. Mobile digital mammography serves screening programmes in estate-constrained geographies. Belfast's regional hub coordinates fleet deployment across the province's distributed catchment areas.
United Kingdom Mammography Market Competitive Landscape
Global majors compete with regional champions across detector architecture and procurement framework positioning. Siemens Healthineers and GE Healthcare anchor premium-tier supply through proprietary detector R&D pipelines. The vendor base stratifies into three archetypes: integrated imaging conglomerates with captive detector production, specialized breast imaging pure-plays, and diversified medical technology portfolios seeking share expansion. Consolidated hub procurement fragments previously centralized NHS England acquisition patterns, while MHRA regulatory alignment accelerates approval velocity for next-generation platforms.
Among integrated imaging conglomerates, Siemens Healthineers AG and GE Healthcare occupy positions defined by in-house detector manufacturing capabilities and established NHS procurement framework relationships. Hologic Inc exemplifies the specialized breast imaging pure-play archetype, anchoring competitive positioning through integrated 3D imaging workflows. These three companies represent distinct strategic postures: detector material backward integration, proprietary photon-counting R&D pipelines, and tomosynthesis segment dominance respectively.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Hologic Inc |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Planmed Oy |
| Carestream Health Inc |
| Metaltronica SpA |
| Others |
Value Network & Pricing Analysis
NHS England's mandated 3D-capable replacement cycles are compressing procurement timelines and forcing suppliers to absorb detector material cost volatility into long-term framework pricing. Selenium deposition-grade sourcing constraints and regional hub consolidation are reshaping how manufacturers structure capital equipment contracts and service bundling.
Pricing Analysis
Input-cost pass-through from selenium deposition-grade supply tightness is compressing margins on mid-tier digital systems while premium photon-counting architectures command pricing power through differentiation. Three-tier pricing structure across premium, standard, and economy levels reflects detector material backward integration depth and NHS Quality Assurance Reference Centre certification tiers. Cost compression in standard-tier configurations is intensifying because amorphous silicon indirect architectures face obsolescence pressure from NHS technical performance standard updates. Imaging centers demonstrate highest price sensitivity due to competitive private screening markets, while consolidated NHS hubs prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Belgium anchor hub-and-spoke patterns for detector module fulfillment across UK screening networks. Manufacturing concentrates in Germany, Japan, and the United States for precision detector deposition equipment and X-ray tube assemblies. Raw material dependencies span deposition-grade selenium from specialty chemical suppliers in Belgium and Germany, molybdenum target materials from Chilean mining operations, and rare-earth phosphors from Chinese processors. Single-source vulnerability in selenium purification capacity exposes detector manufacturers to input cost spikes. Distribution runs through manufacturer-direct field service organizations rather than third-party logistics, reflecting installation complexity and regulatory traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK mammography market represents a late-cycle quality story where NHS technical specification upgrades are shifting procurement preference toward integrated 3D-capable systems with enhanced dose efficiency credentials.
For Market Incumbents: Deepen captive selenium deposition capacity to insulate margin structures from specialty chemical supply volatility and secure preferential NHS framework positioning. Accelerate photon-counting detector field validation studies to preempt regulatory preference shifts. Consolidate service contract penetration across Greater Manchester and London hub consolidations to lock out emerging competitors from high-volume installed bases. For New Entrants and Emerging Players: Enter via portable digital mammography segments serving NHS Scotland mobile screening programmes and Northern Ireland rural coverage gaps where fixed-unit economics remain prohibitive. Target estate-constrained Midlands trusts with lease-based financing structures that circumvent capital budget limitations. Pursue photon-counting detector partnerships with academic medical centers to generate clinical evidence for subsequent NHS procurement qualification. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized breast imaging pure-plays possessing integrated 3D workflow software and established NHS Quality Assurance Reference Centre relationships. Long-term viability hinges on regulatory navigation capabilities and detector architecture transition timing rather than installed base scale alone. Monitor MHRA post-market surveillance disclosure patterns as inflection indicator for compliance cost escalation that favors larger manufacturers with dedicated UK regulatory affairs functions.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector CE Marking Pathway | MHRA streamlined conformity assessment accelerates next-generation platform approvals ahead of NHS replacement cycles. |
| NHS Regional Hub Partnership | Direct negotiation authority with Greater Manchester and West Midlands networks displaces national framework dominance. |
| Mobile Screening Fleet Modernization | NHS Scotland portable unit procurement addresses Northern Highlands coverage gaps with lower infrastructure investment. |
| Selenium Supply Security Agreement | Long-term deposition-grade contracts with Belgian and German specialty chemical suppliers mitigate input cost volatility. |
| Tomosynthesis-Qualified Radiographer Training | Workforce development partnerships with NHS trusts alleviate screening personnel bottlenecks constraining 3D capacity utilization. |
Research Methodology
Multiple input streams — structured interviews with NHS procurement leads and biomedical engineering directors, hospital purchasing committee deliberation records, and MHRA device registration databases — were reconciled against secondary validation from NHS England capital allocation disclosures, GPO contract repositories, and medical device trade flow data. Bottom-up equipment deployment tracking across England's regional imaging networks was cross-referenced with top-down manufacturer revenue segmentation to triangulate market sizing.
Historical procurement velocity patterns were cross-referenced against expert panel input from regulatory affairs specialists and screening programme directors to construct analytical framework projections across the analysis window. Segmentation dimensions modeled include product architecture, end-user concentration, detector technology tier, and application workflow purpose. CAGRs were derived from fitted trend extrapolation adjusted for NHS replacement cycle timing and MHRA approval velocity assumptions.
Inputs from NHS England Quality Assurance Reference Centre technical bulletins and MHRA post-market surveillance disclosures were available through the study window; gaps in real-time regional trust capital commitment data introduce uncertainty bands around hub consolidation timing assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Global Veterinary Radiography System Market