
 Global Contrast-Enhanced Ultrasound Market | 2026-2036
Global Contrast-Enhanced Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contrast-Enhanced Ultrasound Market Foresight
CE marking under the EU Medical Device Regulation is reorganizing competitive access for contrast agent manufacturers seeking European commercialization. Bracco Imaging leverages its vertically integrated microbubble manufacturing to sustain supply security across multiple geographies. Siemens Healthineers anchors its position through proprietary harmonic imaging algorithms that optimize contrast signal detection. Lantheus Holdings differentiates via its specialized focus on cardiovascular ultrasound agents with established clinical validation.
Contrast-enhanced ultrasound employs gas-filled microbubbles, typically 1-10 micrometers in diameter with a phospholipid or protein shell, that oscillate within an acoustic field to amplify backscatter signals from blood pool and tissue perfusion. The technique enables real-time visualization of microvascular flow without ionizing radiation or nephrotoxic contrast media. Ultrasound contrast agents command the largest value share within product type segmentation due to recurring consumption and specialized manufacturing complexity. Cardiology applications lead clinical utilization volumes, while oncology represents the fastest-expanding segment as tumor perfusion monitoring gains protocol adoption in liver and renal malignancy staging.
The FDA maintains stringent oversight of ultrasound contrast agent safety profiles through post-market adverse event surveillance and label updates. EMA's MDR framework imposes enhanced clinical evidence requirements for Class III device classification of microbubble formulations. Japan's PMDA operates accelerated review pathways for innovative diagnostic agents that demonstrate superiority over existing modalities. Stakeholders must monitor evolving harmonization between regional pharmacovigilance databases and imaging protocol standardization initiatives to anticipate compliance burdens and market access timing.
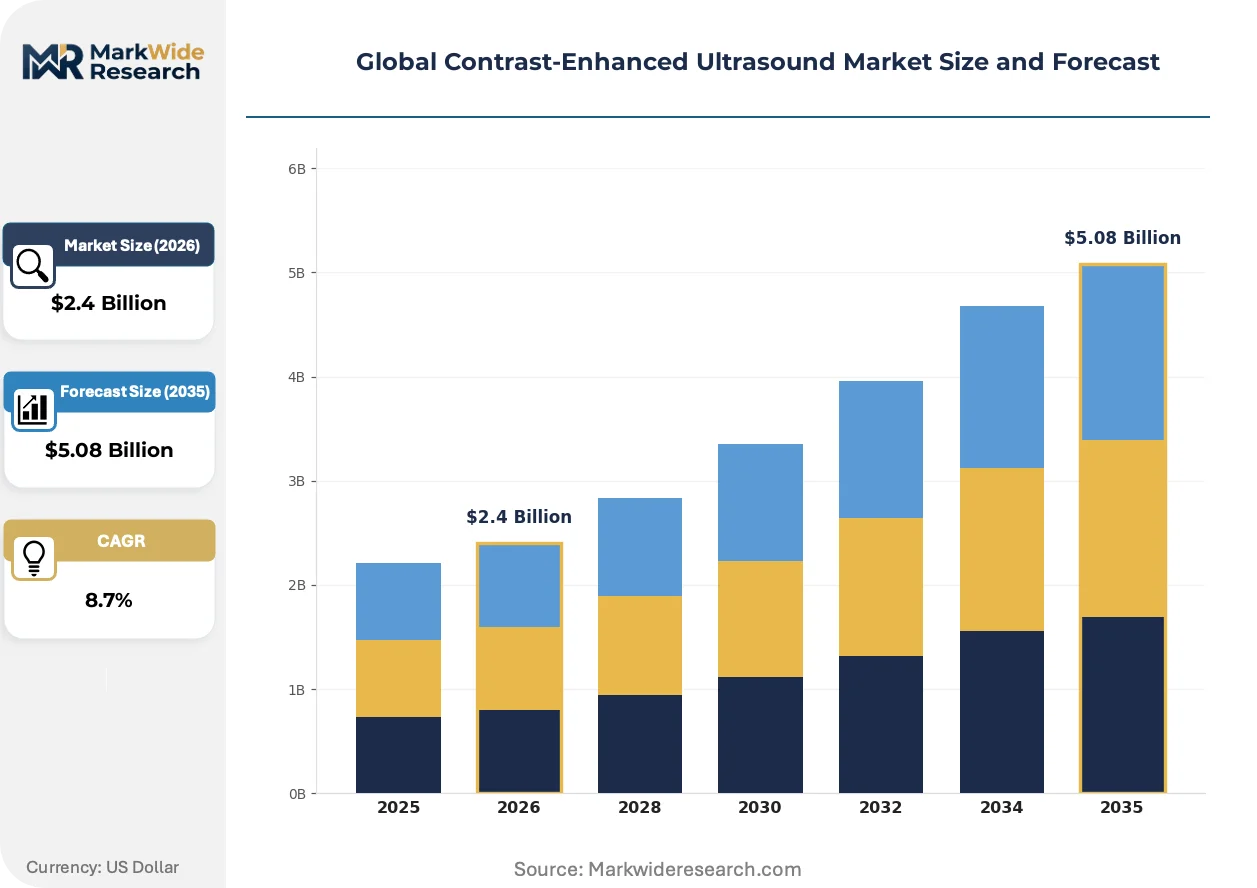
Market Dynamics
Microbubble manufacturing concentration among three specialized suppliers creates supply security vulnerabilities while FDA post-market surveillance requirements intensify compliance burdens for contrast agent developers.
Growth Catalysts
- Cardiology protocol expansion:Tertiary hospitals in the United States, Germany, and Japan now reimburse contrast-enhanced echocardiography for coronary flow assessment, embedding microbubble perfusion imaging into standard cardiac care pathways.
- Oncology application acceleration:Liver and renal malignancy staging protocols increasingly incorporate tumor perfusion monitoring, expanding clinical utility beyond traditional cardiology boundaries.
- CE marking pathway clarity:The EU Medical Device Regulation's Class III device classification for microbubble formulations provides structured commercialization routes for European market access.
Market Restraints
- Perfluorocarbon feedstock volatility:Gas core materials face price instability tied to fluorochemical supply chains concentrated in Chinese and US manufacturing bases.
- Specialized manufacturing bottleneck:Phospholipid shell production requires aseptic processing capabilities limited to a handful of European and North American contract manufacturers.
- CT perfusion substitution threat:Computed tomography angiography with iodinated contrast maintains entrenched referral patterns in emergency department settings despite radiation exposure trade-offs.
Strategic Opportunities
- Pediatric neurology underpenetration:Microbubble-based blood-brain barrier imaging for pediatric brain tumor assessment remains protocol-limited in US children's hospitals, creating first-mover expansion potential.
- Japan PMDA accelerated review:Innovative diagnostic agents demonstrating superiority over existing modalities qualify for priority assessment, compressing time-to-market for novel microbubble formulations.
- Point-of-care integration:Portable ultrasound systems with embedded contrast harmonic imaging algorithms enable ambulatory clinic deployment outside hospital radiology departments.
Industry Challenges
- Sonographer certification complexity:Contrast-enhanced ultrasound administration requires specialized training credentials that vary across US state medical boards and European national radiology societies, fragmenting workforce deployment.
- Harmonization timeline delays:Divergent pharmacovigilance reporting formats between FDA adverse event databases and EMA's Eudamed system complicate multi-regional clinical trial design.
- Legacy echocardiography system integration:Hospital capital equipment refresh cycles averaging seven years delay contrast-specific software upgrades on installed ultrasound platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contrast-Enhanced Ultrasound Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Contrast Agents, Imaging Systems, Software Solutions, Accessories Application: Cardiology, Oncology, Nephrology, Gynecology, Vascular Imaging, Liver Disease Diagnosis End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Specialty Clinics Deployment: On-premise Systems, Cloud-Based Solutions, Hybrid Models, Mobile Units |
| Companies Covered | GE Healthcare, Siemens Healthineers, Bracco Imaging, Koninklijke Philips, Lantheus Holdings, Canon Medical Systems, Fujifilm Holdings, Bayer AG, Guerbet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contrast-Enhanced Ultrasound Market Shifts & Advancements
Targeted microbubble conjugation with ligand-specific binding is redefining molecular imaging capabilities while regulatory harmonization efforts accelerate cross-border protocol standardization.
Next-generation lipid-shelled microbubbles engineered for extended circulation half-life are displacing first-generation albumin-based agents in interventional oncology procedures. Academic medical centers in the United States and Germany have adopted these formulations for transarterial chemoembolization monitoring, compressing the addressable market for conventional contrast agents in hepatocellular carcinoma staging.
EMA's MDR framework imposes enhanced clinical evidence requirements for Class III device classification of microbubble formulations. Manufacturers must now submit post-market clinical follow-up data as a condition of continued CE marking validity, forcing restructuring of European regulatory affairs staffing and documentation systems.
Hospital procurement departments increasingly bundle contrast agent supply contracts with ultrasound equipment leasing arrangements, displacing traditional pharmaceutical distributor relationships. This channel consolidation is most visible in German and Japanese healthcare systems where integrated device-consumable agreements now dominate tertiary hospital purchasing decisions.
Global Contrast-Enhanced Ultrasound Market Segmentation
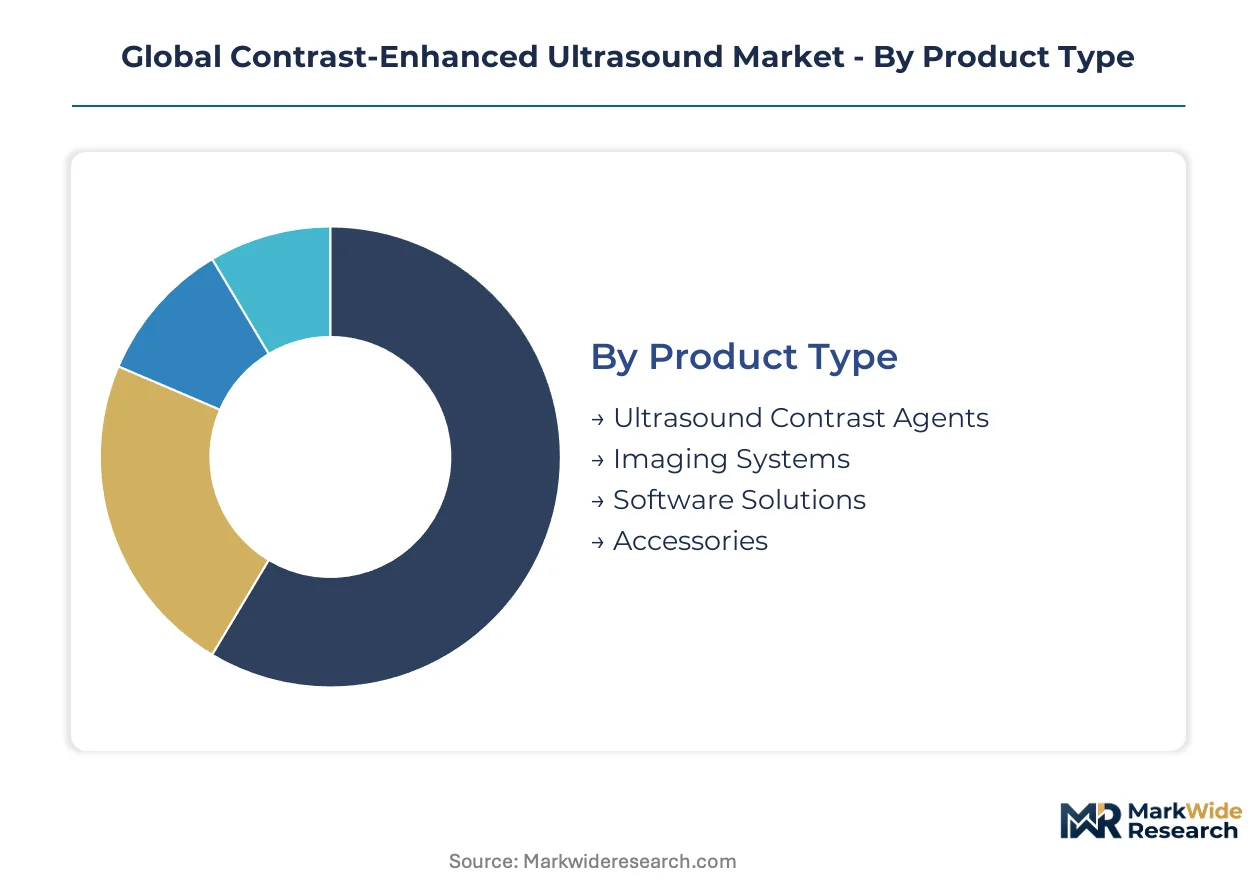
Segmentation in the contrast-enhanced ultrasound market reflects divergent regulatory pathways, manufacturing complexity tiers, and clinical workflow integration requirements. Each category carries distinct compliance burdens and capital intensity profiles that reshape competitive positioning across geographies.
Product Type:
FDA's Class III device classification and EMA's MDR framework impose divergent clinical evidence requirements on each product category, fragmenting market access timelines and documentation burdens.
- Ultrasound Contrast Agents:Gas-filled microbubbles with phospholipid or protein shells oscillate within acoustic fields to amplify backscatter signals. Tertiary hospitals in the United States, Germany, and Japan embed these agents into reimbursable coronary flow assessment protocols, though perfluorocarbon feedstock volatility constrains margin stability.
- Imaging Systems:Hardware platforms with harmonic imaging algorithms optimize contrast signal detection in real-time perfusion monitoring. German and Japanese healthcare systems increasingly bundle system procurement with consumable supply contracts, displacing traditional distributor relationships.
- Software Solutions:Embedded harmonic processing modules and standalone analysis tools quantify perfusion parameters.
- Accessories:Injection systems, sterile tubing sets, and calibration phantoms complete procedural workflows.
Ultrasound contrast agents handle the majority of throughput; software solutions are gaining share fastest through point-of-care integration.
Application:
Clinical utility concentrates where reimbursement pathways have matured, with cardiology anchoring current volumes while oncology applications expand through protocol adoption in academic medical centers.
- Cardiology:Microbubble-based perfusion imaging enables real-time coronary flow assessment without ionizing radiation. United States tertiary hospitals now reimburse contrast-enhanced echocardiography as standard care, embedding the technique into cardiac catheterization laboratory workflows.
- Oncology:Tumor perfusion monitoring in liver and renal malignancy staging compresses time-to-treatment decisions. Academic medical centers in Germany and the United States have adopted next-generation lipid-shelled microbubbles for transarterial chemoembolization monitoring.
- Nephrology:Renal perfusion assessment avoids nephrotoxic contrast media in compromised patients.
- Gynecology:Ovarian and endometrial lesion characterization employs contrast-enhanced transvaginal ultrasound.
- Vascular Imaging:Peripheral artery disease evaluation and carotid plaque assessment utilize microbubble enhancement.
- Liver Disease Diagnosis:Hepatocellular carcinoma characterization and fibrosis staging leverage perfusion quantification.
Cardiology dominates current procedural volumes; oncology represents the steepest expansion trajectory as tumor perfusion protocols gain adoption.
End User:
Capital equipment refresh cycles and sonographer certification requirements fragment deployment patterns across facility types, with hospital systems leveraging scale advantages in contract negotiations.
- Hospitals:Tertiary institutions integrate contrast-enhanced ultrasound across cardiology, radiology, and interventional oncology departments. Seven-year capital equipment refresh cycles delay contrast-specific software upgrades on installed ultrasound platforms.
- Diagnostic Centers:Focused imaging facilities concentrate on high-volume echocardiography and vascular studies. Specialized training credentials required for contrast administration vary across US state medical boards, complicating workforce deployment.
- Ambulatory Surgical Centers:Limited adoption constrained by emergency response requirements for rare adverse events.
- Specialty Clinics:Cardiology and women's health practices pursue targeted perfusion applications.
Hospitals command the largest procurement volumes; diagnostic centers are expanding most quickly through outpatient protocol shifts.
Deployment:
Channel configuration reflects cybersecurity compliance burdens and data residency requirements that vary across FDA, EMA, and PMDA jurisdictions.
- On-premise Systems:Hardware-resident processing ensures data sovereignty and minimizes latency for real-time perfusion imaging. German and Japanese healthcare procurement departments favor these configurations given stringent patient data protection requirements.
- Cloud-Based Solutions:Remote algorithm updates and multi-site image archiving reduce IT infrastructure burdens. FDA guidance on software as a medical device imposes validation requirements that lengthen deployment timelines.
- Hybrid Models:Edge processing with cloud backup balances latency and scalability.
- Mobile Units:Portable ultrasound with embedded contrast capabilities enable ambulatory clinic deployment outside hospital radiology departments.
On-premise systems retain the largest installed base; mobile units are climbing the fastest as point-of-care integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration among tertiary hospitals in the United States, Germany, and Japan shapes regional demand patterns. Reimbursement maturity for contrast-enhanced echocardiography varies sharply across these markets. Regulatory divergence between FDA, EMA, and PMDA frameworks fragments commercialization timelines.
United States
Medicare reimbursement codes for contrast-enhanced echocardiography now cover coronary flow assessment in cardiac catheterization laboratories. FDA post-market surveillance requirements for ultrasound contrast agents intensify pharmacovigilance documentation burdens. The Cleveland Clinic and Mayo Clinic anchor adoption clusters in Ohio and Minnesota.
Germany
Integrated device-consumable procurement agreements dominate tertiary hospital purchasing decisions across Bavaria and North Rhine-Westphalia. EMA's MDR Class III device classification imposes enhanced clinical evidence requirements for microbubble formulations. Siemens Healthineers maintains manufacturing presence in Erlangen.
Japan
PMDA accelerated review pathways compress time-to-market for innovative diagnostic agents demonstrating superiority over existing modalities. National health insurance reimbursement for contrast-enhanced ultrasound in oncology applications expanded in 2023. Tokyo and Osaka academic medical centers drive protocol adoption.
United Kingdom
NICE technology appraisals increasingly reference contrast-enhanced ultrasound for renal perfusion assessment in compromised patients. MHRA post-Brexit regulatory divergence from EMA MDR creates parallel compliance pathways. London teaching hospitals concentrate procurement influence.
China
NMPA innovation review pathways prioritize diagnostic agents with demonstrated clinical advantage over CT perfusion alternatives. Provincial centralized procurement pilots in Jiangsu and Guangdong compress pricing for ultrasound contrast agents. Shanghai medical device clusters expand microbubble manufacturing capacity.
Global Contrast-Enhanced Ultrasound Market Competitive Landscape
Player mix skews toward diversified imaging conglomerates with captive ultrasound hardware platforms. Three specialized microbubble manufacturers supply contrast agents to this installed base. Strategic archetypes separate vertically integrated device-consumable bundlers from standalone pharmaceutical developers and regional equipment specialists. Competitive moves concentrate on M&A for harmonic imaging algorithm portfolios and capacity expansion in aseptic phospholipid processing.
Among diversified imaging conglomerates, GE Healthcare, Siemens Healthineers, and Philips occupy positions anchoring hardware-software-consumable integration. Bracco Imaging and Lantheus Holdings exemplify the specialized pharmaceutical developer archetype focused on cardiovascular ultrasound agents. Canon Medical Systems and Fujifilm Holdings represent regional equipment specialists extending into contrast-enhanced imaging workflows.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Bracco Imaging |
| Koninklijke Philips |
| Lantheus Holdings |
| Canon Medical Systems |
| Fujifilm Holdings |
| Bayer AG |
| Guerbet |
| Others |
Supply & Pricing Matrix
Ninety-day phospholipid shell inventory cycles in European aseptic processing facilities concentrate pricing leverage among three specialized microbubble manufacturers, while German and Japanese hospital procurement departments exploit device-consumable bundling to compress agent margins.
Pricing Analysis
Cost-plus contracts with perfluorocarbon feedstock indexation dominate ultrasound contrast agent procurement between tertiary hospitals and specialized suppliers. Three-tier pricing structure across premium lipid-shelled formulations, standard albumin-based agents, and economy phospholipid variants differentiates by circulation half-life performance. Cost compression in the economy tier is intensifying because Chinese provincial centralized procurement pilots in Jiangsu and Guangdong compress pricing for conventional microbubbles. Diagnostic centers exhibit the highest price sensitivity due to thin procedural margins, while academic medical centers in the United States and Germany prioritize clinical validation over unit cost.
Supply Chain Analysis
Strait of Hormuz transit risk for fluorochemical feedstocks from Chinese and US manufacturing bases concentrates supply vulnerability in perfluorocarbon gas core production. Microbubble formulation draws from phospholipid shell processing in Belgium, Italy, and North Carolina, plus harmonic imaging algorithm development in Germany and Japan. Single-source vulnerability in aseptic phospholipid manufacturing creates bottleneck exposure for European market access. Distribution runs through integrated device-consumable agreements in German and Japanese healthcare systems, displacing traditional pharmaceutical distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tertiary hospital systems in the United States, Germany, and Japan, where seven-year capital equipment refresh cycles and bundled procurement agreements fragment pricing leverage for standalone contrast agent developers.
For Market Incumbents: Consolidate backward integration into phospholipid shell manufacturing to reduce dependency on European and North American contract aseptic processors. Lock in long-term perfluorocarbon supply agreements with Chinese and US fluorochemical suppliers before feedstock volatility intensifies. CE marking renewal under EMA's MDR Class III device classification demands post-market clinical follow-up data restructuring—accelerate European regulatory affairs staffing to defend market access timelines against emerging lipid-shelled competitors. For New Entrants and Emerging Players: Anchor in pediatric neurology blood-brain barrier imaging protocols at US children's hospitals, where microbubble-based tumor assessment remains underpenetrated and first-mover clinical validation can establish protocol lock-in. Target Japan's PMDA accelerated review pathway for innovative diagnostic agents demonstrating superiority over CT perfusion alternatives, compressing time-to-market against entrenched cardiology incumbents. Pursue point-of-care integration partnerships with portable ultrasound manufacturers to bypass hospital radiology department gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurring-revenue play because microbubble per-procedure consumption creates annuity-like cash flows tethered to installed ultrasound hardware bases. Acquisition targets should profile specialized aseptic phospholipid processors with captive supply relationships to Bracco Imaging or Lantheus Holdings, or harmonic imaging algorithm portfolios from mid-cap European software developers. The signal to watch is Japan PMDA reimbursement expansion for oncology applications beyond Tokyo and Osaka academic centers—geographic protocol diffusion indicates addressable market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR Class III device classification imposes enhanced clinical evidence requirements for microbubble formulations seeking European commercialization. |
| Hospital System Partnership | German and Japanese tertiary hospitals bundle contrast agent supply contracts with ultrasound equipment leasing arrangements. |
| Software Companion Development | Embedded harmonic imaging algorithms on portable ultrasound systems enable point-of-care deployment outside radiology departments. |
| Reimbursement Strategy | Medicare coverage for contrast-enhanced echocardiography in US cardiac catheterization laboratories anchors procedural volume. |
| Backward Integration | Captive phospholipid shell manufacturing reduces dependency on limited European and North American aseptic processors. |
Research Methodology
A spread of perspectives from hospital purchasing committees, GPO contracts managers, biomedical engineers, and regulatory affairs leads at microbubble manufacturers converged on the working assumptions for this analysis. Primary interview intelligence combined with secondary validation from FDA adverse event databases, EMA MDR submission filings, CMS Medicare reimbursement codes, and hospital procurement databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Segmentation dimensions modeled include product type (ultrasound contrast agents, imaging systems, software solutions, accessories), application (cardiology, oncology, nephrology, gynecology, vascular imaging, liver disease diagnosis), end user (hospitals, diagnostic centers, ambulatory surgical centers, specialty clinics), and deployment configuration (on-premise, cloud-based, hybrid, mobile). CAGRs derived from regression analysis of historical procedure volumes and reimbursement pathway maturation trajectories. Forecast inputs incorporated sonographer certification fragmentation across US state medical boards and seven-year ultrasound platform refresh cycles.
Material uncertainties—PMDA reimbursement expansion timing, perfluorocarbon feedstock volatility, CT perfusion substitution in emergency departments—sit outside the modeled envelope. Practitioners should keep alternative scenarios live as harmonization between FDA adverse event databases and EMA's Eudamed system evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
France Digital X-Ray Devices Market