
 Digital Respiratory Devices Market | 2026-2036
Digital Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Respiratory Devices Market Intelligence
Hospital procurement of standalone respiratory equipment is collapsing as homecare providers and payers assume purchasing authority for connected monitoring ecosystems. ResMed Inc. dominates the cloud-connected CPAP segment through its proprietary digital health infrastructure. Philips Healthcare leverages its diagnostic imaging relationships to cross-sell integrated spirometry platforms into pulmonary clinics. Adherium specializes in Bluetooth-enabled inhaler adherence systems that compete on medication-therapy-management contracts with pharmacy benefit managers.
Digital respiratory devices integrate sensors, wireless connectivity, and software algorithms into traditional inhalers, nebulizers, spirometers, and CPAP machines to capture real-time pulmonary function data and transmit it to clinicians or cloud platforms for therapeutic adjustment. These systems typically incorporate flow sensors with accuracy thresholds of ±3% and Bluetooth Low Energy modules operating at 2.4 GHz to enable continuous remote monitoring of asthma, COPD, and sleep apnea patients. Inhalers and CPAP machines anchor current revenue pools due to recurring consumables and subscription-based adherence programs, while spirometers represent the fastest-expanding category as employers and insurers deploy workplace screening protocols. IoT-enabled devices capture the dominant technology position through embedded cellular and Bluetooth architectures, though wearables are gaining traction as wrist-worn pulse oximeters and respiratory rate monitors merge with general wellness tracking.
The FDA's Software as a Medical Device framework and the EU MDR's classification rules for active therapeutic devices are elevating clinical evidence requirements before market authorization, directly extending development timelines and capital needs for new entrants. Japan's PMDA has accelerated review pathways for AI-augmented respiratory diagnostics, creating a regulatory arbitrage opportunity for firms with existing Japanese pharmaceutical partnerships. Stakeholders must decide whether to absorb compliance costs for dual FDA-MDR submissions or prioritize single-market dominance with deeper payer integration.
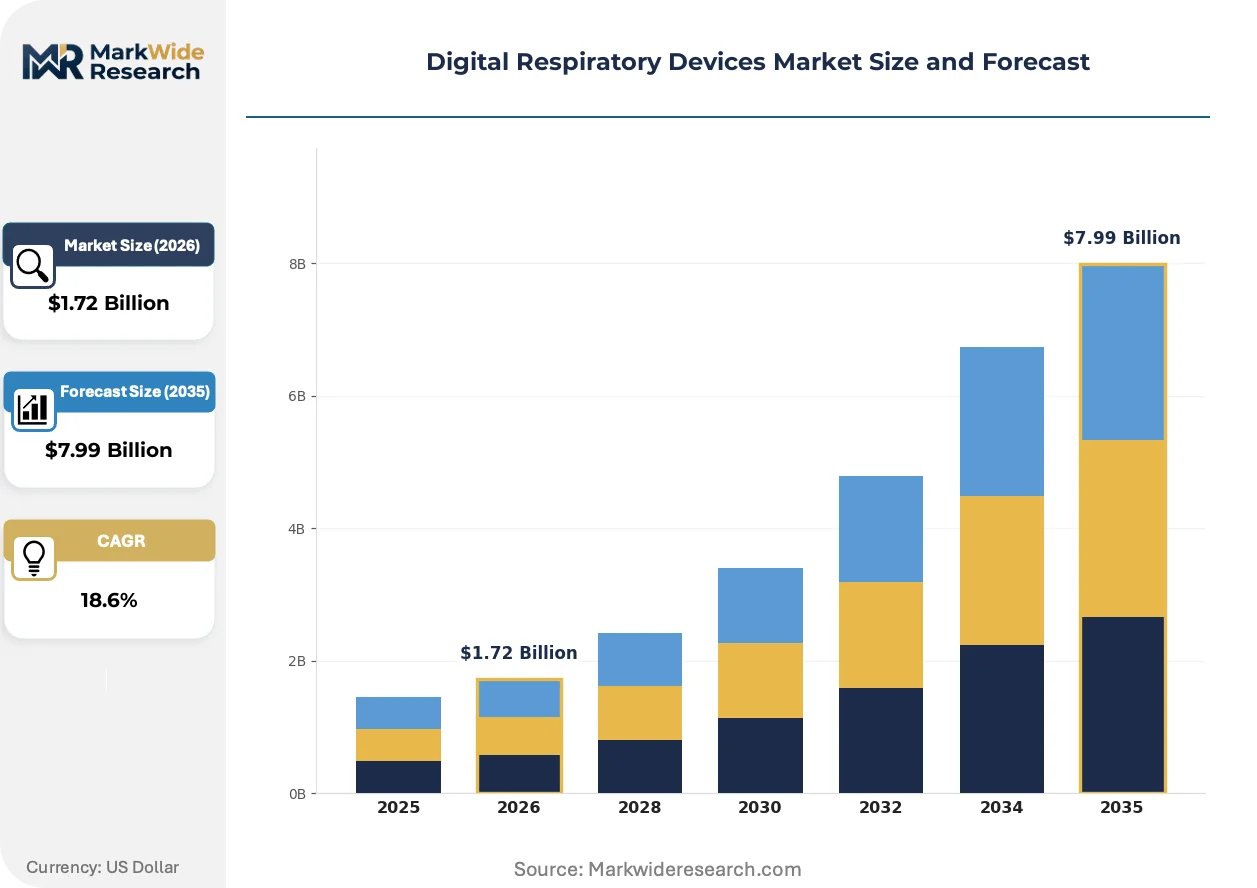
Market Dynamics
Homecare purchasing authority is consolidating around integrated digital respiratory ecosystems as hospital procurement of standalone equipment contracts. Payers now dictate device selection through remote patient monitoring reimbursement codes, forcing manufacturers to embed cellular connectivity and cloud analytics as standard features rather than premium upgrades.
Growth Catalysts
- EU MDR software validation pathways:The framework's classification rules for active therapeutic devices with embedded algorithms create regulatory clarity that accelerates payer confidence in connected inhaler systems across Germany, France, and the Netherlands.
- Bluetooth Low Energy sensor miniaturization:Flow sensors achieving ±3% accuracy thresholds at sub-dollar unit costs enable mass deployment of disposable-connected inhaler attachments for asthma management programs.
- Japan's PMDA accelerated AI diagnostic review:The streamlined pathway for machine learning-augmented respiratory diagnostics attracts development investment from firms with existing pharmaceutical partnerships in Tokyo and Osaka.
Market Restraints
- FDA SaMD clinical evidence requirements:The Software as a Medical Device framework mandates prospective validation studies that extend development timelines by 18-24 months for algorithm-driven spirometry platforms.
- Cellular module supply concentration:Narrow sourcing options for LTE-M and NB-IoT chipsets from Qualcomm and Nordic Semiconductor create procurement vulnerability for device manufacturers scaling production.
- Lithium-ion battery chemistry constraints:Energy density limitations restrict continuous monitoring duration in wrist-worn pulse oximeters, forcing trade-offs between form factor and respiratory rate sampling frequency.
Strategic Opportunities
- Employer workplace spirometry mandates:Occupational health screening protocols in manufacturing and chemical processing sectors create bulk procurement channels for IoT-enabled lung function devices.
- India's CDSCO streamlined medical device registration:The 2017 Medical Device Rules amendments reduce import clearance complexity for Class A and B connected respiratory monitors, opening access to price-sensitive hospital networks.
- AI-augmented medication adherence prediction:Machine learning models analyzing inhaler timing patterns combined with environmental sensor data enable preemptive intervention protocols that differentiate service offerings.
Industry Challenges
- Embedded firmware cybersecurity certification:IEC 62304 compliance for software lifecycle processes demands specialized engineering talent that commands premium compensation in Boston and San Diego device clusters.
- Legacy EMR integration complexity:HL7 FHIR interoperability requirements force custom API development for each health system deployment, inflating implementation costs and extending sales cycles.
- Clinical evidence generation timelines:Prospective studies measuring exacerbation reduction require 12-18 month follow-up periods that strain startup runway financing before payer contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Respiratory Devices Market |
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $7.99 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Spirometers, CPAP Machines Delivery Mode: Digital Platforms, Mobile Apps, Cloud Solutions, Telehealth Services End User: Hospitals, Homecare, Clinics, Rehabilitation Centers Technology: IoT-enabled Devices, Wearables, Mobile Health, Software Solutions |
| Companies Covered | Philips Healthcare, ResMed Inc., Teva Pharmaceuticals Industries Ltd., COHERO Health Inc., 3M, Adherium, Propeller Health, Amiko Digital Health Limited, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Respiratory Devices Market Strategic Shifts & Innovations
Algorithmic respiratory pattern recognition is migrating from cloud-based processing to edge computing architectures embedded directly in inhaler and CPAP hardware. This shift reduces latency for critical alerts while addressing data sovereignty concerns that block hospital adoption.
Capacitive micromachined ultrasonic transducers are displacing traditional piezoelectric flow sensors in next-generation spirometers. Pulmonary diagnostic clinics in Germany and Japan are adopting these solid-state alternatives for their immunity to moisture contamination and extended calibration intervals. The technology is displacing maintenance-intensive pneumatic components that previously required quarterly technician visits.
Japan's PMDA has established a dedicated review pathway for AI-augmented respiratory diagnostics that reduces authorization timelines for algorithm changes post-market. This regulatory innovation permits continuous model improvement without full resubmission, accelerating competitive iteration cycles for software-centric device developers. Domestic pharmaceutical partnerships provide the clinical data access that foreign competitors struggle to replicate under this framework.
Pharmacy benefit managers are consolidating inhaler procurement decisions across regional health plans, concentrating purchasing leverage in three national entities. This buyer concentration forces device manufacturers to compete on medication-therapy-management contract terms rather than hardware specifications alone. The shift is most visible in United States commercial insurance markets where CVS Caremark and Express Scripts determine formulary inclusion for connected inhaler systems.
Digital Respiratory Devices Market Segmentation
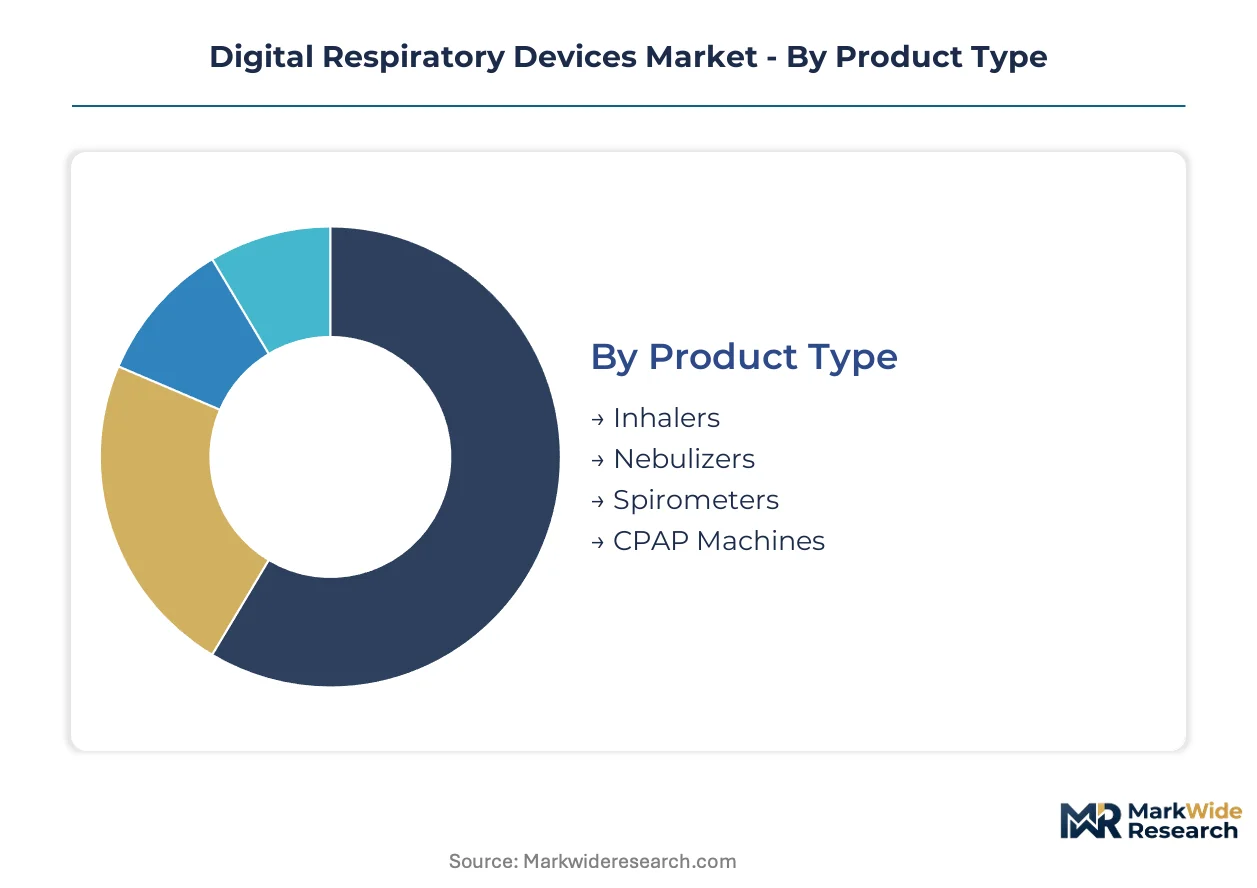
Segmentation in digital respiratory devices determines reimbursement pathways, regulatory classification, and integration requirements with clinical workflows. Each dimension carries distinct FDA SaMD and EU MDR compliance obligations that shape vendor go-to-market economics.
Product Type:
FDA's Software as a Medical Device framework and EU MDR classification rules for active therapeutic devices create divergent approval timelines across hardware categories.
- Inhalers:Bluetooth-enabled metered-dose and dry-powder systems with flow sensors achieving ±3% accuracy thresholds. Pharmacy benefit managers in the United States now mandate cellular connectivity for formulary inclusion, shifting procurement authority from hospitals to CVS Caremark and Express Scripts.
- CPAP Machines:Cloud-connected positive airway pressure systems with embedded humidification control and remote pressure titration. ResMed's proprietary digital health infrastructure dominates homecare purchasing in Germany and Japan where reimbursement codes for remote patient monitoring have matured.
- Spirometers:Pulmonary function devices deploying capacitive micromachined ultrasonic transducers.
- Nebulizers:Jet and mesh systems with dose-tracking sensors for cystic fibrosis management.
CPAP machines handle the majority of throughput; spirometers are expanding most quickly as employers deploy workplace screening protocols.
Delivery Mode:
Cost tier differentiation separates premium integrated ecosystems from standalone software licenses.
- Cloud Solutions:Centralized data aggregation platforms with HL7 FHIR interoperability for health system EMR integration. Implementation costs inflate sales cycles in United States hospital networks demanding custom API development for each deployment.
- Digital Platforms:Manufacturer-proprietary ecosystems combining hardware, connectivity, and analytics subscriptions. Philips Healthcare leverages diagnostic imaging relationships to cross-sell these integrated platforms into pulmonary clinics.
- Mobile Apps:Patient-facing adherence tracking and medication reminder applications.
- Telehealth Services:Clinician-mediated remote monitoring with synchronous video consultation.
Cloud solutions command the highest contract values; telehealth services are climbing the fastest as payers consolidate remote patient monitoring reimbursement.
End User:
Customer type determines purchasing authority concentration and device specification requirements.
- Homecare:Patient-directed procurement of connected inhalers and spirometers with cellular-enabled transmission to pulmonologists. Payer reimbursement frameworks in the United States and Japan now dictate device selection through dedicated RPM codes.
- Hospitals:Enterprise procurement of diagnostic spirometry platforms with EMR integration and cybersecurity certification under IEC 62304.
- Clinics:Pulmonary specialty practices adopting AI-augmented diagnostic platforms.
- Rehabilitation Centers:Post-acute care facilities deploying nebulizers and CPAP for respiratory muscle training.
Homecare handles the majority of throughput; clinics are gaining share fastest as Japan's PMDA accelerates AI diagnostic review pathways.
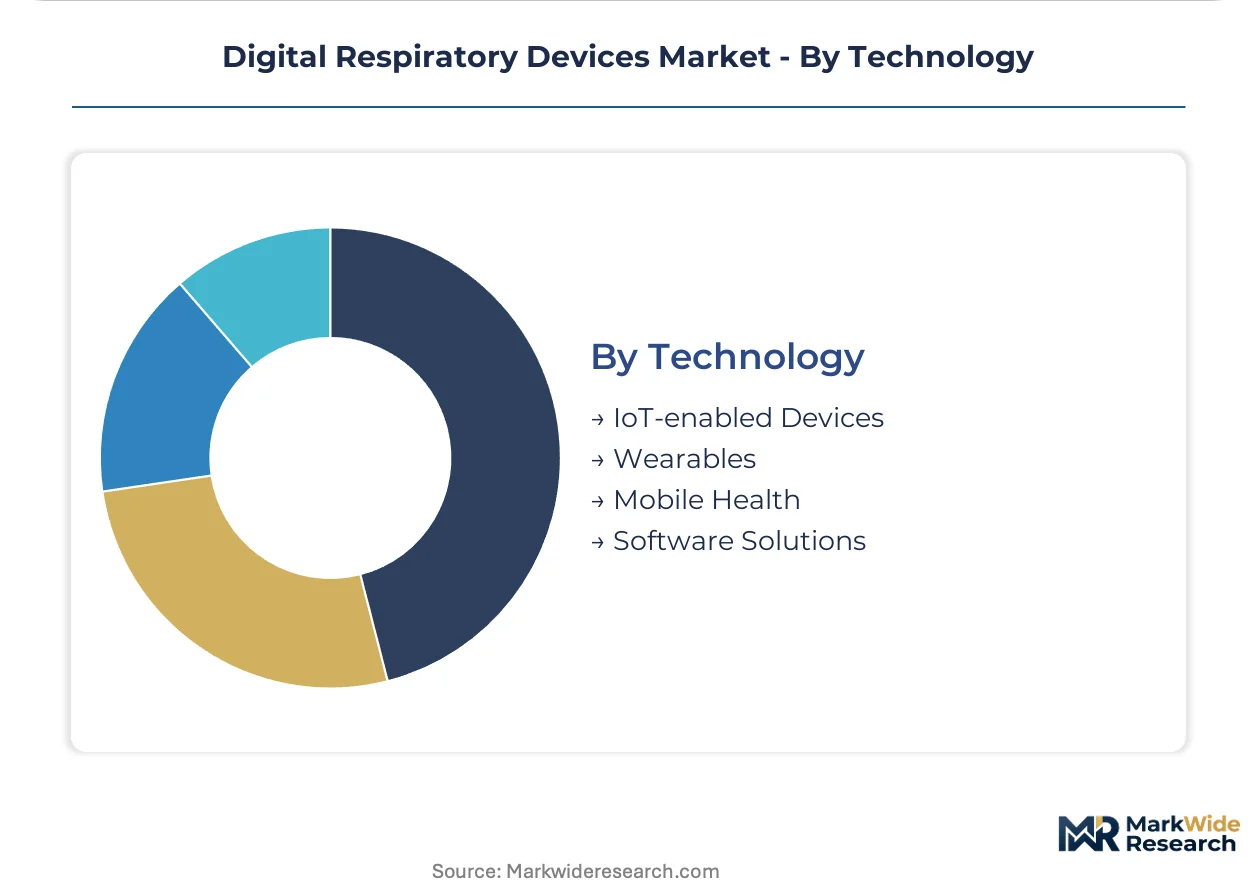
Technology:
Supply concentration in cellular module sourcing from Qualcomm and Nordic Semiconductor constrains scaling economics.
- IoT-enabled Devices:Embedded cellular and Bluetooth architectures with LTE-M and NB-IoT connectivity for continuous data transmission. Lithium-ion battery chemistry constraints restrict form factor miniaturization in wrist-worn configurations.
- Wearables:Wrist-worn pulse oximeters and respiratory rate monitors merging with general wellness tracking. Adherium specializes in Bluetooth-enabled inhaler adherence attachments competing on medication-therapy-management contracts.
- Mobile Health:Smartphone-dependent platforms leveraging device sensors for spirometry approximation.
- Software Solutions:Algorithmic respiratory pattern recognition migrating from cloud to edge computing architectures.
IoT-enabled devices dominate current deployment; wearables show the steepest expansion trajectory as sensor miniaturization reduces unit costs below one dollar.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable corridors linking Boston to Frankfurt and London underpin the data infrastructure for remote patient monitoring platforms. These submarine networks enable real-time transmission of respiratory telemetry from homecare devices to cloud analytics centers. Market expansion correlates directly with the density of these digital arteries.
United States
Commercial insurers now mandate cellular connectivity for connected inhaler formulary inclusion, shifting procurement authority to CVS Caremark and Express Scripts. The FDA's Software as a Medical Device framework extends development timelines for algorithm-driven platforms through prospective validation requirements. Boston and San Diego device clusters concentrate specialized IEC 62304 engineering talent at premium compensation levels.
Germany
The EU MDR's classification rules for active therapeutic devices create regulatory clarity that accelerates payer confidence in connected inhaler systems. Reimbursement codes for remote patient monitoring have matured fastest in Bavaria and North Rhine-Westphalia. Munich-based pulmonary diagnostic clinics adopt capacitive micromachined ultrasonic transducers for their immunity to moisture contamination.
Japan
METI's push for aging-in-place healthcare infrastructure drives homecare purchasing authority consolidation around integrated digital respiratory ecosystems. The PMDA's accelerated review pathway for AI-augmented respiratory diagnostics reduces authorization timelines for algorithm changes post-market. Tokyo and Osaka pharmaceutical partnerships provide clinical data access that foreign competitors struggle to replicate.
India
CDSCO's 2017 Medical Device Rules amendments reduce import clearance complexity for Class A and B connected respiratory monitors. Price-sensitive hospital networks in Maharashtra and Gujarat represent the primary demand channel for entry-level IoT-enabled spirometers. Domestic manufacturing incentives under the PLI scheme attract assembly operations for Bluetooth Low Energy sensor modules.
United Kingdom
NHS England's remote patient monitoring procurement frameworks prioritize HL7 FHIR interoperability for EMR integration. The MHRA's post-Brexit regulatory autonomy permits faster adoption of edge computing architectures in inhaler hardware. London's health technology procurement clusters concentrate purchasing decisions for workplace spirometry mandates in manufacturing sectors.
Digital Respiratory Devices Market Key Industry Players
Concentration sits with diversified medical technology conglomerates that leverage diagnostic imaging relationships to cross-sell integrated platforms. The vendor base stratifies across three tiers: cloud-connected infrastructure owners, Bluetooth-enabled attachment specialists, and pharmaceutical-backed adherence system developers. Strategic moves center on medication-therapy-management contract competition and proprietary digital health ecosystem construction.
Within the cloud-connected infrastructure tier, ResMed Inc. and Philips Healthcare exemplify divergent approaches to homecare purchasing authority consolidation. ResMed anchors the proprietary digital health infrastructure position through its integrated CPAP ecosystem. Philips occupies a position leveraging diagnostic imaging relationships into pulmonary clinic penetration. Among Bluetooth-enabled attachment specialists, Adherium represents the medication-therapy-management contract competition archetype.
| Leading Market Players |
|---|
| Philips Healthcare |
| ResMed Inc. |
| Teva Pharmaceuticals Industries Ltd. |
| COHERO Health Inc. |
| 3M |
| Adherium |
| Propeller Health |
| Amiko Digital Health Limited |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
Capacitive micromachined ultrasonic transducers replacing piezoelectric flow sensors in spirometers simultaneously shifts component sourcing from Japan and Germany toward Taiwan semiconductor foundries while compressing per-unit sensor costs below one dollar. This substitution dynamic redraws procurement geography and intensifies margin pressure on legacy pneumatic component suppliers.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital contracts exceeding ten thousand units from mid-tier pulmonary clinic deployments and individual homecare patient purchases. Pricing stratifies across premium FDA-cleared platforms, standard CE-marked systems, and economy-grade non-connected alternatives. Cost compression in the economy tier intensifies as Indian CDSCO import simplifications attract low-cost manufacturers. Hospital purchasing committees demonstrate lowest price sensitivity due to bundled reimbursement codes, while direct-to-consumer homecare patients exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for Bluetooth Low Energy modules stretch to twenty-six weeks as Qualcomm and Nordic Semiconductor allocate wafer capacity toward automotive and smartphone demand. Component sourcing concentrates in Taiwan, South Korea, and China for MEMS sensors and cellular chipsets. Lithium-ion battery cell supply rests on cylindrical formats from Japan and pouch configurations from China. Single-source vulnerability in LTE-M baseband processors creates procurement risk for device manufacturers scaling production. Distribution runs through pharmaceutical wholesalers for inhaler systems and durable medical equipment distributors for CPAP platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a defensive-moat opportunity anchored in regulatory entrenchment. FDA SaMD validation timelines and EU MDR clinical evidence requirements create structural barriers that protect incumbent positions against rapid competitive displacement.
For Market Incumbents: Fortify cloud-connected infrastructure moats by deepening proprietary digital health ecosystem integration and accelerating IEC 62304 cybersecurity certification investment. Threat from algorithm-native startups with AI-augmented diagnostics demands preemptive edge computing architecture deployment. Channel control through pharmacy benefit manager contract consolidation represents the critical defensive lever.
For New Entrants and Emerging Players: Lead with India's CDSCO-simplified import pathways for Class A and B connected respiratory monitors, where price-sensitive hospital networks in Maharashtra and Gujarat offer lowest competitive density. Workplace spirometry mandates in manufacturing sectors provide the most penetrable application white-space. Go-to-market execution through occupational health service providers bypasses entrenched hospital procurement committees.
For Investors and Strategic Acquirers: The market sits at a regulatory-consolidation phase that favors platform-integrated device developers with existing payer relationships. Long-term viability centers on medication-therapy-management contract concentration rather than hardware innovation cycles. Acquisition target archetype: Bluetooth-enabled attachment specialists with pharmacy benefit manager formulary positioning. Signal to watch: PMDA accelerated AI diagnostic review pathway expansion beyond domestic pharmaceutical partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Submission Pathway | Software validation studies extend development timelines but lock in formulary positioning against unvalidated competitors. |
| CE Marking Under EU MDR | Classification rules for active therapeutic devices create regulatory clarity accelerating German and Dutch payer confidence. |
| Hospital System Partnership | EMR integration via HL7 FHIR interoperability secures long-term procurement contracts with United States health networks. |
| Software Companion Development | Edge computing architectures for inhaler hardware reduce latency and address data sovereignty blocking hospital adoption. |
| Reimbursement Strategy | Remote patient monitoring code alignment with CVS Caremark and Express Scripts formulary requirements determines market access. |
Research Approach
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and pharmacy benefit manager formulary directors provided ongoing calibration against secondary validation. Primary interviews with clinicians and regulatory affairs specialists combined with FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up unit economics and top-down epidemiological prevalence models underwent iterative triangulation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including device hardware category, delivery mode architecture, end-user purchasing authority, and technology connectivity type. CAGRs derived from fitted growth curves applied to patient population forecasts and reimbursement code expansion trajectories. Forecast inputs incorporated Bluetooth sensor cost curves and cellular module availability constraints.
The analysis sits within stated boundaries; outcomes outside sustained FDA SaMD framework stability or EU MDR implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding payer reimbursement code maturation and supply chain lead time normalization. Cybersecurity certification delays or pharmaceutical partnership fragmentation in Japan could materially revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
IV Equipment Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Surgical Display Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Animal Ultrasound Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Ventricular Restoration Systems Market