
 Subperiosteal Implants Market | 2026-2036
Subperiosteal Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Subperiosteal Implants Market Analytics
The FDA's 510(k) clearance framework is pivoting the cost-of-entry calculus for subperiosteal implant manufacturers toward rigorous biocompatibility documentation and predicate device alignment. Straumann Holding AG leverages its Swiss manufacturing heritage to sustain premium positioning across titanium and zirconia material tiers. Danaher Corporation anchors its competitive stance through integrated digital dentistry workflows that span imaging to final prosthesis delivery.
Subperiosteal implants are custom-fabricated or standard prosthetic frameworks that sit atop the alveolar bone beneath the periosteum, typically cast from cobalt-chrome alloys or milled from titanium grade 5 with 10-20 micrometer surface roughness to promote osseointegration, and serve patients with severe mandibular atrophy who lack sufficient bone volume for endosseous alternatives. Custom-fabricated product types dominate margin pools due to patient-specific anatomical matching and higher reimbursement coding, while titanium materials lead volume given decades of clinical validation and favorable strength-to-weight ratios. Robotic-assisted delivery modes represent the fastest-growing structural segment as surgical navigation systems reduce freehand placement variance and compress operative time.
The FDA enforces biocompatibility standards under ISO 10993 series guidance for permanent implant contact, while the EU Medical Device Regulation mandates notified body conformity assessment and clinical evaluation reporting for custom implantable devices. These frameworks elevate compliance spend but simultaneously filter out marginal competitors, concentrating supply among firms with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving FDA guidance on patient-matched device manufacturing and EU MDR transition timelines to calibrate product development pipelines and market access sequencing.
Market Dynamics
Robotic surgical navigation is compressing operative variance and accelerating subperiosteal implant adoption among prosthodontic specialists who previously avoided the procedure's technical complexity.
Growth Catalysts
- FDA 510(k) Pathway Compression:The FDA's streamlined clearance for patient-matched devices reduces regulatory timelines for custom implant architectures, enabling faster commercialization of anatomically-specific frameworks.
- Edentulous Demographics:The United States sustains procedural volume through an aging population with severe mandibular atrophy who lack bone volume for endosseous alternatives.
- Digital Dentistry Integration:Intraoral scanning and CAD/CAM workflows are collapsing the fabrication cycle for cobalt-chrome and titanium grade 5 frameworks.
Market Restraints
- Titanium Grade 5 Supply Concentration:Aerospace and medical device demand concentrates upstream supply among specialty mills, creating input cost volatility for implant manufacturers.
- EU MDR Compliance Burden:The Medical Device Regulation mandates notified body conformity assessment and clinical evaluation reporting, elevating fixed costs for custom device market entry.
- Endosseous Implant Substitution:Zygomatic and pterygoid implant techniques advance as alternatives for atrophic maxillae, capturing cases that previously required subperiosteal frameworks.
Strategic Opportunities
- Zirconia Material Tier Expansion:Ceramic frameworks offer aesthetic superiority for anterior applications and metal-free patient segments, creating premium pricing separation from titanium standards.
- Robotic-Assisted Delivery Modes:Surgical navigation systems reduce freehand placement variance, expanding addressable surgeon pools beyond academic prosthodontic centers.
- Reimbursement Coding Optimization:Favorable dynamics for implant-supported prostheses in United States commercial and Medicare Advantage plans sustain cash-pay conversion rates.
Industry Challenges
- Prosthodontist Training Pipeline:The specialized surgical skill required for subperiosteal placement exceeds general dental residency scope, constraining qualified provider supply.
- ISO 10993 Biocompatibility Documentation:Permanent implant contact classification demands extensive cytotoxicity and sensitization testing, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subperiosteal Implants Market |
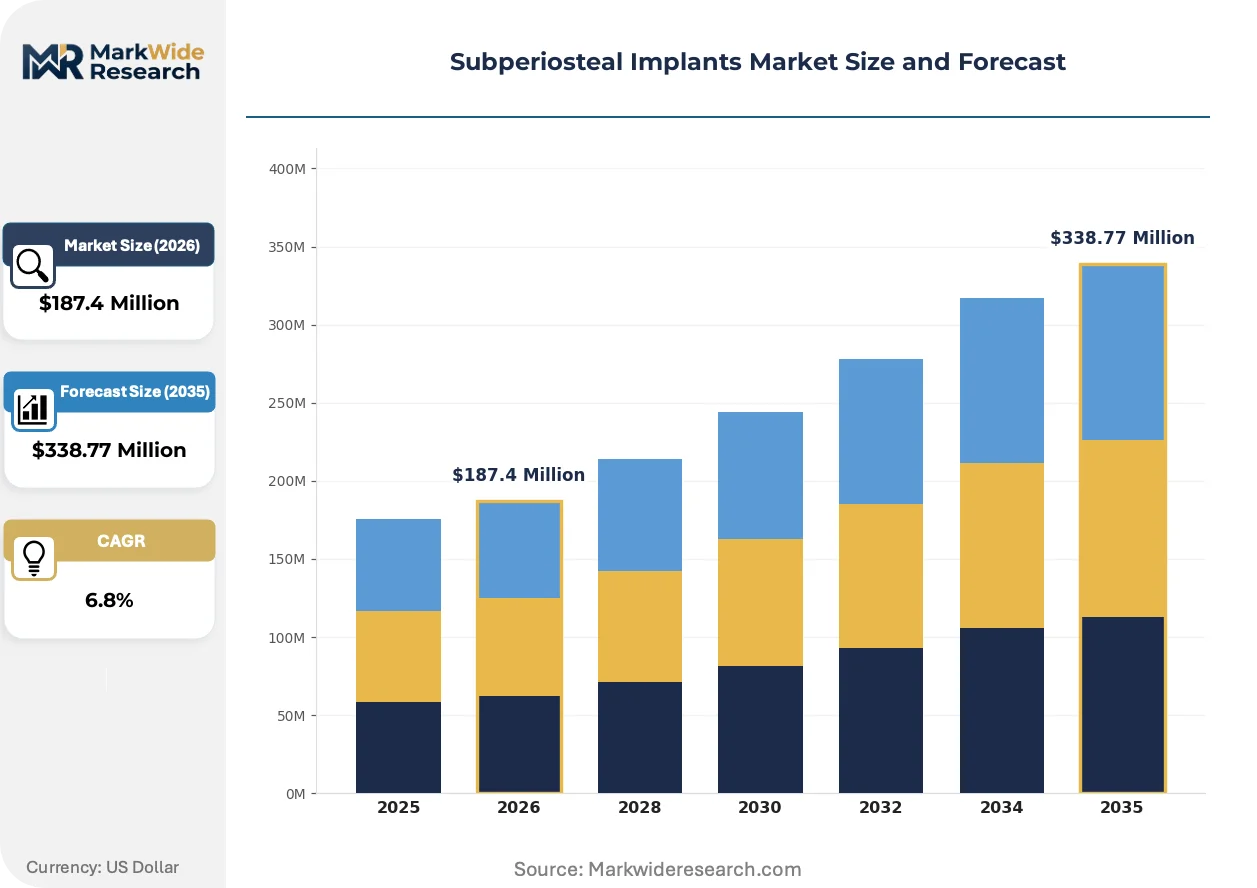
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom-Fabricated, Standard, Reusable, Disposable Material: Titanium, Zirconia, Polyethylene, Composite Delivery Mode: Invasive, Minimally Invasive, Robotic-Assisted, Traditional End User: Dental Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions |
| Companies Covered | AVINENT Implant System, Danaher Corporation, Straumann Holding AG, Bicon, 3M Health Care, Zimmer Biomet Holdings, Osstem Implant, AB Dental Devices Ltd, Dentsply Sirona Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subperiosteal Implants Market Evolving Landscape
Additive manufacturing of patient-specific frameworks is collapsing the traditional casting-to-milling transition and enabling lattice structures that match bone modulus.
Titanium grade 5 with 10-20 micrometer surface roughness remains the clinical standard for osseointegration, but selective laser melting is absorbing direct metal printing from dental laboratories that previously outsourced to central foundries. Prosthodontic clinics with in-house printing capability compress turnaround from weeks to days, capturing margin that casting houses previously extracted.
The EU Medical Device Regulation's 2021 implementation deadline forced recertification of all legacy custom implantable devices, concentrating supply among firms with dedicated regulatory affairs infrastructure. Manufacturers without notified body relationships exited the European market, filtering marginal competitors and elevating compliance spend as a structural barrier.
After-sales technical support is unbundling from device procurement as dental laboratories assume prosthesis modification and framework adjustment responsibilities. This shift transfers service margin from implant manufacturers to lab networks, with United States multi-location dental service organizations negotiating centralized technical support contracts that displace traditional manufacturer-direct field service models.
Subperiosteal Implants Market Segmentation
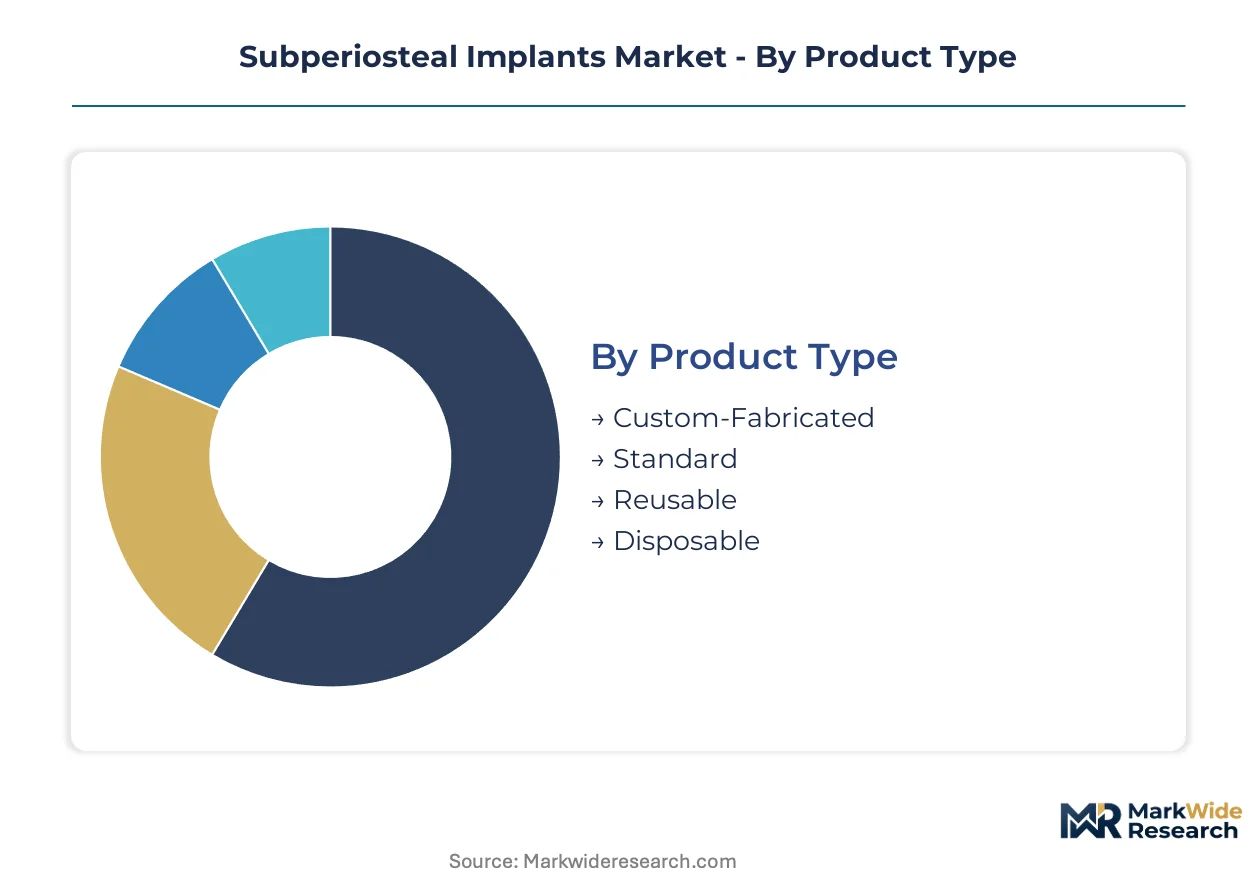
Subperiosteal implant purchasing decisions cascade through four interconnected dimensions. Product architecture determines fabrication cost and reimbursement coding. Material selection governs biocompatibility documentation burden and surface engineering requirements. Delivery mode defines capital equipment needs and surgeon training thresholds. End-user concentration shapes distribution channel economics and technical support intensity.
Product Type:
Capital intensity peaks with patient-matched frameworks requiring CT-based design iteration and specialized manufacturing cells.
- Custom-Fabricated:Anatomically-specific frameworks derived from cone-beam CT datasets demand dedicated CAD/CAM workstations and additive manufacturing or precision casting infrastructure. Dental clinics in the United States with prosthodontic service lines concentrate demand here, driven by favorable reimbursement coding for implant-supported prostheses in Medicare Advantage and commercial plans.
- Standard:Pre-designed architectures reduce per-unit production costs through batch manufacturing economies and eliminate patient-specific regulatory pathways. Volume concentrates among general dental practices in regions with limited access to specialized surgical referral networks.
- Reusable:Modular framework components designed for sterilization and redeployment require durable cobalt-chrome alloys or titanium grade 5 with enhanced fatigue resistance specifications.
- Disposable:Single-use frameworks eliminate sterilization validation costs for ambulatory surgical centers with limited autoclave capacity or rapid turnover requirements.
Most installed capacity flows through Custom-Fabricated. Expansion is steepest in Robotic-Assisted delivery modes.
Material:
Upstream supply concentration and biocompatibility testing burden stratify margin structures across material tiers.
- Titanium:Grade 5 alloy (Ti-6Al-4V) with 10-20 micrometer surface roughness delivers validated osseointegration performance and favorable strength-to-weight ratios for mandibular frameworks. Aerospace and medical device demand concentrates upstream supply among specialty mills, creating input cost volatility that compresses manufacturer margins during titanium spot price spikes.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal offers aesthetic superiority for anterior applications and metal-free alternatives for nickel-sensitive patients. Premium pricing separation from titanium standards sustains margin pools despite higher raw material and milling equipment costs.
- Polyethylene:Ultra-high molecular weight formulations serve provisional or temporary framework applications where load-bearing demands remain modest.
- Composite:Polymer-ceramic hybrid matrices target experimental or research institutional applications with customized mechanical property tuning.
Titanium absorbs the majority of procedural volume. Zirconia claims the steepest pricing premium trajectory.
Delivery Mode:
Surgeon skill requirements and capital equipment thresholds fragment addressable provider pools across placement methodologies.
- Robotic-Assisted:Surgical navigation systems with submillimeter registration accuracy reduce freehand placement variance and compress operative time from three hours to under ninety minutes. Academic prosthodontic centers and large dental service organizations in the United States concentrate adoption, expanding qualified surgeon pools beyond traditional fellowship-trained specialists.
- Minimally Invasive:Flapless or limited-flap approaches reduce postoperative morbidity and accelerate recovery timelines for elderly edentulous patients with comorbid conditions.
- Invasive:Traditional full-thickness flap reflection maintains visualization for complex mandibular atrophy cases with aberrant neurovascular anatomy.
- Traditional:Freehand placement without navigation assistance persists in resource-constrained settings where capital equipment acquisition remains prohibitive.
Traditional methods retain the largest installed base. Robotic-Assisted systems are gaining share fastest among new equipment procurement decisions.
End User:
Procurement authority and technical support expectations diverge sharply between institutional settings and independent practice.
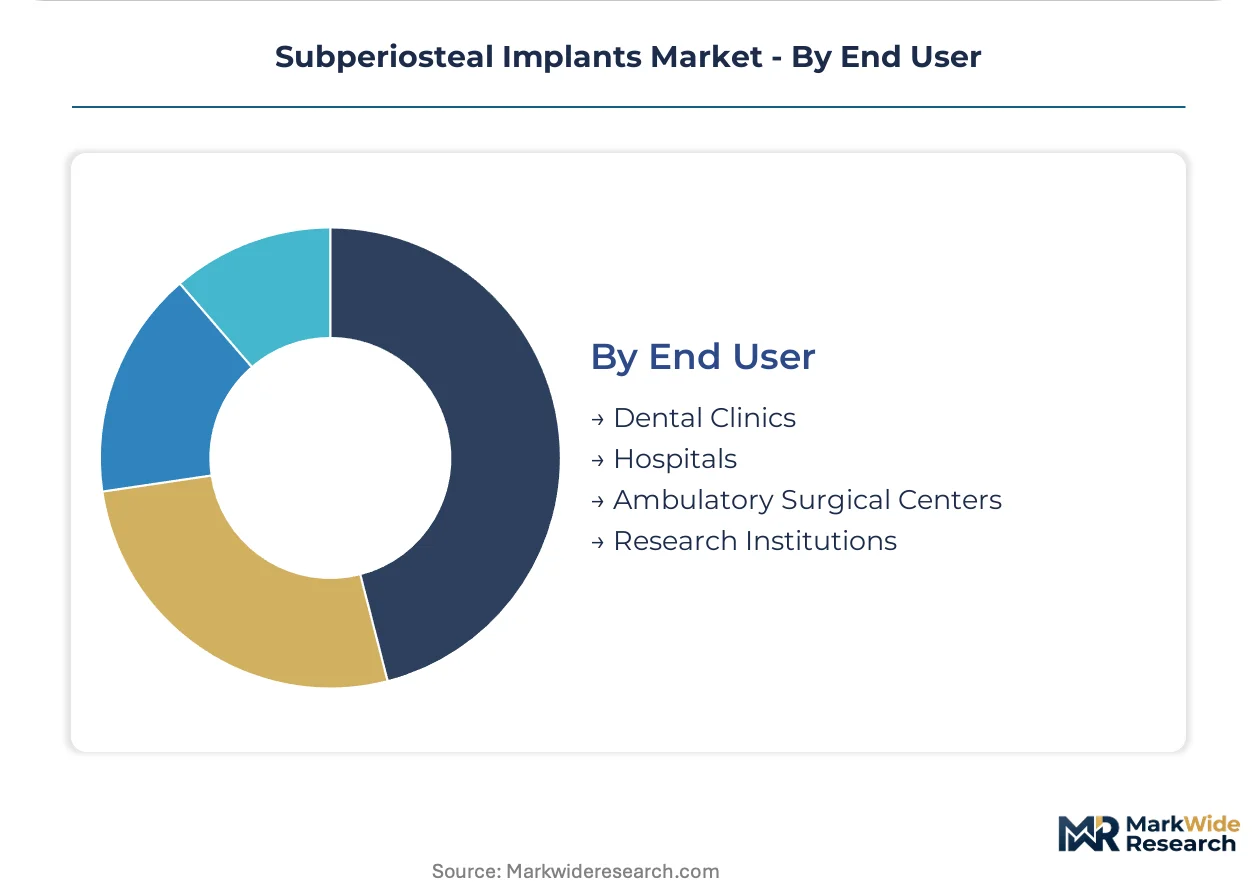
- Dental Clinics:Prosthodontic specialty practices and multi-location dental service organizations command centralized purchasing leverage and negotiate direct manufacturer relationships. The United States aging edentulous population with severe mandibular atrophy sustains procedural volume through expanding prosthodontic service lines as core revenue drivers.
- Hospitals:Integrated health systems with oral and maxillofacial surgery departments manage complex cases requiring general anesthesia and overnight observation.
- Ambulatory Surgical Centers:Same-day discharge protocols and lower facility fees attract commercially insured patients seeking cost-efficient alternatives to hospital-based placement.
- Research Institutions:Academic medical centers with dental schools pursue investigational device exemptions and post-market surveillance studies under FDA oversight.
Dental Clinics process the majority of annual procedures. Ambulatory Surgical Centers are climbing the fastest as site-of-service migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prosthodontic specialists cluster in tertiary dental centers across high-income economies, concentrating procedural expertise where reimbursement frameworks reward implant-supported rehabilitation.
United States
An aging edentulous population with severe mandibular atrophy sustains procedural volume through Medicare Advantage and commercial reimbursement coding. The FDA's 510(k) clearance pathway for custom medical devices compresses time-to-market for patient-specific frameworks. Academic prosthodontic centers in Boston and Los Angeles anchor surgical training pipelines and robotic-assisted adoption curves.
Germany
Precision manufacturing heritage supports cobalt-chrome casting infrastructure and CAD/CAM milling clusters for custom implant frameworks. The EU Medical Device Regulation mandates notified body conformity assessment, elevating compliance spend as a structural filter. Dental laboratories in Stuttgart and Munich concentrate additive manufacturing capability for lattice-structured patient-matched devices.
Switzerland
Swiss manufacturing standards sustain premium positioning across titanium and zirconia material tiers for export-oriented implant producers. Swissmedic oversees clinical evaluation reporting requirements for custom implantable devices under harmonized EU MDR alignment. The Basel-Zurich corridor hosts precision metallurgy suppliers serving dental device manufacturers.
Japan
Super-aging demographics expand the addressable pool of patients with insufficient bone volume for endosseous alternatives. The PMDA enforces biocompatibility documentation under ISO 10993 series guidance for permanent implant contact classification. Tokyo and Osaka dental schools maintain prosthodontic fellowship programs that constrain qualified provider supply.
South Korea
Digital dentistry adoption accelerates intraoral scanning and chairside CAD/CAM workflows for framework fabrication. The MFDS regulates custom medical device manufacturing through quality management system audits and clinical data requirements. Seoul Capital Area dental service organizations centralize procurement leverage for multi-location prosthodontic service lines.
Subperiosteal Implants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across titanium supply chains and digital dentistry workflows. Market structure tilts toward consolidated supply among firms with dedicated regulatory affairs infrastructure capable of navigating FDA 510(k) and EU MDR compliance burdens. Three archetypes dominate: Swiss precision manufacturers leveraging metallurgical heritage, US-based integrated dental technology conglomerates, and Korean-Japanese digital workflow specialists. Competitive moves concentrate on M&A for CAD/CAM software assets and strategic partnerships with dental service organizations for centralized technical support contracts.
Among Swiss-heritage precision manufacturers, Straumann Holding AG occupies a position exemplifying premium-tier metallurgical validation, while Danaher Corporation represents the diversified conglomerate archetype with integrated digital dentistry workflows spanning imaging to final prosthesis delivery. Zimmer Biomet Holdings sits within the orthopedic-dental convergence tier, leveraging scale-driven manufacturing infrastructure.
| Leading Market Players |
|---|
| AVINENT Implant System |
| Danaher Corporation |
| Straumann Holding AG |
| Bicon |
| 3M Health Care |
| Zimmer Biomet Holdings |
| Osstem Implant |
| AB Dental Devices Ltd |
| Dentsply Sirona Inc |
| Others |
Value Network & Pricing Analysis
Selective laser melting's displacement of central foundry casting is collapsing fabrication costs for titanium grade 5 frameworks while concentrating additive manufacturing capacity among dental laboratories with in-house printing capability. This production-method transition simultaneously compresses per-unit margins for traditional casting houses and elevates pricing power for labs that capture same-day turnaround premiums.
Pricing Analysis
The bundled-vs-unbundled service split separates implant manufacturers from dental laboratories in technical support economics. Three-tier pricing structure across premium zirconia, standard titanium, and economy cobalt-chrome levels reflects material certification grade and surface roughness specifications. Pricing pressure stems from dental service organizations negotiating centralized procurement contracts that displace manufacturer-direct field service models. Ambulatory surgical centers exhibit highest price sensitivity due to rapid turnover requirements, while academic prosthodontic centers absorb premium tiers for robotic-assisted delivery modes.
Supply Chain Analysis
Direct-to-dental-laboratory channels handle patient-matched framework demand, with secondary distribution through prosthodontic specialty clinics for complex mandibular atrophy cases. Upstream titanium grade 5 supply concentrates in the United States, Germany, and Japan among aerospace-certified specialty mills. Raw material dependencies include cobalt-chrome alloys, yttria-stabilized zirconia, and precision milling equipment. Single-source vulnerability in titanium spot markets creates input cost volatility during aerospace demand surges. Distribution runs through regional dental laboratory networks with CAD/CAM workstation investments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA 510(k) clearance compression for patient-matched devices accelerates commercialization timelines and rewards firms with dedicated regulatory affairs infrastructure.
For Market Incumbents: Lock in notified body relationships under EU MDR to filter marginal competitors from European market access. Secure backward integration into titanium grade 5 supply through long-term offtake agreements with aerospace-certified mills, defending against spot price volatility that compresses manufacturer margins. Prioritize CAD/CAM software acquisitions to maintain integrated digital dentistry workflows against pure-play specialists.
For New Entrants and Emerging Players: Cloud-based surgical navigation partnerships offer the lowest-friction entry path for robotic-assisted delivery mode adoption without capital-intensive hardware development. Target ambulatory surgical centers in the United States with disposable framework offerings that eliminate sterilization validation costs. Pursue reimbursement coding optimization consulting as a service-layer wedge before device commercialization.
For Investors and Strategic Acquirers: Valuations sit cheapest among dental laboratories with additive manufacturing capability but without prosthodontic clinic network integration. Long-term viability hinges on consolidation of fragmented lab networks under dental service organization umbrellas. Watch FDA guidance evolution on patient-matched device manufacturing as the inflection signal for regulatory compliance spend acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines for patient-matched titanium frameworks reward early regulatory investment. |
| CE Marking Pathway Optimization | EU MDR notified body relationships filter competitors and sustain premium pricing in European markets. |
| Dental Service Organization Partnership | Centralized procurement contracts with United States multi-location clinics displace fragmented lab distribution. |
| Software Companion Development | Surgical navigation integration with robotic-assisted delivery expands addressable surgeon pools beyond academic centers. |
| Reimbursement Strategy | Medicare Advantage coding optimization for implant-supported prostheses sustains cash-pay conversion rates. |
Research Methodology
Multiple input streams — prosthodontic specialists, dental laboratory operators, biomedical engineers, and GPO contracts managers — were reconciled against FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and dental service organization capex disclosures. Secondary validation drew from customs trade data for titanium grade 5 imports and CMS Medicare procedure volume statistics. Bottom-up unit economics and top-down market sizing were triangulated to constrain estimate variance.
Data-stream reconciliation across product architecture, material tier, delivery mode, and end-user concentration dimensions generated volume and value outputs throughout the forecast period. CAGRs were derived from procedural volume elasticity to aging edentulous demographics and reimbursement coding dynamics. Industry-specific forecast inputs included cone-beam CT adoption curves and robotic surgical navigation capital expenditure patterns.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing lattice structures would alter the outlook if bone modulus matching achieves clinical equivalence faster than projected. Forecasts reflect documented assumptions around FDA guidance evolution and EU MDR transition timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable Thermometer Market
Medical Devices
Bone Allografts Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Blood Lancet Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
EEG and EMG Equipment Market