
 Cochlear Implant Systems Market | 2026-2036
Cochlear Implant Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cochlear Implant Systems Market Analysis
Buyer concentration among pediatric ENT clinics is recalibrating as regional hospital networks consolidate procurement decisions across multiple sites. Cochlear Limited leverages in-house electrode manufacturing to sustain supply continuity for its flagship devices. MED-EL Medical Electronics anchors its position through direct distribution in European hearing centers. Advanced Bionics differentiates via integrated sound processing platforms that reduce fitting complexity for audiologists.
Cochlear implant systems are surgically implanted neuroprosthetic devices that bypass damaged cochlear hair cells to electrically stimulate the auditory nerve, typically incorporating an external speech processor and internal receiver-stimulator array with 12-24 electrode contacts. These systems restore functional hearing in severe-to-profound sensorineural hearing loss patients across pediatric and adult populations. The product type dimension shows cochlear implants commanding the core revenue pool while bone anchored hearing aids capture niche conductive loss segments. The end user dimension reveals hospitals absorbing capital-intensive surgical systems as ENT clinics shift toward outpatient fitting and rehabilitation services.
The FDA governs premarket approval and post-market surveillance through its Office of Ear, Nose, and Throat Devices, while the EU MDR imposes stricter clinical evidence requirements for active implantable devices under notified body oversight. China's NMPA has accelerated review pathways for innovative neuroprosthetics, reshaping market access timelines for multinational manufacturers. Stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies to anticipate volume shifts across public and private payer channels.
Market Dynamics
Pediatric screening mandates are expanding addressable patient pools while reimbursement coding battles determine which provider types capture surgical margins. The tension between centralized hospital procurement and distributed ENT clinic networks is reshaping competitive access points across mature markets.
Growth Catalysts
- Universal Newborn Hearing Screening mandates:Legislative requirements in the United States and Germany are pushing diagnosis timelines earlier, expanding the pediatric candidate pool for surgical intervention before critical language development windows close.
- EU MDR clinical evidence pathways:Stricter post-market surveillance requirements for active implantable devices are accelerating real-world data collection infrastructure that supports expanded indications.
- Electrode array miniaturization:Advances in thin-film electrode manufacturing are enabling less traumatic insertion trajectories that preserve residual hearing in hybrid candidates.
Market Restraints
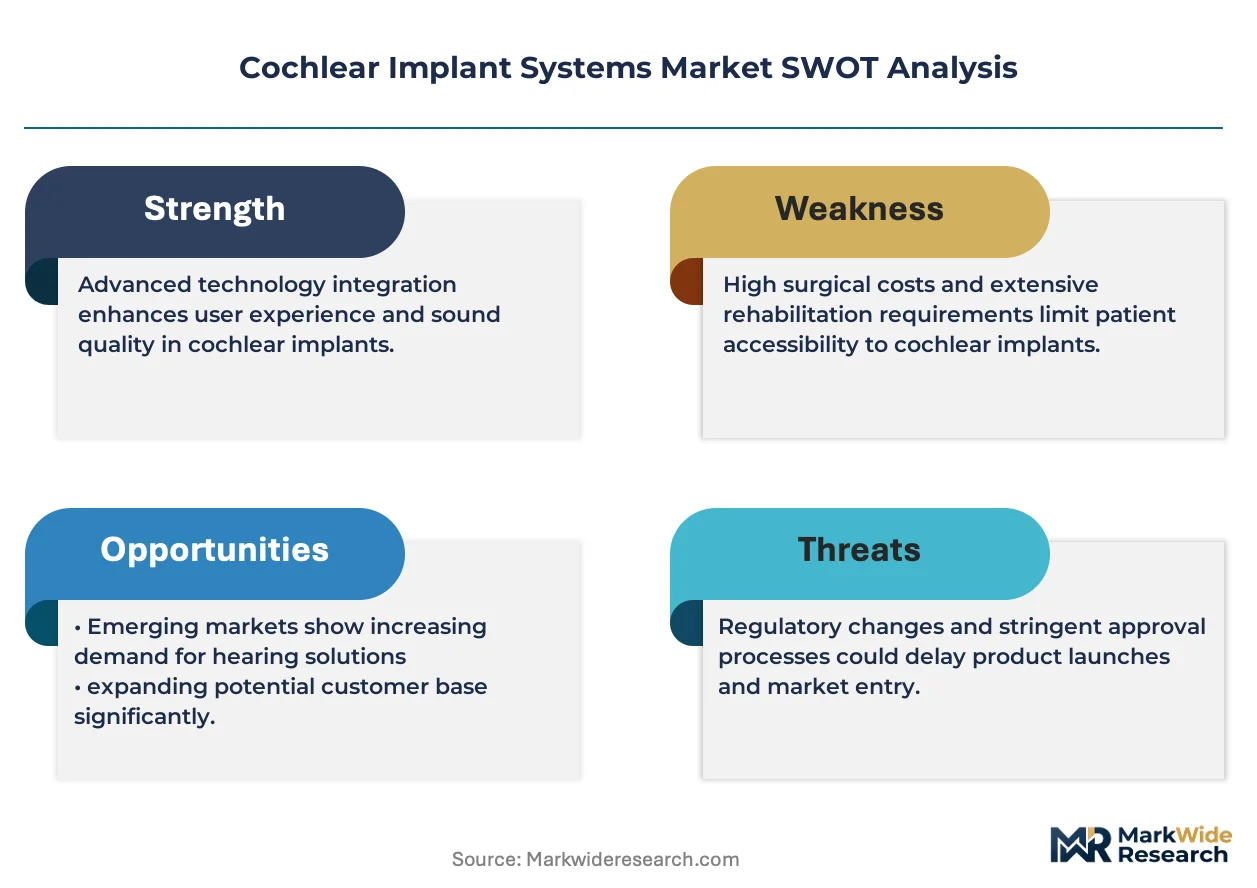
- Platinum-iridium electrode material costs:Precious metal price volatility in the supply chain compresses gross margins on internal receiver-stimulator components.
- Single-source dependency for magnet assemblies:Concentrated supply from specialized Swiss and German precision manufacturers creates vulnerability to regional production disruptions.
- FDA premarket approval timelines:Extended review cycles for novel electrode configurations delay commercialization of next-generation devices by 18-36 months versus European CE marking.
Strategic Opportunities
- China's NMPA innovative device pathway:Accelerated review timelines for breakthrough neuroprosthetics are opening first-mover advantages in tier-one hospital networks.
- Tele-audiology fitting protocols:Remote programming capabilities are enabling service delivery expansion into secondary cities lacking specialized implant centers.
- Hybrid electro-acoustic systems:Convergence of traditional amplification with electrical stimulation is capturing the moderate-to-severe segment previously excluded from candidacy.
Industry Challenges
- Auditory-verbal therapist certification bottlenecks:Post-implant rehabilitation capacity constraints in Brazil and Mexico limit effective device utilization despite surgical access.
- Legacy sound processor backward compatibility:Maintaining firmware support across multi-generational internal implants fragments R&D resources and complicates inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cochlear Implant Systems Market |
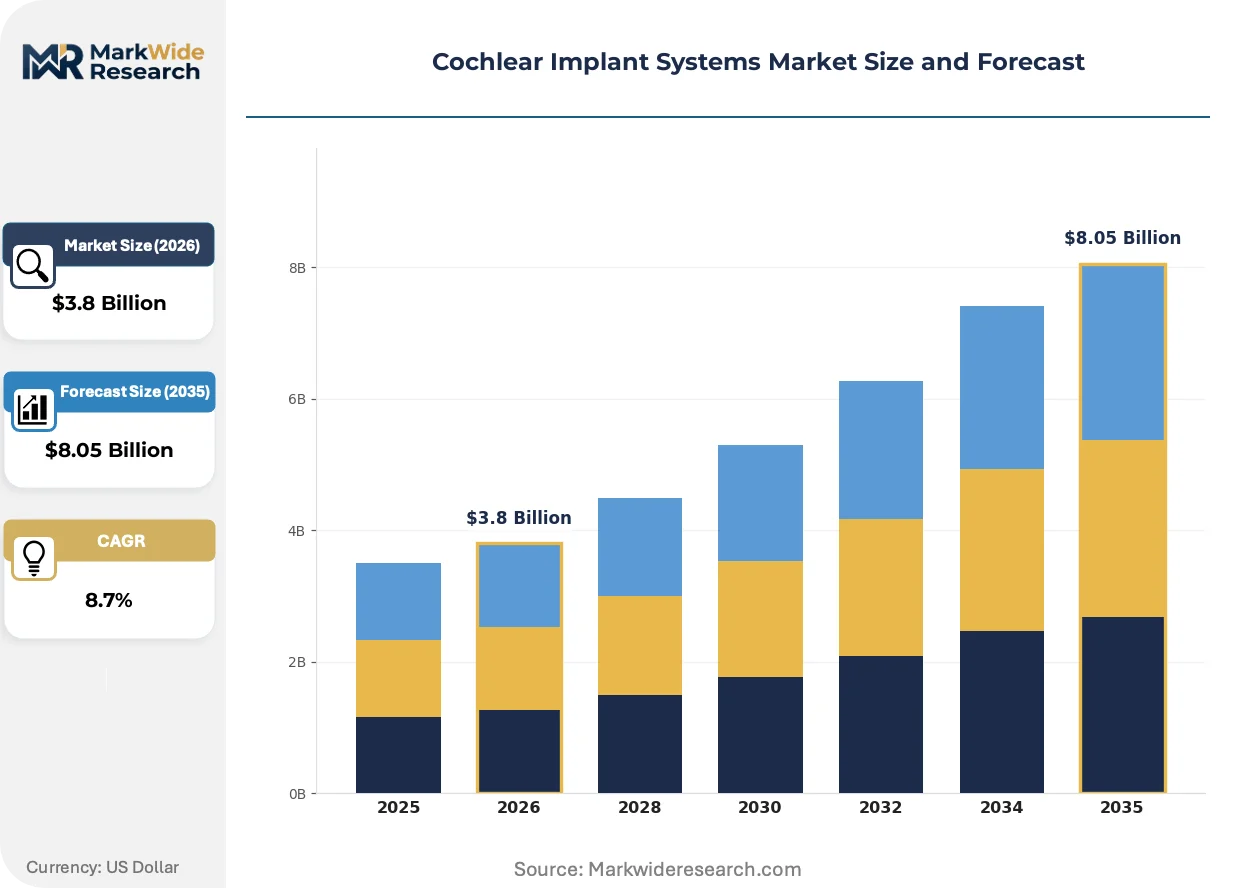
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cochlear Implants, Bone Anchored Hearing Aids, Hybrid Cochlear Implants, Accessories End User: Hospitals, ENT Clinics, Rehabilitation Centers, Home Care Settings Technology: Analog, Digital, Wireless, Cochlear Implant Software Age Group: Pediatrics, Adolescents, Adults, Seniors |
| Companies Covered | Cochlear Limited, Sonova Holding AG, MED-EL Medical Electronics, Demant A/S, Zhejiang Nurotron Biotechnology Co., Ltd., Amplifon S.p.A., Advanced Bionics, GN Store Nord A/S, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cochlear Implant Systems Market Emerging Trajectories
Signal processing architectures are converging with consumer audio platforms while regulatory data requirements intensify. These forces are compressing product lifecycles and elevating software capabilities over hardware iteration.
Artificial intelligence-driven scene classification is unifying environmental sound processing with speech enhancement in next-generation external processors. Pediatric implant centers in the United States are piloting these systems for classroom noise reduction. This convergence is compressing the traditional gap between research-lab algorithms and clinical deployment timelines.
The EU MDR's strengthened clinical evidence requirements for active implantable devices are extending post-market study obligations to 10-15 year follow-up protocols. Manufacturers must now integrate prospective registry infrastructure into commercial operations. Pediatric cohorts in Germany and France face the most stringent surveillance mandates, driving consolidation of investigator sites.
Hospital networks are consolidating procurement decisions across multi-site ENT service lines, displacing individual surgeon preference in device selection. Regional health systems in the United States now mandate standardized sound processor platforms to streamline audiology staffing. This concentration is most visible in the Midwest and Southeast, where Catholic health system mergers have reduced vendor access points by 40 percent in select metropolitan markets.
Cochlear Implant Systems Market Segmentation
Device replacement cycles and upgrade pathways determine revenue predictability across this neuroprosthetic market. Patient candidacy expansion and reimbursement tiering create divergent growth profiles within each segment dimension.
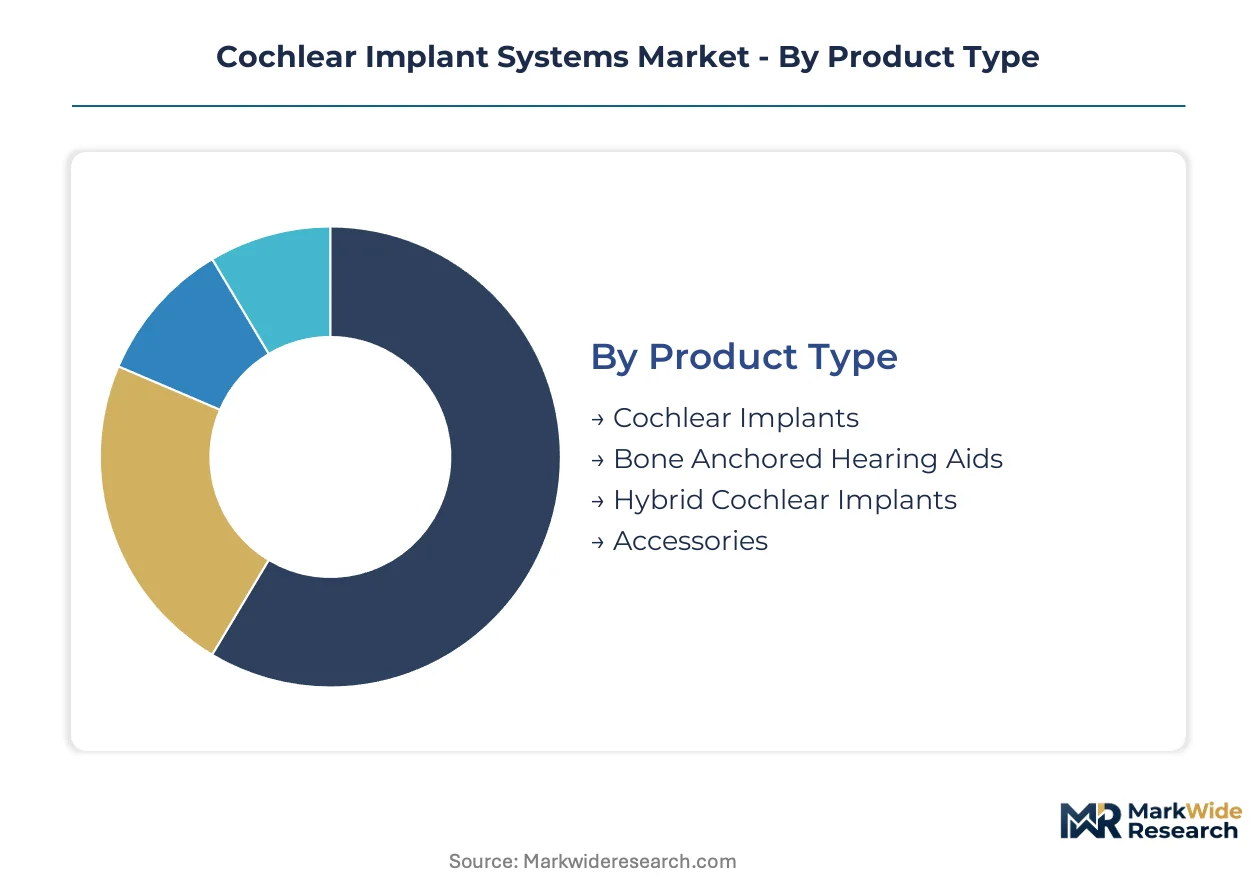
Product Type:
Upgrade cycles vary dramatically across implantable versus external components, with internal devices requiring surgical revision and external processors enabling non-invasive replacement.
- Cochlear Implants:These surgically implanted systems comprise an internal receiver-stimulator and electrode array paired with an external speech processor. Demand concentrates in pediatric hospital networks across the United States and Germany, driven by universal newborn hearing screening mandates that compress diagnosis-to-surgery intervals.
- Bone Anchored Hearing Aids:Percutaneous osseointegrated devices bypass the middle ear to transmit sound via bone conduction. ENT clinics in Scandinavia and the United Kingdom absorb disproportionate volume, constrained by narrower candidacy criteria limiting addressable patient pools relative to conventional implants.
- Hybrid Cochlear Implants:Electro-acoustic systems preserving residual acoustic hearing through combined amplification and electrical stimulation.
- Accessories:External components including rechargeable batteries, wireless streaming adapters, and protective cases.
Volume placements concentrate in Cochlear Implants; the faster expansion belongs to Hybrid Cochlear Implants.
End User:
Procurement authority is consolidating as health system mergers centralize purchasing decisions across dispersed clinical sites.
- Hospitals:Academic medical centers and children's hospitals dominate complex pediatric implantation. Surgical margins here depend on bundled reimbursement rates negotiated with commercial payers in the United States and statutory health insurers in Germany.
- ENT Clinics:Outpatient facilities handle initial candidacy assessment, device fitting, and longitudinal audiological management. These settings in Australia and the Netherlands are piloting remote programming protocols that reduce patient travel burden.
- Rehabilitation Centers:Dedicated auditory-verbal therapy facilities managing post-implant habilitation.
- Home Care Settings:Emerging service delivery model for processor maintenance and tele-audiology follow-up.
Procurement volume tilts toward Hospitals; ENT Clinics are gaining share fastest through outpatient migration.
Technology:
Software-enabled capabilities are displacing hardware iteration as the primary differentiation mechanism.
- Analog:Legacy signal processing architectures with limited programmability. Replacement demand persists in resource-constrained markets where procurement prioritizes capital efficiency over feature depth.
- Digital:Programmable sound processors with multiple stimulation strategies. These systems anchor current standard-of-care in Japan and South Korea, where reimbursement frameworks reward demonstrated speech perception outcomes.
- Wireless:Bluetooth-enabled connectivity with consumer audio devices and remote microphones.
- Cochlear Implant Software:Firmware platforms enabling algorithm updates without hardware replacement.
Installed base concentration remains with Digital; Wireless is climbing the fastest as connectivity becomes standard.
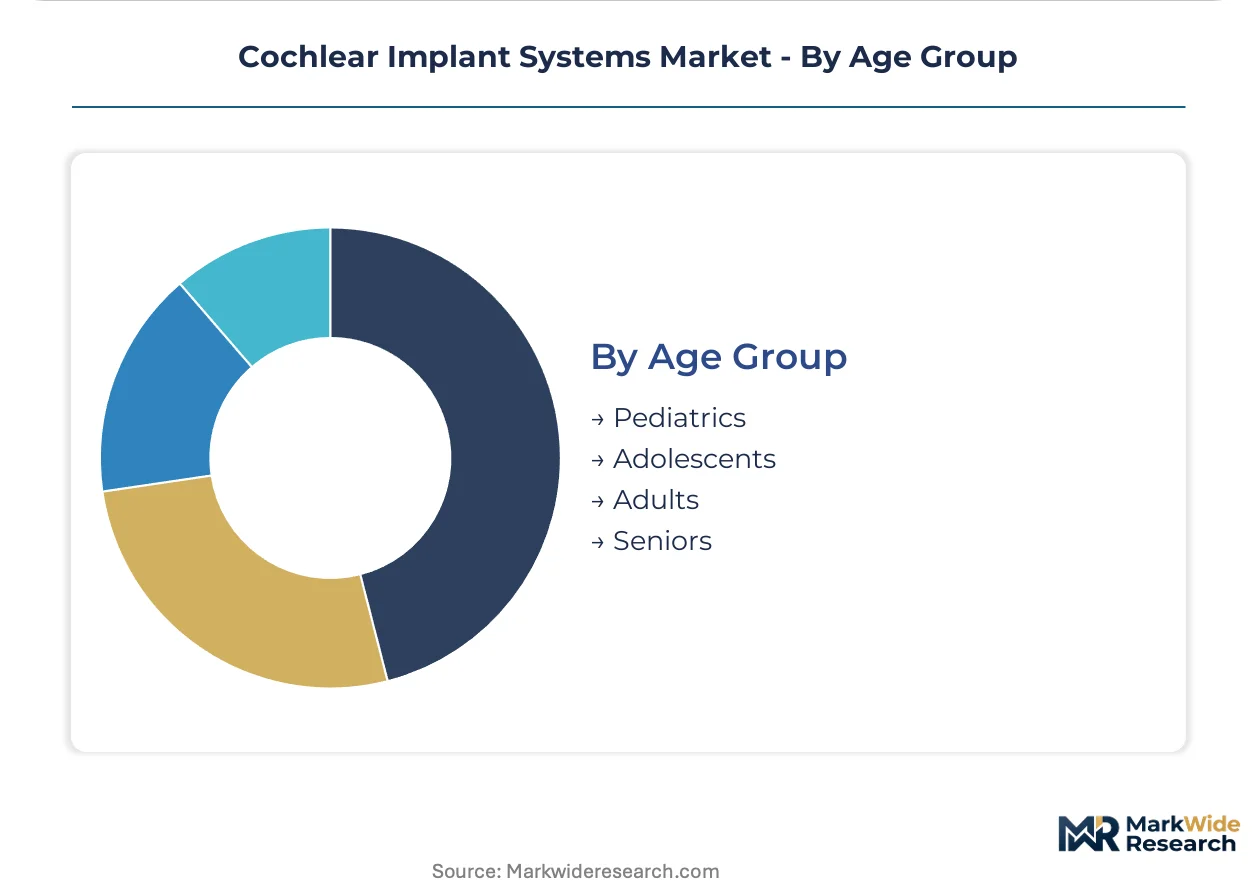
Age Group:
Developmental neuroplasticity windows and reimbursement age cutoffs create sharply divergent clinical pathways.
- Pediatrics:Candidates under 5 years of age requiring intervention before critical language acquisition periods close. Surgical volumes in the United States and Australia concentrate in specialized children's hospitals with dedicated cochlear implant teams.
- Adolescents:School-age patients transitioning from pediatric to adult service models. Educational accommodation requirements in Germany and France drive processor upgrade frequency in this cohort.
- Adults:Post-lingually deafened candidates with established language foundations.
- Seniors:Aging populations with progressive sensorineural decline.
Surgical access concentrates in Pediatrics; Seniors represent the steepest expansion trajectory as aging demographics broaden candidacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and China, where pediatric screening mandates and reimbursement expansion drive surgical volume. Hospital network consolidation and regulatory acceleration are reshaping access timelines across these core markets.
United States
Universal newborn hearing screening mandates in all 50 states compress diagnosis-to-surgery intervals, expanding the pediatric candidate pool. The FDA governs premarket approval through its Office of Ear, Nose, and Throat Devices, with extended review cycles for novel electrode configurations. Midwest and Southeast hospital networks have reduced vendor access points by 40 percent in select metropolitan markets through Catholic health system mergers.
Germany
Statutory health insurers anchor reimbursement for complex pediatric implantation at academic medical centers. The EU MDR imposes stricter clinical evidence requirements for active implantable devices under notified body oversight, extending post-market study obligations to 10-15 year follow-up protocols. Pediatric cohorts in Germany and France face the most stringent surveillance mandates, driving consolidation of investigator sites.
China
Tier-one hospital networks absorb disproportionate surgical volume as NMPA accelerates review pathways for innovative neuroprosthetics. China's national medical products regulator has reshaped market access timelines for multinational manufacturers seeking first-mover positioning. Tele-audiology fitting protocols are enabling service delivery expansion into secondary cities lacking specialized implant centers.
Australia
Specialized children's hospitals with dedicated cochlear implant teams dominate surgical placement. The Therapeutic Goods Administration maintains alignment with international standards while enabling faster adoption of firmware-enabled upgrades. Outpatient ENT clinics in Sydney and Melbourne pilot remote programming protocols that reduce patient travel burden.
Switzerland
Precision manufacturers concentrate supply of magnet assemblies for internal receiver-stimulator components. Swissmedic oversees post-market surveillance with particular attention to precious metal supply chain integrity. Regional production disruptions in specialized German and Swiss facilities create vulnerability points for global device assembly.
Cochlear Implant Systems Market Vendor Landscape
Australian and Austrian producers anchor one tier; Danish and American specialists hold differentiated positions in sound processing and distribution architecture. The vendor base clusters around three strategic archetypes: integrated electrode manufacturers, direct-distribution hearing center operators, and software-centric platform developers. M&A activity concentrates on audiology service network acquisition, while capacity expansion targets electrode array miniaturization and thin-film manufacturing.
Within the integrated manufacturing tier, Cochlear Limited exemplifies captive supply chain control through in-house electrode production. MED-EL Medical Electronics anchors direct distribution capabilities across European hearing centers. Advanced Bionics occupies a position emphasizing software-enabled differentiation in external processor platforms.
| Leading Market Players |
|---|
| Cochlear Limited |
| Sonova Holding AG |
| MED-EL Medical Electronics |
| Demant A/S |
| Zhejiang Nurotron Biotechnology Co., Ltd. |
| Amplifon S.p.A. |
| Advanced Bionics |
| GN Store Nord A/S |
| Medtronic plc |
| Others |
Supply Flow & Price Mechanics
Thin-film electrode manufacturing advances are compressing production costs for internal receiver-stimulator arrays while concentrating supply among specialized Swiss and German precision manufacturers. This dual effect tightens margin structures for device assemblers dependent on single-source magnet assemblies while rewarding captive electrode production capabilities.
Pricing Analysis
Volume placements concentrate in pediatric hospital networks where bundled reimbursement rates compress per-unit margins, while upgrade cycles for external sound processors sustain premium pricing in the outpatient ENT clinic channel. Price differentiation hinges on FDA premarket approval tier and residual hearing preservation capability, with hybrid electro-acoustic systems commanding higher positioning. Pricing pressure stems from platinum-iridium electrode material cost volatility, which squeezes gross margins on internal components. Pediatric ENT clinics exhibit highest price sensitivity due to constrained public reimbursement frameworks, whereas academic medical centers absorb premium tiers through statutory insurance anchoring in Germany.
Supply Chain Analysis
Reverse-logistics flows for sound processor refurbishment and battery recycling are emerging as cost centers, with manufacturers reclaiming value from trade-in programs for legacy device compatibility support. Component supply concentrates in Switzerland, Germany, and China, with precision magnet assemblies drawing from Alpine manufacturing clusters and electrode arrays sourcing from East Asian thin-film facilities. Raw material dependencies span platinum-iridium alloys, titanium casings, and rare-earth magnets. Single-source vulnerability in Swiss magnet production creates exposure to regional disruption. Distribution runs through direct hospital procurement in consolidated US networks and specialized European hearing center partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with electrode manufacturing and audiology service networks representing the critical upstream and downstream levers that determine margin capture.
For Market Incumbents: To counter NMPA-accelerated entry by Chinese manufacturers, secure captive supply of thin-film electrode arrays through backward integration into precision manufacturing or long-term offtake agreements with Swiss component suppliers. Simultaneously consolidate audiology service networks to lock in fitting and rehabilitation revenue streams that hardware margins alone cannot sustain. For New Entrants and Emerging Players: Tele-audiology platforms offer the most penetrable route into secondary cities lacking specialized implant centers, particularly in China's tier-two hospital networks and Brazil's rehabilitation-deficient markets. Target the senior segment with simplified fitting protocols and remote programming capabilities. Partner with existing ENT clinic chains rather than building de novo surgical capacity. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid electro-acoustic specialists given expanding candidacy into moderate-to-severe hearing loss and reimbursement tiering that rewards residual hearing preservation. Long-term viability over a five-to-ten year window depends on software-enabled upgrade pathways that decouple revenue from surgical revision cycles. Monitor NMPA approval timelines for multinational manufacturers as an inflection signal for competitive positioning shifts in China's tier-one hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| Electrode Array Miniaturization | Thin-film manufacturing investments in Germany and Switzerland preserve residual hearing and expand hybrid candidacy pools. |
| Tele-audiology Platform Deployment | Remote programming capabilities in Australian and Chinese ENT clinics reduce patient travel burden and capture secondary city volume. |
| EU MDR Clinical Evidence Infrastructure | Prospective registry investments across German and French pediatric cohorts satisfy ten-to-fifteen year surveillance mandates. |
| Hospital System Partnership Consolidation | Standardized sound processor platforms in Midwest and Southeast US Catholic health networks streamline audiology staffing. |
| NMPA Innovative Device Pathway Navigation | Accelerated review timelines for breakthrough neuroprosthetics reshape market access for multinational manufacturers in China. |
Methodological Framework
Document review covered FDA premarket approval filings, EU MDR notified body guidance, NMPA neuroprosthetic registration databases, and hospital procurement contract disclosures, complemented by interviews with cochlear implant surgeons, audiology department heads, biomedical engineers at children's hospitals, GPO contracts managers, and reimbursement specialists at statutory health insurers. Secondary validation drew from CMS Medicare claims data, German hospital reimbursement schedules, and Chinese tier-one hospital surgical volume records. Bottom-up and top-down triangulation reconciled device placement estimates with audiology service capacity assessments.
Cross-referencing historical placement trends against expert panel input on screening mandate expansion and reimbursement coding shifts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user procurement authority, technology architecture, and age group developmental windows. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions for internal versus external components. Industry-specific inputs incorporated newborn hearing screening penetration rates and auditory-verbal therapist certification bottlenecks.
The model holds under stable reimbursement coding and screening mandate continuity; deviation in NMPA regulatory acceleration or EU MDR surveillance burden expansion would shift volume trajectories across geographies. Practitioners should monitor platinum-iridium commodity price indices and Catholic health system merger announcements for early signals of margin compression and vendor access point reduction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Global Pacemakers Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Global Wearable Skin Patch Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market