
 Cold Disposable Biopsy Forceps Market | 2026-2036
Cold Disposable Biopsy Forceps Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Disposable Biopsy Forceps Market Outlook
Disposable instrument servicing and compliance bundling is repositioning how procurement teams evaluate total cost of ownership in endoscopy suites. Cook Medical leverages its vertically integrated sterilization-free supply chain to anchor hospital group purchasing contracts across North American networks. Olympus Corporation competes through endoscope-forceps ecosystem lock-in, while Boston Scientific differentiates via procedure-specific jaw configurations for pulmonology applications.
Cold disposable biopsy forceps are single-use grasping instruments manufactured from medical-grade stainless steel or polymer composites with alligator-cup or oval jaw designs, typically ranging from 1.0 mm to 2.4 mm in working channel diameter, intended for retrieving tissue specimens during flexible endoscopy without electrocautery capability. Rotatable configurations command premium positioning due to the technical complexity of helical shaft engineering and the procedural efficiency gains they deliver in retroflexed gastric examinations. Straight jaw variants dominate high-volume screening programs where cost per procedure drives purchasing decisions, while coated materials are gaining traction as manufacturers respond to biocompatibility testing requirements under evolving sterilization assurance frameworks.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence thresholds for market entry, with notified bodies demanding enhanced biocompatibility documentation for polymer-based alternatives. The EPA's medical waste incineration standards influence material selection as manufacturers seek to reduce halogenated byproducts from disposal. Stakeholders must monitor how reimbursement coding for disposable versus reusable instruments evolves across Medicare and commercial payers, as this determines conversion economics for hospital systems weighing capital avoidance against per-procedure supply costs.
Market Dynamics
The Cold Disposable Biopsy Forceps Market pivots on infection control mandates tightening across ambulatory surgical networks, with single-use instrument conversion accelerating as reprocessing liability costs mount for hospital systems managing flexible endoscopy workflows.
Growth Catalysts
- FDA Reprocessing Guidance:Updated sterilization assurance protocols for flexible endoscopes are forcing facilities toward disposable alternatives that eliminate cross-contamination risk documentation burdens.
- Ambulatory Surgical Center Expansion:United States outpatient facilities are converting to fully disposable biopsy workflows to minimize capital equipment sterilization infrastructure.
- Polymer Composite Materials:Advanced medical-grade polymer alternatives to stainless steel are reducing manufacturing costs while meeting biocompatibility testing requirements under evolving frameworks.
Market Restraints
- Medical-Grade Stainless Steel Volatility:Raw material price swings for surgical-grade alloys compress margins for manufacturers maintaining competitive per-unit pricing against polymer entrants.
- EPA Incineration Standards:Halogenated byproduct restrictions from medical waste disposal are constraining material selection flexibility and increasing compliance engineering costs.
- Reusable Forceps Durability:High-cycle stainless steel instruments retain cost-per-procedure advantages in high-volume screening programs where capital depreciation models favor multi-use devices.
Strategic Opportunities
- Pulmonology Application Expansion:Bronchoscopy suites represent underpenetrated demand for procedure-specific jaw configurations optimized for transbronchial lung biopsies.
- Rotatable Configuration Premiumization:Helical shaft engineering complexity creates defensible margin pools in retroflexed gastric examination workflows where procedural efficiency commands price tolerance.
- Medicare Reimbursement Recoding:Shifting disposable instrument coding structures could convert hospital system economics from capital avoidance toward supply-cost acceptance.
Industry Challenges
- EU MDR Biocompatibility Documentation:Notified bodies demand enhanced polymer-based alternative testing protocols, extending product development timelines and clinical evidence thresholds.
- Helical Shaft Engineering Talent:Rotatable configuration manufacturing requires specialized precision engineering capabilities scarce in contract manufacturing networks serving medical device OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Disposable Biopsy Forceps Market |
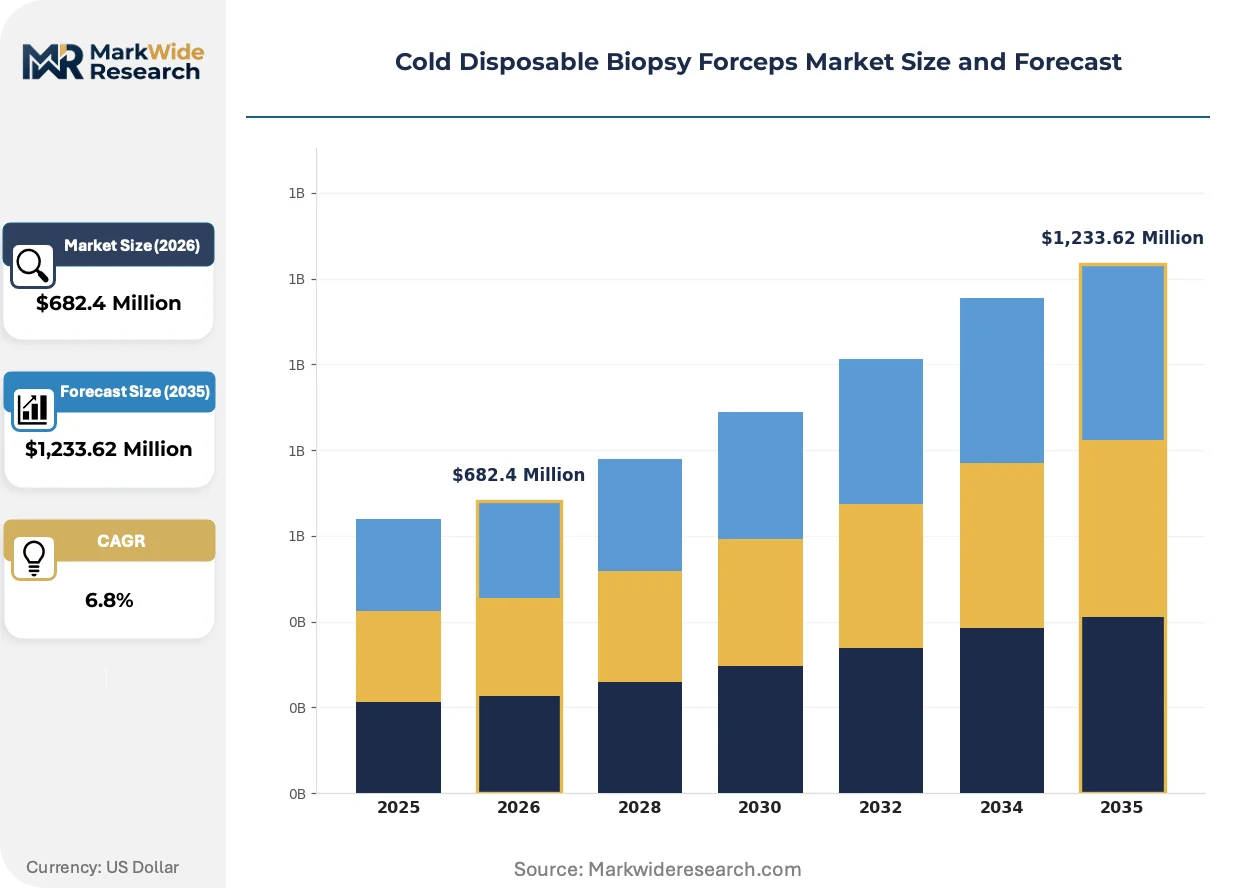
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,233.62 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight, Curved, Rotatable, Triple Action Application: Endoscopic Procedures, Surgical Biopsies, Diagnostic Tests, Research Material: Stainless Steel, Polymer, Coated Materials, Biodegradable Components End User: Hospitals, Diagnostic Laboratories, Research Facilities, Ambulatory Surgical Centers |
| Companies Covered | Cook Medical, Micro-Tech, Olympus Corporation, Medi-Globe GmbH, PENTAX Medical, Boston Scientific, ConMed, Medline Industries, KARL STORZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Disposable Biopsy Forceps Market Strategic Shifts
Material science convergence with regulatory pressure is compressing traditional stainless steel dominance while procurement models in United States ambulatory networks accelerate single-use conversion timelines.
Polymer composite biopsy forceps are consolidating position in cost-sensitive screening programs where per-procedure economics dominate purchasing decisions. Gastroenterology departments in United States hospital systems are adopting polymer variants at accelerating pace as sterilization assurance documentation burdens mount. This material transition is consolidating manufacturing scale toward injection-molding specialists with medical-grade polymer certification capabilities, compressing traditional metal-forming equipment suppliers from high-volume contract opportunities.
EU Medical Device Regulation biocompatibility documentation requirements are reshaping polymer alternative development timelines and clinical evidence thresholds. Manufacturers face extended notified body review periods for polymer-based forceps requiring enhanced material characterization studies. Polymer composite product categories are absorbing disproportionate regulatory compliance investment as notified bodies apply stricter interpretation frameworks to single-use polymer instruments relative to established stainless steel predicates.
Hospital group purchasing organizations are centralizing disposable instrument procurement across integrated delivery networks, compressing vendor fragmentation that historically characterized endoscopy supply purchasing. Ambulatory surgical centers are consolidating purchasing decisions through national GPO contracts that bundle single-use forceps with endoscope servicing and compliance packages. United States integrated delivery networks are most visibly consolidating procurement authority, displacing individual facility purchasing autonomy with system-level standardization mandates.
Cold Disposable Biopsy Forceps Market Segmentation
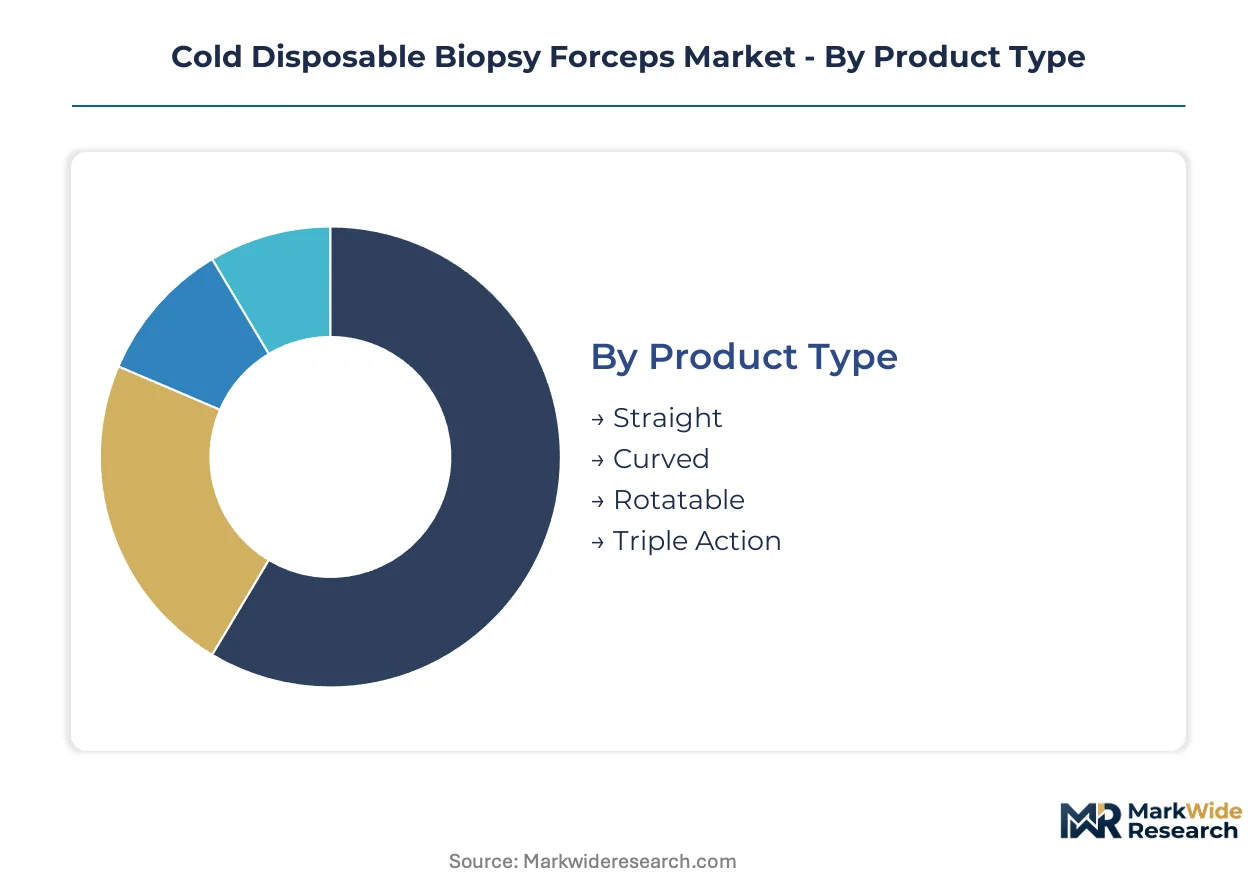
Segmentation in cold disposable biopsy forceps reveals how procurement economics, procedural requirements, and regulatory compliance intersect to reshape vendor positioning. Supply concentration varies dramatically across material and configuration categories, creating distinct margin architectures that manufacturers must navigate.
Product Type:
Supply concentration in helical shaft manufacturing concentrates premium pricing power among rotatable configurations, while straight variants anchor high-volume contract manufacturing networks.
- Straight:Fixed jaw geometry manufactured through conventional metal-forming or injection molding processes dominates high-volume screening programs where cost per procedure drives purchasing decisions. United States ambulatory surgical centers are consolidating procurement around straight configurations to minimize per-unit expenditure in colonoscopy workflows.
- Rotatable:Helical shaft engineering enables 360-degree jaw orientation control, commanding defensible margin pools in retroflexed gastric examinations where procedural efficiency justifies price tolerance. Helical shaft engineering talent scarcity constrains manufacturing expansion, limiting supplier entry and preserving incumbent positioning.
- Curved:Pre-angled jaw configurations address anatomical access challenges in duodenal and biliary procedures.
- Triple Action:Multi-mechanism jaw actuation systems serve specialized interventional pulmonology applications requiring simultaneous grasping, cutting, and retrieval functions.
Today's leader: Straight. Tomorrow's challenger: Rotatable.
Application:
Cost tier differentiation separates capital-intensive hospital workflows from lean ambulatory operations, with diagnostic applications absorbing disproportionate regulatory documentation burdens.
- Endoscopic Procedures:Flexible endoscopy suites in United States hospital systems are converting to fully disposable instrument workflows as FDA reprocessing guidance tightens sterilization assurance requirements. Gastroenterology departments are bundling single-use forceps with endoscope servicing contracts to transfer liability risk.
- Surgical Biopsies:Operating room integration demands higher jaw precision specifications and sterile packaging protocols that elevate per-unit costs above standard endoscopic variants. United States integrated delivery networks are standardizing surgical biopsy forceps procurement across system-level contracts.
- Diagnostic Tests:High-throughput pathology screening programs prioritize polymer alternatives to reduce per-specimen supply expenditure.
- Research:Academic medical centers and contract research organizations require specialized lot tracking and material certification documentation.
Endoscopic procedures command current volume leadership; surgical biopsies are climbing the fastest as OR disposable conversion accelerates.
Material:
Volume concentration in polymer injection molding is displacing traditional metal-forming equipment suppliers from high-volume contract opportunities.
- Stainless Steel:Surgical-grade alloy construction retains established biocompatibility documentation under FDA 510(k) pathways, preserving rapid market entry timelines. Raw material price volatility compresses margins for manufacturers maintaining competitive per-unit pricing against polymer alternatives.
- Polymer:Medical-grade polymer composites are consolidating position in cost-sensitive screening programs as sterilization assurance documentation burdens mount for stainless steel reprocessing. EU MDR biocompatibility documentation requirements extend notified body review periods for polymer alternatives.
- Coated Materials:Surface-modified substrates address friction reduction and tissue adhesion properties in specialized retrieval procedures.
- Biodegradable Components:Emerging material platforms target EPA medical waste incineration compliance by eliminating halogenated byproduct generation.
Stainless steel retains installed base dominance; polymer is gaining share fastest as ambulatory networks prioritize supply-cost economics over capital depreciation models.
End User:
Customer type fragmentation is compressing as United States hospital group purchasing organizations centralize procurement authority across integrated delivery networks.
- Hospitals:Gastroenterology departments are expanding single-use instrument procurement as infection control protocols tighten and reprocessing liability costs mount. System-level standardization mandates are displacing individual facility purchasing autonomy.
- Ambulatory Surgical Centers:United States outpatient facilities are converting to fully disposable biopsy workflows to minimize capital equipment sterilization infrastructure and maximize procedure throughput efficiency.
- Diagnostic Laboratories:Independent pathology operations prioritize straight jaw polymer variants for high-volume tissue acquisition.
- Research Facilities:Academic and commercial research organizations require specialized configurations with enhanced material traceability documentation.
Hospitals anchor current procurement volume; ambulatory surgical centers represent the steepest expansion trajectory as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as polymer injection-molding capacity migrates toward jurisdictions with streamlined medical-device approval pathways. Cost-of-compliance gaps between FDA 510(k) timelines and EU MDR notified-body review periods are influencing supplier location decisions.
United States
Ambulatory surgical centers in Texas and Florida are converting to fully disposable biopsy workflows as infection control liability costs mount. FDA updated reprocessing guidance for flexible endoscopes is forcing hospital systems toward single-use alternatives that eliminate cross-contamination documentation. The Minneapolis medical-device corridor anchors polymer forceps manufacturing scale as sterilization-free supply chains consolidate.
Germany
EU MDR biocompatibility documentation requirements are extending notified-body review periods for polymer-based alternatives entering the European market. German hospital group purchasing organizations are centralizing procurement authority across integrated delivery networks in Bavaria and North Rhine-Westphalia. The Baden-Württemberg precision engineering cluster retains helical shaft manufacturing capability for rotatable configurations.
China
NMPA medical device registration pathways are attracting polymer injection-molding investment from manufacturers seeking to serve cost-sensitive screening programs. Domestic demand concentrates in Yangtze River Delta gastroenterology departments expanding single-use instrument procurement. Shanghai-based contract manufacturers are scaling medical-grade polymer certification capabilities to capture export contract opportunities.
Japan
PMDA approval timelines for polymer alternatives remain conservative relative to stainless steel predicates, preserving incumbent metal-forming supplier positioning. Tokyo and Osaka hospital systems maintain preference for established biocompatibility documentation under traditional pathways. The Nagoya precision manufacturing belt continues supplying helical shaft components for rotatable forceps configurations.
India
CDSCO medical device rules are streamlining import pathways for disposable biopsy forceps serving diagnostic laboratory expansion in Maharashtra and Karnataka. Mumbai and Bengaluru pathology screening programs prioritize polymer variants to reduce per-specimen supply expenditure. Domestic contract manufacturers in Gujarat are developing medical-grade polymer molding capabilities for regional supply.
Cold Disposable Biopsy Forceps Market Competitive Environment
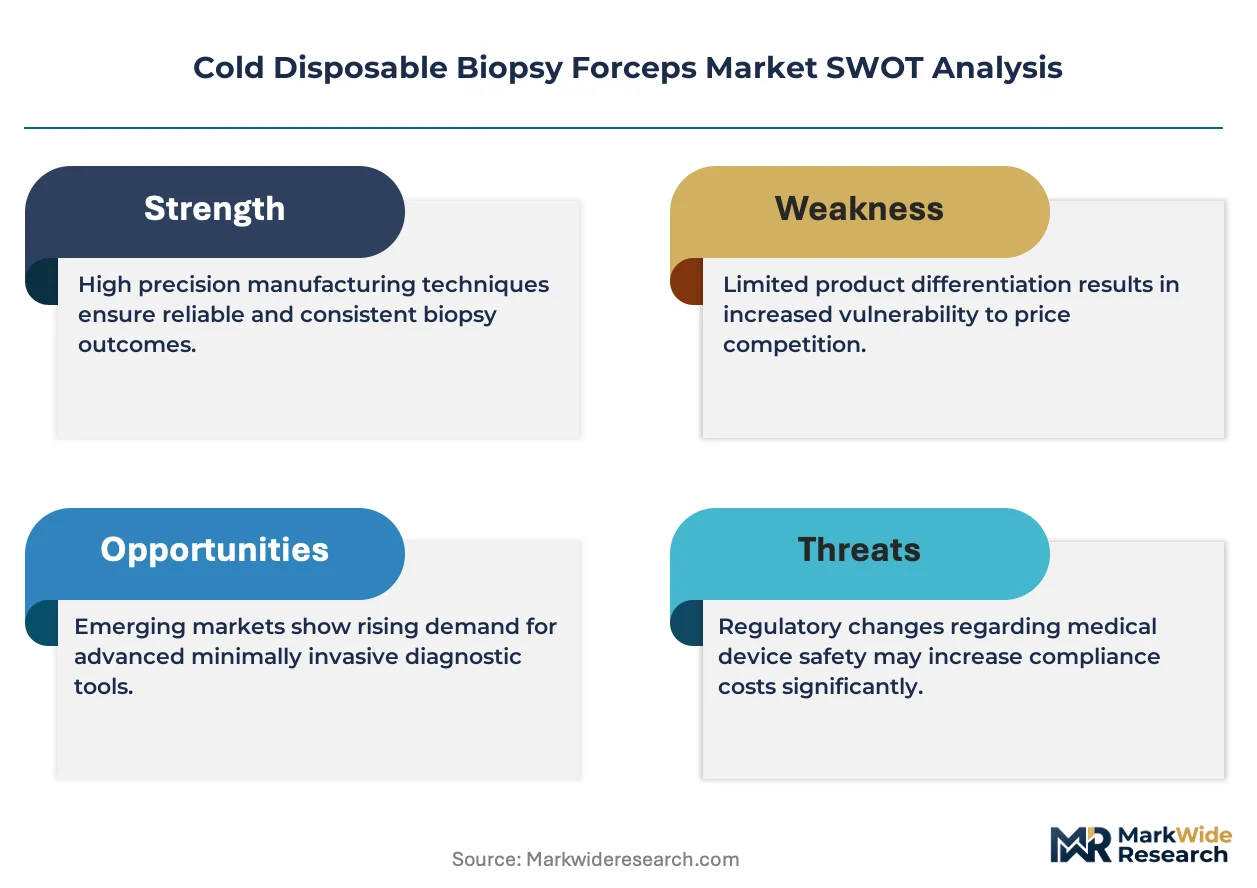
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated device companies commanding premium positioning in rotatable configurations while injection-molding specialists capture polymer straight-jaw volume. The vendor base concentrates around three strategic archetypes: sterilization-free supply chain integrators, endoscope-forceps ecosystem lock-in providers, and procedure-specific jaw configuration specialists. Dominant competitive moves include backward integration into polymer compounding capabilities and strategic partnerships with group purchasing organizations for ambulatory network access.
Among North American-based device companies, Cook Medical and Boston Scientific exemplify divergent archetype positioning, with the former representing sterilization-free supply chain integration and the latter occupying the procedure-specific specialization tier. Olympus Corporation anchors the endoscope-forceps ecosystem lock-in archetype among Asia-Pacific headquartered competitors. These three companies sit within distinct competitive vectors that shape how procurement teams evaluate total cost of ownership across hospital and ambulatory settings.
| Leading Market Players |
|---|
| Cook Medical |
| Micro-Tech |
| Olympus Corporation |
| Medi-Globe GmbH |
| PENTAX Medical |
| Boston Scientific |
| ConMed |
| Medline Industries |
| KARL STORZ |
| Others |
Value Chain & Pricing Dynamics
Rotatable versus straight jaw configuration bifurcation creates divergent margin architectures that reshape both procurement negotiations and manufacturing footprint decisions across the cold disposable biopsy forceps market. Premium helical shaft engineering commands three-tier pricing stratification across premium, standard, and economy levels, while polymer injection-molding scale economies compress per-unit costs in high-volume screening segments.
Pricing Analysis
Distributor margin layers absorb 15-25 points between OEM factory pricing and hospital system procurement, with direct-to-OEM discounts reserved for integrated delivery networks consolidating annual volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates rotatable configurations with helical shaft complexity from straight polymer variants and commodity stainless steel alternatives. Cost compression in polymer straight-jaw segments is intensifying because medical-grade resin suppliers are expanding compounding capacity in the United States and China. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers purchasing rotatable configurations for retroflexed gastric procedures demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States integrated delivery networks, while regional distributors serve fragmented diagnostic laboratory segments. Manufacturing gravity centers on the Minneapolis medical-device corridor for polymer compounding and helical shaft assembly, with injection-molding scale expanding in Shanghai and Stuttgart. Raw material feeds draw from surgical-grade stainless steel mills in Germany and Japan, medical-grade polymer resin suppliers in the United States and South Korea, and precision coil spring manufacturers in Switzerland. Single-source vulnerability concentrates in helical shaft engineering talent pools, constraining rotatable configuration expansion. Distribution runs through hospital group purchasing organization contracts bundling forceps with endoscope servicing compliance packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold disposable biopsy forceps market functions as a stable compounder anchored by irreversible infection control protocol tightening across ambulatory surgical networks. FDA reprocessing guidance for flexible endoscopes creates durable conversion economics favoring single-use instruments over reusable alternatives.
For Market Incumbents: Deepen backward integration into medical-grade polymer compounding to defend margin position against resin price volatility and secure supply assurance for high-volume GPO contracts. Anchor hospital system partnerships through bundling single-use forceps with endoscope servicing liability transfer, while accelerating helical shaft engineering capacity in Baden-Württemberg to capture rotatable configuration premium pools before contract manufacturers develop comparable precision capabilities. For New Entrants and Emerging Players: Enter via pulmonology application specialization, where procedure-specific jaw configurations for transbronchial lung biopsies remain underpenetrated relative to saturated gastroenterology segments. Target bronchoscopy suites in United States ambulatory surgical centers converting to disposable workflows, leveraging polymer straight-jaw cost advantages to displace stainless steel incumbents in high-volume screening programs through aggressive GPO contract bidding. For Investors and Strategic Acquirers: Consolidation pressure builds where helical shaft engineering talent scarcity constrains manufacturing expansion and preserves incumbent pricing power in rotatable configurations. Five-to-ten year viability favors sterilization-free supply chain integrators with captive polymer molding capabilities and established GPO contract relationships. Monitor Medicare reimbursement recoding proposals as the critical inflection signal determining whether hospital system economics shift decisively toward supply-cost acceptance from capital avoidance models.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for polymer alternatives against established stainless steel predicates under streamlined review. |
| Hospital System Partnership | Locks in multi-year GPO contracts bundling forceps with endoscope servicing across integrated delivery networks. |
| CE Marking Pathway | Navigates EU MDR biocompatibility documentation requirements for polymer-based forceps entering European markets. |
| Backward Integration into Polymer Compounding | Captures margin pool from medical-grade resin suppliers and secures supply assurance for high-volume manufacturing. |
| Reimbursement Strategy | Aligns disposable instrument coding structures with Medicare and commercial payer evolution to convert hospital procurement economics. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and endoscopy suite clinicians with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up demand modeling across ambulatory surgical center conversion rates and top-down supply-side capacity assessments were triangulated to produce segment-level estimates.
Segment-weighting approaches applied differential growth assumptions across material categories, product configurations, and end-user archetypes throughout the forecast period. The analytical framework incorporated procedure volume trajectories, infection control protocol adoption curves, and polymer versus stainless steel substitution elasticities. CAGRs were derived from logarithmic trend fitting across annual interval projections, with sensitivity testing around FDA guidance implementation timing and EU MDR review period variability.
The model holds under stable regulatory enforcement trajectories and continued ambulatory surgical center expansion; deviation in Medicare reimbursement recoding decisions or helical shaft engineering talent availability would shift volume and value outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Hysteroscopy Instruments Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Global Surgical Instrument Tracking System Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Equine Surgical Equipment Market
Surgical Instruments
Surgical Lamps Market