
 Pulmonary Stents Market | 2026-2036
Pulmonary Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Stents Market Analytics
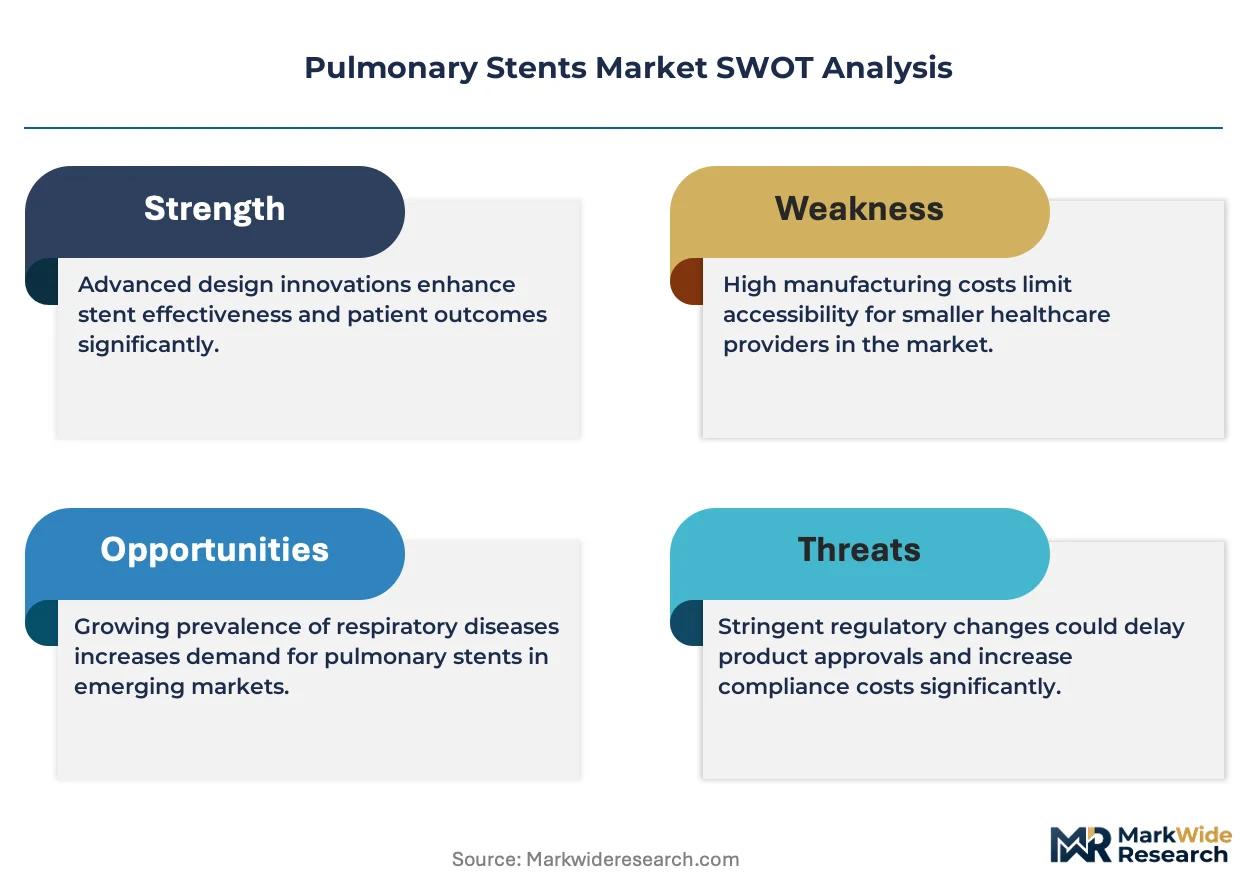
The Pulmonary Stents Market is recalibrating around a widening gap between premium nitinol-based self-expandable systems and commodity metal stents for basic airway obstruction. Boston Scientific Corporation leverages its interventional pulmonology portfolio to sustain dominance in complex malignant airway cases. Cook Group anchors its position through backward integration into nitinol wire production and specialized delivery catheter manufacturing. Merit Medical Systems, Inc. competes by extending its peripheral interventional expertise into bronchial applications with customized sizing platforms.
Pulmonary stents are implantable tubular devices, typically constructed from nitinol or stainless steel alloys with diameters ranging from 6 to 16 millimeters, designed to restore patency in stenotic tracheobronchial passages compromised by malignancy, inflammation, or post-surgical stricture. Self-expandable nitinol stents dominate procedural volumes due to superelastic recovery and conformability to irregular airway anatomy, while drug-eluting variants capture disproportionate margin pools through sustained local pharmacologic action against granulation tissue. Balloon-expandable platforms occupy a narrower niche in rigid proximal tracheal segments where precise diameter control matters, whereas polymer biodegradable options remain experimental outside research institutions.
FDA breakthrough device designation and EMA conditional approval pathways shape competitive timelines by compressing regulatory review for stents addressing life-threatening central airway obstruction. ISO 25539-2 cardiovascular implant standards and ASTM F2063 nitinol composition specifications govern material biocompatibility and fatigue resistance testing protocols that manufacturers must satisfy before commercial access. Stakeholders should monitor how reimbursement authorities in Germany, Japan, and the United States classify complex bronchoscopic stenting relative to surgical alternatives, as coding decisions will determine procedural economics and physician adoption curves.
Market Dynamics
The pulmonary stents market is bifurcating around nitinol self-expandable platforms versus commodity metal alternatives, with interventional pulmonology departments in tertiary hospitals driving procedural migration from open surgery toward minimally invasive airway restoration.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's accelerated review pathway compresses clinical validation timelines for novel stent architectures addressing life-threatening central airway obstruction, reducing time-to-market for innovators.
- Interventional Pulmonology Expansion:Tertiary hospitals across the United States, Germany, and China are establishing dedicated bronchoscopy suites with advanced imaging infrastructure to support complex malignant airway cases.
- Superelastic Nitinol Recovery:Self-expandable nitinol stents with shape-memory properties enable conformability to irregular tracheobronchial anatomy, expanding addressable patient populations beyond rigid proximal segments.
Market Restraints
- Nitinol Raw Material Concentration:Supply of nickel-titanium alloy wire concentrates among a limited set of specialized metallurgical suppliers, creating input cost volatility and qualification bottlenecks for stent manufacturers.
- Reimbursement Coding Uncertainty:Complex bronchoscopic stenting procedures lack standardized reimbursement classifications relative to surgical alternatives in Germany, Japan, and the United States, compressing physician economics.
- Granulation Tissue Formation:Metal stents provoke reactive tissue proliferation requiring repeat interventions, limiting long-term patency and driving preference toward drug-eluting alternatives with sustained local pharmacologic action.
Strategic Opportunities
- Drug-Eluting Platform Expansion:Sustained-release pharmacologic coatings targeting granulation tissue represent disproportionate margin capture opportunities as interventional pulmonologists seek reduced revision rates.
- Biodegradable Polymer Development:Experimental absorbable stent platforms outside research institutions offer temporary scaffolding without permanent foreign body complications, pending clinical validation.
- Specialized Delivery Catheter Manufacturing:Backward integration into precision catheter production enables customized sizing platforms and procedural workflow optimization for complex airway anatomies.
Industry Challenges
- Interventional Pulmonology Training Pipeline:Specialized bronchoscopic stenting requires advanced fellowship training in malignant airway management, creating capability scarcity relative to procedural volume growth.
- ISO 25539-2 Fatigue Testing Compliance:Cardiovascular implant standards mandate extensive biocompatibility and fatigue resistance validation, extending certification timelines and capital requirements for nitinol stent commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Stents Market |
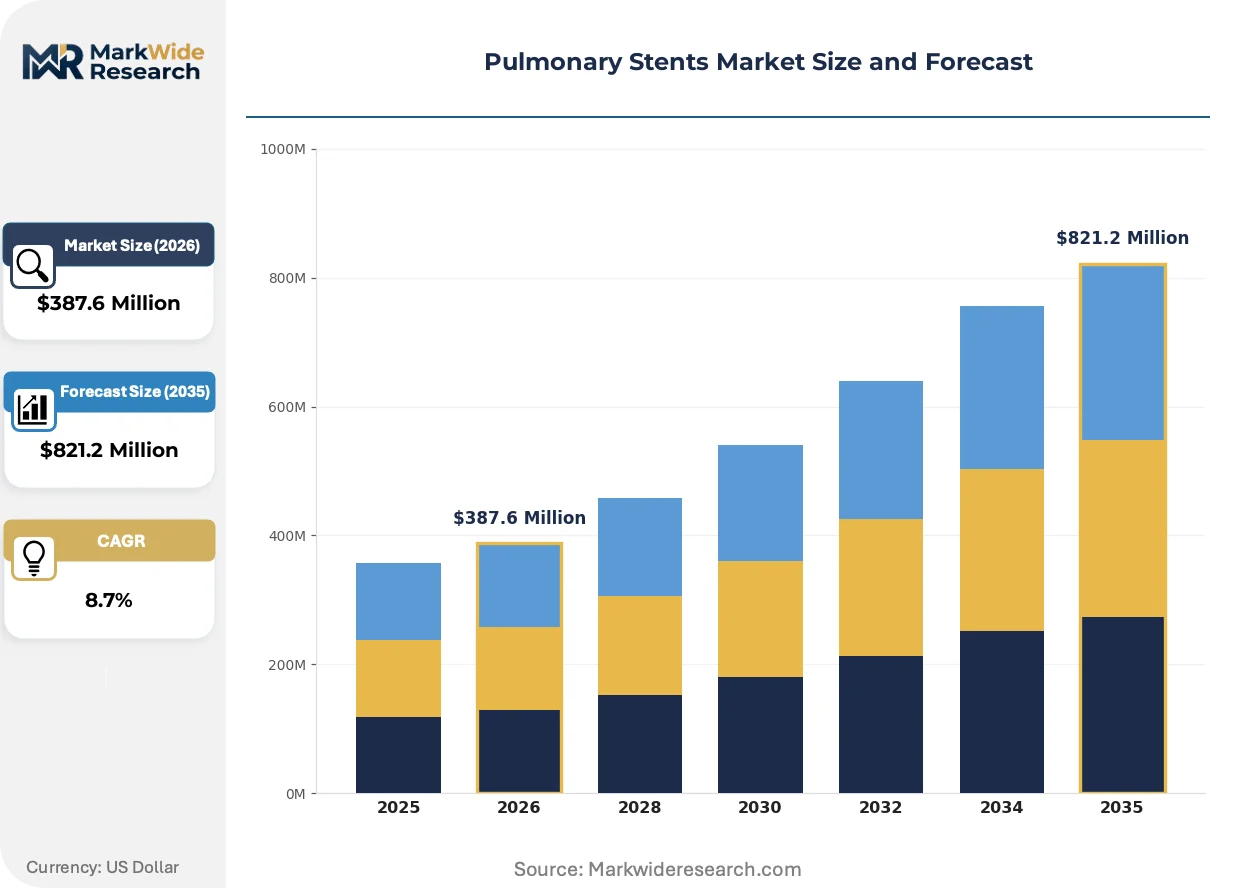
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expandable, Balloon-Expandable, Drug-Eluting, Metal End User: Hospitals, Specialty Clinics, Outpatient Surgical Centers, Research Institutions Material: Stainless Steel, Polymer, Nitinol, Coated Materials Deployment Technique: Endobronchial, Radiologic, Bronchoscopy, Surgical |
| Companies Covered | Boston Scientific Corporation, Novatech SA, Cook Group, Taewoong Medical Co., Ltd., Merit Medical Systems, Inc., Micro-Tech (Nanjing) Co., Ltd., ENDO-FLEX GmbH, E. Benson Hood Laboratories, Inc., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Stents Market Evolving Landscape
Material science advances and regulatory pathway adaptations are compressing development cycles while reshaping competitive positioning around pharmacologic integration and biodegradable alternatives.
Nitinol self-expandable stent technology is consolidating procedural preference across malignant and benign airway obstruction cases. Interventional pulmonology departments in tertiary hospitals are adopting these platforms at accelerating rates due to superelastic recovery properties. The technology is consolidating market structure by displacing balloon-expandable alternatives in all but rigid proximal tracheal segments where diameter precision remains critical.
The FDA breakthrough device designation and EMA conditional approval pathways are compressing regulatory review timelines for life-threatening central airway obstruction indications. These accelerated pathways reduce clinical validation periods while maintaining safety thresholds through post-market surveillance commitments. Complex malignant airway cases in the United States and European Union benefit most, with manufacturers restructuring development programs around early regulator engagement.
After-sales service unbundling is altering procurement relationships between stent manufacturers and hospital systems. Interventional pulmonology departments are negotiating direct technical support and procedural training separately from device supply contracts, displacing traditional bundled pricing models. This pattern is most visible in Germany and the United States where hospital procurement consolidation has strengthened buyer negotiating leverage.
Pulmonary Stents Market Segmentation
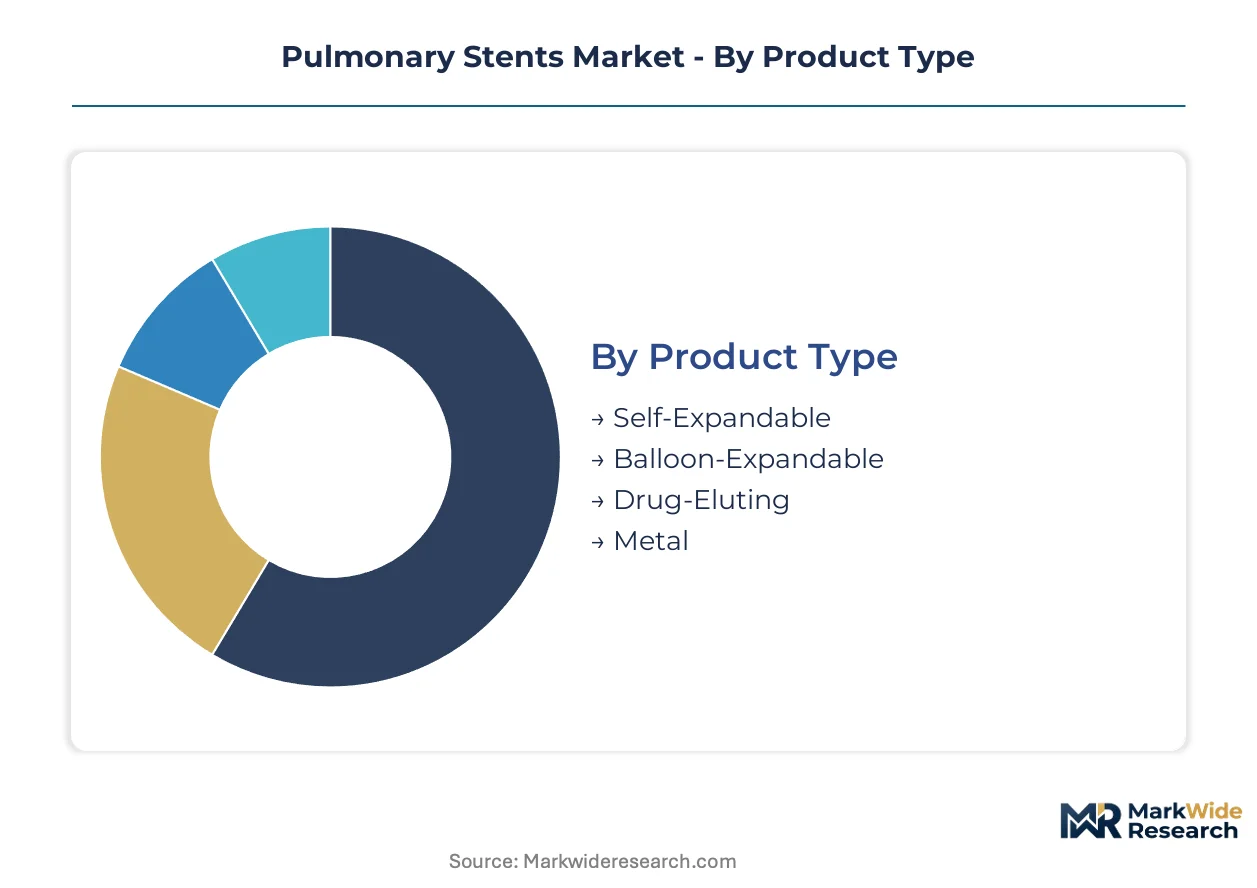
Pulmonary stent segmentation reveals how procedural migration and material innovation reshape purchasing patterns. Device selection now tracks closely with interventional pulmonology capability tiers and reimbursement classifications across hospital systems.
Product Type:
Upgrade cycles in pulmonary stenting accelerate as tertiary hospitals replace first-generation metal platforms with conformable nitinol systems and pharmacologic-enhanced alternatives.
- Self-Expandable:Nitinol superelastic stents recover predetermined shapes upon deployment, conforming to irregular tracheobronchial anatomy without balloon assistance. United States tertiary hospitals drive procedural volumes as interventional pulmonology suites expand malignant airway capabilities.
- Drug-Eluting:Sustained-release coatings targeting granulation tissue proliferation command premium positioning through reduced revision rates. Germany's statutory health insurance framework increasingly differentiates reimbursement for pharmacologic-enhanced platforms versus bare metal alternatives.
- Balloon-Expandable:Rigid proximal tracheal segments requiring precise diameter control.
- Metal:Commodity stainless steel platforms for basic obstruction cases.
Volume placements concentrate in Self-Expandable systems; the faster expansion belongs to Drug-Eluting platforms.
End User:
Procurement authority patterns bifurcate between consolidated hospital systems with specialized bronchoscopy infrastructure and distributed outpatient settings seeking procedural efficiency.
- Hospitals:Tertiary medical centers with dedicated interventional pulmonology departments anchor complex malignant airway case volumes. China's hospital tier classification system directs advanced stenting procedures toward Class III facilities with requisite imaging and anesthesia support.
- Specialty Clinics:Focused pulmonary practices in Germany and the United States perform elective benign stricture interventions outside acute care settings.
- Outpatient Surgical Centers:Ambulatory bronchoscopic procedures for stable airway obstruction.
- Research Institutions:Experimental biodegradable polymer validation and next-generation coating development.
Procedure economics favor Hospitals for complex cases; Specialty Clinics capture the steepest expansion trajectory for stable interventions.
Material:
Supply concentration in nickel-titanium metallurgy shapes cost structures and qualification timelines across manufacturer tiers.
- Nitinol:Nickel-titanium shape-memory alloys enable superelastic deployment and kink resistance through cyclic respiratory motion. ASTM F2063 composition specifications govern fatigue resistance testing that manufacturers must satisfy for FDA clearance.
- Stainless Steel:Balloon-expandable platforms for rigid proximal segments requiring precise diameter calibration.
- Polymer:Experimental absorbable scaffolds under clinical investigation.
- Coated Materials:Drug-eluting surfaces with sustained pharmacologic release profiles.
Commercial traction clusters in Nitinol; Polymer platforms are climbing the fastest toward validation milestones.
Deployment Technique:
Procedural workflow integration determines platform selection as interventional pulmonologists prioritize imaging compatibility and anesthesia requirements.
- Bronchoscopy:Flexible bronchoscopic deployment with fluoroscopic guidance dominates malignant airway obstruction management. Interventional pulmonology fellowship training programs in the United States expand procedural pipelines for advanced airway interventions.
- Endobronchial:Direct visualization techniques for proximal lesions.
- Radiologic:Image-guided placement for complex anatomies.
- Surgical:Open placement reserved for combined resection cases.
Procedural volume concentrates in Bronchoscopy; Endobronchial techniques gain share fastest among community hospital adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors interventional pulmonology device development in the United States, with tertiary hospital networks driving procedural standardization across North American markets.
United States
Mayo Clinic and Cleveland Clinic networks drive complex malignant airway case volumes through dedicated bronchoscopy suites. FDA breakthrough device designation compresses validation timelines for nitinol stent innovators. Minneapolis-Boston corridor concentrates manufacturer headquarters and specialized catheter production facilities.
Germany
University hospitals in Heidelberg and Munich establish European benchmarks for interventional pulmonology fellowship training. EMA conditional approval pathways accelerate market access for life-threatening central airway obstruction devices. Baden-Württemberg's medical technology cluster integrates nitinol metallurgy with precision catheter manufacturing.
China
Class III hospital tier classification directs advanced stenting procedures toward Beijing and Shanghai medical centers. NMPA regulatory reforms streamline innovative device review for domestic manufacturers. Yangtze River Delta concentration of nitinol wire suppliers reduces input logistics costs for regional stent producers.
Japan
Tokyo and Osaka university hospitals pioneer hybrid bronchoscopic-radiologic deployment techniques. PMDA's sakigake designation system accelerates priority review for central airway obstruction interventions. Kanto region medical device clusters support specialized delivery catheter development.
United Kingdom
Royal Brompton Hospital and Manchester University NHS Foundation Trust anchor national interventional pulmonology training networks. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for novel stent architectures. London-Oxford-Cambridge corridor concentrates academic research into biodegradable polymer platforms.
Pulmonary Stents Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material sophistication and clinical validation depth. The vendor base organizes into three tiers: integrated nitinol specialists with captive metallurgy, interventional pulmonology portfolio conglomerates, and regional catheter fabricators. Strategic archetypes include backward-integrated metallurgy controllers, bronchoscopy platform extenders, and precision delivery system specialists. Dominant competitive moves center on regulatory pathway optimization and procedural training ecosystem capture.
Among United States-based interventional device conglomerates, Boston Scientific Corporation exemplifies portfolio breadth across malignant airway management. Cook Group represents the backward-integrated archetype through nitinol wire production control. Taewoong Medical Co., Ltd. anchors Korean manufacturing specialization in self-expandable platform export markets. ENDO-FLEX GmbH occupies a position within German precision catheter fabrication for customized airway anatomies.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Novatech SA |
| Cook Group |
| Taewoong Medical Co., Ltd. |
| Merit Medical Systems, Inc. |
| Micro-Tech (Nanjing) Co., Ltd. |
| ENDO-FLEX GmbH |
| E. Benson Hood Laboratories, Inc. |
| Olympus Corporation |
| Others |
Value Network & Pricing Analysis
Drug-eluting coating technology migration toward sustained-release pharmacologic platforms simultaneously elevates manufacturing complexity and concentrates pricing power among coating specialists with validated FDA master files. Nitinol self-expandable stent producers face divergent cost structures as backward-integrated metallurgy controllers capture margin pools unavailable to assembly-only competitors.
Pricing Analysis
Revision-rate reduction anchors value-based pricing for drug-eluting pulmonary stents, with interventional pulmonologists accepting premium positioning for platforms demonstrating measurable patency extension. Three-tier pricing structure across premium pharmacologic-enhanced, standard nitinol self-expandable, and economy bare-metal tiers reflects certification depth and clinical validation burden. Cost compression in commodity stainless steel segments intensifies as Chinese manufacturers expand export capacity. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement frameworks, while outpatient surgical centers drive aggressive tender negotiations for high-volume benign stricture cases.
Supply Chain Analysis
Nitinol wire supply rests on specialized metallurgical producers in the United States, Germany, and China with ASTM F2063 qualification capabilities. Shape-memory alloy feedstock, precision laser-cutting equipment, and drug-eluting polymer coatings constitute critical input dependencies. Single-source vulnerability concentrates in coating formulation suppliers with validated pharmaceutical cGMP facilities. Distribution runs through GPO-negotiated contracts with tertiary hospital systems and specialized interventional pulmonology distributors serving regional bronchoscopy centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulmonary stent manufacturing is consolidating around metallurgy-integrated players as ISO 25539-2 fatigue testing compliance costs eliminate undercapitalized competitors. FDA breakthrough device designation timelines favor incumbents with established regulatory affairs infrastructure.
For Market Incumbents: Acquire specialized coating formulation assets with validated pharmaceutical release profiles to defend drug-eluting margin pools against emerging polymer specialists. Secure captive nitinol wire supply through offtake agreements with Yangtze River Delta metallurgical producers before qualification bottlenecks intensify. Reinforce hospital system partnerships through unbundled technical training contracts that displace distributor intermediaries. For New Entrants and Emerging Players: Interventional pulmonology fellowship training programs represent the most penetrable channel for procedural workflow integration, with United States academic centers seeking simulation-based stent deployment curricula. Target community hospital bronchoscopy adopters in Germany's statutory health insurance regions where reimbursement differentiation for pharmacologic-enhanced platforms creates first-mover positioning. Pursue white-label manufacturing partnerships with established catheter fabricators to bypass ISO 25539-2 certification capital requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by interventional pulmonology portfolio conglomerates seeking malignant airway case volume capture. Five-to-ten year viability favors backward-integrated nitinol specialists with FDA-cleared drug-eluting platforms over assembly-only metal stent producers. Watch NMPA regulatory reform pace in China as the inflection signal for domestic manufacturer valuation premiums versus export-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review compresses time-to-market for life-threatening central airway obstruction indications. |
| Backward Integration into Nitinol Metallurgy | Captive wire production insulates against ASTM F2063 qualification bottlenecks and input cost volatility. |
| Drug-Eluting Coating Partnership | Validated pharmaceutical release profiles command premium positioning through measurable revision-rate reduction. |
| Hospital System Training Contract | Unbundled technical support displaces traditional distributor relationships and locks procedural workflow adoption. |
| Specialized Delivery Catheter Development | Customized sizing platforms address complex airway anatomies inaccessible to standard off-the-shelf configurations. |
Research Methodology
SEC 10-K filings, FDA 510(k) clearance databases, and EMA conditional approval records formed the secondary backbone for manufacturer revenue segmentation and regulatory timeline mapping. Primary interviews with interventional pulmonologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers validated procedural adoption curves and procurement authority patterns. Bottom-up stent placement volume estimates triangulated against top-down manufacturer reported sales across product type and material categories.
Historical procedural volume trendlines across tertiary hospital bronchoscopy suites anchored the analytical framework, with segmentation modeling across self-expandable versus balloon-expandable platforms, nitinol versus stainless steel materials, and malignant versus benign indication categories. CAGRs were derived from weighted average procedure growth assumptions and average selling price evolution across pharmacologic-enhanced and bare-metal tiers. Forecast inputs incorporated interventional pulmonology fellowship training pipeline expansion rates and reimbursement coding decisions in Germany, Japan, and the United States.
Caveats apply where NMPA regulatory reform implementation delays or EMA conditional approval withdrawal could materially shift the outlook for emerging manufacturer market access. Reimbursement reclassification risk in statutory health insurance frameworks and nitinol raw material supply concentration represent additional revision triggers. A small set of named triggers—central airway obstruction mortality registry outcomes, granulation tissue pharmacologic trial readouts, and hospital procurement consolidation pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Vascular Patch Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Transcatheter Heart Valve Market