
 IV Equipment Market | 2026-2036
IV Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
IV Equipment Market Intelligence
Smart infusion pumps with integrated dose error reduction software is rotating the market toward higher-value, safety-oriented systems. This shift prioritizes patient safety and reduces medication administration errors in clinical environments. Baxter International leverages its deep relationships with hospital networks to deploy these advanced systems at scale. B. Braun SE differentiates through its comprehensive portfolio covering both infusion pumps and related consumables, offering a complete therapy solution.
Intravenous (IV) equipment comprises devices designed for the parenteral administration of fluids, medications, and nutrients. These systems, including catheters specified by gauge size and pumps with precise flow rate controls, enable controlled delivery directly into the bloodstream. Within the product landscape, infusion pumps represent a dominant category due to their technological complexity and high unit cost. The home care providers segment is expanding rapidly, driven by the decentralization of care for chronic disease management.
Regulatory frameworks from bodies like the US FDA and the European Medicines Agency under the MDR mandate stringent pre-market approval and post-market surveillance. These rules, alongside ISO 13485 quality standards, govern device safety, material biocompatibility, and manufacturing practices. The critical decision for manufacturers now involves balancing investment in software connectivity and data features with the imperative for robust cybersecurity protections against emerging threats.
Market Dynamics
The market's evolution is defined by the dual push for greater device connectivity and the critical imperative for robust cybersecurity. This creates a fundamental design tension for manufacturers balancing data-rich features against the need to protect against network-based threats.
Growth Catalysts
- Aging Demographics:The growing elderly population in developed nations like Germany and Japan, which have higher incidences of chronic diseases, is expanding the patient base requiring long-term IV therapies.
- Home Care Expansion:A systemic shift towards decentralized care models, particularly for chronic disease management, is accelerating demand for portable and user-friendly IV equipment suitable for home use.
- Regulatory Mandates for Safety:The US FDA’s push for interoperable smart pumps with dose error reduction software is compelling healthcare providers to upgrade their existing device fleets to safer, more advanced systems.
Market Restraints
- High Development Costs:The integration of complex software, connectivity features, and cybersecurity protocols into new smart pumps requires substantial R&D investment, elevating the final product cost.
- Stringent Regulatory Hurdles:The EU's Medical Device Regulation (MDR) imposes extensive clinical data and post-market surveillance requirements, which can significantly delay product launches and increase compliance costs.
- Legacy System Integration:The technical difficulty and cost of integrating modern, connected IV pumps with disparate and often outdated hospital electronic health record (EHR) systems can deter adoption.
Strategic Opportunities
- Emerging Market Penetration:Expanding sales and distribution networks in regions like Latin America and Southeast Asia, where healthcare infrastructure is modernizing, offers significant volume growth potential.
- AI-Powered Analytics:Integrating artificial intelligence with infusion data can enable predictive maintenance alerts and clinical decision support tools, creating new value-added service revenue streams for manufacturers.
- Direct-to-Patient Models:Developing service models for the home care segment that include device leasing, consumable replenishment, and remote monitoring bypasses traditional hospital-centric distribution channels.
Industry Challenges
- Cybersecurity Talent Scarcity:A shortage of software engineers with specialized expertise in medical device security and threat modeling creates a bottleneck for developing and maintaining secure connected pumps.
- Compliance and Certification Timelines:Navigating the multi-year process for obtaining ISO 13485 quality management certification and specific device approvals from bodies like the PMDA in Japan is a major operational hurdle.
- Interoperability Standardization:Lack of universal communication standards across different manufacturers' devices complicates the creation of truly integrated and seamless clinical workflows in hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IV Equipment Market |
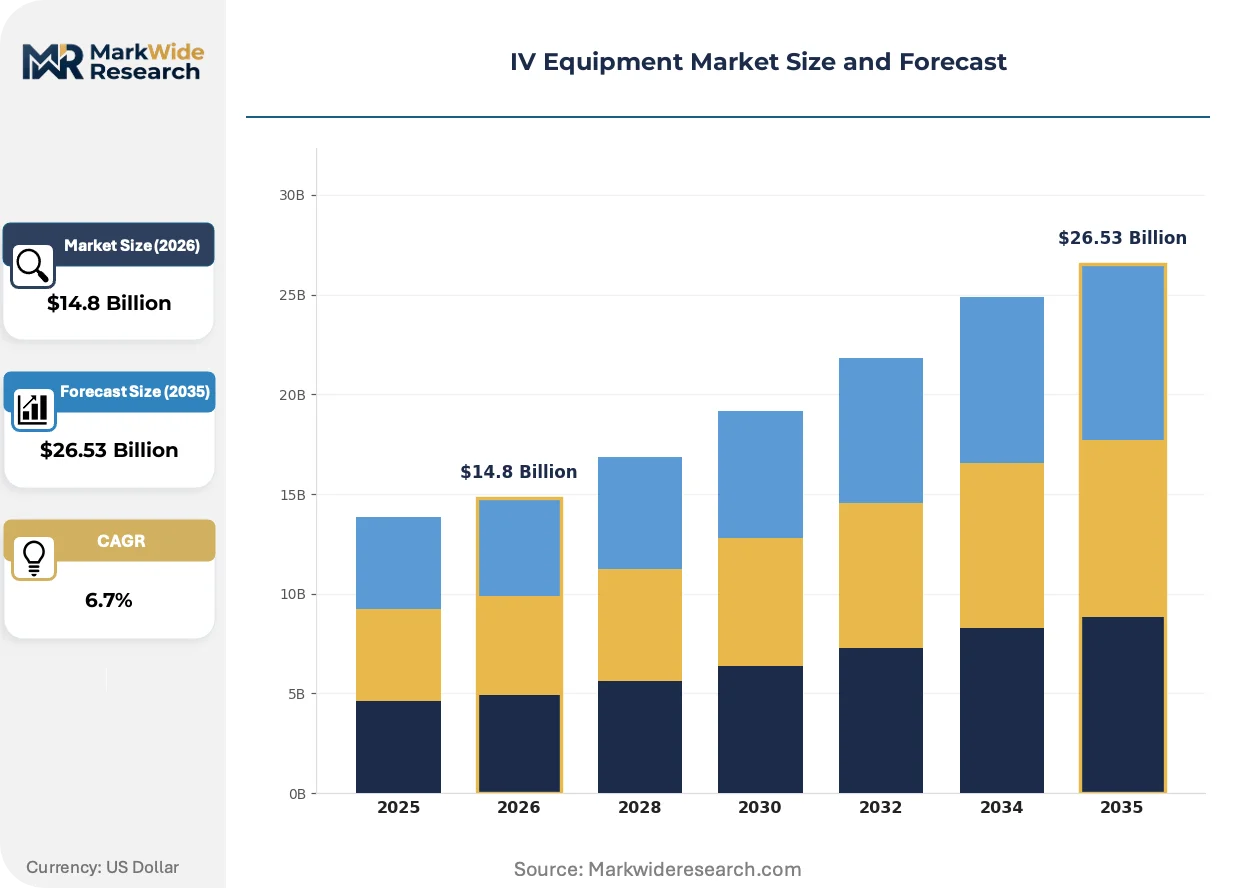
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, IV Catheters, Cannulas, IV Tubing, Fluid Warmer, Filters Therapy Area: Oncology, Cardiology, Critical Care, Neonatal, Anesthesia, Endocrinology End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Labs, Rehabilitation Centers, Home Care Providers, Research Institutes Distribution Channel: Direct Sales, Medical Distributors, E-Commerce, Retail Pharmacies, Group Purchasing Organizations |
| Companies Covered | Becton, Dickinson and Company, Baxter International, B. Braun SE, Fresenius Kabi AG, ICU Medical, Terumo Corporation, Nipro Corporation, Teleflex Incorporated, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IV Equipment Market Strategic Shifts & Innovations
A fundamental transformation is underway, driven by the shift toward software-defined medical devices and the concurrent decentralization of patient care. This dual evolution is redefining product requirements and altering traditional care delivery pathways.
Smart infusion pumps incorporate dose error reduction software (DERS) to guard against medication administration errors. Hospitals and acute care facilities are the primary adopters, driven by patient safety initiatives and regulatory pressure. This software-led intelligence is decomposing the pump from a standalone mechanical device into a connected data-gathering node within a broader clinical IT network.
The European Union’s Medical Device Regulation (MDR) establishes a more rigorous framework for demonstrating device safety and efficacy. It mandates enhanced clinical evidence, lifecycle traceability through Unique Device Identification (UDI), and continuous post-market surveillance. Infusion pump and catheter manufacturers are most impacted, facing significant costs to update technical files and recertify products.
Patient preference for treatment outside of hospitals is a clear behavioral shift influencing equipment design and sales channels. This trend is reducing the dominance of centralized hospital procurement, creating opportunities for specialized home infusion therapy providers. This pattern is most visible in the United States, where chronic disease management is increasingly moving into home care settings.
IV Equipment Market Segmentation
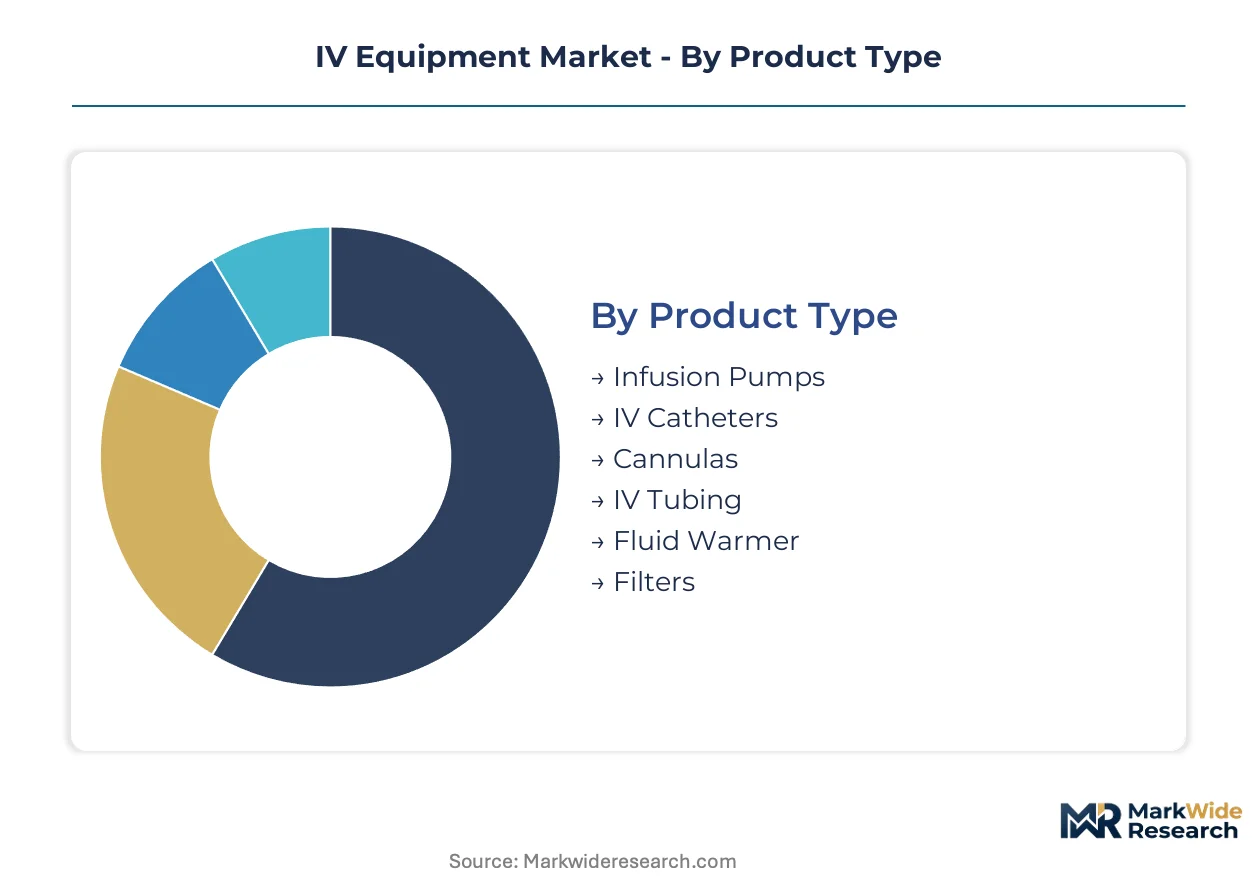
The IV equipment market segmentation highlights the diverse applications and technological nuances driving product development and end-user adoption. Understanding these distinct segments is critical for manufacturers to tailor offerings and navigate complex regulatory landscapes. This analysis dissects the market across product types, therapy areas, end users, and distribution channels.
Product Type:
Regulatory frameworks heavily influence product design and market access within the IV equipment sector, particularly for devices requiring precise dose control and material biocompatibility.
- Infusion Pumps:These sophisticated devices precisely control fluid and medication delivery rates into a patient's bloodstream. Demand for smart pumps with integrated dose error reduction software is concentrating in hospitals across the US and Europe, driven by FDA and MDR safety mandates.
- IV Catheters:Catheters are flexible tubes inserted into a vein for fluid or medication administration, specified by gauge size for various clinical needs. Demand is strong in acute care settings in Germany and Japan, where an aging population requires frequent intravenous access for chronic disease management.
- Cannulas:These short, flexible tubes are inserted into veins for short-term IV access, often used for blood draws or basic fluid delivery.
- IV Tubing:Tubing sets connect IV bags to patient access points, requiring sterile and biocompatible materials for safe fluid transfer.
- Fluid Warmer:Devices like fluid warmers prevent hypothermia during rapid or large-volume fluid infusions, crucial in critical care environments.
- Filters:IV filters remove particulate matter or air from infusion lines, protecting patients from potential complications during therapy.
Infusion Pumps handle the majority of throughput; IV Catheters are the fastest mover on share.
Therapy Area:
The specific clinical application of IV equipment dictates design requirements, material selection, and required precision for patient outcomes across diverse medical conditions.
- Oncology:IV equipment supports chemotherapy delivery and supportive care for cancer patients, often requiring long-term, precise infusions. Demand concentrates in specialized cancer centers and home care settings in the United States, driven by increasing chronic disease prevalence and decentralized care models.
- Critical Care:This area demands highly accurate IV systems for administering life-sustaining medications and fluids to critically ill patients. Hospitals in advanced healthcare markets like Germany prioritize sophisticated pumps for intensive care units, ensuring patient stability and safety.
- Cardiology:IV therapies for cardiology involve delivering medications to manage heart conditions, often requiring controlled infusions in acute settings.
- Neonatal:Specialized IV equipment with micro-infusion capabilities caters to the delicate needs of newborns, ensuring precise and safe fluid administration.
- Anesthesia:IV access is fundamental for administering anesthetic agents and maintaining hydration during surgical procedures in various clinical environments.
- Endocrinology:IV equipment supports the delivery of hormones and other medications for endocrine disorders, including diabetes management in some cases.
Demand in Critical Care remains strong due to acute patient needs; Oncology exhibits the steepest expansion trajectory.
End User:
The maturity and infrastructure of different healthcare settings significantly influence the type and volume of IV equipment procured, ranging from centralized facilities to decentralized care models.
- Hospitals:These institutions represent the largest end-user segment, utilizing a wide range of IV equipment for inpatient care, surgeries, and emergency services. Procurement in US and European hospitals increasingly focuses on smart, interoperable pumps to meet regulatory mandates and enhance patient safety.
- Home Care Providers:This segment is expanding rapidly, delivering IV therapies in patient homes for chronic disease management and post-acute care. The preference for out-of-hospital treatment in countries like the United States drives demand for portable, user-friendly devices and direct-to-patient service models.
- Ambulatory Surgery Centers:These facilities use IV equipment for short-stay surgical procedures, requiring efficient and reliable administration systems.
- Diagnostic Labs:IV equipment in diagnostic labs primarily facilitates blood draws and contrast agent administration for imaging procedures.
- Rehabilitation Centers:Patients in rehabilitation centers may require IV access for medication or nutritional support during their recovery process.
- Research Institutes:These institutions utilize IV equipment for clinical trials and experimental studies, often requiring specialized or customized delivery systems.
The shift towards Home Care Providers reflects evolving patient preferences, while Hospitals maintain their foundational role.
Distribution Channel:
The concentration of supply within distribution channels impacts market reach, pricing strategies, and the efficiency of delivering IV equipment to various end-users.
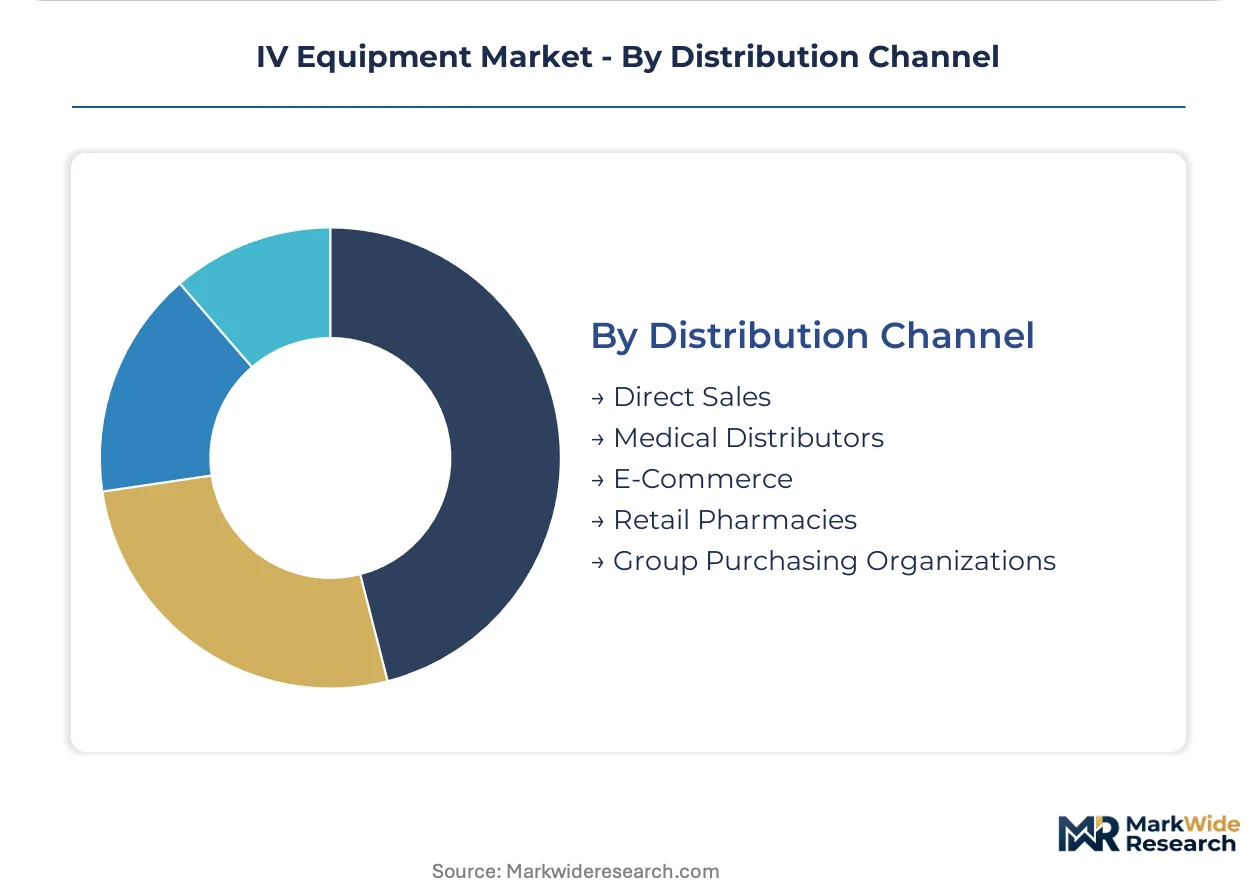
- Direct Sales:Manufacturers engage in direct sales to large hospital networks and government healthcare systems, fostering deep relationships and offering customized solutions. This channel provides manufacturers with greater control over product messaging and service delivery in key markets.
- Medical Distributors:Distributors provide broad market access, particularly to smaller clinics, ambulatory centers, and home care providers, leveraging established logistics and regional presence. This channel is crucial for reaching fragmented customer bases across diverse geographies.
- E-Commerce:Online platforms are emerging for procurement of IV consumables and less complex devices, offering convenience and competitive pricing for smaller practices.
- Retail Pharmacies:Pharmacies play a role in dispensing specific IV-related medications and some basic IV supplies for home care patients.
- Group Purchasing Organizations:GPOs negotiate bulk purchasing agreements for hospitals and health systems, streamlining procurement and driving cost efficiencies for members.
Traditional channels like Direct Sales and Medical Distributors continue to dominate, but digital platforms are gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for IV equipment is pronounced in regions with advanced healthcare infrastructure and robust regulatory frameworks. Countries like the United States, Germany, and Japan anchor significant demand due to aging populations and a shift towards decentralized care. These nations also drive innovation in connected and safety-oriented IV systems.
United States
United States demand for IV equipment stems from expanding home care and chronic disease management. The US FDA's push for interoperable smart pumps drives technology upgrades across hospital systems. Boston's medical device cluster actively develops advanced, connected IV systems for patient safety.
Germany
Germany's IV equipment market is shaped by aging demographics and critical care needs in hospitals. The EU's Medical Device Regulation (MDR) mandates stringent safety and efficacy standards for all devices. Bavaria hosts numerous medical technology firms specializing in sophisticated infusion pump development.
Japan
Japan's market requires frequent intravenous access for its large elderly population with chronic conditions. The PMDA ensures rigorous quality and safety approvals for all medical devices. Tokyo's medical technology sector focuses on specialized, high-precision IV equipment tailored for geriatric care.
China
China's modernizing healthcare infrastructure and expanding hospital networks fuel IV equipment demand. The NMPA oversees medical device approvals and enforces quality control for domestic and imported products. Shanghai's medical device industry is investing heavily in local production and advanced IV system development.
IV Equipment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the IV equipment market. The market exhibits a tiered structure, encompassing diversified medical technology conglomerates, specialized infusion pump manufacturers, and regional consumable providers. Global players focus on M&A for software capabilities, while others prioritize geographic expansion into modernizing healthcare systems. Portfolio diversification and strategic partnerships for interoperability also represent dominant competitive moves.
Diversified medical technology conglomerates, such as Baxter International, exemplify companies providing comprehensive IV solutions, leveraging deep relationships with healthcare providers. B. Braun SE, a Germany-based firm, occupies a position across both advanced pumps and consumables, offering complete therapy solutions. ICU Medical, an American corporation, represents a specialized entity focusing on high-acuity infusion systems and critical care technology. These players anchor different segments of the market, from broad hospital deployment to niche, high-precision applications.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Baxter International |
| B. Braun SE |
| Fresenius Kabi AG |
| ICU Medical |
| Terumo Corporation |
| Nipro Corporation |
| Teleflex Incorporated |
| Cardinal Health |
| Others |
Cost & Logistics Intelligence
The EU's Medical Device Regulation (MDR) gates both supply qualification and price differentiation for IV equipment, demanding stringent compliance for market access and premium positioning.
Pricing Analysis
US FDA mandates dictate the pricing tier structure for smart infusion pumps, driving demand for advanced, safety-oriented systems. Pricing stratifies across premium, standard, and economy tiers, reflecting software sophistication, material biocompatibility, and after-sales support. Cost compression in basic IV consumables is intensifying due to regional competition and high-volume procurement. Home care providers exhibit higher price sensitivity for portable devices, while large hospital networks prioritize long-term contract value for integrated systems.
Supply Chain Analysis
Volatility in global shipping costs for specialized electronic components impacts the inbound logistics of IV equipment manufacturers. Supply concentrates heavily in China for basic consumables and electronic components, while Germany and the United States lead in advanced infusion pump manufacturing. The industry depends on medical-grade plastics and microcontrollers, creating a single-source vulnerability for some specialized sensors. Distribution runs through established medical distributors for broad market access, complemented by direct sales to large hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IV equipment market is at a platform-economics inflection, driven by the imperative for interoperable smart pumps integrating seamlessly with electronic health records.
For Market Incumbents: Compound deep relationships with hospital networks by investing in AI-powered analytics for predictive maintenance and clinical decision support. Prioritize R&D in cybersecurity protocols to mitigate emerging network-based threats to connected devices. Expand certification investment for new products under the EU's Medical Device Regulation, securing continued market access against new entrants.
For New Entrants and Emerging Players: Remote patient monitoring platforms represent a service-layer gap where incumbents under-serve. Target specialized home care providers in modernizing healthcare systems like Southeast Asia with user-friendly, portable IV solutions. Develop direct-to-patient service models that bundle device leasing with consumable replenishment, bypassing traditional hospital-centric distribution channels.
For Investors and Strategic Acquirers: US FDA smart pump mandates reshape the acquisition landscape, favoring companies with advanced software and connectivity expertise. Long-term viability hinges on acquiring firms that offer robust cybersecurity capabilities and seamless integration with existing hospital IT infrastructure over the projection horizon. The signal to watch is the pace of interoperability standardization across different manufacturers' devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Clinical Decision Support | Enhances patient safety and creates new service revenue streams for manufacturers. |
| Secure MDR and FDA Device Certifications | Ensures market access and compliance in key developed healthcare economies. |
| Expand Direct-to-Patient Service Models | Captures share in the rapidly growing decentralized home care segment. |
| Invest in Cybersecurity for Connected Devices | Protects patient data and device integrity against network-based threats. |
| Form Strategic Partnerships for Interoperability | Facilitates seamless integration with diverse hospital electronic health record systems. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement officers, biomedical engineers, clinical nurses, and regulatory affairs specialists, then refined through iterative analysis. This involved combining insights from in-depth interviews with extensive secondary validation using FDA device approvals, EMA guidance documents, WHO health statistics, and GPO purchasing data. A robust bottom-up and top-down triangulation approach ensured comprehensive market sizing.
The variance-decomposition analytical framework was applied across the analysis window, segmenting the market by product type, therapy area, end user, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived from historical data and projected forward based on identified market dynamics. Chronic disease prevalence rates and healthcare expenditure growth served as key industry-specific forecast inputs.
Underlying assumptions cover regulatory stability and the pace of technological advancement, with deviation risk concentrated in unforeseen supply chain disruptions or rapid shifts in patient care settings. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Urinary Flow Meters Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Retinal Implant Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Surgical Display Market
Medical Devices
APAC AMH Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Pharmacy Automation Devices Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Assisted Walking Devices Market