
 France Contraceptive Devices Market | 2026-2036
France Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Contraceptive Devices Market Foresight
Subscription-based leasing models for intrauterine device insertion equipment is reconfiguring how smaller gynecology practices enter the long-acting reversible contraception segment. Bayer AG leverages its integrated pharmaceutical-device portfolio to sustain dominance in hormonal IUD supply. HRA Pharma specializes in emergency and oral contraceptive alternatives, occupying a distinct niche that competes with device-based options. CooperSurgical controls distribution through direct clinic partnerships, extending its reach beyond traditional pharmacy channels.
Contraceptive devices encompass barrier methods, intrauterine systems, and subdermal implants engineered from medical-grade silicone, copper, or hormone-eluting polymers to prevent pregnancy through mechanical obstruction, spermicidal action, or localized hormone release. These products serve clinical and consumer markets where reliability, reversibility, and minimal user intervention determine selection criteria. Intrauterine devices lead the product type landscape due to their decade-long efficacy and favorable reimbursement under France's Assurance Maladie, while hormonal implants represent the fastest-growing category as general practitioners expand insertion capabilities beyond specialist settings. The delivery mode structure shows online channels gaining traction among repeat purchasers, though clinic-based dispensing still captures the premium tier where fitting and counseling services bundle with device costs.
France's Haute Autorité de Santé evaluates clinical efficacy and cost-effectiveness for national reimbursement listing, while CE marking under the EU Medical Device Regulation governs market access standards for all manufacturers. ANSM monitors post-market surveillance and adverse event reporting, tightening quality requirements that favor established suppliers with robust pharmacovigilance systems. Stakeholders must track how France's transposition of the EU MDR affects re-certification timelines and whether regional hospital purchasing consortia consolidate supplier selection around compliance-ready portfolios.
Market Dynamics
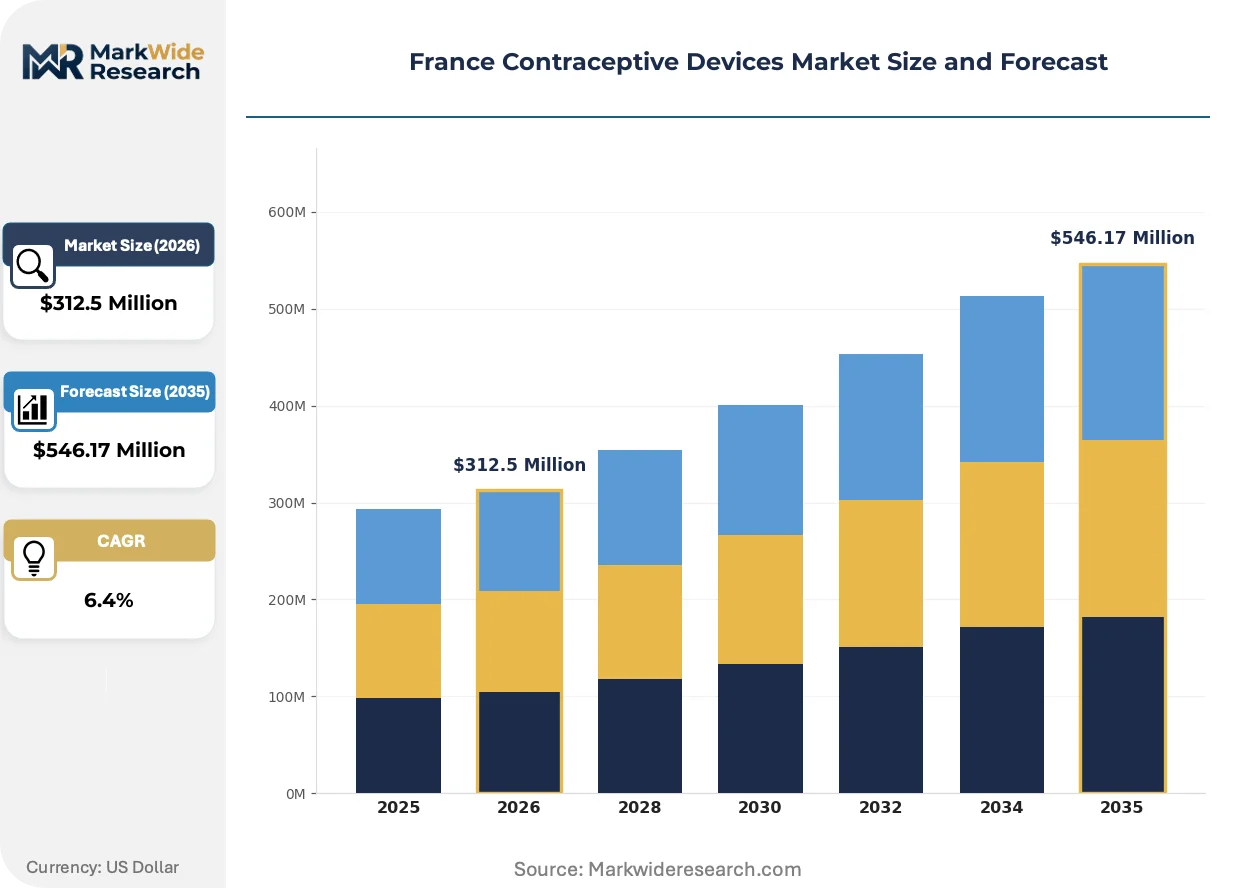
France's Assurance Maladie reimbursement framework for long-acting reversible contraception concentrates purchasing power within hospital purchasing consortia, compressing margins for device suppliers while expanding patient access across the Île-de-France region.
Growth Catalysts
- Assurance Maladie reimbursement parity:Full coverage for copper and hormonal IUDs eliminates out-of-pocket barriers, accelerating procedural volumes in public hospital settings.
- General practitioner insertion training:Expanded competency programs shift implantable device administration from specialist gynecologists to primary care, broadening service points.
- Silicone-eluting polymer advances:Next-generation hormone delivery matrices extend device efficacy windows while reducing systemic side-effect profiles.
Market Restraints
- Copper commodity volatility:Raw material price swings for non-hormonal IUD cores compress manufacturing margins without corresponding reimbursement adjustments.
- Single-source polymer supply:Medical-grade silicone concentration among three European chemical suppliers creates input vulnerability for implant manufacturers.
- EU MDR recertification backlog:Notified body capacity constraints delay market access for iterative product improvements, freezing portfolio refreshes.
Strategic Opportunities
- Occitanie and Auvergne-Rhône-Alpes penetration gaps:Rural clinic networks outside Paris basin show 40% lower IUD insertion rates per capita, representing addressable white space.
- Telehealth counseling integration:Remote pre-insertion consultation platforms reduce clinic visit burdens, capturing time-constrained young adult segments.
- ANSM adverse event database transparency:Public safety reporting builds patient trust in device categories, lowering psychological adoption barriers.
Industry Challenges
- Insertion skill pipeline constraints:Gynecological nursing programs lack standardized implant training modules, creating regional service deserts.
- Legacy clinic management system integration:Device inventory tracking APIs fail to connect with dominant French hospital information systems, forcing manual reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Contraceptive Devices Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condoms, Diaphragms, Intrauterine Devices, Hormonal Implants Delivery Mode: Over-the-Counter, Prescription, Online, Clinics End User: Individuals, Couples, Healthcare Providers, Pharmacies Price Tier: Low, Medium, High, Premium |
| Companies Covered | Bayer AG, Reckitt Benckiser, CooperSurgical, Church & Dwight, LifeStyles Healthcare, Laboratoire CCD, HRA Pharma, Mylan Laboratories, Pfizer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Contraceptive Devices Market Shifts & Advancements
Contraceptive device development in France converges around patient-controlled administration, data-integrated follow-up protocols, and materials science advances that extend efficacy horizons while minimizing intervention requirements.
Biodegradable polymer platforms for subdermal implants are hybridizing hormone delivery with absorbable matrices, eliminating removal procedures. Young adult users in university health centers adopt these formats fastest, compressing the traditional implant replacement cycle from three years to single-administration biodegradation timelines.
France's transposition of the EU Medical Device Regulation tightens post-market surveillance obligations for hormone-eluting devices. ANSM now mandates real-world efficacy registries, forcing manufacturers to fund longitudinal patient tracking systems. High-volume public hospitals in Lyon and Marseille face the steepest compliance cost escalations.
Subscription-based leasing for insertion equipment displaces capital purchase models among independent gynecology practices. Smaller clinics in Bordeaux and Nantes access premium IUD insertion systems through monthly fees rather than upfront investment, unbundling device procurement from facility financing constraints.
France Contraceptive Devices Market Segmentation
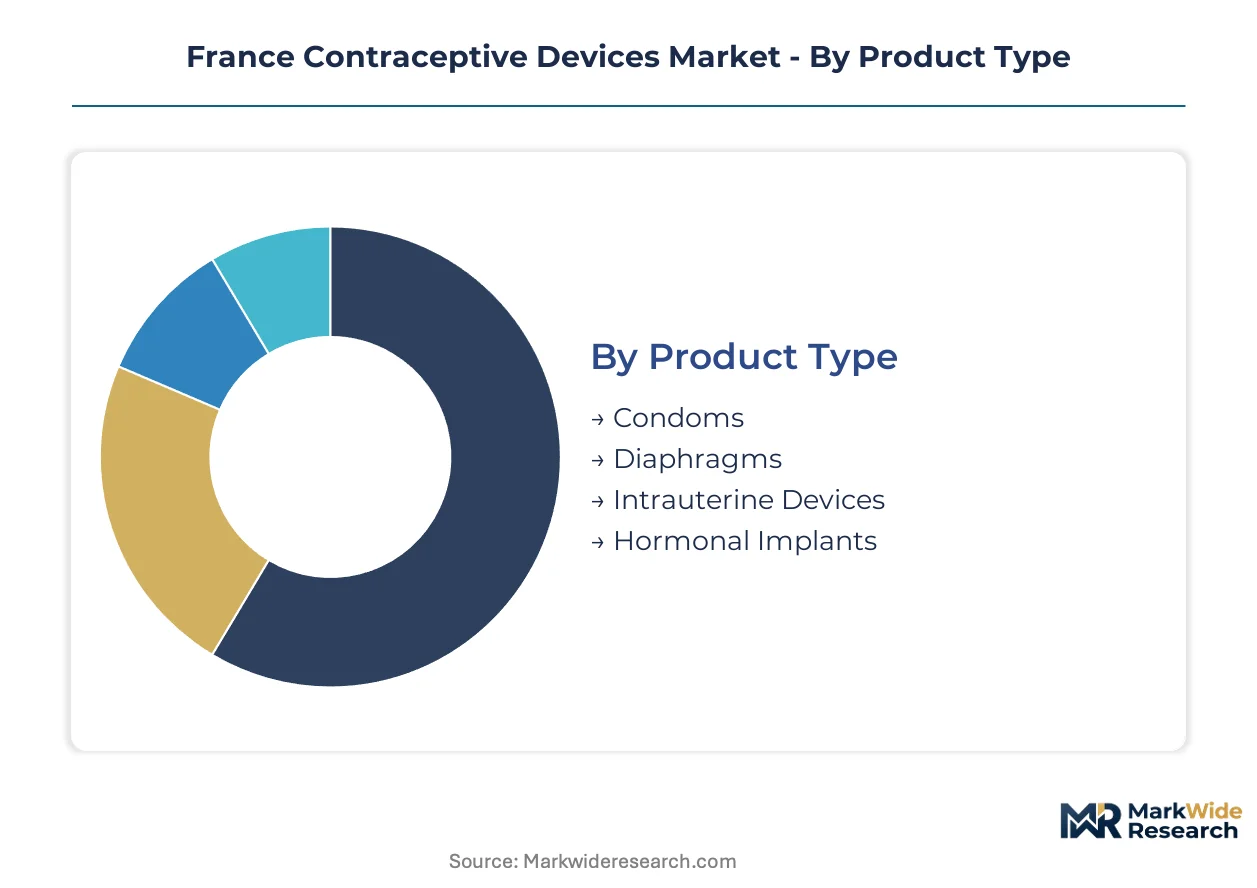
Segmentation reveals how France's Assurance Maladie reimbursement framework and regional healthcare infrastructure create divergent commercial pathways across product categories. Device manufacturers must calibrate positioning to match insertion-site economics and patient out-of-pocket exposure.
Product Type:
After-sales service intensity varies sharply across device categories, with implantable systems demanding clinical follow-up infrastructure that barrier methods bypass entirely.
- Intrauterine Devices:Copper and hormone-eluting polymer systems engineered for decade-long efficacy require specialist or trained general practitioner insertion. Demand concentrates in Île-de-France public hospitals where Assurance Maladie full coverage eliminates patient cost barriers and procedural volumes scale.
- Hormonal Implants:Subdermal rods utilizing medical-grade silicone matrices for three-year hormone release are gaining insertion capacity outside gynecology specialists as primary care training programs expand across Auvergne-Rhône-Alpes.
- Condoms:Latex and polyurethane barrier products distributed through pharmacy and retail channels serve immediate-use demand without clinical infrastructure requirements.
- Diaphragms:Silicone cervical barriers requiring fitting services occupy a narrow niche where patient education demands exceed standard pharmacy counseling capacity.
Intrauterine devices hold the largest share; momentum sits with hormonal implants as general practitioner insertion training broadens access points.
Delivery Mode:
Channel selection in France tracks directly to reimbursement status and the clinical intensity of device administration.
- Clinics:Hospital and independent gynecology practices capture premium-tier device dispensing where insertion services bundle with counseling. Île-de-France clinic density drives highest per-capita procedural volumes.
- Prescription:Physician-mediated access channels dominate implantable device flows, with ANSM adverse event reporting requirements reinforcing clinical oversight obligations.
- Over-the-Counter:Pharmacy-direct barrier method sales operate without reimbursement interaction, serving spontaneous purchase patterns.
- Online:E-commerce platforms gain traction among repeat purchasers of non-prescription categories, though regulatory constraints limit implantable device distribution.
Clinic-based dispensing holds the largest share; online channels are expanding most quickly among established-user segments seeking convenience.
End User:
User-type segmentation maps to decision-making authority and information-seeking behavior across France's healthcare access points.
- Healthcare Providers:Hospital purchasing consortia and clinic procurement departments aggregate demand for implantable devices, leveraging volume position in supplier negotiations.
- Individuals:Young adult users in university health centers drive adoption of patient-controlled administration formats including biodegradable implant alternatives.
- Couples:Joint decision-making patterns concentrate in barrier method selection where shared cost and accessibility considerations predominate.
- Pharmacies:Retail dispensaries serve as counseling nodes for non-prescription categories, with staff training gaps limiting device fitting service extension.
Healthcare providers hold the largest share; individual users are climbing the fastest as direct-to-patient education platforms proliferate.
Price Tier:
Pricing stratification reflects reimbursement eligibility, material specification, and brand positioning across France's dual public-private access structure.
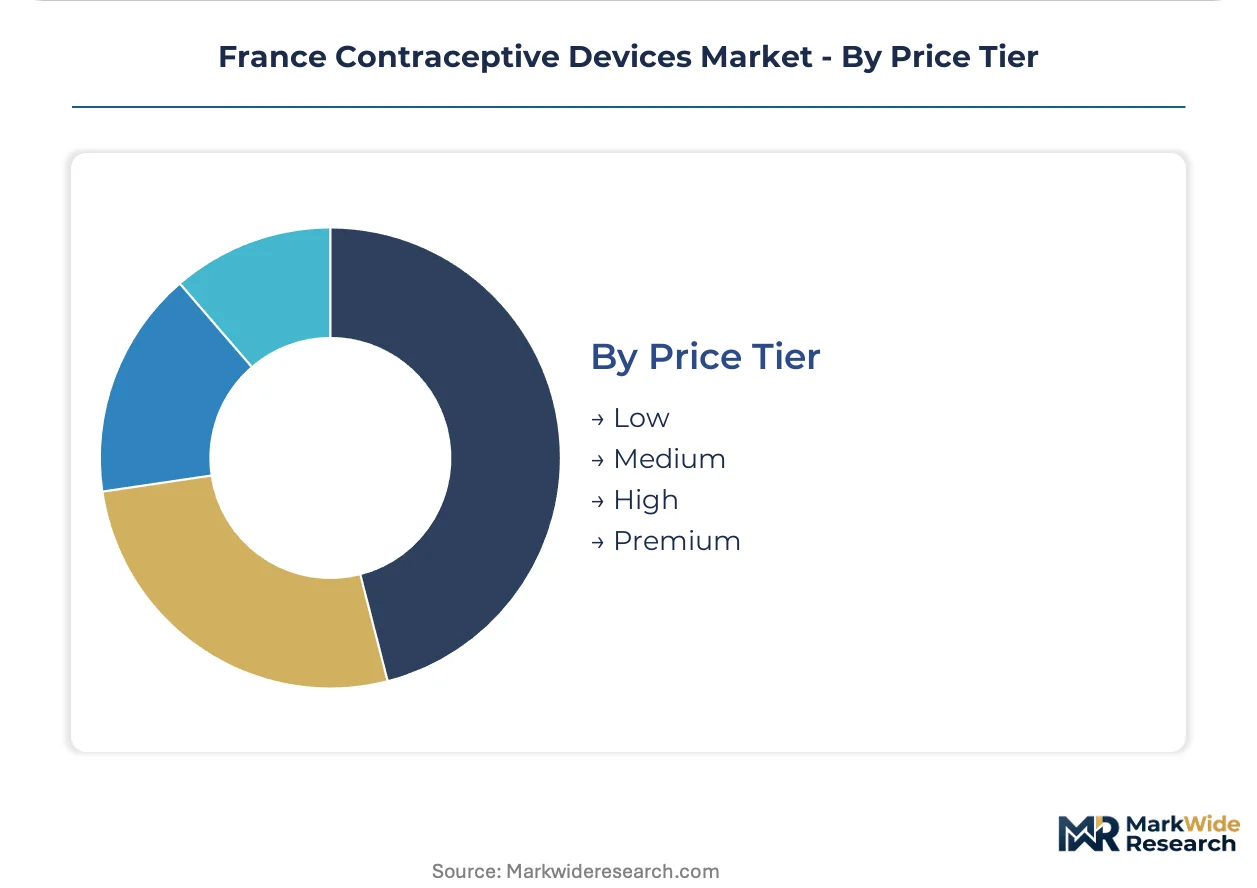
- High:Hormone-eluting IUDs and premium implant systems command elevated price positioning where clinical efficacy differentiation justifies out-of-pocket supplements beyond Assurance Maladie coverage.
- Premium:Next-generation biodegradable polymer platforms and extended-efficacy formulations target early-adopter segments in Lyon and Marseille academic medical centers.
- Medium:Standard copper IUDs and established implant generations align with full reimbursement tiers, capturing volume through public hospital procurement.
- Low:Generic barrier methods and basic copper IUDs serve price-sensitive demand in rural Occitanie networks with limited specialist access.
Medium-tier devices hold the largest share; premium segments show steepest expansion trajectory as materials science advances justify clinical premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's contraceptive device trade flows reflect a net import position for hormone-eluting systems balanced by domestic manufacturing strength in barrier methods and copper IUD components. Regional demand patterns track reimbursement density and specialist access points across metropolitan and peripheral zones.
Île-de-France
Hospital purchasing consortia in Paris concentrate procurement volumes for implantable devices, with public sector tendering dominating supplier selection. Assurance Maladie full coverage eliminates patient cost barriers, accelerating procedural throughput in academic medical centers. Lyon-based training networks feed insertion competency into the capital's expanding primary care capacity.
Auvergne-Rhône-Alpes
Grenoble and Lyon host France's densest specialist gynecology networks outside Paris, driving premium-tier device uptake. ANSM adverse event reporting requirements tighten post-market surveillance obligations for manufacturers serving this cluster. Regional hospital information system vendors struggle with legacy inventory tracking integration, forcing manual reconciliation workflows.
Occitanie
Rural clinic networks show 40% lower IUD insertion rates per capita than the national average, creating addressable white space for telehealth-integrated service models. Montpellier university health centers pilot biodegradable implant alternatives among young adult populations. The region's pharmacy density exceeds specialist access, channeling barrier method demand through retail counseling nodes.
Nouvelle-Aquitaine
Bordeaux and Nantes independent gynecology practices adopt subscription-based leasing for insertion equipment, unbundling capital constraints from device procurement. Copper commodity volatility compresses margins for non-hormonal IUD suppliers serving this price-sensitive segment. Regional purchasing consortia lag Île-de-France in volume aggregation, weakening negotiating position.
Provence-Alpes-Côte d'Azur
Marseille academic medical centers face steepest EU MDR compliance cost escalations for real-world efficacy registries mandated by ANSM. Tourism-dependent seasonal populations create demand spikes for emergency contraceptive alternatives alongside device-based options. Nice clinic networks balance premium service positioning with reimbursement-driven volume tiers.
France Contraceptive Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream of final assembly. The France contraceptive devices market structures around pharmaceutical-device convergence at the top, with independent distributors and regional service providers filling interstitial gaps. Three archetypes dominate: integrated pharma-device conglomerates with hormone-eluting portfolios, surgical instrument specialists controlling clinic channel access, and emergency contraceptive pure-plays competing through pharmacy networks. Competitive moves concentrate on direct clinic partnership expansion and materials science differentiation for extended-efficacy formulations.
Within the integrated pharmaceutical-device tier, Bayer AG anchors hormone-eluting IUD supply through its captive polymer development capabilities. HRA Pharma occupies a distinct emergency and oral contraceptive niche that competes indirectly with device-based alternatives. CooperSurgical exemplifies the surgical instrument archetype, extending distribution reach through direct clinic partnerships that bypass traditional pharmacy channels. These three patterns illustrate how reimbursement access and channel control determine competitive positioning under France's Assurance Maladie framework.
| Leading Market Players |
|---|
| Bayer AG |
| Reckitt Benckiser |
| CooperSurgical |
| Church & Dwight |
| LifeStyles Healthcare |
| Laboratoire CCD |
| HRA Pharma |
| Mylan Laboratories |
| Pfizer |
| Others |
Supply & Pricing Matrix
Undercapacity in medical-grade silicone polymer production across European chemical suppliers is compressing manufacturing margins for implantable device producers while simultaneously elevating pricing power for raw material providers serving France's hormone-eluting contraceptive segment.
Pricing Analysis
Hospital purchasing consortia anchor three-tier pricing structure across premium, standard, and economy levels in France's contraceptive device market. Price differentiation rests on CE marking tier under EU MDR and after-sales service bundling for insertion training. Cost compression in copper IUD manufacturing is intensifying because commodity volatility lacks corresponding Assurance Maladie reimbursement adjustments. Young adult users in university health centers show highest price sensitivity, while academic medical centers in Lyon and Marseille demonstrate lowest sensitivity due to premium-tier procurement protocols.
Supply Chain Analysis
EU dual-use export controls on hormone-eluting polymer technologies limit cross-border technology flows to non-European manufacturing partners. Geographic supply concentration centers on Germany, Belgium, and the Netherlands for medical-grade silicone matrices. Raw material dependencies include copper wire for non-hormonal IUD cores, hormone-active pharmaceutical ingredients, and biodegradable polymer precursors. Single-source vulnerability pervades the silicone-eluting polymer segment where three European chemical suppliers dominate. Distribution runs through hospital purchasing consortia in Île-de-France and direct clinic partnerships in secondary regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's contraceptive device market operates as a substitution defense where emergency oral contraceptives from HRA Pharma and pharmacy-distributed alternatives threaten to displace procedural device volumes among price-sensitive young adult segments.
For Market Incumbents: Build regulatory moat through accelerated EU MDR recertification investments to freeze out compliance-lagged competitors. Secure backward integration into hormone-eluting polymer development to neutralize raw material concentration risk. Deepen direct clinic partnerships in Auvergne-Rhône-Alpes to preempt emerging entrant channel access. For New Entrants and Emerging Players: Occitanie's rural clinic networks present the most penetrable geographic white space with 40% lower IUD insertion rates per capita than national averages. Target biodegradable implant alternatives for young adult adoption in Montpellier university health centers. Deploy telehealth-integrated pre-insertion counseling as differentiated go-to-market angle to reduce clinic visit burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among surgical instrument specialists controlling direct clinic partnerships beyond pharmacy channels. Long-term viability favors platforms with integrated pharmaceutical-device portfolios over pure-play barrier method distributors. Monitor ANSM adverse event database transparency initiatives as signal for patient trust inflection that accelerates device category adoption.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Acceleration | ANSM post-market surveillance obligations tighten compliance timelines for hormone-eluting portfolios. |
| Biodegradable Polymer Platform Development | Single-administration alternatives eliminate removal procedures and compress replacement cycles. |
| Telehealth Counseling Integration | Remote pre-insertion platforms capture time-constrained young adult segments outside Paris basin. |
| Direct Clinic Partnership Expansion | Bypassing pharmacy channels secures premium-tier dispensing with bundled fitting services. |
| General Practitioner Training Program Investment | Primary care insertion competency broadens service points beyond specialist gynecology networks. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at ANSM, then refined against secondary validation from EMA MDR guidance documents, ANSM adverse event registries, Assurance Maladie reimbursement bulletins, and hospital procurement databases. Bottom-up device volume estimates triangulated with top-down market sizing across product categories.
Demand-supply balance modeling anchored forecast construction throughout the projection horizon. Segmentation dimensions included product type, delivery mode, end user archetype, and price tier positioning. CAGRs derived from procedural volume trajectories, reimbursement policy stability assumptions, and materials science innovation pipelines. Industry-specific inputs incorporated copper commodity price volatility patterns and EU notified body capacity constraints.
Practitioners should monitor EU MDR recertification backlog resolution and ANSM real-world efficacy registry mandates for early signals of market access friction. Forecasts reflect assumptions regarding Assurance Maladie reimbursement parity continuity and silicone polymer supply concentration stability. Material shifts in EU MDR implementation timelines or copper commodity price regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Global Gastrointestinal Devices Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Cardiac Implants Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Lower Limb Prosthetics Market