
 Vascular Closure Device (VCD) Market | 2026-2036
Vascular Closure Device (VCD) Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Closure Device (VCD) Market Analytics
Multi-source procurement of polymer and collagen biomaterials is repositioning supply strategies across the VCD industry. Terumo Corporation leverages captive Japanese manufacturing to sustain cost discipline on suture-based platforms. Abbott differentiates through biodegradable plug technologies that reduce time-to-hemostasis in interventional cardiology. Merit Medical Systems anchors North American distribution through direct hospital contracting and specialized sales forces.
A vascular closure device is a mechanical or biological implant deployed percutaneously to achieve arterial hemostasis following catheter-based procedures, typically incorporating collagen plugs, suture mechanisms, or nitinol clips designed for 5F to 8F access sites. Its primary commercial purpose is to reduce bedrest duration, compress complications, and accelerate discharge in cardiac catheterization and peripheral vascular workflows. Active closure devices command premium pricing due to their immediate mechanical seal and lower complication profiles in high-volume cardiac centers. Biodegradable device demand is accelerating fastest as hospitals prioritize resorbable materials that eliminate permanent foreign body retention and simplify follow-up imaging protocols.
FDA 510(k) premarket notification requirements, EU MDR technical documentation mandates, and Japan PMDA foreign manufacturer registration collectively elevate barrier costs for new entrants while rewarding incumbent quality systems. These frameworks compel clinical evidence investments that extend product development timelines but strengthen reimbursement positioning in risk-averse procurement environments. Stakeholders must monitor evolving MDR notified body capacity constraints and CMS procedural coding decisions that will determine site-level purchasing authority and technology migration speed.
Market Dynamics
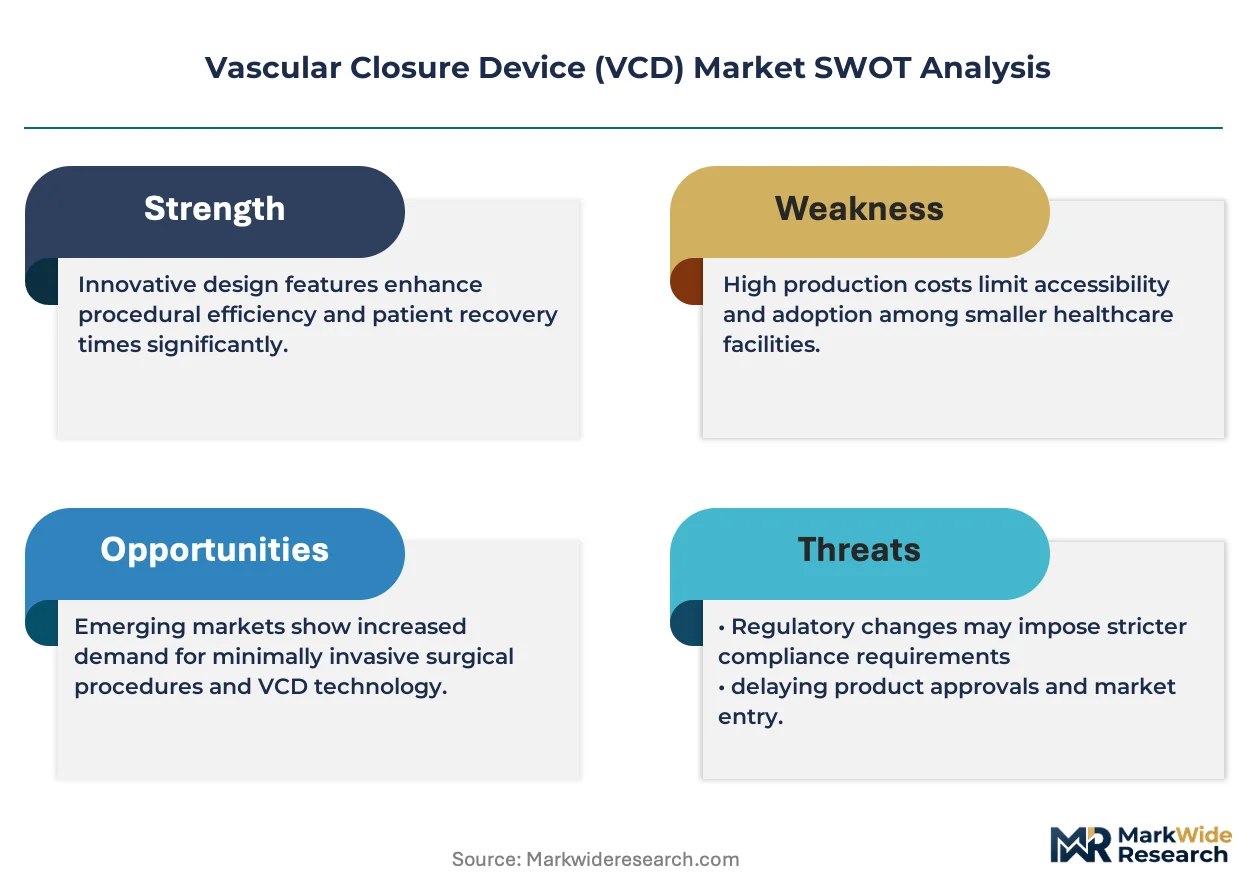
Biodegradable polymer formulations are displacing permanent metal implants across cardiac catheterization workflows, forcing manufacturers to reconfigure R&D priorities and supply chains around resorbable material science.
Growth Catalysts
- FDA 510(k) pathway efficiency:Streamlined premarket notification for predicate-based VCD submissions accelerates product iteration cycles for established manufacturers with robust quality systems.
- Japan's aging demographic density:Concentrated elderly populations in Tokyo and Osaka metropolitan clusters sustain procedural volumes for femoral access closure in interventional cardiology suites.
- Collagen plug biodegradability:Complete resorption eliminating foreign body retention is compressing follow-up imaging requirements and reducing long-term complication management costs.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains cluster around specialized vacuum arc remelting capacity in limited geographic zones, exposing device makers to input volatility.
- EU MDR notified body bottleneck:Technical documentation review capacity constraints extend certification timelines by 12-18 months for new biodegradable platform submissions.
- Manual compression substitution:Zero-device cost alternative retains preference in resource-constrained settings and low-volume catheterization labs, capping premium device penetration.
Strategic Opportunities
- Germany's outpatient procedural migration:Ambulatory cardiac catheterization expansion under DRG reimbursement reform creates demand for rapid-hemostasis closure enabling same-day discharge.
- Radial access protocol standardization:Transradial coronary intervention growth requires smaller-profile 5F-6F closure devices with modified deployment mechanics.
- Digital health integration:Bluetooth-enabled hemostasis monitoring systems paired with closure devices enable remote complication surveillance post-discharge.
Industry Challenges
- Polymer degradation rate calibration:Batch-to-batch variability in collagen crosslinking density complicates shelf-life validation and clinical performance consistency.
- Interventional cardiologist retraining requirements:Biodegradable plug deployment techniques differ substantially from suture-based platforms, necessitating proctored case volumes for competency certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Closure Device (VCD) Market |
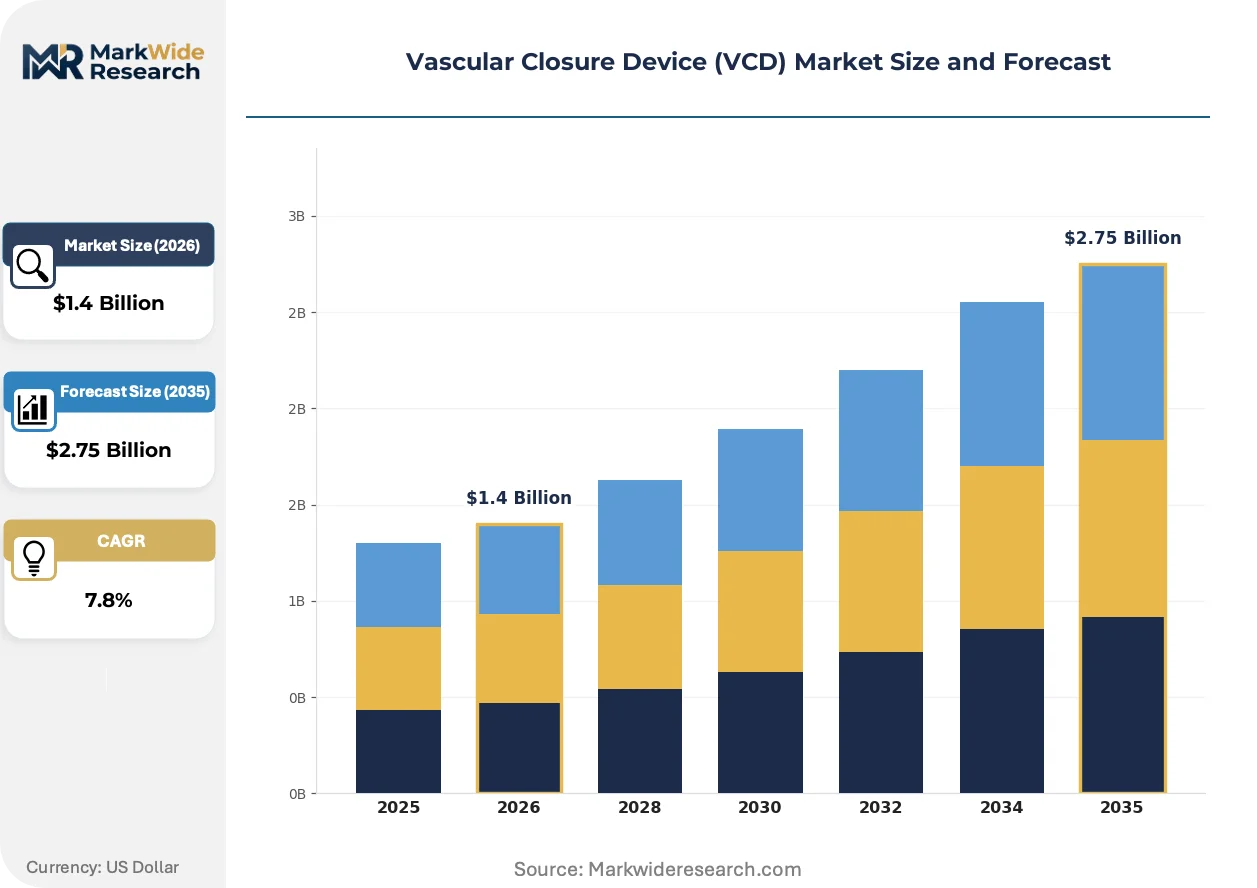
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Closure Devices, Passive Closure Devices, Intrinsic Closure Devices, Adhesive Strips End User: Hospitals, Clinics, Cardiac Centers, Ambulatory Surgical Centers Technology: Mechanical Devices, Biodegradable Devices, Sutured Devices, Spring-Loaded Devices Application: Interventional Cardiology, Peripheral Vascular Procedures, Pediatric Cardiology, Endovenous Procedures |
| Companies Covered | Haemonetics Corporation, Medtronic, Terumo Corporation, Merit Medical Systems, Cordis, Abbott, Cardinal Health, Vivasure Medical Ltd., Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Closure Device (VCD) Market Evolving Landscape
Material science breakthroughs and regulatory data requirements are compressing product lifecycles while elevating clinical evidence thresholds for market access across all major jurisdictions.
Bioresorbable synthetic polymers engineered for tunable degradation kinetics are converging with active closure mechanisms to create hybrid devices that combine immediate mechanical seal with complete material absorption. Academic medical centers in Germany and Japan are piloting these platforms in high-risk anticoagulated patient cohorts. The structural consequence is compression of permanent implant inventory and simplification of post-procedural MRI compatibility protocols.
EU MDR Article 10 technical documentation mandates now require systematic clinical evaluation reports with post-market surveillance integration for all Class IIa and above VCD submissions. This regulatory architecture elevates barrier costs for new entrants while rewarding incumbent manufacturers with established PMCF infrastructure. German notified bodies are prioritizing review capacity for biodegradable platforms, accelerating technology migration speed in that market.
Hospital value analysis committees are consolidating purchasing authority for closure devices into centralized procurement frameworks that bundle cardiac catheterization consumables across quarterly or annual contracts. This channel compression displaces individual physician preference item selection with standardized formulary decisions driven by total procedure cost modeling. The United States exhibits the most advanced committee governance structures, with IDN-level contracting now dominating metropolitan market access.
Vascular Closure Device (VCD) Market Segmentation
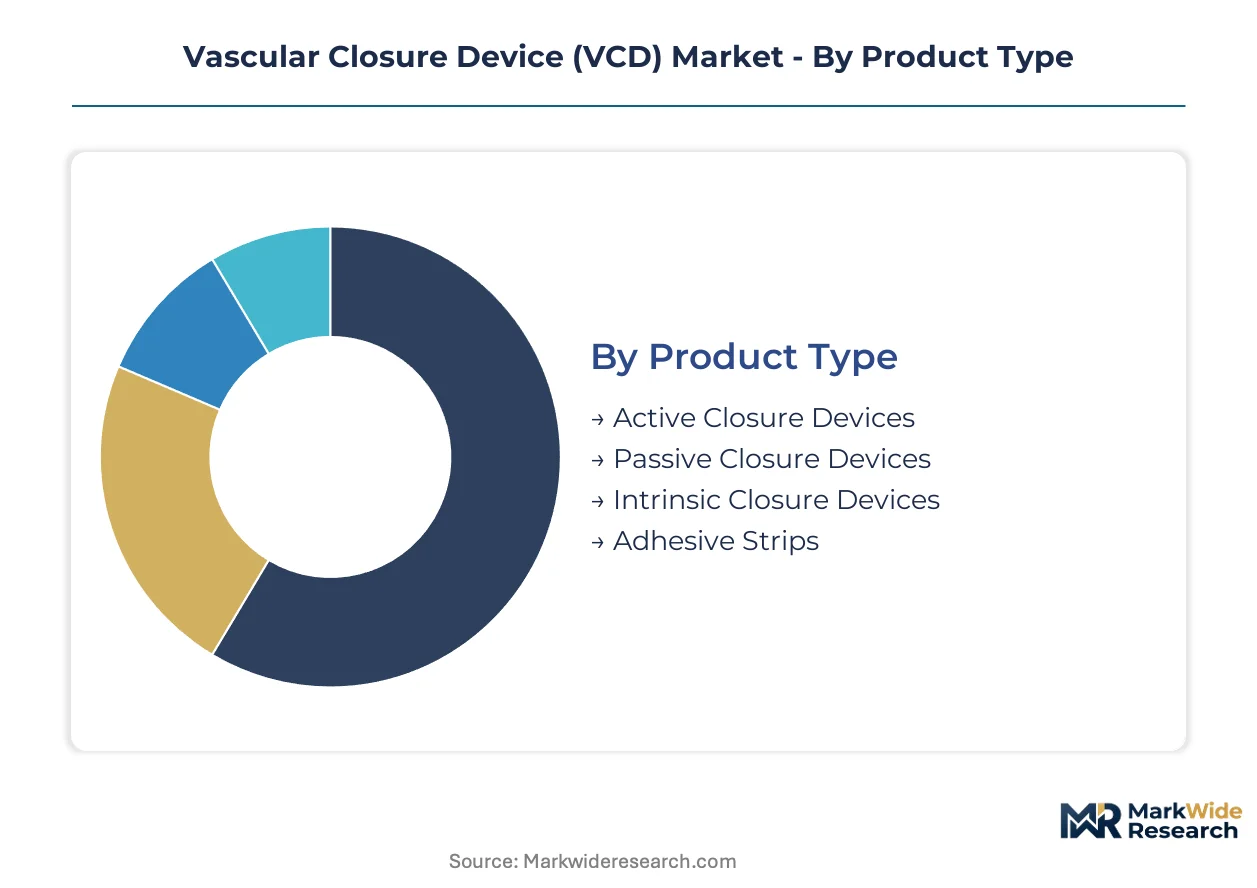
VCD segmentation reveals distinct upgrade cycles across product generations, with active-to-biodegradable transitions reshaping hospital procurement cadences. Technology migration patterns differ materially by access site complexity and anticoagulation protocols, forcing manufacturers to maintain parallel platform portfolios.
Product Type:
Replacement cycles accelerate where mechanical seal performance intersects with resorption timelines, compressing obsolescence windows for first-generation platforms.
- Active Closure Devices:Nitinol clip or suture-based mechanisms deliver immediate arterial seal through mechanical compression. Demand clusters in high-volume cardiac catheterization laboratories across the United States where procedural throughput justifies premium acquisition costs.
- Passive Closure Devices:Collagen or polymer plugs rely on intrinsic coagulation cascade activation without mechanical assist. German outpatient centers favor these for rapid deployment in same-day discharge protocols under DRG reimbursement reform.
- Intrinsic Closure Devices:Procoagulant-impregnated matrices accelerate natural hemostasis without foreign body retention.
- Adhesive Strips:External compression adjuncts for low-risk access sites with minimal arterial puncture diameter.
Volume placements concentrate in Active Closure Devices; the faster expansion belongs to Passive Closure Devices.
End User:
Site-level purchasing authority varies with procedural volume thresholds and value analysis committee maturity.
- Hospitals:Integrated delivery networks dominate procurement through quarterly cardiac catheterization consumable bundles. United States metropolitan clusters exhibit the most centralized formulary governance.
- Cardiac Centers:Specialized interventional suites prioritize device performance consistency over acquisition cost in anticoagulated patient populations. Japanese university hospitals anchor procedural volume in Tokyo and Osaka corridors.
- Clinics:Lower-throughput settings retain manual compression protocols due to capital constraint.
- Ambulatory Surgical Centers:Medicare reimbursement shifts toward outpatient cardiac procedures expand addressable sites.
Revenue concentration sits with Hospitals; Ambulatory Surgical Centers are climbing the fastest.
Technology:
Material science differentiation determines margin structure and regulatory pathway complexity.
- Biodegradable Devices:Synthetic polymer or collagen formulations engineered for tunable resorption kinetics eliminate permanent foreign body retention. FDA 510(k) predicates for resorbable platforms accelerate review timelines for established manufacturers.
- Mechanical Devices:Permanent nitinol or stainless steel implants retain structural integrity indefinitely. EU MDR technical documentation requirements for permanent implants extend certification timelines versus resorbable alternatives.
- Sutured Devices:Manual or automated arterial closure requiring operator-dependent technique mastery.
- Spring-Loaded Devices:Deploy-and-release mechanisms reducing deployment variability.
Installed base remains Mechanical Devices; Biodegradable Devices gain share fastest.
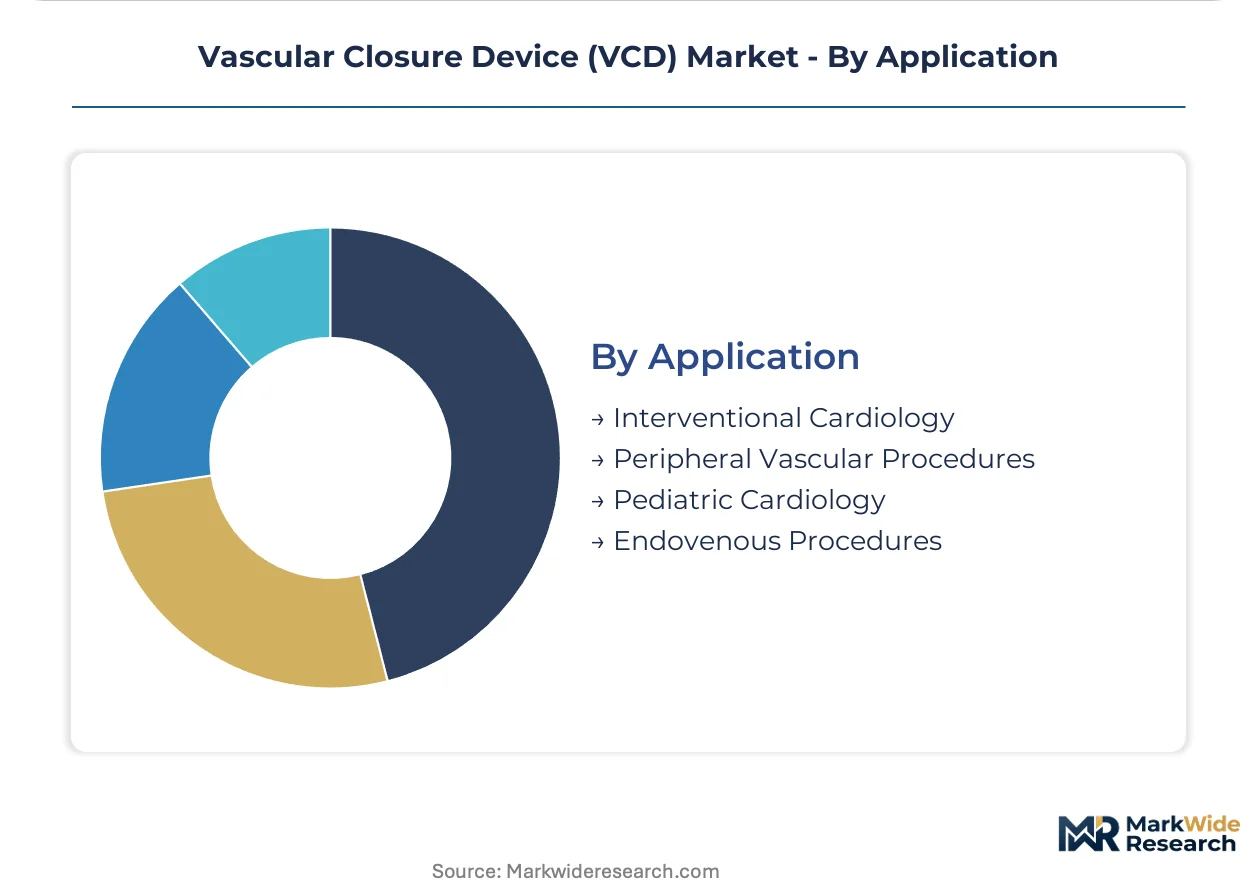
Application:
Procedure-specific hemostasis requirements dictate device selection criteria and complication tolerance.
- Interventional Cardiology:Coronary angiography and percutaneous coronary intervention generate the highest femoral and radial access closure volumes. German statutory health insurance reimbursement rates sustain device utilization despite cost-containment pressure.
- Peripheral Vascular Procedures:Larger access sheaths in endovascular aortic repair demand robust seal mechanisms. Japan's aging demographic density sustains procedural growth in femoropopliteal intervention.
- Pediatric Cardiology:Smaller vessel diameters require modified device profiles with limited commercial scale.
- Endovenous Procedures:Venous access closure exhibits lower device penetration due to compression sufficiency.
Procedure volume concentrates in Interventional Cardiology; Peripheral Vascular Procedures show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized nitinol foundries in Pennsylvania and North Rhine-Westphalia supply superelastic alloys to device manufacturers across three continents. Raw material proximity shapes regional manufacturing footprints and regulatory submission strategies.
United States
Integrated delivery networks in Texas and California consolidate cardiac catheterization procurement through quarterly consumable bundles. FDA 510(k) premarket notification pathways reward established manufacturers with predicate device portfolios. Minneapolis-St. Paul anchors a cluster of interventional cardiology device engineering.
Germany
Outpatient cardiac catheterization migration under DRG reimbursement reform accelerates same-day discharge protocols in Bavarian and Baden-Württemberg cardiac centers. EU MDR notified body capacity constraints extend certification timelines for biodegradable platform submissions. Berlin-Brandenburg hosts technical documentation consultancies serving pan-European regulatory submissions.
Japan
Tokyo and Osaka metropolitan corridors concentrate elderly populations sustaining femoral access closure volumes in university hospital interventional suites. PMDA foreign manufacturer registration requirements elevate barrier costs for new market entrants. Kansai region manufacturing maintains captive suture-based platform production for domestic and export markets.
United Kingdom
NHS England value analysis committees standardize closure device formularies across integrated care systems in Greater London and the Midlands. MHRA post-Brexit regulatory alignment with EU MDR technical documentation extends review parallelism. Oxford-Cambridge corridor academic medical centers pilot bioresorbable synthetic polymer platforms in anticoagulated cohorts.
India
Private hospital chains in Maharashtra and Karnataka expand catheterization laboratory capacity to serve domestic and medical tourism demand. CDSCO medical device rules harmonization with IMDRF standards accelerates import registration for multinational manufacturers. Hyderabad medical device park incubates local component fabrication for global supply chains.
Vascular Closure Device (VCD) Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent manufacturers reconfigure around biodegradable material science. Market structure concentrates among multinational medical technology conglomerates with established cardiovascular divisions, mid-cap specialists with focused interventional portfolios, and regional fabricators serving price-sensitive procurement channels. Three archetypes define competitive positioning: integrated cardiovascular platforms leveraging cath lab bundling, pure-play closure specialists defending technology differentiation, and contract manufacturers supplying private-label devices. M&A activity and technology licensing agreements represent the dominant competitive moves reshaping product pipelines.
Among integrated cardiovascular platforms, Abbott and Medtronic occupy positions exemplifying premium-tier device portfolios with established FDA predicates. Terumo Corporation anchors the Asia-Pacific manufacturing archetype through captive Japanese production. Merit Medical Systems represents North American distribution specialists with direct hospital contracting capabilities. These three named entities illustrate how geographic manufacturing concentration, regulatory pathway mastery, and channel access configuration collectively determine sustainable competitive position without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| Medtronic |
| Terumo Corporation |
| Merit Medical Systems |
| Cordis |
| Abbott |
| Cardinal Health |
| Vivasure Medical Ltd. |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Hospital value analysis committee consolidation into quarterly cardiac catheterization consumable bundles is compressing manufacturer margins and forcing supply chain reconfiguration toward direct contracting models that bypass distributor markups.
Pricing Analysis
Warranty and proctoring service bundling separates premium active closure platforms from unbundled economy-tier passive devices. Three-tier pricing structure across premium, standard, and economy levels reflects FDA predicate status, biodegradable certification, and geographic delivery cost. Price differentiation hinges on clinical evidence depth and reimbursement coding support. Cost compression in the economy tier is intensifying because manual compression substitution retains preference in low-volume catheterization labs.
Supply Chain Analysis
Japan's PMDA foreign manufacturer registration requirements and Germany's EU MDR technical documentation mandates are reshaping sourcing toward domestic-content-compliant regional hubs. Nitinol superelastic alloy supply draws from specialized vacuum arc remelting capacity in Pennsylvania and North Rhine-Westphalia, while collagen biomaterial feedstocks source from Japanese and German pharmaceutical-grade suppliers. Single-source vulnerability concentrates in superelastic alloy refining. Distribution runs through integrated delivery network quarterly bundles in the United States and direct hospital contracting in German cardiac centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where backward control over biodegradable polymer formulations and captive nitinol foundry access determines sustainable margin defense.
For Market Incumbents: To counter biodegradable platform commoditization from emerging Korean and Chinese contract manufacturers, Abbott and Terumo must deepen captive production of resorbable collagen matrices and secure exclusive suture-based deployment mechanism licensing. FDA 510(k) predicate accumulation and EU MDR notified body relationship investment remain critical defensive levers. For New Entrants and Emerging Players: CDSCO medical device rules harmonization with IMDRF standards in India opens a window for import-registration-fast-track entry into Maharashtra and Karnataka private hospital chains. Target ambulatory surgical centers in Germany's DRG-reformed outpatient cardiac catheterization migration. Pursue private-label supply agreements with Merit Medical Systems' North American distribution infrastructure. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with biodegradable material science platforms and established PMCF infrastructure. Long-term viability centers on resorbable polymer degradation rate calibration capabilities and German notified body certification relationships. Monitor EU MDR Article 10 technical documentation review capacity expansion as inflection signal for technology migration speed.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate-based pathways accelerate biodegradable platform iteration cycles for established quality systems. |
| CE Marking Pathway | EU MDR technical documentation mandates elevate barrier costs while rewarding incumbent PMCF infrastructure. |
| Hospital System Partnership | IDN-level quarterly bundling contracts displace physician preference items with standardized formulary decisions. |
| Biodegradable Polymer Development | Tunable resorption kinetics eliminate foreign body retention and compress follow-up imaging protocols. |
| Reimbursement Strategy | CMS procedural coding decisions determine site-level purchasing authority and technology migration speed. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR certification bottlenecks, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with interventional cardiologists, biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs directors at cardiovascular device manufacturers. Secondary validation drew from FDA premarket notification databases, EUDAMED device registrations, CMS Medicare procedure volume data, and German statutory health insurance reimbursement rate filings. Bottom-up device placement modeling and top-down cardiac catheterization procedural volume estimates were triangulated.
Input-output matrices mapped biodegradable polymer formulation costs, nitinol raw material pricing, and regulatory compliance expenditure against hospital procurement willingness-to-pay thresholds across the projection horizon. Segmentation dimensions modeled included product type, end user facility tier, technology platform, and application procedure category. CAGRs were derived from procedure volume elasticity to aging demographic density and reimbursement policy shifts. Forecast inputs incorporated PMDA foreign manufacturer registration queue lengths and EU notified body capacity utilization rates.
Caveats apply where EU MDR technical documentation review backlogs, nitinol supply disruptions, or radial access protocol standardization acceleration could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Medical Face Shield Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Membrane Oxygenators Market