
 Medical Vending Machines Market | 2026-2036
Medical Vending Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Vending Machines Market Outlook
The gap between premium automated dispensing systems and basic commodity units is expanding. Omnicell, Inc. leverages its software-integrated platform to dominate the high-reliability hospital segment, while ScriptPro LLC anchors its position through specialized outpatient pharmacy automation. InstyMeds Corporation competes in the compact, clinic-deployable tier where space constraints and lower capital budgets define purchasing criteria.
Medical vending machines are electromechanical dispensing systems engineered with biometric authentication, temperature-controlled compartments, and real-time inventory tracking to distribute pharmaceuticals and medical supplies in regulated healthcare environments. These units typically operate within 2-8°C cold-chain parameters for temperature-sensitive medications and integrate with hospital information systems for audit-trail compliance. The pharmaceuticals product type commands the deepest margin pools due to controlled-substance tracking requirements, while remote monitoring technology is displacing basic touchscreen models as health systems prioritize centralized fleet management. Emergency services as an end user represents the fastest-growing deployment channel, driven by 24/7 access needs in ambulance bays and fire stations where traditional pharmacy hours create operational gaps.
FDA 510(k) clearance requirements shape product development timelines and capital allocation for manufacturers targeting the United States, while ISO 13485 quality management standards govern design controls for software-integrated medical devices across international markets. The EU Medical Device Regulation imposes post-market surveillance obligations that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must weigh the trade-off between cloud-connected inventory platforms and cybersecurity hardening as healthcare ransomware incidents reshape procurement specifications.
Market Dynamics
Hospital pharmacy consolidation is compressing vendor relationships into multi-year fleet contracts, forcing equipment manufacturers to embed software subscriptions and remote diagnostics into hardware pricing to defend account tenure.
Growth Catalysts
- Biometric authentication mandates:The FDA 510(k) pathway for Class II medical devices is accelerating clearance timelines for fingerprint-integrated dispensing units, reducing commercialization friction for manufacturers targeting acute care settings.
- Emergency services deployment:Fire stations and ambulance bays in the United States are installing compact refrigerated units to close 24/7 pharmaceutical access gaps created by traditional pharmacy hour limitations.
- Cold-chain compliance requirements:Temperature-sensitive biologics are driving replacement cycles for non-refrigerated legacy cabinets, with 2-8°C controlled compartments becoming standard specification in oncology and infusion center environments.
Market Restraints
- Stainless steel and electronic component volatility:Input cost swings for medical-grade enclosures and IoT sensors are compressing gross margins on mid-tier dispensing systems, forcing manufacturers to absorb price increases or risk share loss.
- Cybersecurity hardening requirements:Healthcare ransomware incidents are extending procurement cycles as hospital IT departments impose network isolation protocols and penetration testing mandates on connected inventory platforms.
- ISO 13485 certification complexity:Small manufacturers lacking dedicated quality management infrastructure face 12-18 month design control documentation timelines, creating barriers to software-integrated product launches.
Strategic Opportunities
- Retail clinic expansion:MinuteClinic and urgent care chains in the United States are deploying compact, script-dispensing units to reduce patient wait times and capture pharmacy revenue previously routed to external retail locations.
- EU MDR post-market surveillance:The Medical Device Regulation's vigilance reporting obligations are favoring established players with regulatory affairs teams, creating acquisition opportunities for compliant mid-tier manufacturers.
- AI-powered inventory forecasting:Machine learning demand prediction is converging with automated dispensing to reduce stockout events in hospital pharmacies, with early adopters seeing working capital improvements.
Industry Challenges
- Biomedical engineering talent scarcity:The intersection of mechanical design, embedded software, and FDA regulatory expertise is creating hiring bottlenecks for manufacturers scaling connected device portfolios.
- Legacy HIS integration complexity:Hospital information system interoperability remains fragmented, with Epic and Cerner implementations requiring 6-9 month custom interface development for real-time inventory synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Vending Machines Market |
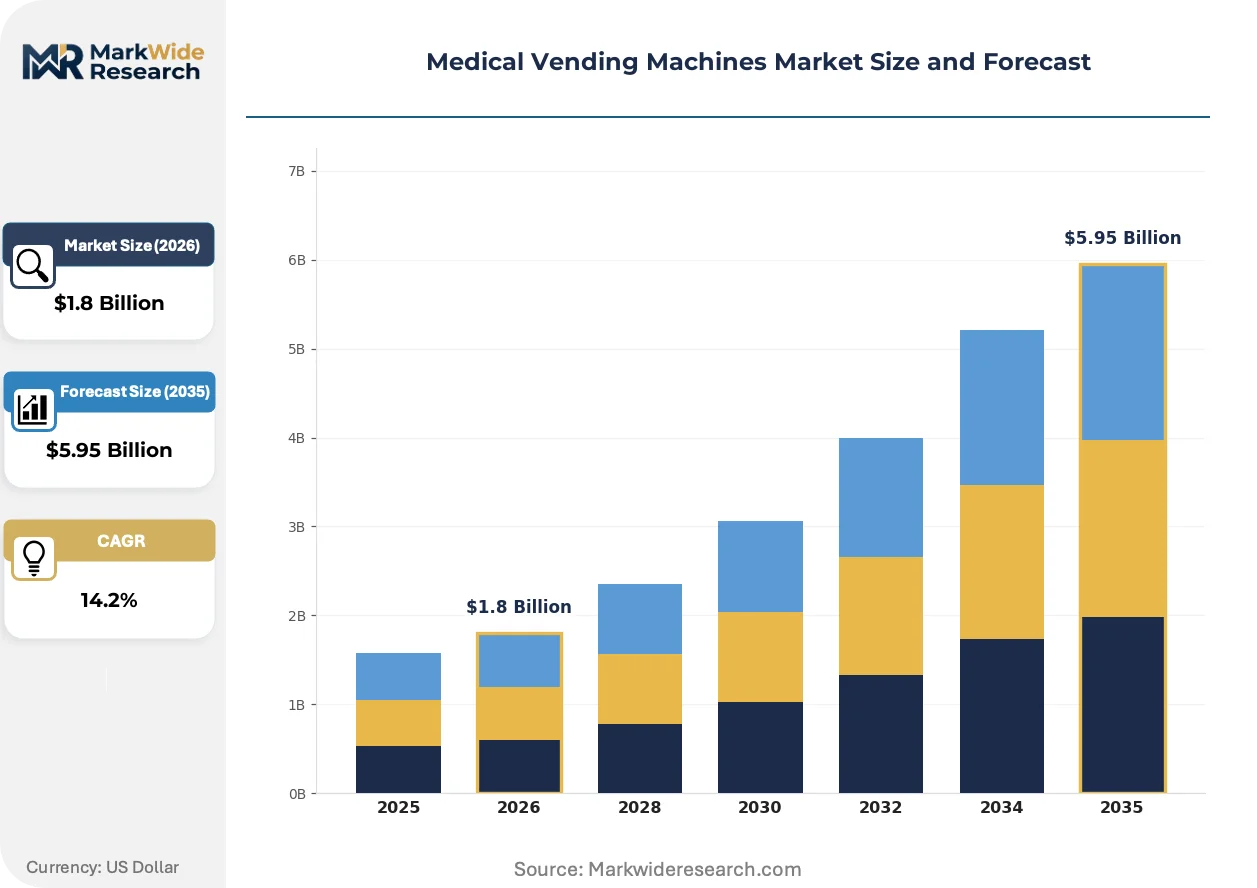
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Medical Supplies, Nutritional Products, Personal Care Items End User: Hospitals, Clinics, Pharmacies, Emergency Services Technology: Touchscreen Interface, Cashless Payment, Remote Monitoring, Inventory Management Distribution Channel: Online, Direct Sales, Partnerships, Franchise Models |
| Companies Covered | Pharmashop24 Srl, Omnicell, Inc, InstyMeds Corporation, ScriptPro LLC, Parata Systems, Xenco Medical, Capsa Healthcare, Intelligent Dispensing Solutions, Magex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Vending Machines Market Strategic Shifts
Cloud-connected fleet management platforms are displacing standalone touchscreen interfaces as health systems prioritize centralized oversight of distributed dispensing assets across multi-site networks.
Computer vision verification systems are expanding into high-risk medication dispensing workflows, using optical character recognition and barcode scanning to reduce human verification errors in chemotherapy and anticoagulant distribution. Oncology pharmacies at academic medical centers are piloting these systems ahead of broader hospital pharmacy adoption. The technology is expanding into regulatory documentation, automatically generating audit trails that satisfy Joint Commission inspection requirements.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing manufacturers to redesign labeling and traceability systems for European market access. Serialization requirements are extending production lead times and increasing per-unit compliance costs. Software-integrated dispensing systems with built-in UDI management capabilities are capturing preference share in German and French hospital procurement tenders.
Subscription-based service models are replacing traditional capital equipment sales in health system purchasing, with vendors bundling hardware, software, maintenance, and consumables into per-dispense or per-site monthly fees. This shift transfers utilization risk to manufacturers while locking in multi-year revenue streams. The model is most advanced in United States integrated delivery networks with centralized pharmacy automation budgets.
Medical Vending Machines Market Segmentation
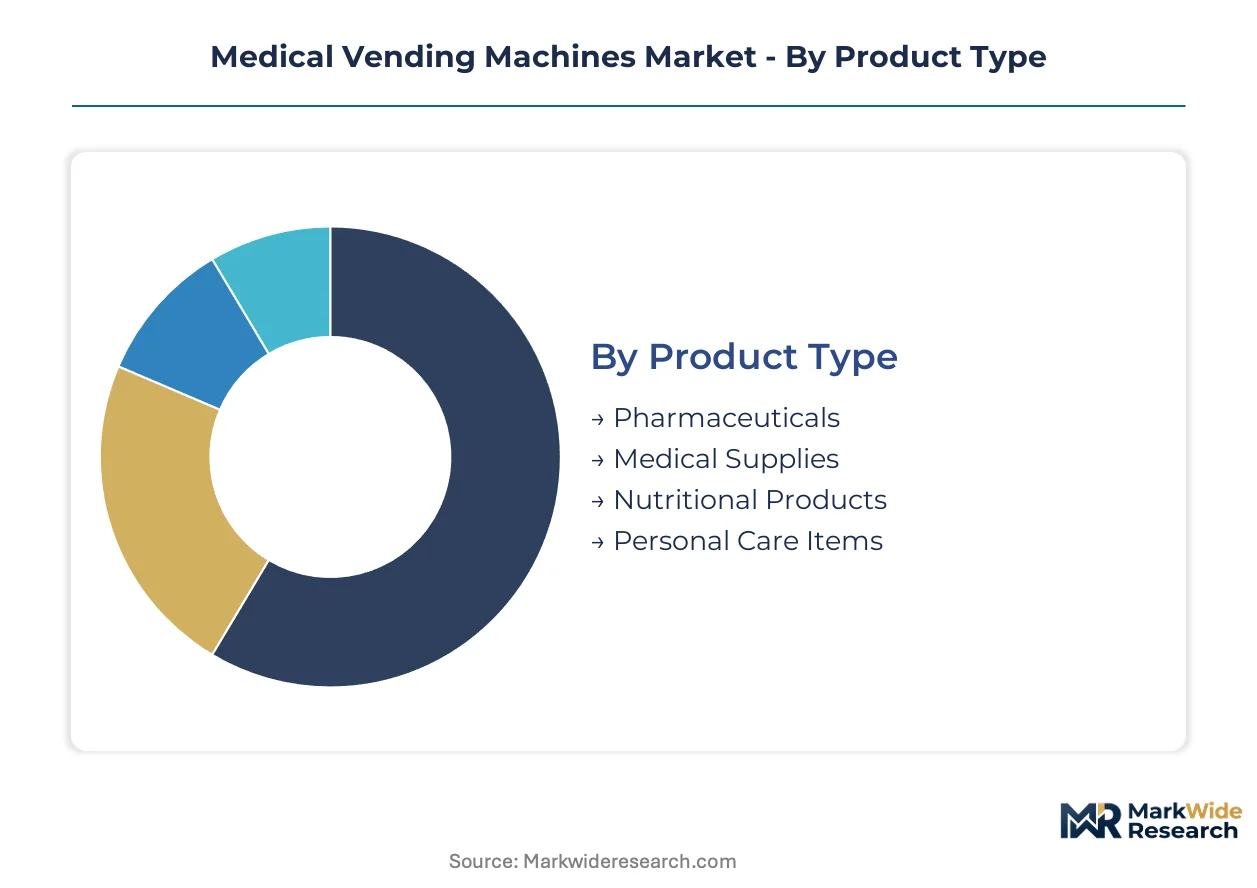
Segmentation in medical vending machines reveals distinct procurement patterns across product types and deployment settings. Hospital pharmacy consolidation favors integrated technology platforms, while emergency services drive demand for compact, ruggedized units.
Product Type:
Supply concentration tilts toward segments with regulatory complexity and recurring revenue potential.
- Pharmaceuticals:Temperature-controlled dispensing systems with biometric authentication and controlled-substance tracking capabilities. Hospital oncology and infusion centers in the United States demand 2-8°C cold-chain compliance for biologics, with FDA 510(k) clearance requirements filtering vendor pools.
- Medical Supplies:Electromechanical cabinets distributing syringes, wound care kits, and PPE through automated inventory tracking. Ambulance bays and fire stations prioritize 24/7 access with minimal supervision, driving compact footprint specifications.
- Nutritional Products:Standard ambient-temperature units serving outpatient clinics and retail health settings.
- Personal Care Items:Basic dispensing solutions for wellness centers and employee health programs with lower compliance burdens.
Pharmaceuticals absorbs the bulk of installed capacity; emergency services deployment is expanding most quickly.
End User:
Procurement scale varies dramatically by institutional budget cycles and regulatory oversight intensity.
- Hospitals:Enterprise-grade automated dispensing cabinets integrating with Epic and Cerner hospital information systems for real-time inventory synchronization. Academic medical centers pilot computer vision verification for chemotherapy workflows ahead of broader adoption.
- Emergency Services:Refrigerated compact units deployed in ambulance bays and fire stations to close pharmaceutical access gaps outside traditional pharmacy hours. United States municipalities favor ruggedized enclosures with biometric access.
- Clinics:Mid-tier systems serving urgent care chains and retail health locations with space-constrained footprints.
- Pharmacies:Outpatient-focused automation reducing labor costs in high-volume dispensing environments.
Hospitals command the deepest capital budgets; emergency services is climbing the fastest.
Technology:
Feature differentiation increasingly centers on connectivity architecture and cybersecurity posture.
- Remote Monitoring:Cloud-connected fleet management platforms enabling centralized oversight across multi-site health networks. United States integrated delivery networks prioritize network isolation protocols following healthcare ransomware incidents.
- Inventory Management:AI-powered demand forecasting reducing stockout events through machine learning algorithms. Early hospital pharmacy adopters report working capital improvements from predictive replenishment.
- Touchscreen Interface:Legacy standalone interfaces being displaced by connected platforms in fleet renewal cycles.
- Cashless Payment:Payment integration for retail-facing deployments in urgent care and clinic settings.
Inventory management dominates new installations; remote monitoring is gaining share fastest.
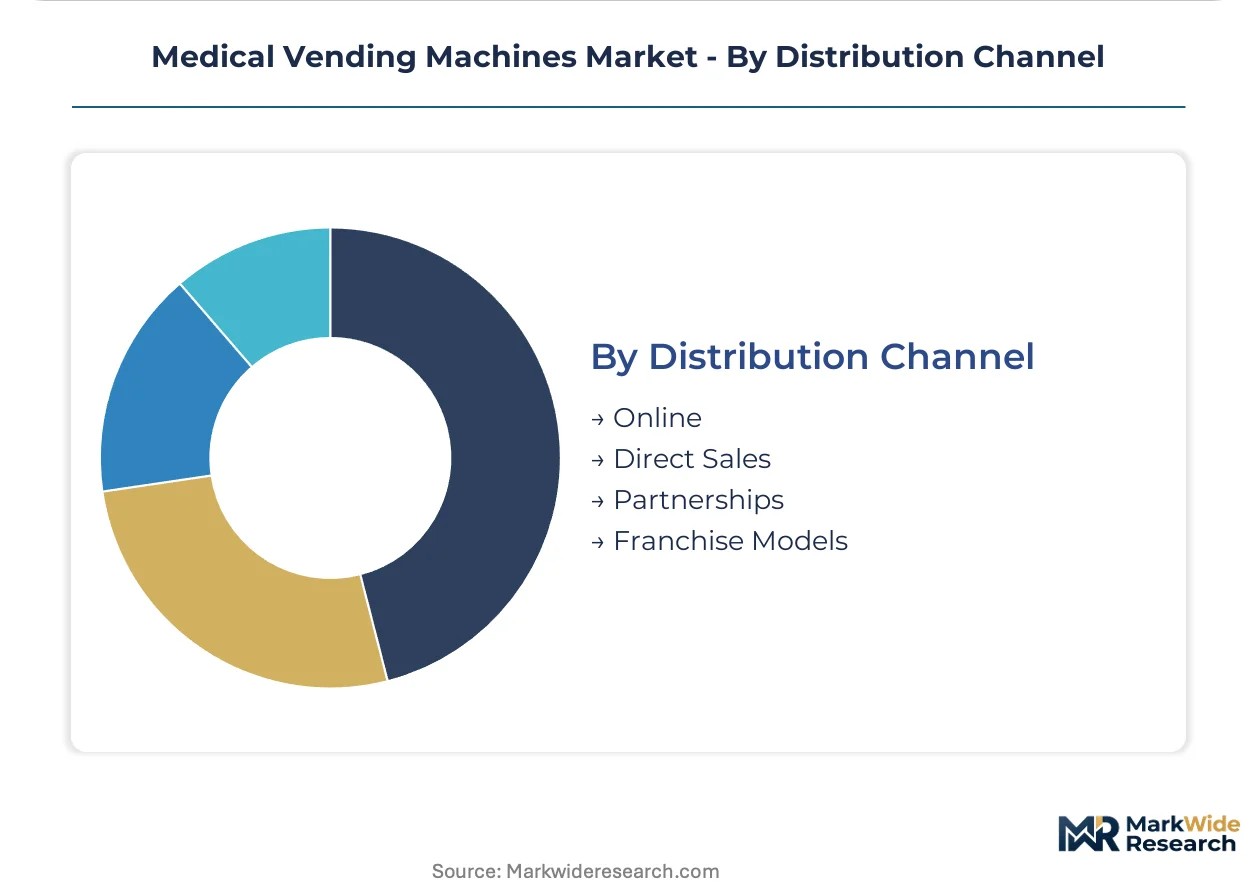
Distribution Channel:
Channel strategy reflects the shift from capital equipment sales toward recurring revenue models.
- Direct Sales:Multi-year fleet contracts bundling hardware, software subscriptions, and remote diagnostics. Health system consolidation in the United States compresses vendor relationships into centralized procurement.
- Partnerships:Strategic alliances with hospital information system vendors and pharmacy automation integrators. ISO 13485 certification requirements favor established players with dedicated quality infrastructure.
- Online:Digital procurement channels serving smaller clinics and independent pharmacy operators.
- Franchise Models:Emerging channel for retail health and corporate wellness deployments with standardized unit configurations.
Direct sales captures the largest contract value; partnerships is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-Saint Paul corridor anchors North American medical vending machine deployment, where health system consolidation drives centralized pharmacy automation procurement across multi-hospital networks.
United States
Hospital pharmacy automation absorbs the deepest capital investment, with integrated delivery networks consolidating vendor relationships into multi-year fleet contracts. FDA 510(k) clearance pathways for Class II medical devices streamline commercialization timelines for biometric-authenticated dispensing units. The Texas Medical Center in Houston pilots computer vision verification systems for chemotherapy workflows ahead of broader academic medical center adoption.
Germany
EU Medical Device Regulation post-market surveillance obligations favor established manufacturers with dedicated regulatory affairs infrastructure. The country's national pharmaceutical regulator enforces serialization requirements that extend production lead times for software-integrated dispensing systems. The Rhine-Ruhr metropolitan region concentrates hospital pharmacy automation procurement, with university hospitals in Düsseldorf and Cologne driving early adoption of AI-powered inventory forecasting platforms.
Japan
Aging demographics and pharmacist workforce shortages accelerate deployment of automated dispensing cabinets in acute care settings. PMDA quality management standards govern design controls for connected medical devices, filtering vendor pools toward ISO 13485-certified manufacturers. The Kansai region surrounding Osaka anchors domestic production capacity, with medical device clusters in Kyoto and Kobe supplying temperature-controlled units for biologics distribution.
United Kingdom
NHS pharmacy consolidation creates procurement scale for enterprise-grade automated dispensing systems integrating with electronic health record infrastructure. MHRA medical device regulations align with EU MDR vigilance reporting obligations, extending compliance documentation requirements for cloud-connected inventory platforms. The Cambridge-Oxford-London golden triangle concentrates health technology procurement decision-making, with academic medical centers piloting remote monitoring fleet management ahead of national rollout.
India
CDSCO medical device registration requirements are tightening quality management expectations for imported pharmacy automation equipment. The country's national pharmaceutical regulator is harmonizing with international standards, creating compliance barriers for uncertified manufacturers. The Mumbai-Pune pharmaceutical corridor drives demand for compact clinic-deployable units, with hospital chains in Maharashtra accelerating outpatient pharmacy automation to reduce labor costs.
Medical Vending Machines Market Competitive Environment
Premium-margin players sit above commodity-margin players across software integration depth and regulatory certification breadth. The vendor base stratifies into three tiers: enterprise platform providers commanding multi-hospital fleet contracts, specialized outpatient automation suppliers, and compact clinic-deployable unit manufacturers. Strategic archetypes include software-integrated platform builders, regulatory compliance specialists, and space-constrained deployment optimizers. Competitive moves center on embedding subscription services into hardware pricing and acquiring ISO 13485-certified mid-tier manufacturers to accelerate EU market access.
Within the software-integrated platform tier, Omnicell, Inc. and ScriptPro LLC exemplify divergent specialization vectors. Omnicell anchors the high-reliability hospital segment through enterprise fleet management capabilities, while ScriptPro occupies a position in outpatient pharmacy automation where script volume throughput determines competitive standing. InstyMeds Corporation represents the compact deployment archetype, with clinic-focused units addressing space constraints and lower capital budgets outside acute care settings.
| Leading Market Players |
|---|
| Pharmashop24 Srl |
| Omnicell, Inc |
| InstyMeds Corporation |
| ScriptPro LLC |
| Parata Systems |
| Xenco Medical |
| Capsa Healthcare |
| Intelligent Dispensing Solutions |
| Magex |
| Others |
Value Chain & Pricing Dynamics
Cloud-connected fleet management platforms are compressing hardware margins while concentrating procurement power among integrated delivery networks with multi-site standardization requirements. Biometric authentication modules and cold-chain refrigeration systems now constitute the dominant cost stack, with FDA 510(k) clearance investments filtering vendor pools toward capital-rich manufacturers capable of absorbing extended design control timelines.
Pricing Analysis
Per-dispense subscription pricing tied to uptime guarantees anchors enterprise health system contracts, displacing traditional capital equipment sales. Three-tier pricing structure across premium software-integrated platforms, standard connected cabinets, and basic touchscreen units reflects certification depth and HIS interoperability scope. Cost compression in mid-tier systems intensifies because stainless steel enclosure and IoT sensor input volatility forces manufacturers to absorb margin erosion or cede share to Asian competitors. Emergency services municipalities exhibit highest price sensitivity due to constrained municipal budgets, while academic medical centers prioritize reliability metrics over unit economics.
Supply Chain Analysis
Domestic-content mandates in United States federal healthcare procurement are reshaping sourcing patterns for electromechanical components and embedded software development. Medical-grade stainless steel fabrication concentrates in Germany, Japan, and the United States, while semiconductor and sensor module production draws from Taiwan, South Korea, and China. Single-source vulnerability in biometric sensor supply creates exposure to geopolitical disruption, with fingerprint module lead times extending during semiconductor allocation cycles. Distribution runs through direct sales teams for enterprise hospital contracts and GPO partnerships for mid-tier clinic deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
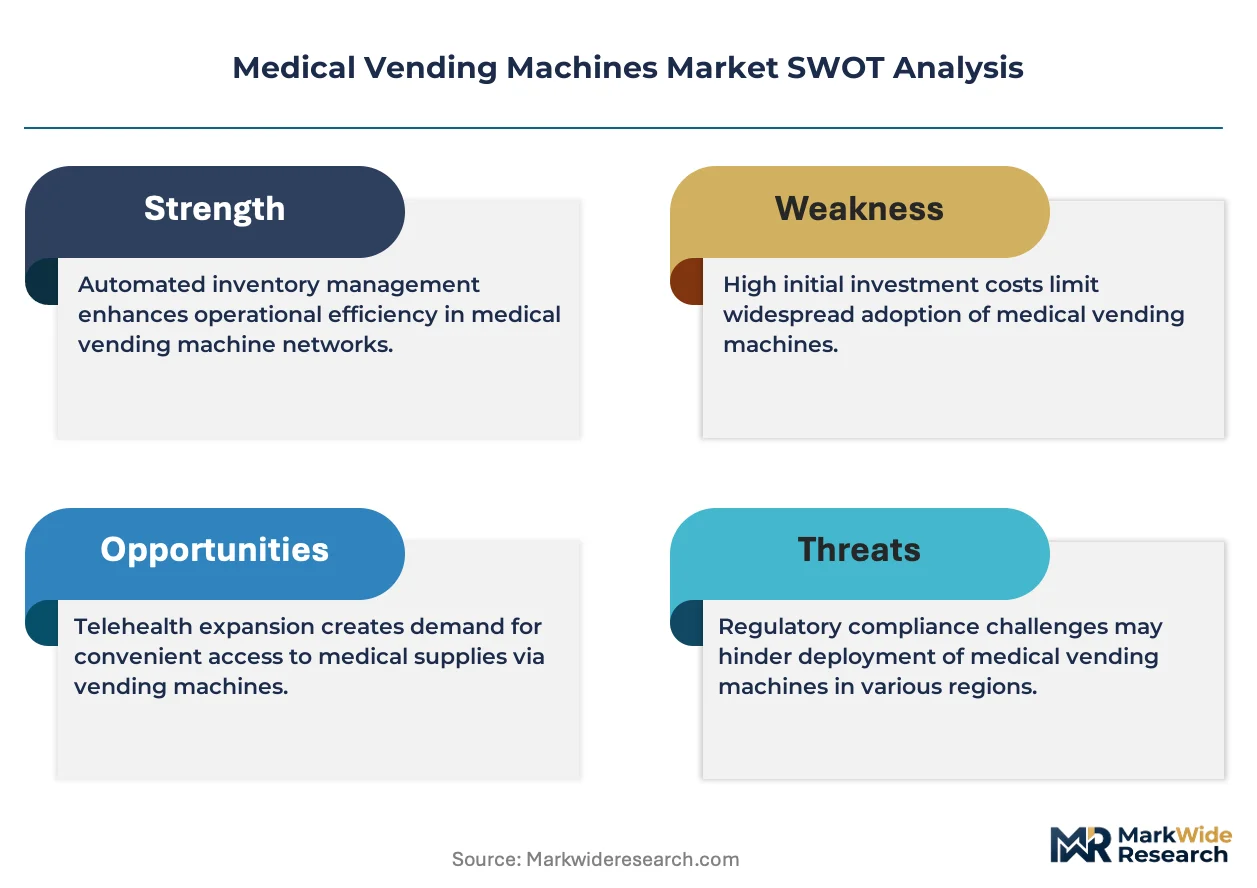
This market reads as a cost-of-compliance story where ISO 13485 certification and FDA 510(k) clearance infrastructure create barrier-to-entry moats that favor capitalized incumbents over bootstrap competitors.
For Market Incumbents: Acquire ISO 13485-certified mid-tier manufacturers with established EU MDR vigilance reporting capabilities to accelerate European market penetration. Consolidate biomedical engineering talent pools through targeted recruitment in Minneapolis-Saint Paul and Rhine-Ruhr medical device clusters. Defensive positioning requires embedding AI-powered inventory forecasting into base platform subscriptions before specialized analytics vendors capture pharmacy workflow integration. For New Entrants and Emerging Players: Launch via compact clinic-deployable units targeting urgent care chains and retail health settings where space constraints and lower capital budgets define purchasing criteria. White-space concentration sits in fire station and ambulance bay deployments across United States municipalities seeking 24/7 pharmaceutical access outside traditional pharmacy hours. Go-to-market traction depends on ruggedized enclosure specifications and biometric access integration at price points below enterprise hospital tiers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hospital information system vendors seeking vertical integration into pharmacy automation workflows. Five-to-ten year viability hinges on software subscription attach rates exceeding hardware replacement cycles. Acquisition target archetype: mid-tier manufacturers with ISO 13485 certification and established GPO contracts but limited AI analytics capabilities. Signal to watch: health system ransomware incidents accelerating network isolation procurement specifications that favor hardened incumbent platforms over emerging connected entrants.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management infrastructure unlocks EU MDR market access and filters vendor pools in German hospital tenders. |
| AI-Powered Inventory Forecasting Integration | Machine learning demand prediction reduces working capital requirements for hospital pharmacy adopters. |
| Hospital Information System Partnership | Epic and Cerner interoperability agreements compress 6-9 month custom interface development timelines. |
| Biometric Authentication Module Development | FDA 510(k) clearance for fingerprint-integrated units accelerates commercialization in acute care settings. |
| Emergency Services Channel Expansion | Compact refrigerated units address 24/7 access gaps in United States fire stations and ambulance bays. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital pharmacy directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at FDA-cleared manufacturers. FDA 510(k) premarket notification database, EU EUDAMED vigilance reports, hospital procurement databases, and GPO contract disclosures provided device-level segmentation granularity. Bottom-up unit deployment estimates triangulated against top-down health system capital expenditure surveys.
Segmentation-level modeling captured product type, end user, technology architecture, and distribution channel dimensions across the analysis window. CAGRs derived from logistic diffusion curves fitted to historical adoption rates in comparable medical device categories. Forecast inputs incorporated health system consolidation velocity, cold-chain biologics growth trajectories, and cybersecurity hardening procurement specification shifts.
Regulatory timeline delays, healthcare ransomware incident frequency, and hospital IT budget allocation shifts are the dominant revision risks to deployment assumptions. Forecasts reflect documented assumptions regarding FDA clearance pathway efficiency and EU MDR post-market surveillance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Tubing Market
Medical Equipment
Global Steam Autoclaves Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Cath Lab Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Autopsy Equipment Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market