
 Testicular Implants (Prosthesis) Market | 2026-2036
Testicular Implants (Prosthesis) Market Size, Share, and Industry Trends Forecast 2026-2036
Testicular Implants (Prosthesis) Market Insights
A shortage of reconstructive urologists is reorganizing how manufacturers allocate clinical training resources and field support teams. Coloplast leverages its direct hospital channel infrastructure to sustain premium positioning across Nordic markets. Rigicon competes through specialized silicone formulations that anchor its technical reputation among European surgeons. Groupe Sebbin SAS dominates French domestic procurement through long-standing institutional relationships with public hospital networks.
Testicular implants (prosthesis) are medical devices surgically placed to restore anatomical contour and psychological function following orchiectomy or congenital absence, typically constructed from medical-grade silicone elastomer with saline or solid gel fill to achieve physiological weight and texture. The primary commercial purpose centers on restoring patient quality of life and body image integrity in post-oncological and transgender healthcare pathways. Silicone-based products occupy the dominant value share due to established biocompatibility profiles and surgeon familiarity, while saline alternatives capture niche demand in cost-sensitive procurement environments where reversibility and adjustability carry clinical weight. Hospital end users concentrate the highest procedure volumes, though specialty centers are extending reach into outpatient andrology services.
FDA 510(k) clearance pathways and EU MDR Class IIa device requirements shape product development timelines and material documentation burdens for manufacturers seeking transatlantic market access. ISO 10993 biocompatibility testing standards and REACH silicone monomer restrictions further constrain formulation choices and supplier qualification processes. Stakeholders must monitor evolving FDA guidance on long-term implantable silicone devices alongside EMA post-market surveillance expectations to anticipate compliance cost escalations.
Market Dynamics
EU MDR Class IIa device documentation burdens and FDA 510(k) pathway modifications are compressing product development timelines while forcing manufacturers toward specialized silicone formulation partnerships.
Growth Catalysts
- Post-oncological reconstruction protocols:Hospital urology departments in Germany are expanding dedicated andrology units to address rising testicular cancer survivor volumes seeking restorative procedures.
- REACH silicone monomer standards:Stricter ECHA material purity requirements are accelerating supplier consolidation toward certified medical-grade elastomer producers.
- Transgender healthcare pathway formalization:France's public hospital networks are integrating prosthetic placement into standardized gender-affirming surgical sequences.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical producers in Germany control 70% of implant-grade elastomer feedstock, creating input vulnerability.
- EU MDR technical documentation burden:Class IIa device conformity assessment timelines have extended from 12 to 22 months, freezing pipeline releases.
- Reconstructive urologist scarcity:Fellowship-trained specialists number fewer than 400 across the United States, constraining procedural capacity expansion.
Strategic Opportunities
- Outpatient andrology center expansion:Ambulatory surgical facilities in Texas and Florida are building dedicated prosthetic placement capabilities outside hospital cost structures.
- ISO 10993-23 in vitro testing adoption:Alternative biocompatibility validation methods are reducing animal testing dependencies and accelerating European market entry.
- Saline-filled adjustable devices:Reversible implant designs are capturing pediatric and adolescent patient segments where anatomical growth necessitates future revision.
Industry Challenges
- FDA long-term implantable silicone guidance compliance:Evolving post-market surveillance requirements are forcing manufacturers to rebuild clinical follow-up infrastructure.
- Surgeon training program scaling:Proctoring capacity for silicone handling and placement technique certification lags behind device innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testicular Implants (Prosthesis) Market |
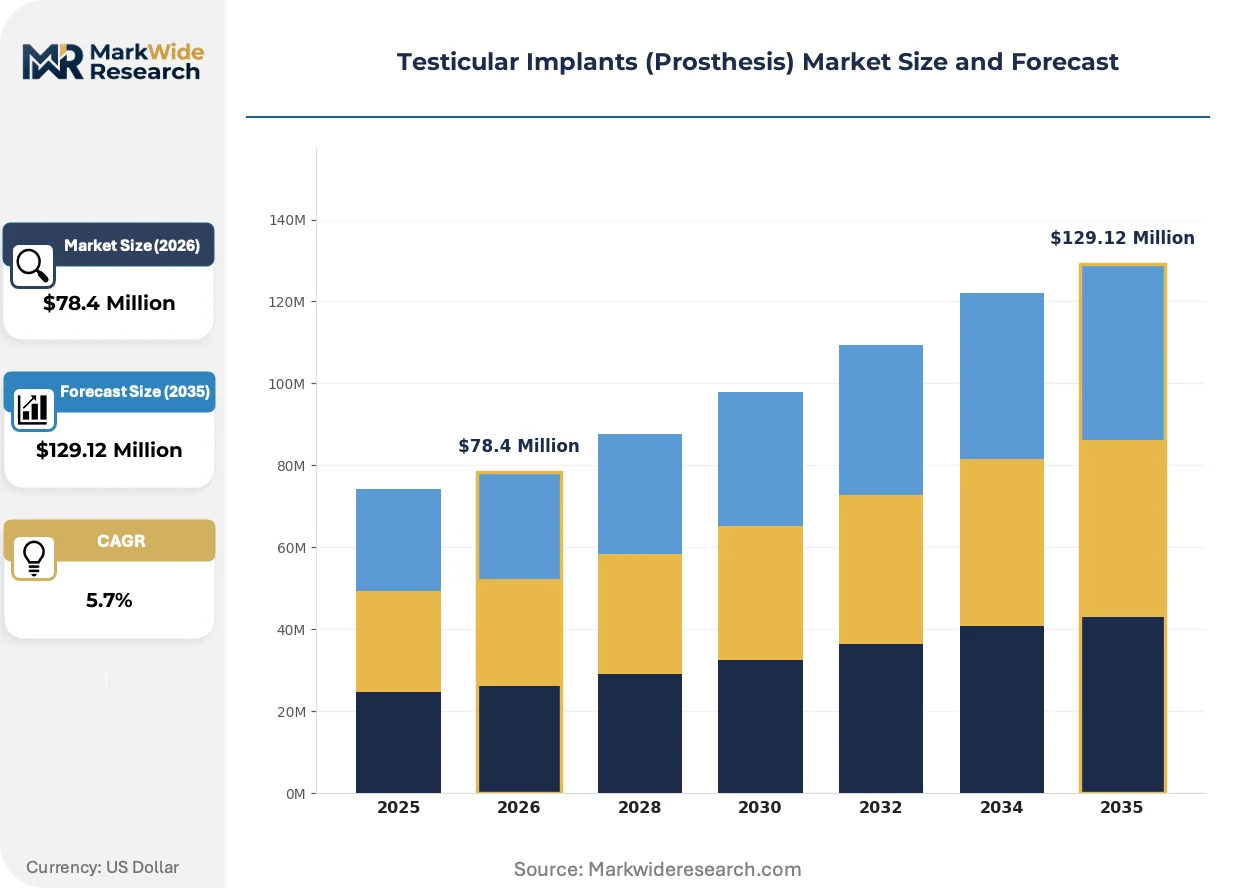
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $129.12 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Saline, Polyurethane, Others End User: Hospitals, Clinics, Specialty Centers, Home Care Manufacturing Stage: Raw Material Processing, Quality Control, Assembly, Packaging Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Wholesalers |
| Companies Covered | Groupe Sebbin SAS, Rigicon, Coloplast, UROMED, Implantech, Polytech Health & Aesthetics, GC Aesthetics, Alpha Aesthetics, Promedon GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testicular Implants (Prosthesis) Market Trends and Innovations
Silicone surface engineering and digital surgical planning tools are fragmenting traditional procurement patterns while compressing the gap between device specification and anatomical customization.
Customized 3D-printed silicone molds are fragmenting the standard implant sizing paradigm. Academic medical centers in Boston and Heidelberg are adopting patient-specific contour matching for complex congenital cases. This capability is fragmenting volume concentration away from mass-produced SKUs toward low-batch production partnerships.
EMA post-market surveillance expectations for long-term implantables are tightening adverse event reporting granularity. Manufacturers must now submit annual safety update reports with 10-year follow-up data. French and German notified bodies are rejecting submissions lacking real-world evidence registries, forcing portfolio prioritization toward devices with existing clinical track records.
Direct-to-hospital contracting is displacing distributor intermediaries in high-volume procurement environments. Nordic hospital purchasing consortia are negotiating multi-year silicone implant supply agreements with embedded training provisions. This pattern is most visible in Denmark and Sweden where centralized procurement authorities aggregate demand across regional health systems.
Testicular Implants (Prosthesis) Market Segmentation
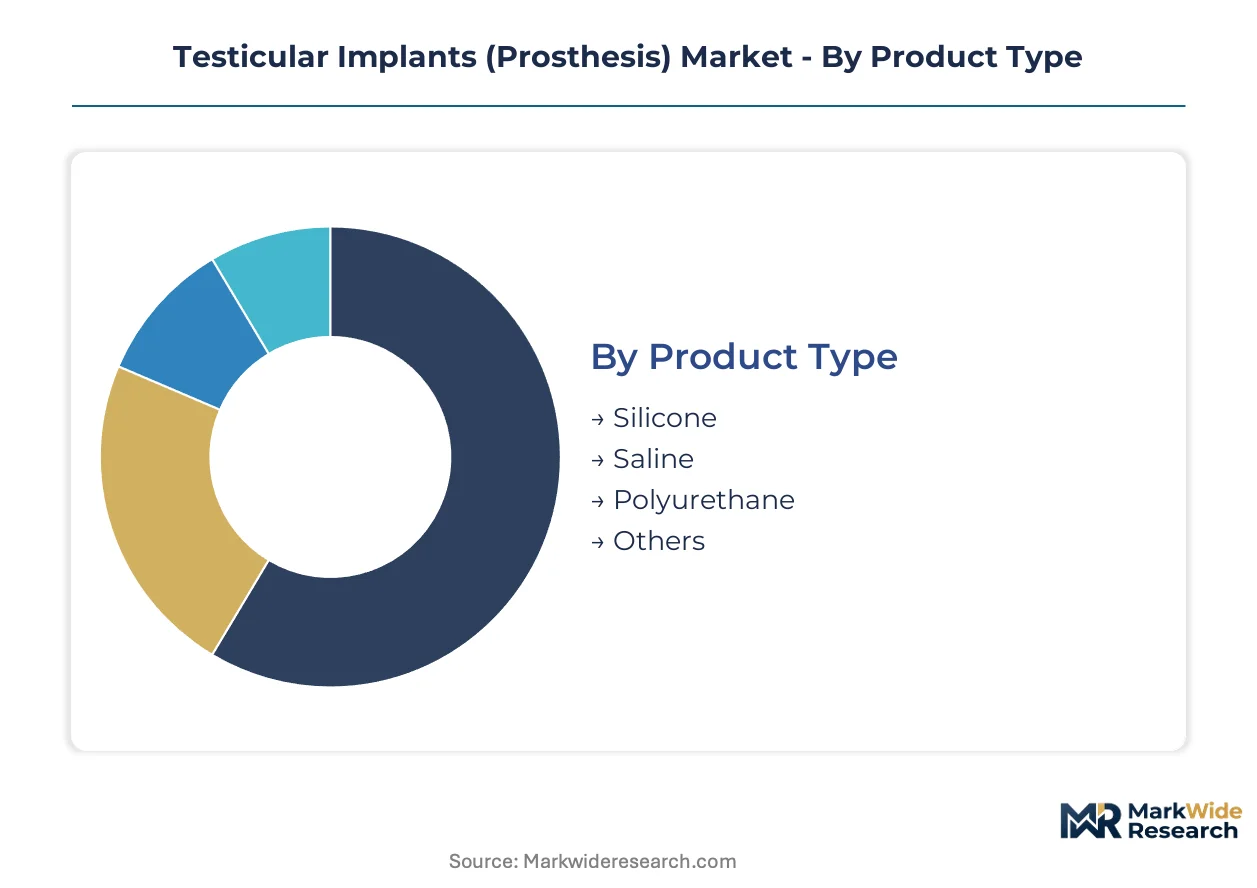
Segmentation in testicular implants reveals how regulatory pathways, procedural settings, and supply chain configurations fragment commercial opportunity. Manufacturers must align formulation choices with FDA 510(k) and EU MDR Class IIa requirements while calibrating channel presence to hospital procurement consolidation patterns.
Product Type:
FDA long-term implantable silicone guidance and EU REACH monomer standards create divergent compliance burdens across material categories.
- Silicone:Medical-grade silicone elastomer with solid gel or saline fill dominates hospital procurement due to established biocompatibility profiles and surgeon familiarity. German andrology centers and French public hospital networks concentrate demand here, though REACH-certified feedstock concentration among three German specialty chemical producers creates supply vulnerability.
- Saline:Adjustable fill volumes enable reversibility for pediatric and adolescent segments where anatomical growth necessitates future revision. Texas and Florida ambulatory surgical facilities are expanding placement capabilities for this design outside traditional hospital cost structures.
- Polyurethane:Alternative elastomer with distinct surface properties captures niche applications where silicone hypersensitivity contraindicates standard devices.
- Others:Experimental bioengineered scaffolds and composite materials remain preclinical or limited to academic medical center trials.
Established volume favors silicone; emerging adoption favors saline.
End User:
Procedure reimbursement tiers and facility accreditation requirements concentrate margin capture across institutional categories.
- Hospitals:Academic medical centers in Boston and Heidelberg perform complex congenital reconstructions with patient-specific contour matching. Dedicated andrology units in German hospital systems drive the highest procedural volumes for post-oncological restoration.
- Specialty Centers:Outpatient andrology facilities in Denmark and Sweden leverage centralized Nordic procurement consortia for multi-year supply agreements with embedded training provisions.
- Clinics:Private urology practices handle routine placements with faster scheduling but limited device customization capabilities.
- Home Care:Post-operative monitoring and patient education services extend reach beyond surgical episodes, though implant placement itself remains strictly inpatient or ambulatory surgical.
Revenue concentration sits with hospitals; specialty centers are climbing the fastest.
Manufacturing Stage:
ISO 10993 biocompatibility testing burdens and EMA post-market surveillance documentation requirements reshape value chain participation.
- Raw Material Processing:Implant-grade silicone elastomer production concentrates among certified German suppliers meeting ECHA purity standards.
- Quality Control:In vitro testing adoption under ISO 10993-23 reduces animal testing dependencies and accelerates European market entry timelines.
- Assembly:Cleanroom device fabrication requires specialized silicone handling expertise that lags behind innovation cycles.
- Packaging:Sterile barrier systems must satisfy FDA 510(k) and EU MDR Class IIa documentation for transatlantic distribution.
Regulatory scrutiny intensifies at quality control; assembly faces capability constraints.
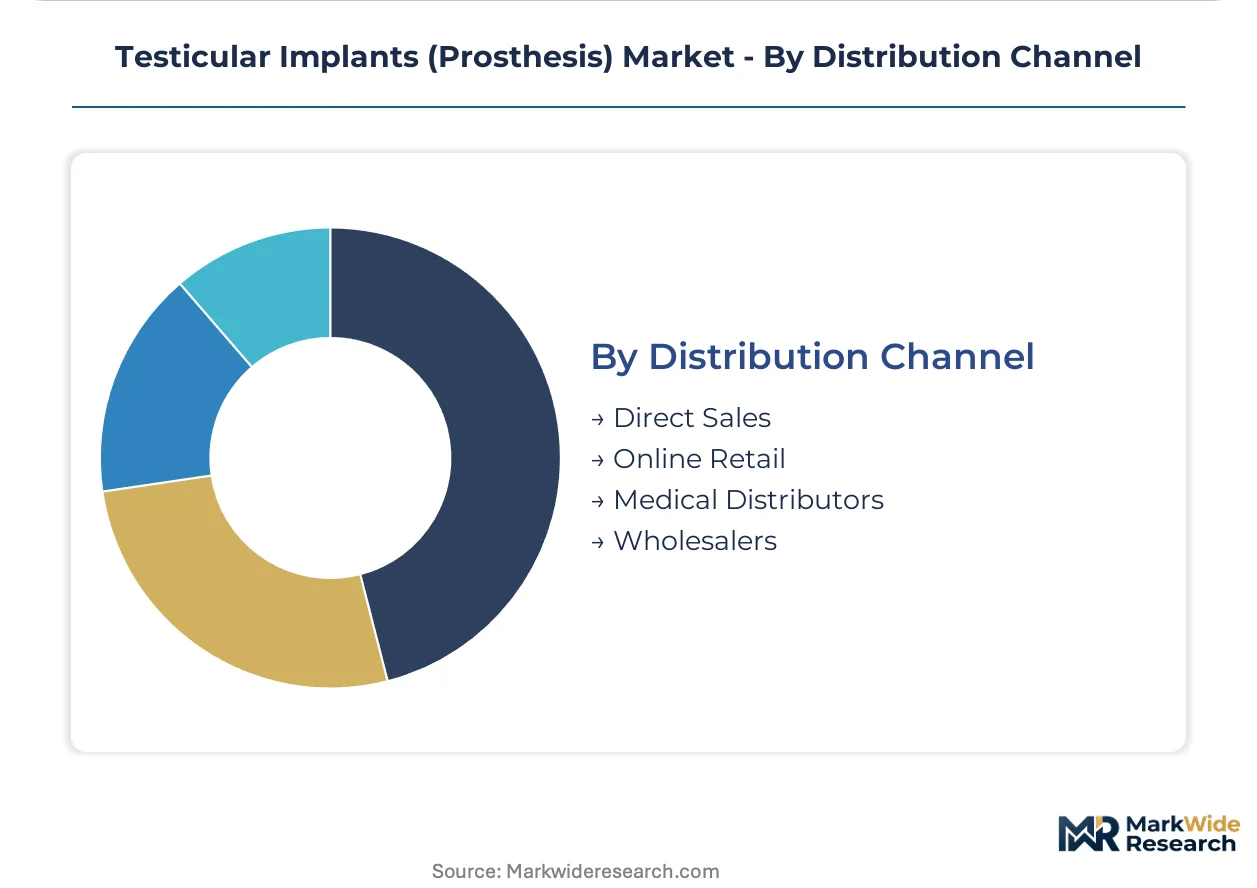
Distribution Channel:
Hospital purchasing consolidation and direct contracting patterns are displacing traditional intermediary structures.
- Direct Sales:Nordic hospital purchasing consortia negotiate multi-year agreements with manufacturers, embedding clinical training and field support into supply contracts.
- Medical Distributors:Regional intermediaries retain relevance in fragmented private clinic networks where aggregated demand justifies inventory holding.
- Online Retail:Patient education resources and accessory products move through digital channels, though implant devices require prescription and surgical placement.
- Wholesalers:Bulk procurement for cost-sensitive markets where saline alternatives compete on reversibility and adjustability.
Direct sales capture premium positioning; wholesalers serve price-sensitive procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA long-term implantable silicone guidance anchors the United States market, while EU MDR Class IIa device requirements reshape European procurement patterns across Germany, France, and the Nordic hospital systems.
United States
Post-oncological reconstruction protocols drive procedural volumes at academic medical centers in Boston and major hospital systems in Texas and Florida. FDA 510(k) clearance pathways compress product development timelines while demanding robust clinical follow-up infrastructure. Ambulatory surgical facilities in Dallas and Miami are building dedicated prosthetic placement capabilities outside traditional hospital cost structures.
Germany
Dedicated andrology units within public hospital networks address rising testicular cancer survivor volumes seeking restorative procedures. ECHA REACH silicone monomer standards accelerate supplier consolidation toward certified medical-grade elastomer producers in the country's specialty chemical corridor. Heidelberg medical centers pioneer patient-specific contour matching for complex congenital reconstructions using customized 3D-printed silicone molds.
France
Public hospital networks integrate prosthetic placement into standardized gender-affirming surgical sequences, expanding addressable patient populations. ANSM post-market surveillance expectations tighten adverse event reporting granularity for long-term implantables. Paris and Lyon hospital purchasing authorities negotiate multi-year supply agreements with embedded clinical training provisions.
Sweden
Centralized procurement consortia aggregate demand across regional health systems, displacing traditional distributor intermediaries. EU MDR technical documentation burdens extend conformity assessment timelines, freezing pipeline releases for manufacturers lacking existing clinical track records. Stockholm and Gothenburg specialty centers leverage direct-to-hospital contracting with embedded field support teams.
United Kingdom
NHS specialized commissioning frameworks concentrate reconstructive urology services at designated supra-regional centers. MHRA alignment with EU MDR device requirements maintains transatlantic market access continuity post-Brexit. London teaching hospitals and Manchester regional centers drive the highest procedural volumes for post-oncological restoration within the national health system.
Testicular Implants (Prosthesis) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure where scale-driven manufacturers compete on regulatory compliance breadth while niche players anchor on silicone formulation expertise and regional hospital relationships. The market structure favors companies with captive medical-grade elastomer supply and direct hospital channel infrastructure. Three strategic archetypes dominate: integrated silicone producers with backward control over feedstock, specialized prosthetic manufacturers with surgeon training ecosystems, and diversified medical device conglomerates leveraging urology portfolio synergies. Competitive moves concentrate on M&A for elastomer supply security and strategic partnerships for EU MDR notified body access.
Among European specialists, Groupe Sebbin SAS and Rigicon occupy positions within the formulation-expertise tier, anchoring technical reputation among surgeons through specialized silicone handling capabilities. Coloplast represents the diversified conglomerate archetype, leveraging direct hospital channel infrastructure across Nordic markets. These three companies exemplify how regulatory compliance breadth and clinical training investment separate sustainable competitors from procurement-dependent challengers.
| Leading Market Players |
|---|
| Groupe Sebbin SAS |
| Rigicon |
| Coloplast |
| UROMED |
| Implantech |
| Polytech Health & Aesthetics |
| GC Aesthetics |
| Alpha Aesthetics |
| Promedon GmbH |
| Others |
Pricing and Supply Chain Analysis
Batch-scale economies in medical-grade silicone elastomer production anchor price floors across implant categories, concentrating margin leverage among German specialty chemical producers who supply certified feedstock under ECHA REACH monomer standards. This upstream consolidation cascades into downstream procurement, where hospital purchasing consortia in Nordic markets and public networks in France negotiate multi-year supply agreements that embed training provisions as non-price value components.
Pricing Analysis
German hospital procurement contracts command 15-20% premiums over Spanish and Italian equivalents due to embedded field support and proctoring services bundled into supply agreements. Pricing stratifies across premium, standard, and economy tiers based on silicone formulation certification grade and surgeon training ecosystem depth. Cost compression in the economy tier intensifies as saline-filled alternatives capture pediatric segments where reversibility carries clinical weight. Ambulatory surgical facilities in Texas and Florida exhibit the highest price sensitivity, while academic medical centers in Boston and Heidelberg prioritize contour-matching capabilities over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for non-European manufacturers seeking EU MDR Class IIa device market entry. Implant-grade silicone elastomer production concentrates in Germany, with secondary capacity in Switzerland and the United States. Raw material dependencies rest on platinum-cured silicone polymers, sterilization-grade packaging films, and 3D-printed mold substrates. Single-source vulnerability in German feedstock supply creates structural risk for manufacturers lacking qualified secondary suppliers. Distribution runs through direct hospital contracting in consolidated Nordic markets, while regional medical distributors retain relevance in fragmented private clinic networks across Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Testicular implants occupy an early-cycle expansion phase as post-oncological reconstruction protocols and formalized transgender healthcare pathways extend addressable patient populations beyond traditional congenital indications.
For Market Incumbents: Consolidate elastomer supply security through captive partnerships with REACH-certified German specialty chemical producers, insulating against feedstock concentration risk. Deepen direct hospital channel infrastructure across Nordic purchasing consortia to defend premium positioning against procurement commoditization. Prioritize ISO 10993-23 in vitro testing investment to compress EU MDR conformity assessment timelines.
For New Entrants and Emerging Players: Differentiate on saline-filled adjustable device architectures that address unmet pediatric and adolescent segments where anatomical growth necessitates future revision. Target ambulatory surgical facilities in Texas and Florida as the most penetrable channel outside established hospital cost structures. Pursue proctoring partnerships with fellowship-trained reconstructive urologists to overcome surgeon scarcity constraints.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized silicone formulation expertise over diversified urology portfolio breadth. Long-term viability hinges on regulatory compliance infrastructure capable of sustaining EMA post-market surveillance expectations and FDA long-term implantable guidance evolution. Acquisition target archetype: European specialists with notified body relationships and existing clinical track records. Signal to watch: EU MDR technical documentation burden relaxation or notified body capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Partnership | Secures Class IIa device conformity assessment capacity for pipeline acceleration. |
| REACH-Certified Elastomer Supply Agreement | Locks implant-grade silicone feedstock access under tightening monomer purity standards. |
| Hospital System Direct Contracting | Displaces distributor intermediaries in Nordic and French procurement consolidation. |
| Surgeon Proctoring Program Scale-Up | Addresses fellowship-trained specialist scarcity constraining procedural capacity expansion. |
| ISO 10993-23 In Vitro Testing Adoption | Reduces animal testing dependencies and accelerates European market entry timelines. |
Research Methodology
A standing panel of reconstructive urologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration across the research window. Primary interviews with silicone formulation specialists and regulatory affairs leads at notified bodies combined with secondary validation against FDA 510(k) filings, EMA device registration databases, hospital procurement records, and ISO 10993 biocompatibility testing protocols. Bottom-up volume estimates by product type and end user triangulated against top-down market sizing derived from procedural volume data and implant reimbursement schedules.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including material category, procedural setting, distribution channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates, incorporating procedure volume forecasts, reimbursement trajectory assumptions, and silicone raw material cost indices as key inputs.
Material uncertainties — regulatory guidance modifications, notified body capacity constraints, and reconstructive urologist training pipeline fluctuations — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EU MDR implementation pace and FDA long-term implantable surveillance evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Bone Allografts Market
Medical Devices
Centrifugation-Free Sperm Separation Systems Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Meniscus Repair Systems Market