
 Global IV Infusion Pump Accessories Market | 2026-2036
Global IV Infusion Pump Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Global IV Infusion Pump Accessories Market Intelligence
Manufacturing expansion in China is reconfiguring the supply base for essential components like tubing and connectors. B. Braun Melsungen AG leverages its extensive distribution network to maintain market presence across Europe. Becton Dickinson & Company differentiates through its focus on integrated smart pump systems and data connectivity protocols. Meanwhile, Terumo Corporation sustains its position with a strong portfolio in specialized infusion sets and catheters for oncology.
IV infusion pump accessories are disposable or reusable components used with infusion pumps to deliver fluids and medications. These products, including infusion sets with specific flow rates and micro-bore tubing, ensure precise administration in clinical settings. Infusion sets and administration sets constitute the largest product segments by volume due to their single-use nature. The home care end-user segment is experiencing rapid expansion, altering the traditional dominance of hospitals.
Regulatory bodies including the US FDA, Europe's EMA, and China's NMPA impose stringent requirements on material biocompatibility and device interoperability. These standards, alongside CE marking for European market access and ISO 8536 for infusion equipment, directly influence design and manufacturing costs. Vendor selection increasingly depends on the ability to demonstrate robust cybersecurity measures for connected smart pump accessories.
Market Dynamics
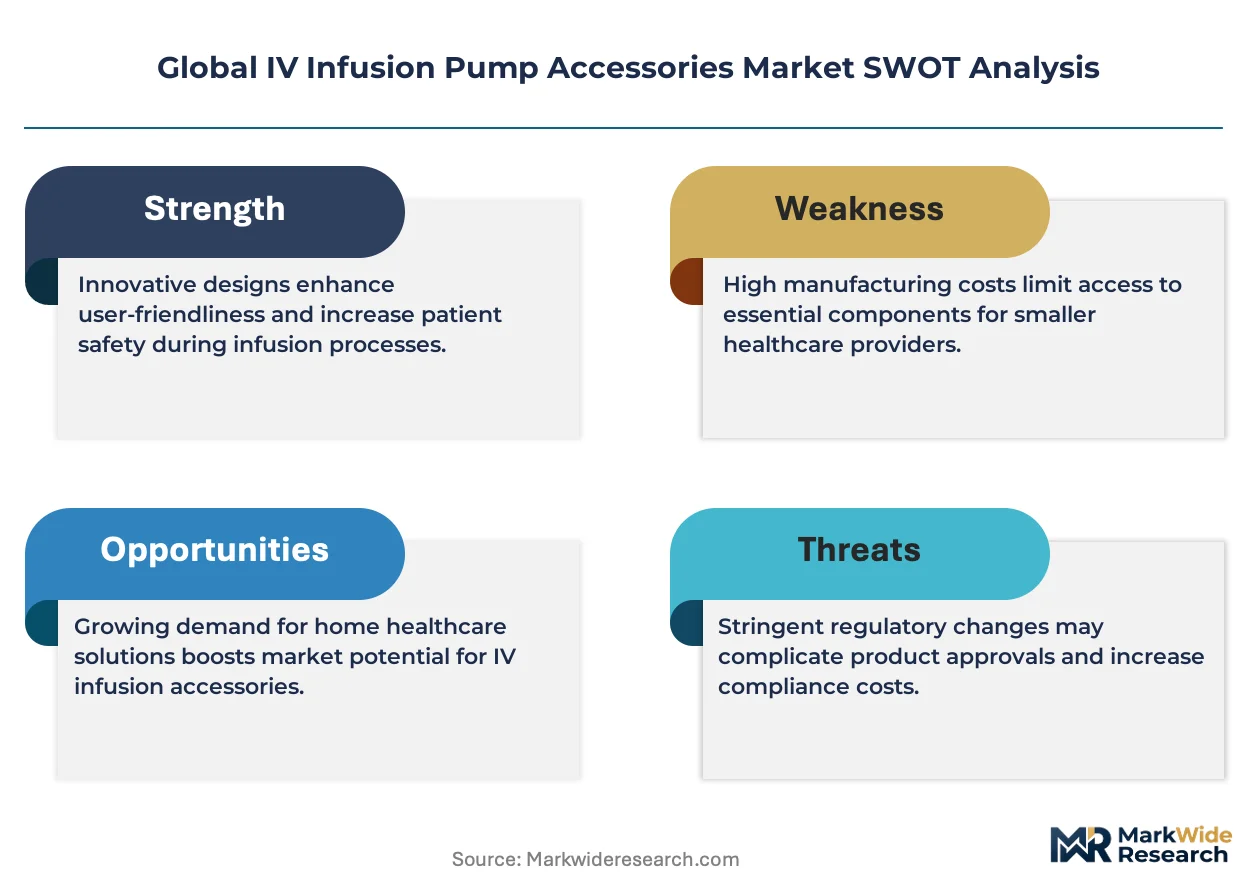
The convergence of decentralized healthcare and digital connectivity is the central force shaping the IV infusion pump accessories market. Pressure to provide hospital-level care in alternate sites like homes is driving demand for user-friendly, safe accessories, while regulatory mandates for cybersecurity in connected devices redefine product design and validation protocols.
Growth Catalysts
- Home Care Expansion:Government reimbursement policies supporting home-based infusion therapy in countries like Germany and France are expanding the addressable market beyond traditional hospital settings, creating sustained demand for disposable infusion sets.
- Specialized Clinical Needs:The growth of oncology and personalized medicine requires specialized accessories, such as multi-lumen catheters and light-protected tubing, to ensure the safe and effective delivery of complex, high-cost therapeutics.
- Material Science Advances:The development of new biocompatible polymers that are DEHP-free and offer improved drug compatibility is enabling manufacturers to meet stricter regulatory standards like REACH in Europe and create higher-margin, differentiated products.
Market Restraints
- Stringent Regulatory Hurdles:Lengthy and costly pre-market approval pathways, such as the FDA's 510(k) process in the US and the conformity assessments for CE marking under the EU's MDR, delay product launches and increase development expenses.
- Interoperability Failures:A lack of universal standards for connectors and data protocols between pumps and accessories from different manufacturers creates vendor lock-in and can lead to dangerous administration errors, limiting hospital procurement flexibility.
- Supply Chain Volatility:The supply of critical raw materials, including medical-grade plastics and electronic components for smart accessories, is subject to price fluctuations and geopolitical disruptions, impacting production costs and stability.
Strategic Opportunities
- Accessories for Biologics:Developing infusion sets and catheters specifically designed for the unique viscosity and stability requirements of cell and gene therapies presents a high-value opportunity as these advanced treatments become more common.
- Integrated Sensor Technology:Embedding micro-sensors for flow rate, pressure, and temperature monitoring directly into infusion tubing can create smart accessories that provide real-time data, enhancing patient safety and differentiating products. *Emerging Market Modernization: Hospital infrastructure upgrades in nations across Southeast Asia and Latin America create significant greenfield opportunities for vendors offering complete infusion systems, including pumps and a portfolio of compatible standard accessories.
Industry Challenges
- Cybersecurity Compliance:Adhering to evolving cybersecurity guidance from regulatory bodies like the US FDA for connected smart pump accessories requires continuous investment in threat modeling, vulnerability testing, and software lifecycle management.
- Legacy System Integration:Ensuring seamless data flow between new smart infusion accessories and existing, often outdated, hospital IT infrastructure, including Electronic Health Record systems, remains a significant technical and operational hurdle.
- Sterilization Process Validation:Validating sterilization methods, such as ethylene oxide or gamma radiation, for new materials or complex accessory designs is a resource-intensive process that can pose a challenge for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IV Infusion Pump Accessories Market |
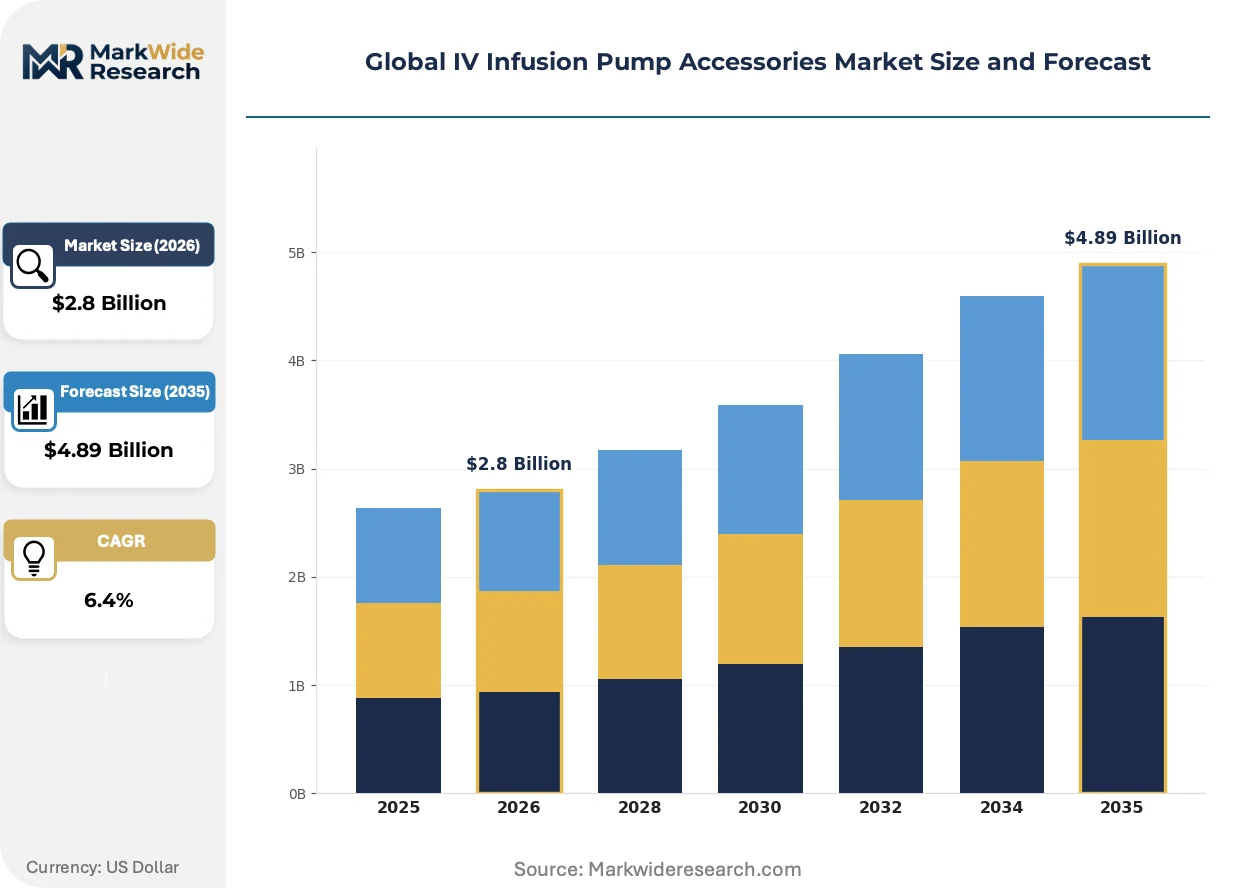
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Sets, Catheters, Syringe Pumps, Administration Sets End User: Hospitals, Home Care, Ambulatory Surgical Centers, Clinics Technology: Volumetric Pumps, Gravity Pumps, Smart Pumps, Peristaltic Pumps Distribution Channel: Online, Offline, Direct Sales, Third-Party Distributors |
| Companies Covered | Terumo Corporation, MOOG INC, B. Braun Melsungen AG, ICU Medical, Inc, Nipro Corporation, Smiths Medical, Becton Dickinson & Company, Fresenius Kabi AG, Chemyx, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IV Infusion Pump Accessories Market Strategic Shifts & Innovations
The market's evolution is defined by the transformation of passive disposables into active, data-generating components. This shift is driven by a push for greater precision in medication delivery, stricter regulatory oversight on device performance, and new procurement models that prioritize patient outcomes over unit cost.
Smart infusion sets incorporating embedded micro-sensors represent a key product evolution. These sensors provide real-time monitoring of flow rates and can detect occlusions or air-in-line, transmitting alerts directly to the pump or a central nursing station. Adoption is currently highest within intensive care units and oncology centers in North America and Western Europe. This technology is hybridizing the single-use accessory with data-generating capabilities, turning it from a simple fluid conduit into an active component of the patient safety ecosystem.
Europe's Medical Device Regulation (MDR) is a significant policy shift impacting all market participants. The MDR mandates more rigorous clinical evidence, post-market surveillance, and supply chain traceability for all medical devices, including infusion accessories previously subject to less stringent rules. Manufacturers of infusion sets and catheters face increased compliance costs and are forced to re-evaluate their product portfolios, potentially discontinuing older products to focus resources on certifying their core offerings for continued access to the EU market.
A notable behavioral shift is occurring in hospital purchasing. Health systems are moving away from sourcing accessories based on the lowest unit price and toward a total-cost-of-ownership model that considers the risks and costs of infusion-related adverse events. This change disrupts the traditional channel where separate departments might procure pumps and disposables independently. This trend is most apparent in large integrated delivery networks in the United States, which increasingly favor single-vendor contracts for integrated pump and accessory systems to guarantee compatibility and accountability.
Global IV Infusion Pump Accessories Market Segmentation
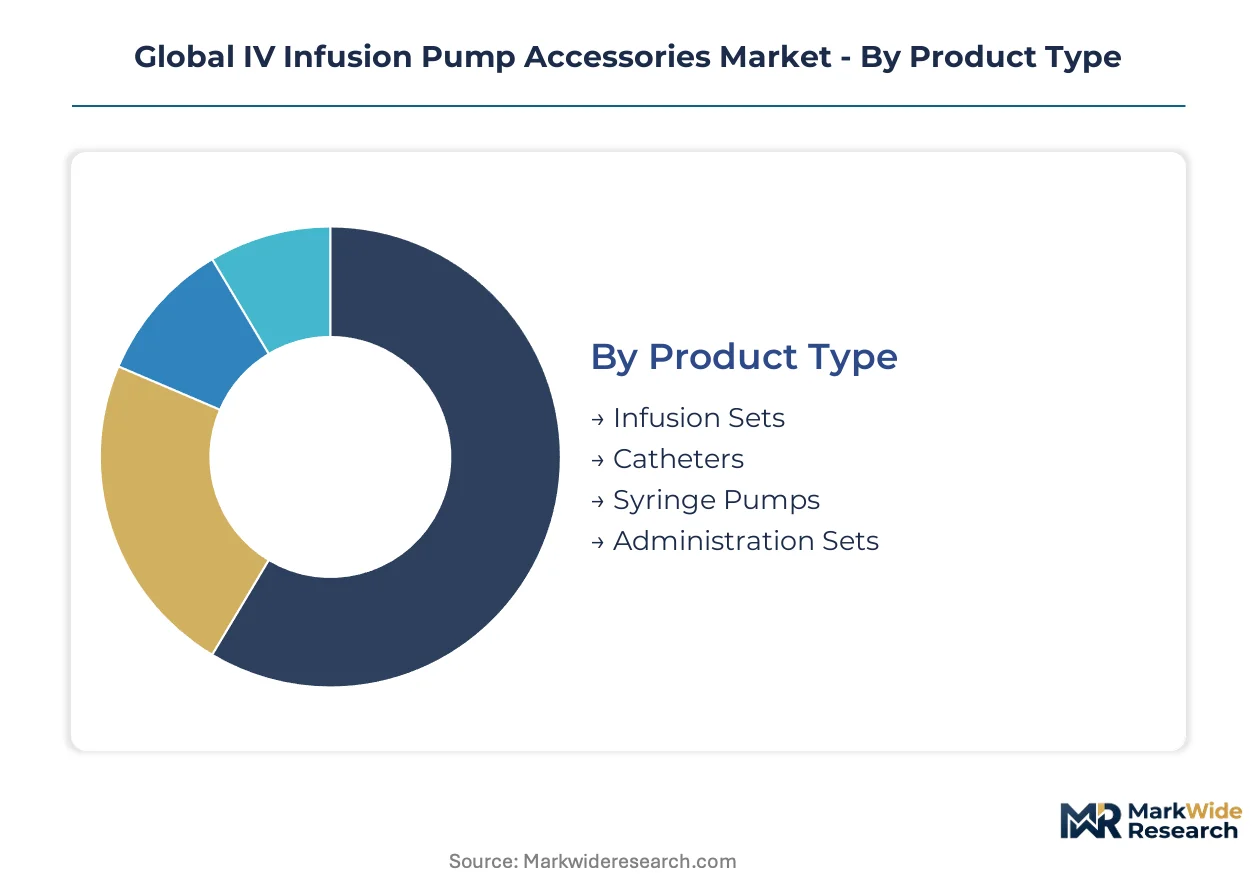
Understanding the varied requirements across different user groups and product functionalities is essential for strategic market engagement in IV infusion pump accessories. Manufacturers must align product development and distribution strategies with specific segment demands to capture market share effectively.
Product Type:
The after-sales service intensity for IV infusion pump accessories varies significantly based on their complexity and single-use versus reusable nature.
- Infusion Sets:These components control fluid flow from the IV bag to the patient, featuring specific flow rates and micro-bore tubing for precise administration. Demand for these disposable components is concentrating in home care settings, driven by government reimbursement policies in Germany and France supporting home-based infusion therapy.
- Administration Sets:Designed for single-use, these sets connect directly to the IV solution container and pump, ensuring sterile delivery of fluids and medications. Hospitals in North America are increasingly favoring administration sets that integrate advanced safety features like anti-reflux valves to minimize medication errors.
- Catheters:These slender tubes are inserted into a body cavity, duct, or vessel, allowing for fluid drainage, administration of fluids, or access by surgical instruments. Specialized catheters are crucial for oncology, where precise delivery of complex therapeutics is paramount.
- Syringe Pumps:These devices deliver precise, small volumes of fluid at controlled rates, often used in neonatology and critical care. Their demand is stable in intensive care units requiring highly accurate micro-infusions.
Infusion Sets hold the largest share; momentum sits with Administration Sets.
End User:
Cost tiering influences procurement decisions across various end-user segments, reflecting differences in patient volume, acuity levels, and budget constraints.
- Hospitals:These institutions represent the traditional core market, demanding a broad spectrum of accessories for diverse clinical applications, from general wards to specialized units. Large integrated delivery networks in the United States increasingly seek single-vendor contracts for integrated pump and accessory systems.
- Home Care:This segment is experiencing rapid expansion, driven by patient preference and cost-effectiveness of home-based therapy. Demand is strong for user-friendly, disposable infusion sets that can be managed by patients or caregivers.
- Ambulatory Surgical Centers:These facilities focus on same-day surgical procedures, requiring efficient and reliable infusion accessories for perioperative care. Procurement prioritizes sterile, pre-packaged solutions to streamline workflows.
- Clinics:Smaller healthcare facilities and specialized clinics utilize infusion accessories for specific treatments like chemotherapy or hydration therapy. Their purchasing decisions are often influenced by local distributor availability and product compatibility with existing equipment.
Hospitals maintain the largest market share, while the Home Care segment is expanding most quickly.
Technology:
Application diversity dictates the technological requirements for IV infusion pump accessories, with specialized needs emerging for complex treatments and monitoring.
- Smart Pumps:These advanced systems incorporate drug libraries and safety software to reduce medication errors, often integrating with electronic health records. Adoption is highest in intensive care units and oncology centers in North America and Western Europe.
- Volumetric Pumps:Delivering fluids at a programmed rate and volume, these pumps are widely used for general fluid administration and medication delivery. Their reliability makes them a staple in most hospital settings.
- Gravity Pumps:These simple, cost-effective systems rely on gravity to deliver fluids, with flow regulated by a roller clamp. They are common in low-resource settings and for basic hydration therapies.
- Peristaltic Pumps:Utilizing rollers to push fluid through tubing, these pumps offer precise flow control for specific applications, including enteral feeding and blood transfusions. Their use is specialized, focusing on particular clinical needs.
Smart Pumps are gaining significant traction, while Volumetric Pumps continue to hold a substantial base.
Distribution Channel:
Volume considerations significantly influence the choice of distribution channel, balancing reach, cost-efficiency, and direct customer engagement.
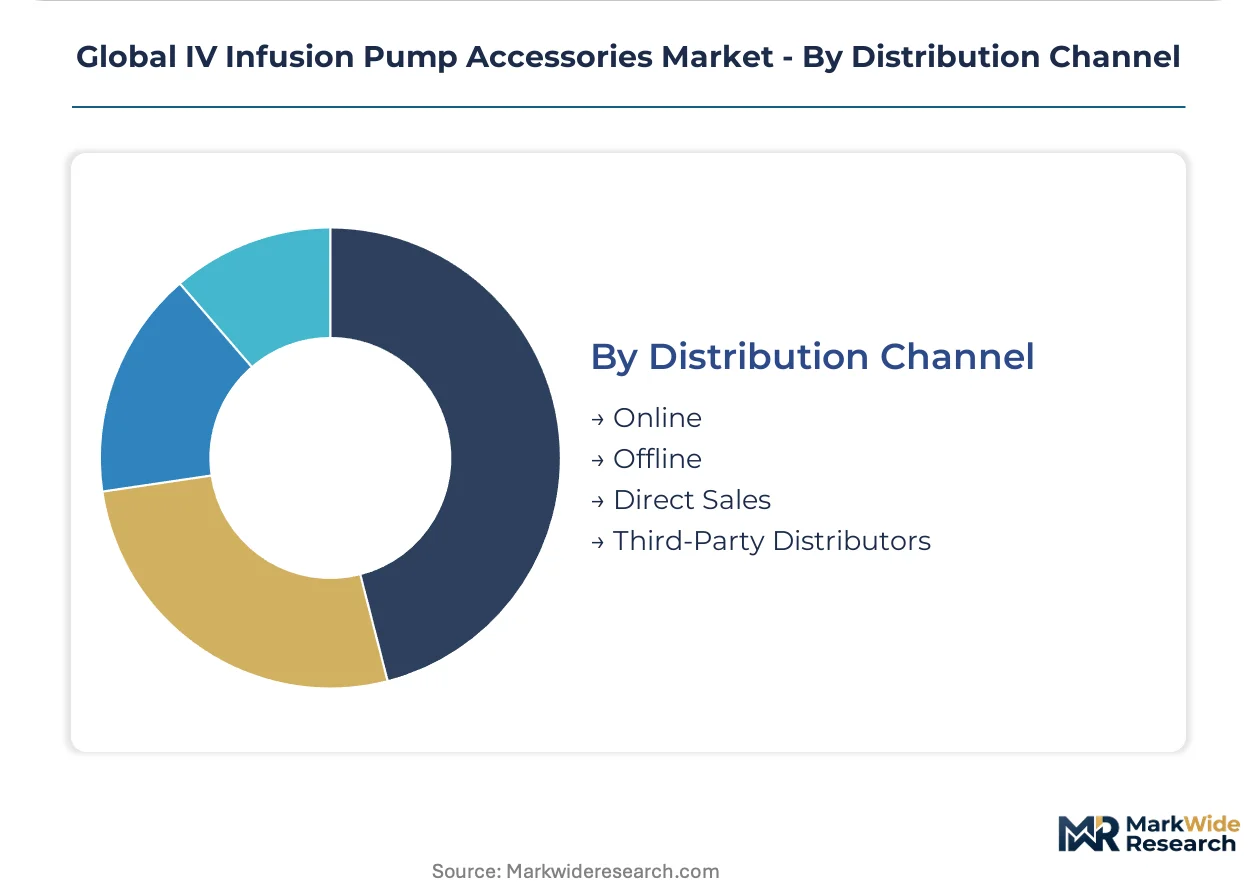
- Direct Sales:Manufacturers engage directly with large healthcare systems and key accounts, providing tailored solutions and technical support. This channel is critical for complex integrated systems and high-value accessories.
- Third-Party Distributors:These entities provide extensive market reach, particularly to smaller clinics and geographically dispersed customers, handling logistics and local inventory. Their networks are essential for broad market penetration.
- Online:E-commerce platforms facilitate convenient procurement of standard, high-volume accessories, offering competitive pricing and quick delivery. This channel is growing for routine supply orders.
- Offline:Traditional brick-and-mortar suppliers and medical equipment stores serve local markets, often providing immediate access to essential accessories. These channels remain important for urgent supply needs.
Third-Party Distributors account for the largest volume of accessories, with Direct Sales representing a high-value segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced healthcare infrastructure and robust government reimbursement policies for home-based care underwrite Europe's significant role in the IV infusion pump accessories market. This established framework supports both high-acuity hospital demand and the expanding home care segment. The convergence of digital health initiatives and stringent regulatory oversight across the continent influences product development and market access strategies.
Germany
Demand for user-friendly, safe accessories is expanding due to government reimbursement policies supporting home-based infusion therapy. The EU's Medical Device Regulation (MDR) mandates rigorous clinical evidence for infusion sets and catheters, influencing local manufacturing. Major medical technology clusters in Bavaria and North Rhine-Westphalia drive innovation in smart accessory development and production.
United States
Integrated smart pump systems and data connectivity protocols drive significant demand for advanced accessories. The US FDA's cybersecurity guidance for connected medical devices shapes product design and validation. Major medical device hubs in Boston and Minneapolis foster intense R&D for next-generation sensor-embedded infusion technologies.
China
Manufacturing expansion is reconfiguring the supply base for essential components like tubing and connectors. The NMPA's stringent requirements for device interoperability and material biocompatibility impact local and international suppliers. Industrial zones in the Yangtze River Delta region are becoming key centers for high-volume production of disposable infusion accessories for both domestic and export markets.
Japan
Specialized infusion sets and catheters for oncology and personalized medicine are experiencing sustained demand. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict quality and safety standards for all infusion accessories. Metropolitan areas like Tokyo and Osaka host significant R&D centers for advanced medical devices, focusing on precision delivery systems.
France
Government reimbursement policies supporting home-based infusion therapy expand the addressable market beyond traditional hospital settings. The European Medicines Agency (EMA) and national health authorities enforce strict compliance with device performance standards. Medical technology clusters in Lyon and Grenoble specialize in developing innovative solutions for complex, high-cost therapeutic delivery.
Global IV Infusion Pump Accessories Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing essential raw materials and sub-assemblies. The market structure exhibits a tiered consolidation, with large multinational corporations offering comprehensive integrated solutions alongside specialized manufacturers focused on niche accessories. This environment fosters strategic partnerships for interoperability and targeted mergers and acquisitions for portfolio expansion, driving competitive positioning.
Integrated system providers like Becton Dickinson & Company exemplify a strategy focused on complete smart pump systems and data connectivity. B. Braun Melsungen AG, a German multinational, leverages its extensive distribution network to maintain a broad market presence across Europe. Terumo Corporation, a Japanese company, sustains its position by offering a strong portfolio in specialized infusion sets and catheters, particularly for oncology applications.
| Leading Market Players |
|---|
| Terumo Corporation |
| MOOG INC |
| B. Braun Melsungen AG |
| ICU Medical, Inc |
| Nipro Corporation |
| Smiths Medical |
| Becton Dickinson & Company |
| Fresenius Kabi AG |
| Chemyx, Inc |
| Others |
Cost & Logistics Intelligence
Commodity volatility for medical-grade plastics and electronic components determines both pricing tier spreads and the supply chain shape for IV infusion pump accessories. Manufacturers face pressure to balance cost-efficiency with stringent regulatory compliance and product innovation.
Pricing Analysis
A volume-discount tiering structure dominates accessory procurement, where larger integrated delivery networks secure more favorable terms. Price differentiation stems from material biocompatibility, such as DEHP-free polymers, and the integration of advanced smart features. Pricing pressure stems from increasing regulatory compliance costs, particularly for CE marking under Europe's MDR. The home care segment exhibits higher price sensitivity, while hospitals prioritize product reliability and safety for critical applications.
Supply Chain Analysis
The NMPA's stringent requirements for material biocompatibility in China influence the global supply base for essential components like tubing. Geographic supply concentration centers in China for high-volume disposables, with Germany and the United States leading in advanced technology manufacturing. Raw material dependencies include medical-grade plastics and micro-electronic components for smart accessories. Single-source vulnerability for specialized sensor components presents a structural supply chain risk. Distribution runs through third-party distributors for broad market reach, while direct sales target large healthcare systems for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IV infusion pump accessories market is experiencing a significant buyer-power shift, as large integrated delivery networks increasingly favor single-vendor contracts for integrated pump and accessory systems.
For Market Incumbents: Harden strategic partnerships with raw material suppliers to mitigate commodity volatility and secure critical component access. Develop robust cybersecurity frameworks for smart accessories, ensuring compliance with US FDA guidance and differentiating offerings. Invest in R&D for specialized accessories compatible with advanced biologics and cell and gene therapies. This protects against emerging entrants focused on niche therapeutic areas.
For New Entrants and Emerging Players: Underpenetration in emerging markets across Southeast Asia and Latin America presents significant greenfield opportunities for basic and standard accessories. Target hospital infrastructure upgrades in these regions by offering complete, cost-effective infusion systems. A go-to-market angle focused on establishing strong local distribution partnerships and providing comprehensive training can facilitate market entry.
For Investors and Strategic Acquirers: The market sits at a modernization phase that favors integrated solution providers with strong data connectivity and patient safety features. Acquire specialized accessory manufacturers possessing intellectual property in micro-sensor technology or advanced material science. Focus on companies demonstrating robust regulatory compliance capabilities and established distribution networks in expanding home care segments. Increased M&A activity for niche capabilities would signal further market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Smart Accessories | Achieves market access in the United States for advanced data-generating components. |
| CE Marking Pathway Acceleration | Ensures continued access to the European market under stringent MDR regulations. |
| Hospital System Partnership Expansion | Secures long-term contracts with large buyers, enhancing market share for integrated solutions. |
| Software Companion Development | Integrates accessory data with EHR systems, improving clinical workflow for healthcare providers. |
| Reimbursement Strategy Optimization | Facilitates broader adoption of home-based infusion therapies in key geographies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to construct a comprehensive market perspective. Primary interviews with hospital procurement managers, home care providers, regulatory affairs specialists, and biomedical engineers were triangulated with extensive secondary validation. Secondary data sources included FDA filings, EMA submissions, ISO standards documents, and industry association reports, ensuring a robust data foundation.
The analytical framework calibrated market size and growth rates across the projection horizon. Segmentation dimensions modeled included product type, end-user, technology, distribution channel, and material composition. Compound annual growth rates were derived from historical trends and projected market dynamics. Industry-specific forecast inputs included growth in home care patient volumes and adoption rates of smart pump technology, providing granular insights.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new entrants or large technology firms would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and technological progression. Material shifts in healthcare policy or significant disruptions to global supply chains would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Appendage Management Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Global Microkeratome Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Global Pupillometer Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Hearing Loop Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Dialysis Disposable Devices Market