
 Global Craniomaxillofacial Fixation Devices Market | 2026-2036
Global Craniomaxillofacial Fixation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Craniomaxillofacial Fixation Devices Market Foresight
The EU Medical Device Regulation (MDR) is broadening compliance obligations for implantable cranial hardware across European member states. Stryker leverages its vertically integrated titanium forging capacity to sustain premium positioning in plate and screw portfolios. Medtronic anchors its European distribution through specialized trauma care unit partnerships in Germany and France.
Craniomaxillofacial fixation devices encompass titanium and stainless steel plates, screws, pins, and mesh systems manufactured via CNC milling and additive powder-bed fusion, designed to stabilize cranial, mandibular, and midface fractures while permitting osseointegration. Titanium plate segments dominate value contribution due to biocompatibility premiums and revision surgery avoidance, while biodegradable polymer screws represent the fastest-expanding material category amid pediatric osteotomy demand. Hospitals command the largest end-user value pool, though maxillofacial clinics are capturing disproportionate volume growth in ambulatory cranial defect reconstruction.
FDA 510(k) pathways and EU MDR technical documentation requirements shape product development cycles and market access timelines for all manufacturers seeking multi-region commercialization. Japan's PMDA and China's NMPA impose additional clinical evaluation standards that filter entrants without localized regulatory infrastructure. Stakeholders must monitor MDR notified body capacity constraints and evolving biodegradable polymer degradation standards to calibrate portfolio and geographic prioritization.
Market Dynamics
EU MDR recertification deadlines are compressing supplier timelines and elevating documentation burdens for implantable cranial hardware, forcing manufacturers to restructure quality management systems and notified body relationships ahead of 2027 renewal waves.
Growth Catalysts
- Titanium osseointegration performance:Superior biocompatibility profiles in mandibular reconstruction are displacing stainless steel in tertiary hospital trauma units across Germany and Japan.
- Pediatric osteotomy demand:Biodegradable polymer screws eliminate secondary removal surgeries in cranial vault remodeling, accelerating adoption in specialized pediatric maxillofacial clinics.
- EU MDR Article 120 transition provisions:Legacy device certificates extended under specific conditions sustain market access while manufacturers complete technical documentation updates.
Market Restraints
- Titanium sponge price volatility:Aerospace sector competition for premium-grade titanium feedstock elevates raw material costs for plate and screw forging operations.
- Notified body capacity concentration:Only 12 EU MDR-designated bodies handle cranial implant reviews, creating bottlenecks for conformity assessment timelines.
- Biodegradable polymer degradation variability:Inconsistent hydrolysis rates in PLLA-PDGA copolymers generate revision surgery risks that temper clinical confidence.
Strategic Opportunities
- Brazil trauma network expansion:Public hospital craniomaxillofacial unit investments under SUS reforms create procurement scale for plate-screw system vendors.
- Additive powder-bed fusion:Patient-specific titanium mesh manufacturing converges with digital surgical planning platforms to enable custom cranial defect reconstruction.
- Japan PMDA Sakigake pathway:Expedited review for innovative biodegradable fixation devices accelerates market entry for novel polymer formulations.
Industry Challenges
- CNC milling technician scarcity:Precision machining expertise for complex plate geometries concentrates in medical device manufacturing clusters, constraining capacity expansion.
- EU MDR clinical evaluation report requirements:Systematic literature reviews and post-market surveillance data compilation demand 18-24 month preparation cycles for legacy device recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Craniomaxillofacial Fixation Devices Market |
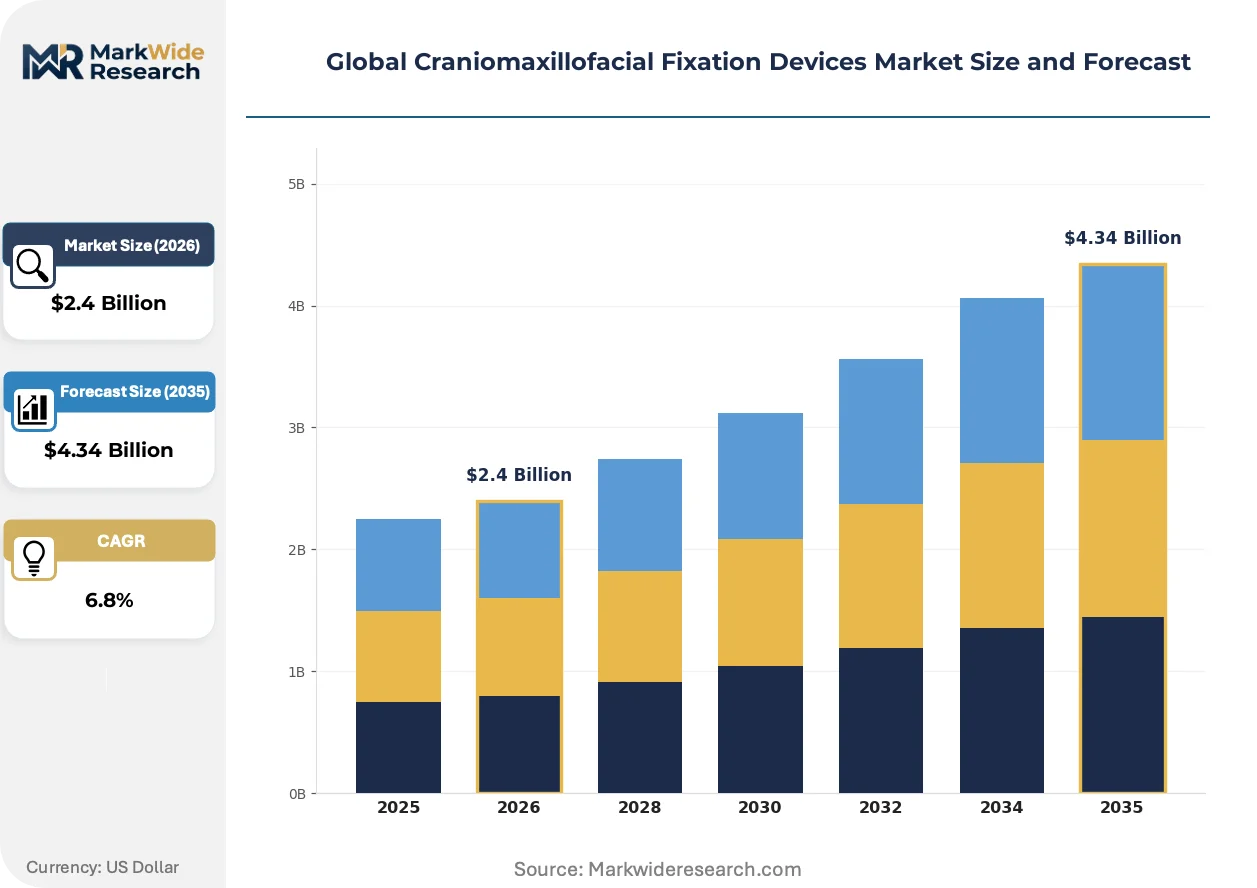
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Pins, Wires, Mesh, Clamps Application: Fracture Repair, Reconstructive Surgery, Trauma Management, Corrective Osteotomy, Cranial Defect Reconstruction, Pediatric Surgery End User: Hospitals, Maxillofacial Clinics, Surgical Centers, Medical Research Institutes, Orthopedic Facilities, Trauma Care Units Material: Titanium, Stainless Steel, Biodegradable Polymers, Cobalt-Chromium Alloys, Peek, Ceramic Composites |
| Companies Covered | Stryker, Zimmer Biomet, DePuy Synthes, Medtronic, Integra LifeSciences, KLS Martin, Medartis AG, OsteoMed, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Craniomaxillofacial Fixation Devices Market Shifts & Advancements
Digital surgical planning platforms are integrating with manufacturing execution systems to compress the design-to-implant timeline for patient-specific cranial reconstruction hardware.
Robotic-guided drilling systems are automating screw trajectory precision in mandibular osteosynthesis, reducing operative time and iatrogenic nerve injury risk. Tertiary trauma centers in Germany and South Korea are deploying these platforms for complex midface fracture repair. The technology is automating plate-bending workflows that previously required intraoperative manual adaptation.
EU MDR Annex XVI expansion to include previously unregulated cranial implant accessories is compelling manufacturers to reclassify instrument sets and navigation probes under higher scrutiny levels. Technical documentation requirements now encompass software validation for surgical planning algorithms. Maxillofacial device suppliers with limited regulatory infrastructure face exclusion from European procurement tenders.
Hospital purchasing consortia are consolidating cranial fixation device procurement across multi-site trauma networks, displacing individual surgeon preference-based selection. Standardized vendor qualification criteria emphasize MDR certification status and biodegradable polymer degradation data. This concentration is most visible in France's regional hospital groupings and England's NHS supply chain centralization.
Global Craniomaxillofacial Fixation Devices Market Segmentation
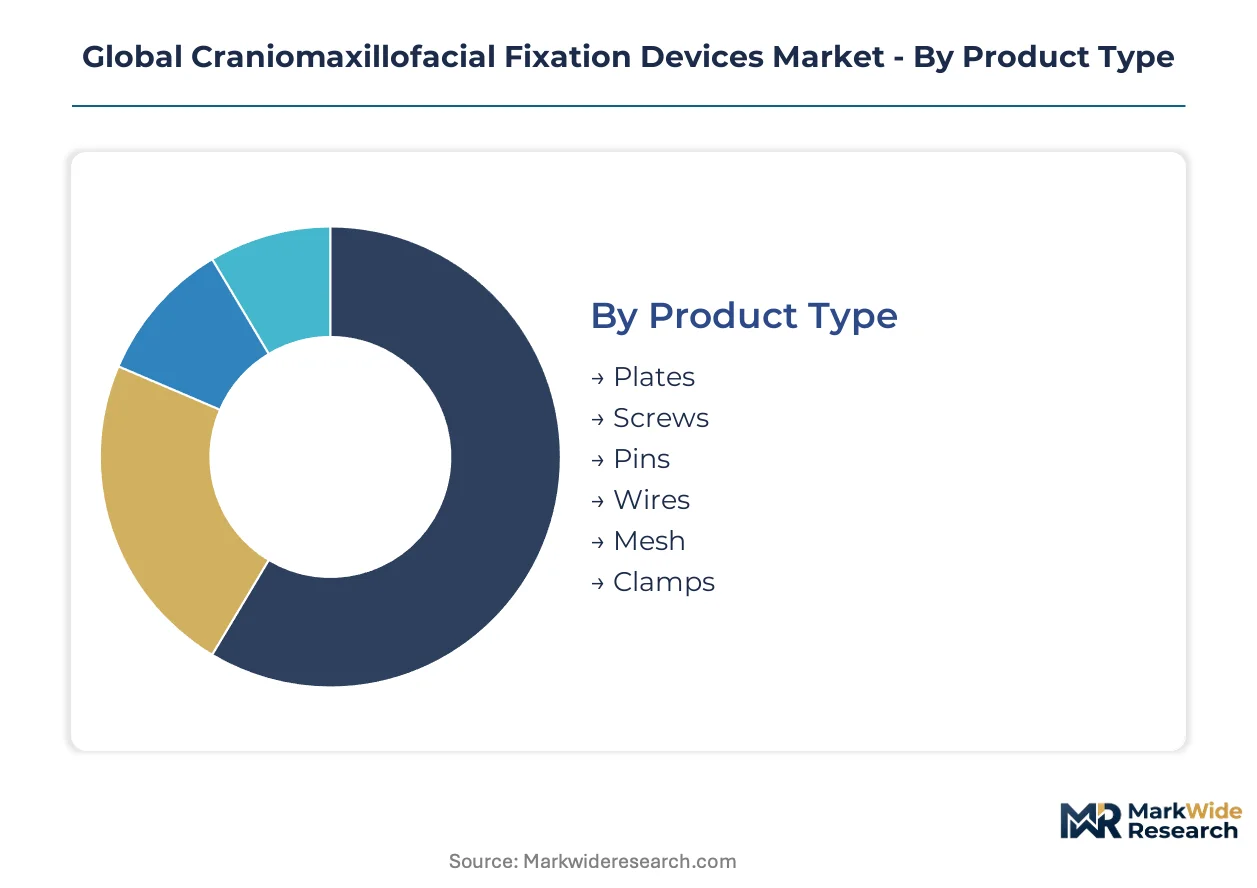
Craniomaxillofacial fixation devices fragment across four structural dimensions that determine procurement patterns, clinical utility, and margin architecture. Product type and material selection drive hardware specifications, while application and end-user categories shape demand concentration and geographic deployment.
Product Type:
Surgeons select hardware based on fracture complexity, load-bearing requirements, and revision risk tolerance.
- Plates:CNC-milled titanium plates with anatomically contoured profiles stabilize mandibular and midface fractures. Demand concentrates in German and Japanese tertiary trauma centers where osseointegration performance dictates premium procurement.
- Screws:Self-tapping and locking screw variants secure plate-to-bone interfaces. Pediatric maxillofacial clinics in France and South Korea are driving biodegradable polymer screw adoption to eliminate secondary removal procedures.
- Pins:Kirschner wire derivatives provide temporary skeletal stabilization in emergency trauma settings.
- Wires:Stainless steel cerclage configurations reinforce mandibular continuity in resource-constrained surgical environments.
- Mesh:Titanium and PEEK mesh systems reconstruct cranial vault defects following decompressive craniectomy.
- Clamps:External fixation clamps stabilize complex mandibular fractures pending definitive internal fixation.
Volume sits with Plates; growth tilts toward Screws.
Application:
Clinical indication determines hardware selection, operative approach, and reimbursement pathway.
- Fracture Repair:Mandibular and zygomatic fracture fixation consumes the largest hardware volume across emergency trauma networks. Brazil's SUS hospital expansion is elevating plate-screw system procurement for maxillofacial trauma.
- Reconstructive Surgery:Post-oncologic and post-traumatic facial reconstruction demands patient-specific titanium mesh and advanced plating systems. Digital surgical planning integration is compressing design-to-implant timelines in specialized centers.
- Trauma Management:Acute craniomaxillofacial injury protocols standardize hardware configurations for rapid surgical response.
- Corrective Osteotomy:Orthognathic procedures employ rigid fixation to stabilize repositioned skeletal segments.
- Cranial Defect Reconstruction:Custom titanium mesh and PEEK implants address decompressive craniectomy sequelae.
- Pediatric Surgery:Cranial vault remodeling in infants drives biodegradable polymer demand to accommodate skull growth.
Revenue concentrates in Fracture Repair; Pediatric Surgery climbs the fastest.
End User:
Facility type dictates purchasing authority, case volume, and technology adoption velocity.
- Hospitals:Tertiary academic medical centers with dedicated craniomaxillofacial surgical programs command the largest procurement scale. England's NHS supply chain centralization is consolidating purchasing across multi-site trauma networks.
- Maxillofacial Clinics:Ambulatory surgical centers specializing in cranial defect reconstruction are capturing disproportionate volume growth. France's regional hospital groupings are qualifying vendors based on MDR certification status.
- Surgical Centers:Independent facilities perform selective osteosynthesis procedures outside hospital networks.
- Medical Research Institutes:Academic centers evaluate novel biodegradable polymer formulations and additive manufacturing techniques.
- Orthopedic Facilities:General orthopedic departments handle mandibular trauma in markets with limited maxillofacial specialist density.
- Trauma Care Units:Emergency departments initiate stabilization prior to definitive surgical intervention.
Procurement scale favors Hospitals; Maxillofacial Clinics gain share fastest.
Material:
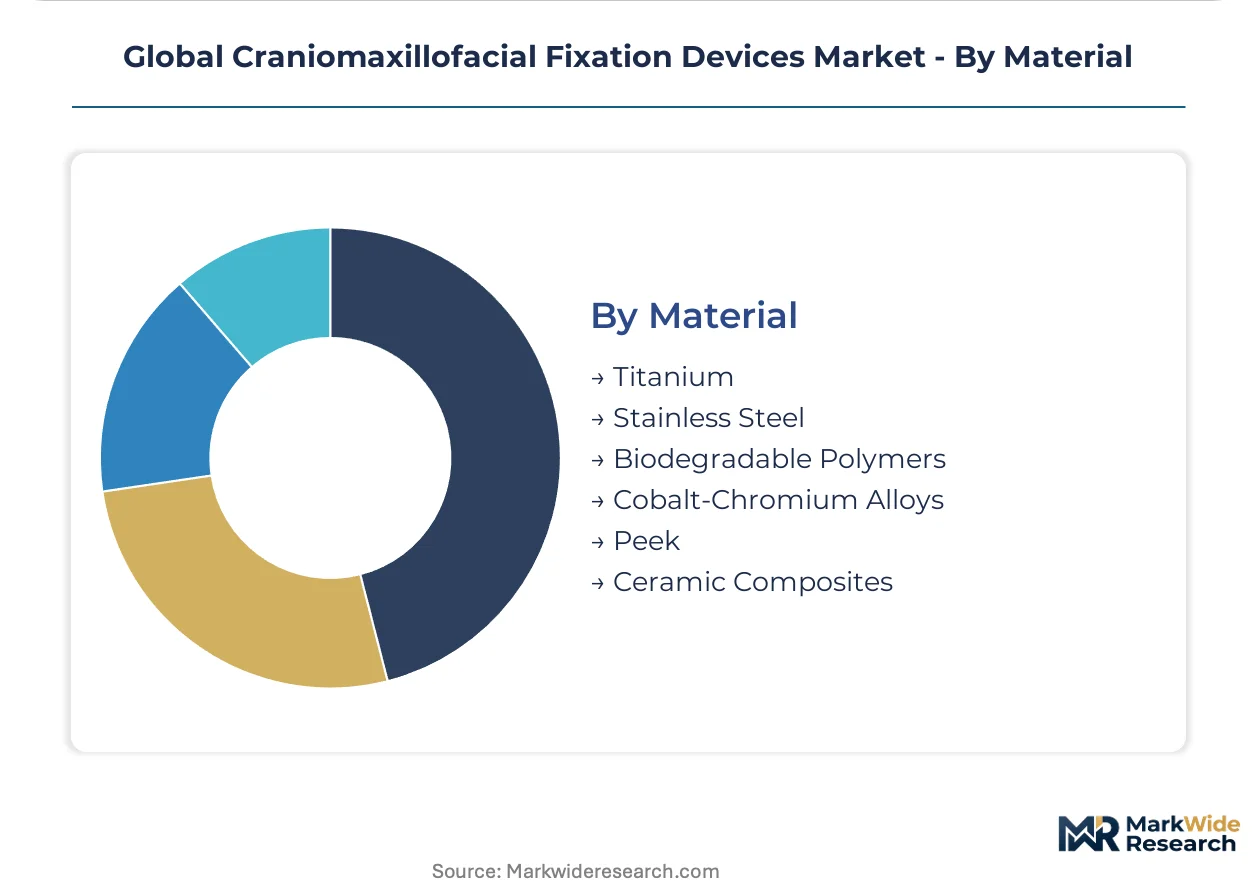
Biocompatibility, mechanical performance, and degradation kinetics determine material selection for specific anatomical applications.
- Titanium:Grade 2 and Grade 5 titanium alloys deliver superior osseointegration and fatigue resistance. Aerospace sector competition for premium-grade titanium sponge is elevating raw material costs for forging operations.
- Biodegradable Polymers:PLLA-PDGA copolymers and pure PLLA formulations eliminate secondary removal surgeries in pediatric applications. Japan's PMDA Sakigake pathway accelerates regulatory review for innovative polymer formulations.
- Stainless Steel:316L stainless steel retains cost-sensitive market share in emerging trauma networks.
- Cobalt-Chromium Alloys:High-strength alloys address load-bearing mandibular reconstruction requirements.
- PEEK:Polyetheretherketone radiolucency advantages cranial defect reconstruction with postoperative imaging clarity.
- Ceramic Composites:Experimental bioactive glass and calcium phosphate composites target osteoconductive fixation applications.
Value contribution peaks with Titanium; Biodegradable Polymers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for craniomaxillofacial fixation hardware clusters in Germany, Switzerland, and the United States, while trauma care demand expansion drives procurement growth across Japan, Brazil, and South Korea.
United States
Tertiary trauma centers in Boston and Baltimore sustain premium titanium plate procurement volumes through dedicated craniomaxillofacial surgical programs. FDA 510(k) pathways shape product development cycles for manufacturers seeking multi-region commercialization. The Cleveland Clinic and Mayo Clinic anchor specialized reconstructive surgery networks that standardize hardware configurations.
Germany
Academic medical centers in Munich and Heidelberg command the largest European procurement scale for mandibular reconstruction systems. EU MDR recertification deadlines compress supplier timelines and elevate documentation burdens for implantable cranial hardware. The Freiburg and Tübingen surgical clusters pioneer robotic-guided drilling platforms for complex midface fracture repair.
Japan
Pediatric maxillofacial clinics in Tokyo and Osaka drive biodegradable polymer screw adoption to eliminate secondary removal procedures. PMDA Sakigake pathway provisions expedite regulatory review for innovative fixation devices. The Nagoya and Kyoto medical manufacturing corridors concentrate precision machining expertise for complex plate geometries.
Brazil
Public hospital craniomaxillofacial unit investments under SUS reforms create procurement scale for plate-screw system vendors. ANVISA registration requirements filter entrants without localized regulatory infrastructure. São Paulo and Rio de Janeiro trauma networks anchor the Latin American demand concentration for emergency mandibular fixation.
South Korea
Digital surgical planning integration accelerates in Seoul and Busan tertiary centers, compressing design-to-implant timelines for patient-specific reconstruction. MFDS clinical evaluation standards govern market access for novel biodegradable formulations. The Daegu-Gyeongbuk medical device cluster supplies precision-forged titanium components to regional trauma networks.
Global Craniomaxillofacial Fixation Devices Market Competitive Landscape
The competitive structure tilts toward diversified orthopedic conglomerates with captive titanium forging capacity. Stryker and Zimmer Biomet anchor the premium tier through vertically integrated manufacturing, while mid-scale specialists concentrate on patient-specific additive manufacturing. Strategic moves center on EU MDR certification maintenance and biodegradable polymer portfolio expansion.
Among diversified orthopedic conglomerates, Stryker, Zimmer Biomet, and DePuy Synthes exemplify the scale-driven archetype that dominates procurement tenders in consolidated hospital purchasing consortia. These entities occupy positions where titanium supply chain control and regulatory infrastructure breadth determine market access. Mid-scale specialists such as KLS Martin and Medartis AG represent the precision-focused tier, anchoring regional clusters in Freiburg and Basel where CNC milling expertise concentrates.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| DePuy Synthes |
| Medtronic |
| Integra LifeSciences |
| KLS Martin |
| Medartis AG |
| OsteoMed |
| B. Braun |
| Others |
Supply & Pricing Matrix
Captive titanium forging operations anchor supply positioning and pricing power for premium plate-screw system vendors. Aerospace sector competition for premium-grade titanium sponge elevates raw material costs, while EU MDR recertification burdens compress supplier margins across European procurement tenders.
Pricing Analysis
Margin tightening in standard-grade stainless steel configurations traces to Brazilian SUS hospital procurement scale and emerging trauma network cost-down mandates. Three-tier pricing structure across premium titanium, standard stainless steel, and economy cerclage wire levels stratifies by osseointegration performance and certification grade. Pricing pressure intensifies in biodegradable polymer segments as Japan's PMDA Sakigake pathway accelerates competitive entry. Pediatric maxillofacial clinics exhibit lowest price sensitivity due to revision surgery avoidance value, while public hospital trauma networks in Brazil and India drive hardest bargain.
Supply Chain Analysis
Single-source vulnerability sits with Ukrainian titanium sponge suppliers and Swiss precision-machining clusters for complex plate geometries. Manufacturing gravity centers on Germany, Switzerland, and the United States for CNC-milled hardware, while South Korea and Japan concentrate additive powder-bed fusion capacity. Feedstock draws from aerospace-grade titanium sponge, medical-grade PEEK resin, and PLLA-PDGA copolymer pellets. Tariff exposure on Chinese-sourced raw materials threatens margin stability for mid-scale specialists. Distribution runs through hospital purchasing consortia and specialized trauma care unit partnerships rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players securing backward integration into titanium forging and additive manufacturing capabilities. Control over premium-grade feedstock and patient-specific production workflows separates consolidators from commodity suppliers.
For Market Incumbents: Anticipate biodegradable polymer substitution threats in pediatric applications by accelerating PLLA-PDGA copolymer R&D pipelines. Defend German and Japanese tertiary hospital anchoring through MDR certification maintenance and robotic-guided drilling platform co-development. Prioritize captive titanium sponge sourcing agreements to offset aerospace sector price volatility. For New Entrants and Emerging Players: Digital surgical planning platform partnerships offer the lowest-friction route to hospital system access without legacy regulatory infrastructure burdens. Target Brazil's SUS trauma network expansion and South Korea's MFDS-registered additive manufacturing clinics as penetrable white-space. Lead with patient-specific titanium mesh customization capabilities rather than commodity plate-screw catalog competition. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale specialists with EU MDR certification and additive manufacturing patient-specific workflows. Long-term viability hinges on regulatory infrastructure breadth and titanium supply chain control rather than single-product innovation. Watch PMDA Sakigake pathway biodegradable polymer approvals as inflection signal for material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | MDR technical documentation completion unlocks European hospital procurement tender eligibility. |
| Hospital System Partnership | Stryker's trauma care unit alliances in Germany secure multi-year plate-screw supply commitments. |
| Backward Integration into Titanium Forging | Captive forging capacity insulates margin from aerospace sponge price volatility. |
| Software Companion Development | Digital surgical planning integration compresses design-to-implant timelines for patient-specific mesh. |
| Reimbursement Strategy | Brazil SUS procedure coding alignment accelerates public hospital adoption velocity. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and Japanese PMDA Sakigake pathway records formed the secondary backbone for regulatory landscape mapping. Primary interviews with craniomaxillofacial surgeons, hospital purchasing committee chairs, biomedical engineers at tertiary trauma centers, and GPO contracts managers validated procurement pattern assumptions. Bottom-up triangulation across product-type volume estimates and top-down cross-check against macro healthcare expenditure trends anchored market sizing integrity.
Bottom-up modeling segmented titanium plate, biodegradable polymer screw, stainless steel wire, and PEEK mesh categories across fracture repair, reconstructive surgery, pediatric osteotomy, and cranial defect reconstruction applications. CAGRs derived from procedure volume elasticity to trauma incidence rates, material substitution curves, and hospital capital expenditure cycles. Forecast inputs incorporated EU MDR recertification timeline compression, PMDA Sakigake pathway approval velocity, and Brazilian SUS hospital network expansion cadence across the analysis window.
The model holds under stable regulatory transition timelines and titanium sponge supply continuity; deviation in MDR notified body capacity collapse or aerospace demand spikes would shift trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Global Capnography Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Global Hi-Tech Medical Devices Market