
 Table-Top Autorefractor Market | 2026-2036
Table-Top Autorefractor Market Size, Share, and Industry Trends Forecast 2026-2036
Table-Top Autorefractor Market Insights
Equipment leasing and pay-per-use financing is reshaping competitive dynamics in the table-top autorefractor landscape, lowering capital barriers for independent optometry practices. Topcon Corporation leverages its direct sales infrastructure across Japan and North America to sustain premium positioning. Nidek Co. Ltd. anchors its competitiveness through in-house optical component manufacturing. Carl Zeiss Meditec AG differentiates via wavefront technology integration in its diagnostic suite.
A table-top autorefractor is a stationary ophthalmic instrument that measures the refractive error of the eye using infrared wavefront sensing or retinoscopic principles, typically achieving resolution of 0.12 diopters or finer. The device generates objective refraction data to guide subjective prescription determination in clinical settings. Fully automated units dominate hospital procurement due to throughput requirements, while semi-automated systems retain stronghold in optometry practices where operator judgment shapes workflow economics. Wavefront technology commands margin premiums despite higher unit costs, whereas digital image processing variants are gaining traction in price-sensitive distribution channels.
FDA 510(k) clearance requirements govern market access in the United States, while CE marking under the EU MDR shapes European commercialization timelines for new table-top autorefractor introductions. Japan's PMDA and METI coordinate on optical medical device standards that influence design specifications for infrared-based systems exported across Asia-Pacific. Stakeholders must monitor evolving reimbursement codes for automated refraction in national health systems, as coverage determinations will dictate replacement cycles and upgrade decisions across installed bases.
Market Dynamics
Optical chain consolidation across Southeast Asia is compressing procurement timelines and favoring vendors with integrated diagnostic suites over standalone device manufacturers.
Growth Catalysts
- Reimbursement code expansion:National health systems in Japan and South Korea are adding automated refraction to covered services, accelerating replacement cycles in hospital ophthalmology departments.
- Infrared wavefront sensing maturation:Resolution improvements to 0.12 diopters or finer are extending diagnostic confidence into pediatric and presbyopic populations previously requiring manual verification.
- India tier-two city expansion:EssilorLuxottica and local franchise networks are building refractive screening capacity in secondary urban centers, creating concentrated demand pockets for semi-automated systems.
Market Restraints
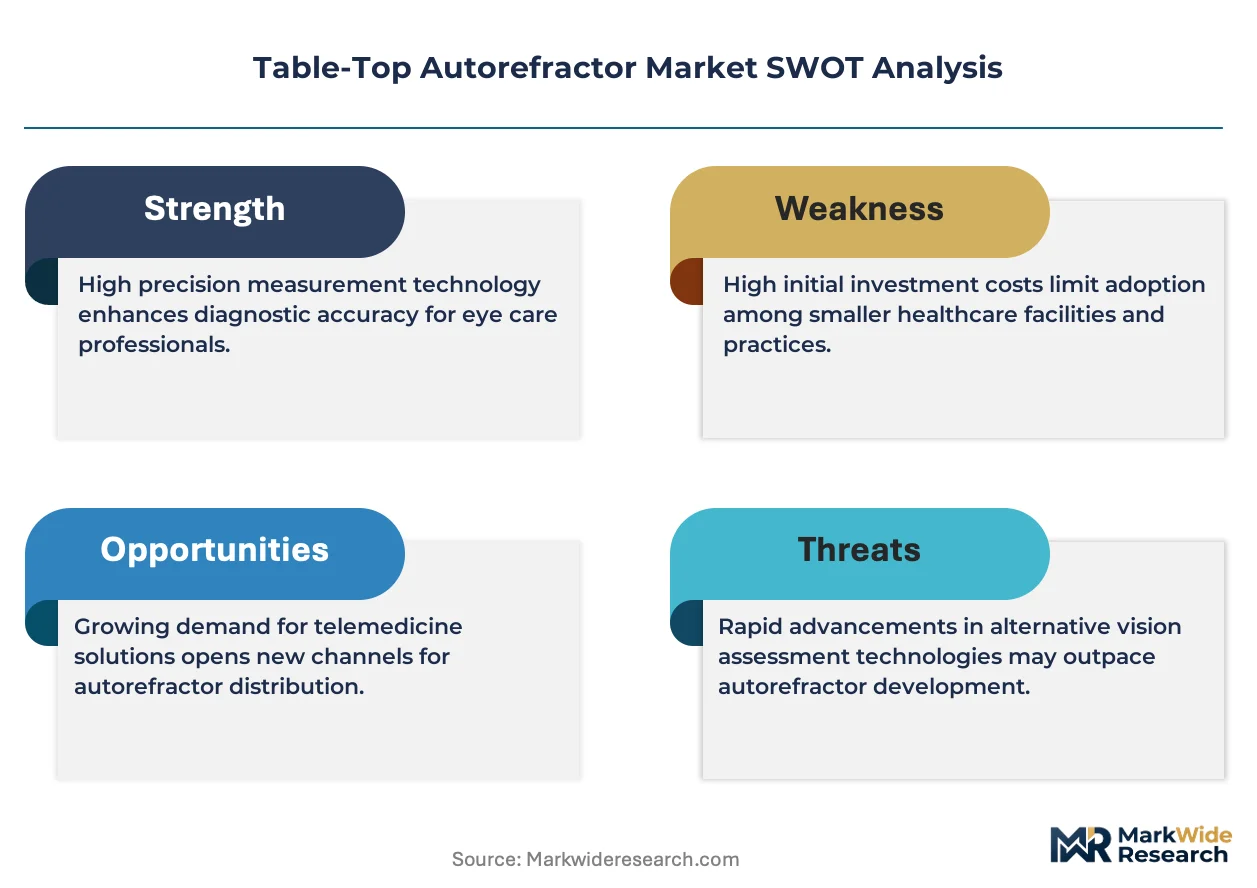
- Optical component supply concentration:In-house manufacturing capabilities at Nidek and limited qualified suppliers for precision wavefront sensors create bottlenecks during demand surges.
- CE marking timeline extension:EU MDR recertification requirements for digital image processing variants are extending commercialization timelines by twelve to eighteen months for new entrants.
- Smartphone-based refraction apps:Low-cost alternatives using smartphone cameras and AI algorithms are capturing price-sensitive screening segments in emerging markets.
Strategic Opportunities
- Equipment leasing proliferation:Pay-per-use financing models are lowering capital barriers for independent optometry practices in North America and Western Europe.
- Wavefront-integrated diagnostic suites:Convergence of autorefraction with corneal topography and optical coherence tomography is creating premium upgrade pathways in hospital settings.
- FDA 510(k) pathway compression:Streamlined clearance for software-only modifications is enabling faster feature iteration for digital image processing variants.
Industry Challenges
- Specialized technician scarcity:Wavefront system operation requires training in optical physics that exceeds standard optometric technician curricula in many markets.
- Legacy EMR integration friction:Semi-automated systems in independent practices face data interoperability barriers with proprietary practice management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Table-Top Autorefractor Market |
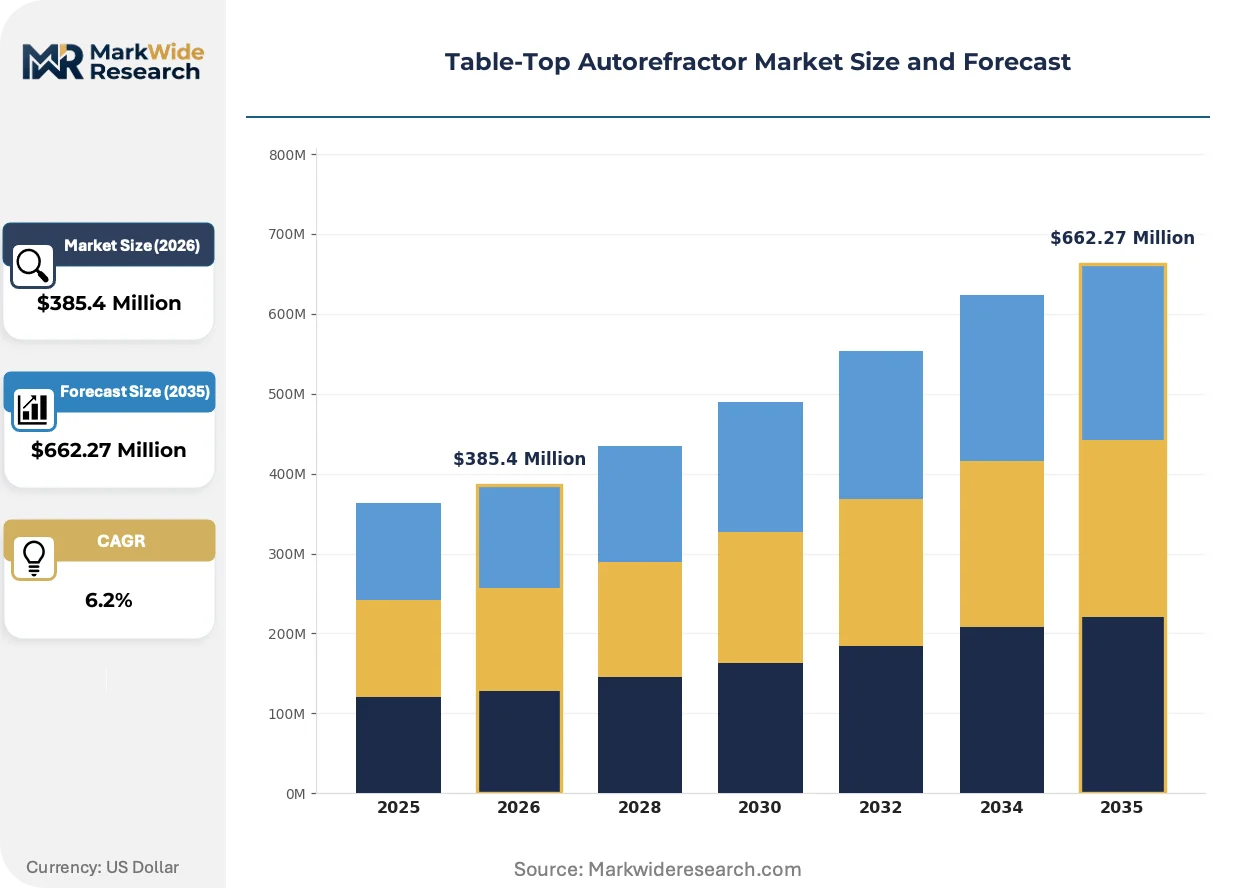
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automated, Semi-Automated, Handheld, Optical End User: Ophthalmology Clinics, Optometry Practices, Hospitals, Research Laboratories Technology: Wavefront, Refractive Index, Digital Image Processing, Infrared Distribution Channel: Direct Sales, Online Sales, Medical Equipment Distributors, Retail Stores |
| Companies Covered | Topcon Corporation, Nidek Co. Ltd., Carl Zeiss Meditec AG, Huvitz Co. Ltd., Canon Inc., EssilorLuxottica, Haag-Streit AG, Marco Ophthalmic, Rexxam Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Table-Top Autorefractor Market Trends and Innovations
Digital image processing is virtualizing core measurement functions, while regulatory frameworks and procurement models undergo parallel restructuring across major ophthalmic device markets.
Wavefront technology is virtualizing the traditional autorefractor value proposition by embedding refraction measurement within comprehensive diagnostic platforms. Hospital procurement committees now evaluate autorefractors as modules within larger capital commitments rather than standalone purchases. This convergence is compressing margins for single-function devices while rewarding vendors with integrated ophthalmic suites.
FDA 510(k) clearance pathways for software-centric devices are shortening time-to-market for algorithm-driven refraction systems. Manufacturers are submitting digital image processing variants as predicate devices to bypass lengthy clinical trials. The regulatory efficiency is attracting venture-backed entrants targeting the mid-market segment previously dominated by established optical equipment houses.
Direct sales infrastructure investments by Japanese and North American incumbents are reshaping channel economics for premium-tier systems. Independent optometry practices now expect bundled training, maintenance, and upgrade commitments within initial purchase agreements. This service unbundling is most visible in Japan, where Topcon's field engineering density supports same-day technical response that franchise networks cannot replicate.
Table-Top Autorefractor Market Segmentation
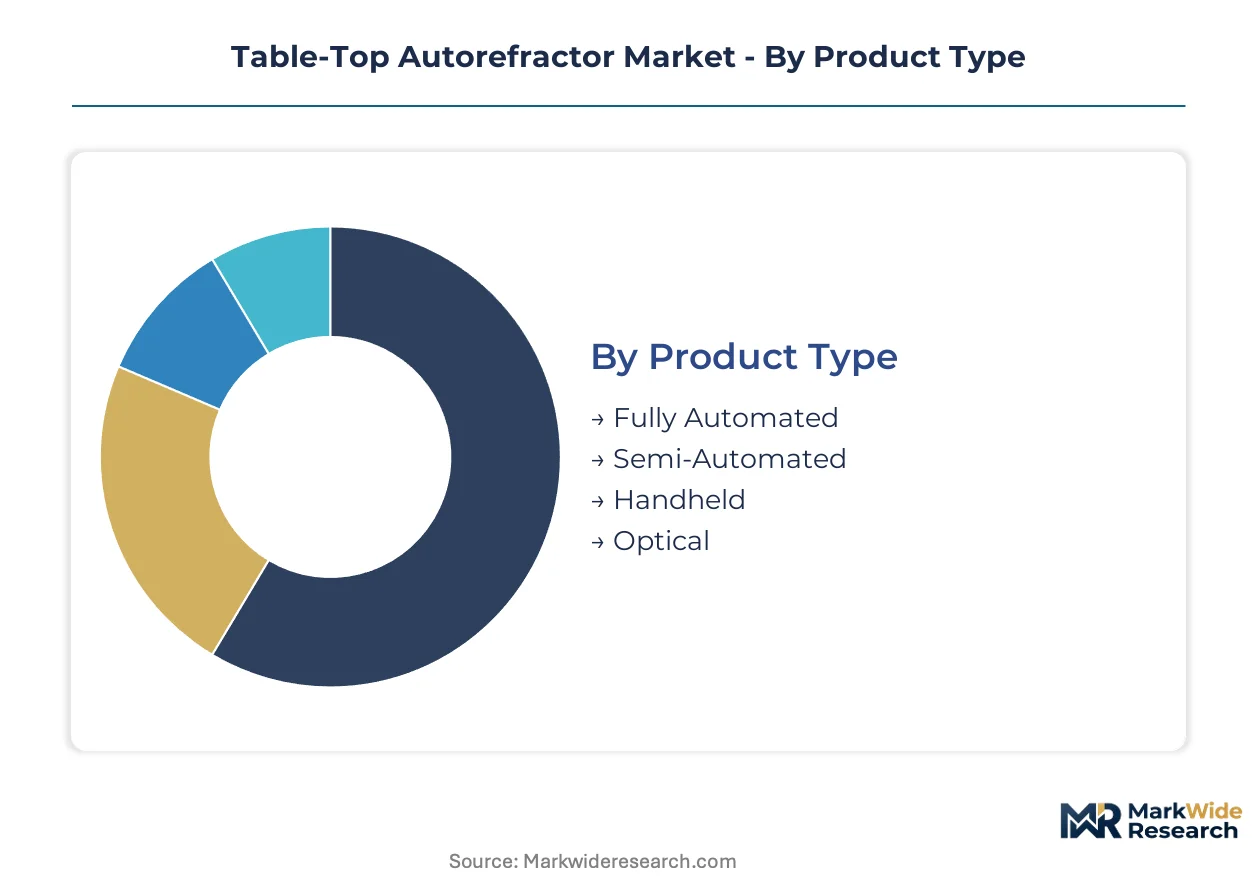
Table-top autorefractor procurement splits sharply between high-throughput hospital systems seeking diagnostic integration and independent practices prioritizing capital efficiency. Technology choices and distribution channels further stratify the vendor landscape across clinical settings.
Product Type:
Use-case spectrum spans from fully automated hospital throughput systems to operator-guided instruments preserving clinical judgment in independent settings.
- Fully Automated:These systems execute complete refraction sequences without operator intervention, achieving sub-0.12 diopter resolution through closed-loop wavefront feedback. Demand concentrates in Japanese and South Korean hospital ophthalmology departments where METI and MFDS reimbursement expansions are accelerating replacement cycles.
- Semi-Automated:Operator judgment shapes measurement sequences, allowing technicians to override algorithmic recommendations during pediatric or presbyopic examinations. India's tier-two cities show concentrated adoption where EssilorLuxottica franchise networks balance throughput against capital constraints.
- Handheld:Portable units enable screening in non-clinical settings with reduced optical bench requirements.
- Optical:Traditional retinoscopic designs persist in price-sensitive procurement channels and legacy installed bases.
Established volume favors fully automated systems; emerging adoption favors semi-automated configurations.
End User:
Customer type determines financing structure, with hospitals favoring capital purchases and independent practices gravitating toward leasing.
- Ophthalmology Clinics:Specialized diagnostic demand drives wavefront-integrated suite purchases where autorefractors function as modules within larger capital commitments. Japanese and German clinic networks are consolidating procurement around vendors with direct field service infrastructure.
- Optometry Practices:Capital efficiency priorities favor pay-per-use financing and semi-automated systems where operator labor substitutes for automation premiums. North American independent practices are driving equipment leasing proliferation.
- Hospitals:Throughput requirements and EMR integration mandates dominate procurement specifications.
- Research Laboratories:Precision specifications and custom algorithm development shape niche demand.
Procurement concentration tilts toward ophthalmology clinics; financing innovation centers on optometry practices.
Technology:
Resolution benchmarks and regulatory pathways differentiate technology choices across clinical applications.
- Wavefront:Hartmann-Shack sensor arrays achieve comprehensive optical aberration mapping beyond spherical and cylindrical corrections. Hospital procurement committees in Japan and Germany are integrating these systems with corneal topography and OCT platforms.
- Digital Image Processing:Algorithm-driven analysis of retinal reflex patterns enables software-centric device architectures with compressed FDA 510(k) timelines. Venture-backed entrants are targeting mid-market segments with predicate device submissions.
- Refractive Index:Traditional measurement principles retain cost advantages in screening applications.
- Infrared:PMDA-METI coordinated standards for infrared-based systems influence design specifications across Asia-Pacific exports.
Margin premiums accrue to wavefront systems; regulatory efficiency favors digital image processing variants.
Distribution Channel:
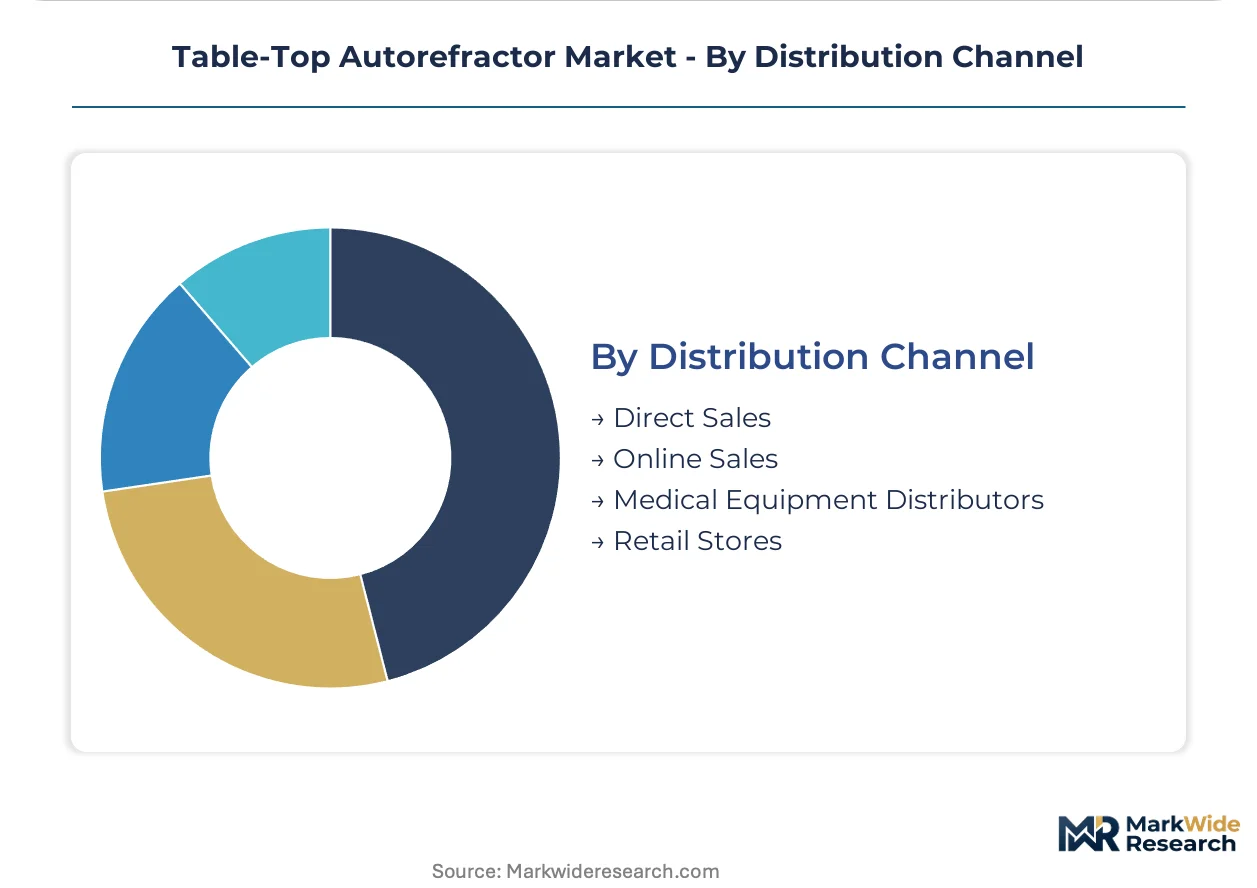
Channel economics diverge between premium-tier direct sales requiring field engineering density and volume-oriented distributor networks.
- Direct Sales:Bundled training, maintenance, and upgrade commitments characterize premium-tier procurement in Japan and North America. Topcon's field engineering density supports same-day technical response that franchise networks cannot replicate.
- Medical Equipment Distributors:Multi-vendor portfolios and regional credit facilities serve mid-market price sensitivity in Southeast Asian optical chain consolidation.
- Online Sales:Digital procurement channels are gaining traction for replacement components and consumables.
- Retail Stores:Limited penetration given clinical validation requirements and regulatory compliance burdens.
Service unbundling distinguishes direct sales; geographic reach defines distributor competitiveness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-tier pricing power concentrates in Japanese metropolitan clusters where direct sales infrastructure commands service premiums, while Indian tier-two procurement favors capital-efficient semi-automated configurations that compress vendor margins.
Japan
Hospital ophthalmology departments in Tokyo and Osaka drive replacement cycles for fully automated wavefront systems. METI coordinates with PMDA on optical medical device standards that shape infrared-based system specifications. Kanto region procurement committees prioritize vendors with same-day field engineering response capabilities.
United States
Independent optometry practices across Texas and Florida are adopting equipment leasing models to lower capital barriers. FDA 510(k) clearance pathways for digital image processing variants are compressing commercialization timelines for new market entrants. Greater Boston's research hospital networks anchor demand for diagnostic suite integration.
Germany
Clinic networks in Bavaria and Baden-Württemberg consolidate procurement around integrated ophthalmic suites. CE marking under EU MDR governs commercialization timelines for wavefront technology introductions. Stuttgart's precision optics cluster supplies specialized Hartmann-Shack sensor arrays to regional device manufacturers.
India
EssilorLuxottica franchise expansion in Maharashtra and Gujarat tier-two cities creates concentrated demand pockets for semi-automated systems. CDSCO medical device registration requirements shape import timelines for foreign manufacturers. Karnataka's Bangalore-Tier-two corridor sees rapid refractive screening capacity buildout.
South Korea
Hospital ophthalmology departments in Seoul and Busan accelerate replacement cycles following MFDS reimbursement expansion for automated refraction. National health system coverage determinations dictate upgrade decisions across installed bases. Daegu-Gyeongbuk's medical device manufacturing cluster supplies precision optical components to domestic vendors.
Table-Top Autorefractor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between consolidated diagnostic suite providers and fragmented standalone device manufacturers. Three archetypes dominate: vertically integrated optical houses, venture-backed algorithm specialists, and precision component fabricators. Competitive dynamics center on M&A activity for diagnostic suite integration and geographic expansion through direct sales infrastructure investments.
Within the integrated platform tier, Topcon Corporation and Nidek Co. Ltd. represent established Japanese optical houses with captive manufacturing capabilities, while Carl Zeiss Meditec AG exemplifies the German precision engineering archetype. These three anchors occupy positions defined by geographic sales density and in-house component production rather than pure technology differentiation.
| Leading Market Players |
|---|
| Topcon Corporation |
| Nidek Co. Ltd. |
| Carl Zeiss Meditec AG |
| Huvitz Co. Ltd. |
| Canon Inc. |
| EssilorLuxottica |
| Haag-Streit AG |
| Marco Ophthalmic |
| Rexxam Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japanese Hartmann-Shack sensor arrays determines both three-tier pricing spreads across premium, standard, and economy levels and supply chain configuration for wavefront-integrated systems. FDA 510(k) pathway compression for digital image processing variants is widening price spreads between algorithm-driven entrants and precision optics incumbents.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers, with wavefront-integrated suites commanding premiums based on METI-certified resolution benchmarks and same-day field engineering density. Cost compression in semi-automated configurations is intensifying because EssilorLuxottica franchise networks in India negotiate volume-scale discounts against capital constraints. Independent optometry practices in North America exhibit highest price sensitivity, while Japanese hospital ophthalmology departments show lowest sensitivity due to bundled service commitments.
Supply Chain Analysis
Export-control alignment between METI and PMDA on infrared optical standards limits component flows from Japan to non-aligned manufacturing destinations, concentrating precision wavefront sensor production in Osaka and Nagoya precision clusters. Supply draws from specialized Hartmann-Shack sensor arrays, infrared emitter assemblies, and algorithm processing modules. Single-source vulnerability persists for sub-0.12 diopter resolution sensors qualified under PMDA optical medical device standards. Distribution runs through direct sales infrastructure for premium-tier systems and regional medical equipment distributors for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as hospital procurement committees evaluate autorefractors as modules within diagnostic suites rather than standalone capital purchases. Interoperability with EMR systems and corneal topography platforms determines vendor selection criteria.
For Market Incumbents: Entrench diagnostic suite integration by embedding wavefront autorefraction within comprehensive ophthalmic platforms that combine corneal topography and OCT capabilities. Deepen backward integration into Hartmann-Shack sensor manufacturing to defend against supply bottlenecks during demand surges. Prioritize same-day field engineering density in Japanese and North American metropolitan clusters where service response times differentiate premium positioning.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-two city expansion corridors where EssilorLuxottica franchise networks seek capital-efficient semi-automated configurations. Target pay-per-use financing channels for North American independent optometry practices seeking to lower capital barriers. Pursue FDA 510(k) predicate device submissions for digital image processing variants to compress commercialization timelines relative to wavefront hardware development cycles.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with captive component manufacturing and direct sales infrastructure. Long-term viability hinges on diagnostic suite convergence rather than standalone device margins. Monitor reimbursement code expansion in national health systems as the primary inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Suite Integration | Hospital procurement committees now mandate autorefractor interoperability with corneal topography and OCT platforms. |
| CE Marking Pathway Investment | EU MDR recertification timelines for digital image processing variants extend commercialization by twelve to eighteen months. |
| Equipment Leasing Proliferation | Pay-per-use financing lowers capital barriers for independent optometry practices across North America and Western Europe. |
| Software Companion Development | Algorithm-driven refraction systems bypass lengthy clinical trials through FDA 510(k) predicate device submissions. |
| Reimbursement Strategy | METI and MFDS coverage expansions for automated refraction accelerate hospital replacement cycles in Japan and South Korea. |
Research Methodology
Initial hypotheses were tested against primary input from hospital ophthalmology department heads, independent optometry practice owners, biomedical equipment procurement managers, and GPO contracts specialists, then refined against secondary validation from FDA 510(k) clearance databases, PMDA medical device registration filings, METI optical standards documentation, and hospital capital expenditure records. Bottom-up installation base modeling and top-down market sizing triangulated volume estimates across the analysis window.
Demand-supply balance framing anchored the analytical approach, with segmentation dimensions spanning product type automation level, end-user clinical setting, wavefront versus digital image processing technology, and direct sales versus distributor channel. CAGRs derived from replacement cycle analysis, reimbursement code expansion trajectories, and tier-two city capacity buildout patterns. Forecast inputs incorporated infrared wavefront sensor resolution maturation and optical chain consolidation timelines.
Sensitivities concentrate around regulatory pathway shifts, reimbursement coverage determinations, and supply concentration in precision optical components. Forecasts reflect documented assumptions on technology adoption curves and procurement model evolution. Material shifts in FDA 510(k) clearance efficiency or EU MDR recertification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United Kingdom Minimally Invasive Surgery Devices Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Cranial Perforator Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Capnography Devices Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Asia-Pacific Biosurgery Market
Medical Devices
Light Therapy Beauty Devices Market