
 Ultrasonic Nebulizers Market | 2026-2036
Ultrasonic Nebulizers Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Nebulizers Market Analytics
Homecare providers are redrawing procurement patterns in the ultrasonic nebulizer landscape, pulling volume away from acute-care purchasing departments. Koninklijke Philips N.V. leverages its sleep-and-respiratory platform to bundle nebulizers with ventilatory support ecosystems. OMRON Healthcare anchors its position through pharmacy and retail channel dominance across Asian and European markets. Drive Medical competes on value-engineered tabletop systems that sustain Medicare reimbursement compliance.
An ultrasonic nebulizer converts electrical energy into high-frequency mechanical vibrations, typically operating at 1–3 MHz, to generate a fine aerosol mist from liquid medication without thermal degradation of active pharmaceutical ingredients. The device serves primarily to deliver bronchodilators, corticosteroids, and antibiotics directly to the lower respiratory tract in patients with obstructive or infectious pulmonary conditions. Portable units command expanding share as battery density improvements and miniaturized piezoelectric transducers enable ambulatory therapy, while tabletop systems retain institutional preference where continuous-duty cycles and higher output volumes dominate. Pediatric configurations represent a specialized margin pool, with mask ergonomics and noise suppression driving differentiation.
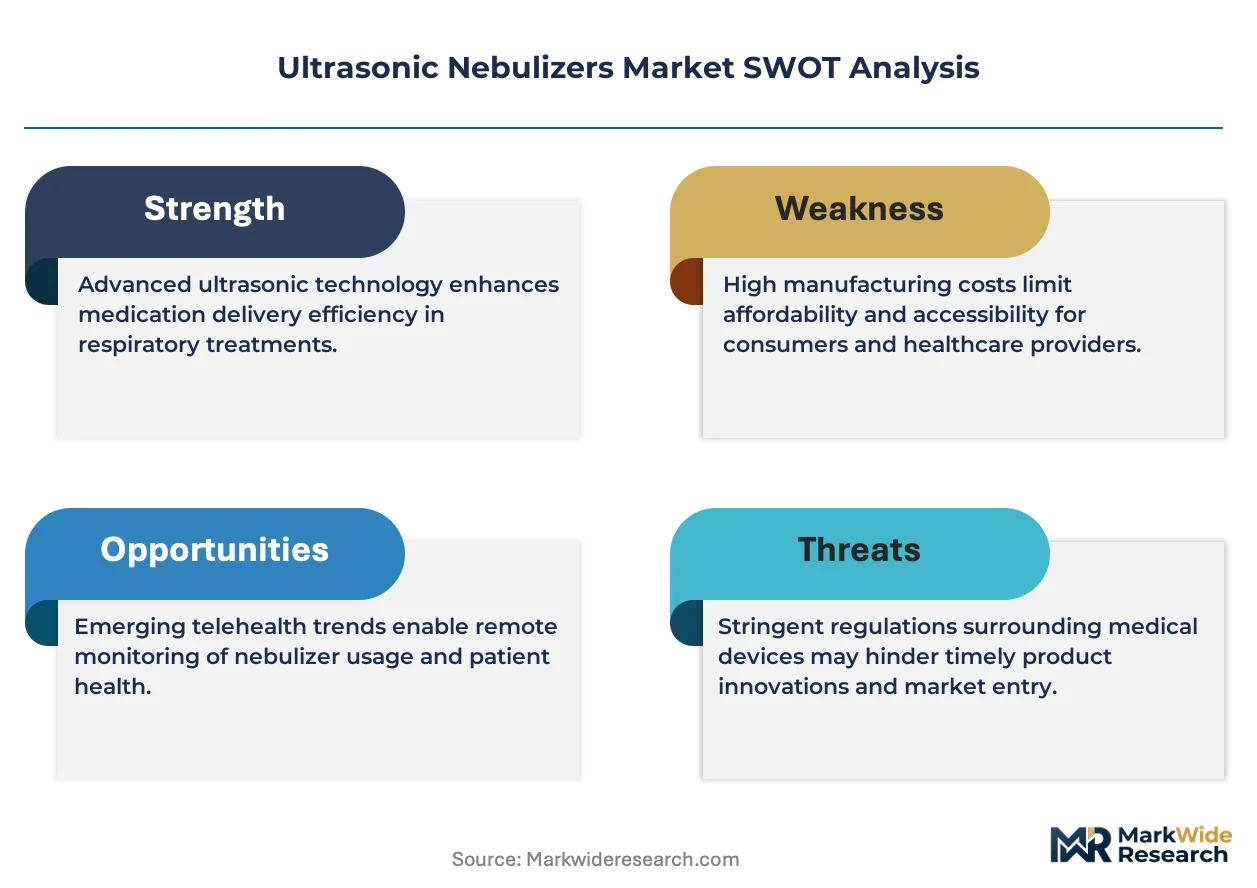
The FDA's 510(k) framework and the EU Medical Device Regulation impose divergent clinical-evidence requirements that fragment product-registration strategies and extend time-to-market for multi-region launches. ISO 27427 standards for nebulizing systems further constrain design parameters around particle-size distribution and delivered-dose consistency, favoring manufacturers with captive metrology capabilities. Stakeholders must monitor reimbursement coding revisions for home respiratory therapy, as payor compression on durable medical equipment threatens to offset volume gains from demographic expansion.
Market Dynamics
The migration of respiratory therapy from hospital wards to domestic environments is restructuring ultrasonic nebulizer procurement, with homecare distributors now commanding volume allocations that acute-care purchasing departments once monopolized.
Growth Catalysts
- EU MDR compliance deadlines:Stricter clinical-evidence requirements for nebulizing systems are accelerating replacement cycles as legacy devices face registration sunset clauses, pulling forward demand for next-generation hardware.
- Piezoelectric transducer miniaturization:Advances in MEMS fabrication are enabling palm-sized portable units that match tabletop output specifications, unlocking ambulatory therapy for COPD patients previously tethered to stationary systems.
- Japan's super-aged society:METI reimbursement expansions for home respiratory equipment are channeling procurement volume toward ultrasonic platforms with extended battery life and simplified elder interfaces.
Market Restraints
- Piezoelectric ceramic supply concentration:High-purity lead zirconate titanate feedstock originates from a narrow supplier base concentrated in East Asian refining corridors, exposing manufacturers to input volatility and export-control friction.
- FDA 510(k) evidentiary burdens:Substantial equivalence demonstrations for ultrasonic nebulizers now require particle-size distribution studies and delivered-dose uniformity data that extend development timelines and compress early-mover advantages.
- Mesh nebulizer substitution:Vibrating-membrane alternatives are capturing pediatric and antibiotic-delivery segments where residual drug volume minimization outweighs ultrasonic throughput advantages.
Strategic Opportunities
- India's Ayushman Bharat homecare expansion:Government-mandated coverage for domiciliary respiratory therapy is opening reimbursement pathways for cost-optimized ultrasonic systems targeting tier-2 and tier-3 cities.
- Smart inhaler convergence:Integration of ultrasonic nebulizers with Bluetooth dose-tracking and cloud-based adherence analytics is creating premium positioning for connected-device ecosystems in managed-care contracts.
- Pharmacy channel bypass:Direct-to-patient subscription models for nebulizer-plus-medication bundles are circumventing traditional durable-medical-equipment distributors, capturing margin and consumption data simultaneously.
Industry Challenges
- ISO 27427 metrology capability gaps:In-house laser diffraction and cascade impaction testing infrastructure requires capital outlays that strain mid-tier manufacturers, forcing reliance on third-party laboratories with extended queue times.
- Legacy device interoperability:Homecare providers operating mixed fleets of pneumatic, ultrasonic, and mesh systems face workflow fragmentation that complicates staff training and maintenance scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Nebulizers Market |
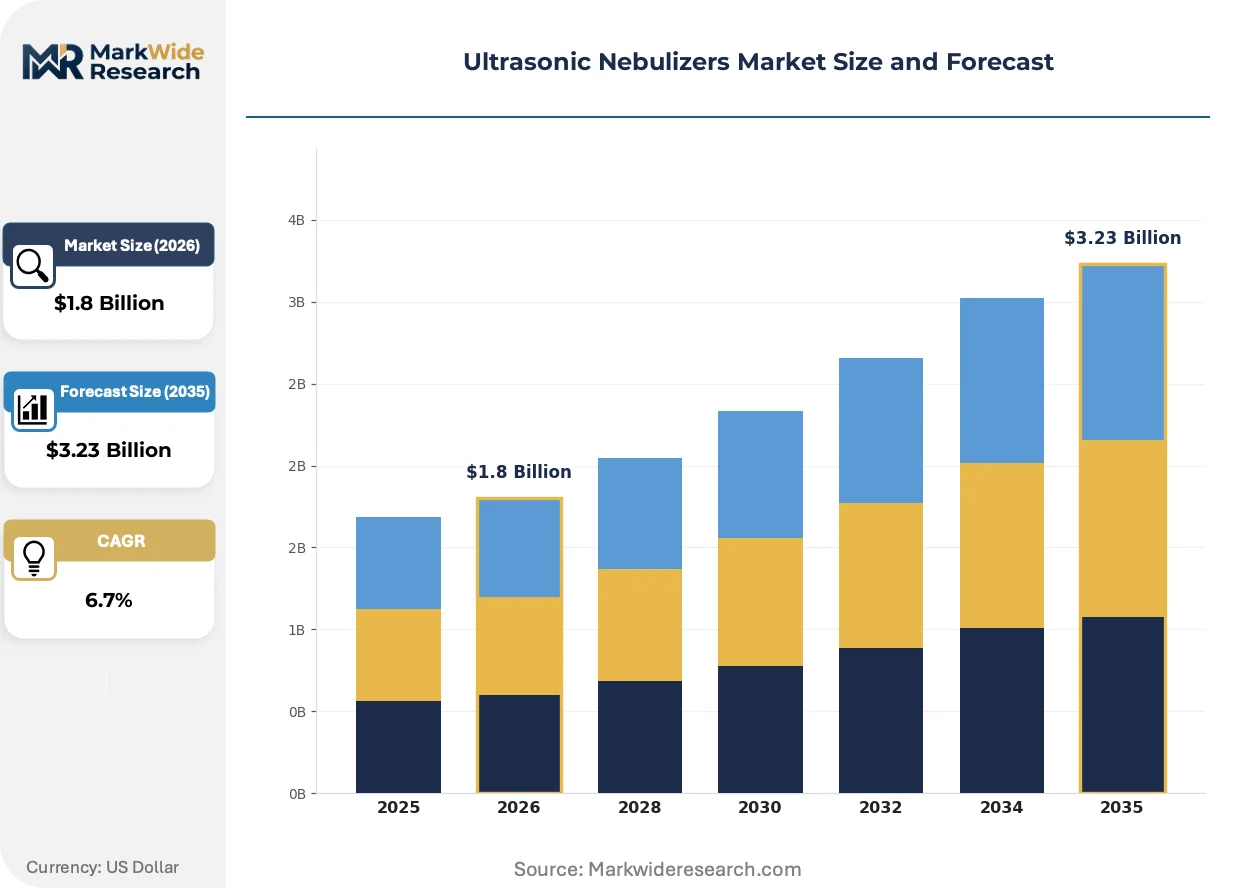
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Tabletop, Rechargeable, Pediatric End User: Hospitals, Clinics, Homecare, Ambulatory Care Technology: Ultrasonic, Mesh, Jet, Vibrating Mesh Application: Asthma, COPD, Cystic Fibrosis, Pneumonia |
| Companies Covered | Koninklijke Philips N.V., OMRON Healthcare, Drive Medical, Invacare Corporation, Agilent Technologies, AireHealth, Inspired Medical, Mercury Medical, Besmed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Nebulizers Market Evolving Landscape
Active pharmaceutical ingredient stability and aerosol physics are converging to redefine ultrasonic nebulizer design priorities, with thermal management and particle-size engineering now central to competitive differentiation rather than peripheral specifications.
Silicon-based MEMS piezoelectric arrays are supplanting conventional bulk-ceramic transducers in next-generation portable units, enabling sub-100-gram form factors without sacrificing nebulization rate. Homecare providers in Germany and the Netherlands are piloting these systems for post-discharge COPD management. The structural consequence is a compression in tabletop system margins as ambulatory platforms capture replacement cycles previously reserved for stationary hardware.
REACH restrictions on lead-containing electronics are forcing reformulation of piezoelectric ceramics across EU-bound product lines, with manufacturers accelerating lead-free perovskite research to maintain CE marking eligibility. The industrial consequence is a bifurcation in component supply chains, with EU-dedicated SKUs diverging from global platforms. Pediatric configurations face the tightest compliance timelines given their proximity to vulnerable-user regulatory scrutiny.
Hospital-at-home programs are consolidating nebulizer procurement under single-source respiratory-therapy contracts that bundle devices, disposables, and remote monitoring into per-patient-per-month fees. Traditional durable-medical-equipment distributors are losing position to integrated service organizations with clinical staffing capabilities. This consolidation is most visible in United States Medicare Advantage plans and United Kingdom NHS integrated care systems, where capitated respiratory budgets favor full-service vendors over hardware-only suppliers.
Ultrasonic Nebulizers Market Segmentation
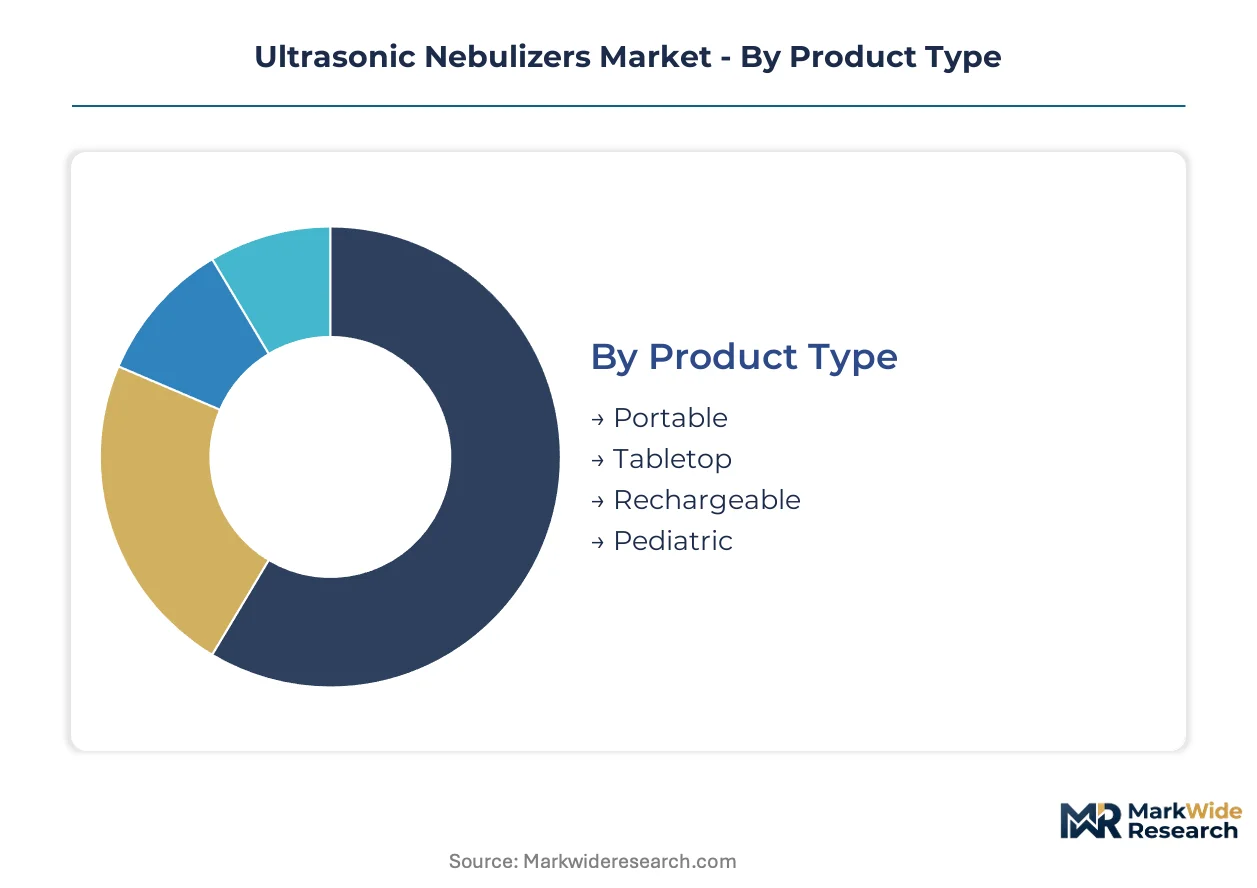
Ultrasonic nebulizer procurement splits sharply across clinical and domestic channels, with product specifications, reimbursement codes, and patient mobility requirements determining which configurations flow through hospital purchasing departments versus retail pharmacy networks.
Product Type:
Portable units dominate pharmacy and direct-to-patient channels, while tabletop systems retain institutional procurement through group purchasing organizations and hospital supply chains.
- Portable:Battery-powered units under 200 grams leverage MEMS piezoelectric arrays to match stationary output. Demand concentrates in Japan's home respiratory programs and Germany's hospital-at-home initiatives, where ambulatory COPD management reimburses mobile devices.
- Tabletop:Continuous-duty systems with 8-hour operational cycles serve institutional settings requiring high-volume aerosol generation. Acute-care purchasing departments in the United States and United Kingdom favor these units for their interoperability with existing respiratory therapy workflows.
- Rechargeable:Lithium-ion configurations bridge stationary and ambulatory use cases, appealing to homecare providers seeking fleet standardization across mixed patient populations.
- Pediatric:Mask-optimized designs with noise suppression below 35 decibels target young patients with asthma and cystic fibrosis, commanding premium positioning through specialized distribution.
By volume, Portable leads. By growth pace, Pediatric is expanding most quickly.
End User:
Procurement authority and reimbursement pathways determine margin capture, with capitated homecare contracts compressing hardware margins while fee-for-service clinical settings sustain premium pricing.
- Hospitals:Centralized respiratory therapy departments drive consolidated purchasing of tabletop systems under multi-year equipment leases. FDA 510(k) clearance and ISO 27427 compliance are non-negotiable entry requirements.
- Homecare:Domiciliary respiratory programs in the United States Medicare Advantage and United Kingdom NHS integrated care systems are displacing acute-care volume. These contracts bundle devices, disposables, and remote monitoring into per-patient-per-month fees.
- Clinics:Outpatient pulmonary practices favor mid-sized rechargeable units that balance patient throughput with space constraints.
- Ambulatory Care:Urgent care and emergency department settings prioritize rapid-deployment portable systems for acute bronchospasm management.
Homecare now matches Hospitals in unit volume, with Ambulatory Care climbing fastest.
Technology:
Cost tier and residual drug volume requirements segment the technology landscape, with ultrasonic platforms defending share in corticosteroid delivery while mesh alternatives capture antibiotic applications.
- Ultrasonic:Piezoelectric transduction at 1–3 MHz generates thermally neutral aerosols ideal for heat-sensitive active pharmaceutical ingredients. This technology anchors the analysis scope and retains dominance in bronchodilator and corticosteroid delivery.
- Mesh:Vibrating-membrane systems minimize residual drug volume below 0.1 milliliters, displacing ultrasonic units in pediatric antibiotic therapy where medication conservation outweighs throughput considerations.
- Jet:Pneumatic compression nebulizers persist in cost-sensitive markets and legacy fleet replacements, though their noise profile and treatment duration disadvantage them in homecare expansion.
- Vibrating Mesh:Advanced membrane geometries with multiple apertures per square millimeter enable precise particle-size targeting for deep lung deposition in cystic fibrosis patients.
Ultrasonic maintains installed-base leadership, though Vibrating Mesh is gaining share fastest in premium segments.
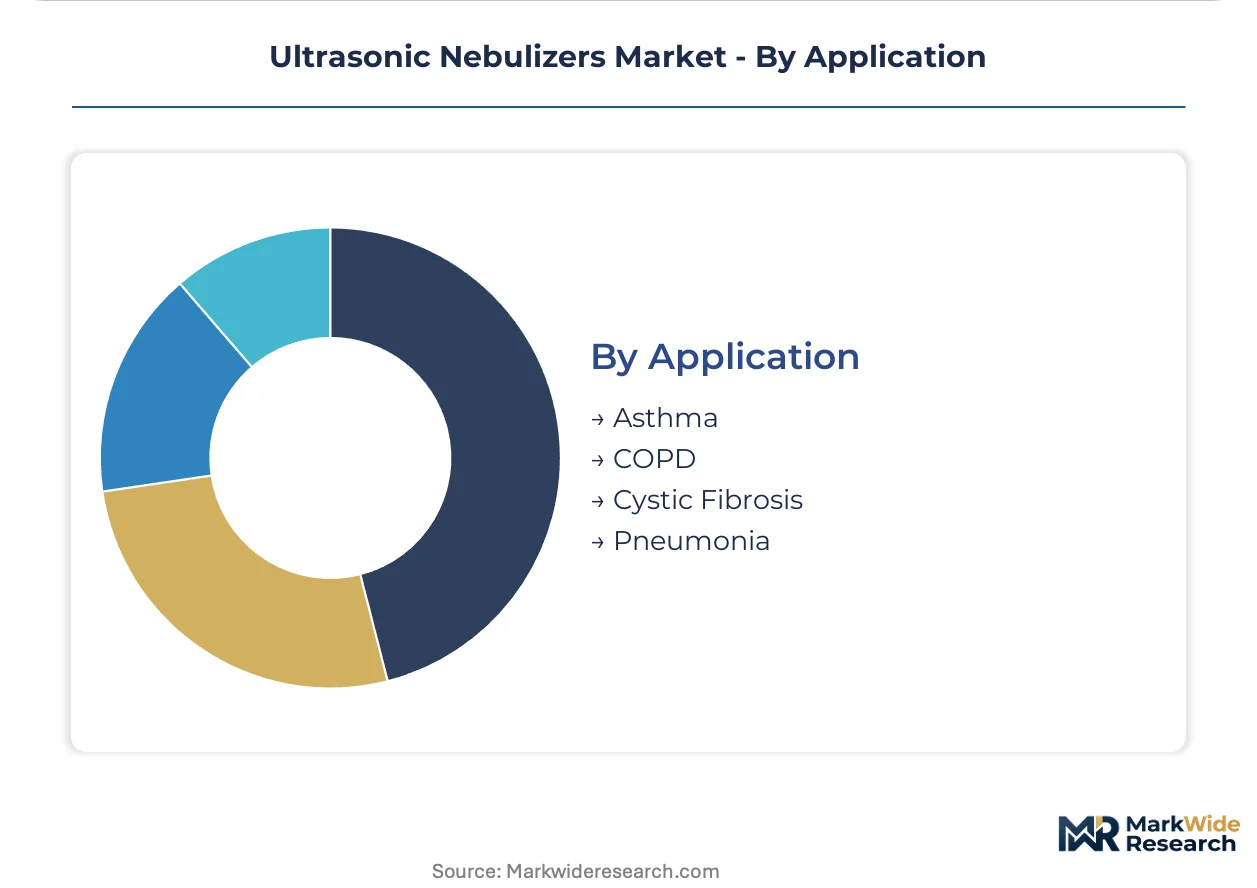
Application:
Disease prevalence and therapy duration shape device selection, with chronic conditions driving recurring revenue through consumable attachments and acute infections favoring lower-cost disposable systems.
- COPD:Progressive obstructive pathology requires long-term bronchodilator and corticosteroid administration. Homecare providers in Japan's super-aged society and the United States deploy portable ultrasonic units for daily maintenance therapy.
- Asthma:Pediatric and adult populations with intermittent symptoms favor rapid-onset delivery systems. Pharmacy channel penetration concentrates in urban United States and European markets where patient self-management is culturally established.
- Cystic Fibrosis:Thick mucus clearance demands high-output nebulization with hypertonic saline and dornase alfa. Specialized clinics prescribe vibrating-mesh or premium ultrasonic systems with extended duty cycles.
- Pneumonia:Acute infectious episodes in institutional settings drive short-term antibiotic nebulization, with cost pressures favoring jet or standard ultrasonic platforms over premium alternatives.
COPD generates the largest addressable patient base, while Cystic Fibrosis commands the steepest expansion trajectory in per-patient device revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturers ship piezoelectric transducer assemblies to European and North American device integrators, with component trade flows concentrated through Shanghai, Shenzhen, and Yokohama export corridors.
United States
Medicare Advantage capitation models are consolidating home respiratory procurement under integrated service contracts. FDA 510(k) clearance timelines for nebulizer systems now average 14–18 months with enhanced particle-size distribution requirements. Minneapolis and Boston medical-device clusters host the largest concentration of respiratory therapy platform developers.
Germany
Hospital-at-home reimbursement under G-DRG transition rules is channeling procurement toward ambulatory-compatible ultrasonic systems. EU MDR compliance deadlines are accelerating replacement cycles for legacy devices. The MedTech cluster around Tübingen and Freiburg specializes in MEMS piezoelectric fabrication for portable nebulizer platforms.
Japan
METI reimbursement expansions for home respiratory equipment are driving demand for extended-battery portable units. PMDA streamlined review pathways for designated medical devices reduce time-to-market for next-generation systems. Osaka-based precision ceramics suppliers dominate high-purity lead zirconate titanate feedstock production.
India
Ayushman Bharat domiciliary care coverage is opening reimbursement pathways for cost-optimized ultrasonic systems in tier-2 and tier-3 cities. CDSCO medical device rules align with ISO 27427 standards for aerosol performance testing. Bengaluru and Hyderabad electronics manufacturing corridors are developing local piezoelectric transducer assembly capacity.
China
NMPA Class II medical device registration reforms are compressing approval timelines for domestically manufactured nebulizer platforms. Dual carbon policy mandates are accelerating lead-free piezoelectric ceramic research. Shenzhen and Suzhou industrial zones concentrate MEMS fabrication and medical device contract manufacturing.
Ultrasonic Nebulizers Market Competitive Landscape
Player mix skews toward diversified respiratory-platform conglomerates with captive distribution networks. Consolidation pressure intensifies as hospital-at-home procurement favors full-service vendors over hardware-only suppliers. Three archetypes dominate: sleep-and-respiratory ecosystem bundlers, pharmacy-channel specialists, and value-engineered tabletop fabricators. Geographic expansion and strategic partnerships represent the primary competitive vectors as manufacturers seek reimbursement-aligned market access.
Within the ecosystem-bundler tier, Koninklijke Philips N.V. and OMRON Healthcare exemplify divergent geographic anchoring strategies. Philips occupies a position tied to North American and European institutional procurement through integrated ventilatory support platforms. OMRON represents pharmacy-channel dominance across Asian and European retail markets. Drive Medical sits within the value-engineered segment, exemplifying Medicare reimbursement compliance as a competitive differentiator in United States homecare procurement.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| OMRON Healthcare |
| Drive Medical |
| Invacare Corporation |
| Agilent Technologies |
| AireHealth |
| Inspired Medical |
| Mercury Medical |
| Besmed |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for high-purity lead zirconate titanate ceramics concentrate pricing power with East Asian feedstock suppliers, forcing device integrators in North America and Europe to absorb input volatility or reformulate for lead-free alternatives. This inventory exposure cascades through contract negotiations, with multi-year purchasing agreements increasingly indexing raw material costs rather than fixing them.
Pricing Analysis
Next-generation MEMS-based portable units command 40-60% premiums over prior-generation bulk-ceramic tabletop systems, while value-engineered rechargeable configurations fill the mid-market gap. Pricing stratifies across premium, standard, and economy tiers based on ISO 27427 certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because India's Ayushman Bharat reimbursement mandates are pulling procurement toward cost-optimized hardware. Hospital purchasing committees exhibit the lowest price sensitivity due to capitated respiratory therapy budgets, while tier-2 and tier-3 homecare distributors in emerging markets face acute margin pressure.
Supply Chain Analysis
China and Japan anchor piezoelectric ceramic production, with Osaka-based precision ceramics suppliers and Shenzhen MEMS fabrication corridors feeding component assemblies to device integrators in Germany and the United States. Manufacturing draws from high-purity lead zirconate titanate feedstock, lithium-ion battery cells, and medical-grade polymer housings. Single-source vulnerability concentrates in East Asian refining corridors where export-control friction threatens ceramic supply continuity. Distribution runs through hospital group purchasing organizations in North America, pharmacy retail networks across Asia and Europe, and direct-to-patient subscription platforms in managed care systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasonic nebulizer penetration sits at early-cycle expansion as hospital-at-home programs convert acute-care respiratory volume to domiciliary settings. Japan's super-aged society and India's Ayushman Bharat coverage expansion provide structural tailwinds for device procurement.
For Market Incumbents: Compound platform stickiness by bundling nebulizers with ventilatory support ecosystems and remote monitoring services, then backward integrate into MEMS piezoelectric fabrication to offset ceramic supply volatility. Mesh nebulizer substitution in pediatric antibiotic delivery threatens ultrasonic share; defend by accelerating lead-free perovskite R&D to maintain EU CE marking eligibility ahead of REACH deadlines. For New Entrants and Emerging Players: Pharmacy-channel adherence analytics represent an underserved service layer where incumbents under-serve, creating entry points for Bluetooth-enabled dose-tracking platforms. Target India's tier-2 and tier-3 cities through Ayushman Bharat reimbursement pathways, deploying cost-optimized portable units through government-contracted distributors rather than competing for hospital purchasing committee attention. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant respiratory device divisions lacking homecare distribution capabilities. Five-to-ten-year viability hinges on regulatory alignment with FDA 510(k) and EU MDR compliance trajectories. Watch for PMDA streamlined review pathway designations in Japan as an inflection signal for next-generation portable platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance deadlines accelerate replacement cycles for legacy nebulizer systems. |
| Hospital System Partnership | Capitated respiratory contracts in United States Medicare Advantage favor full-service vendors. |
| Backward Integration | In-house MEMS fabrication reduces exposure to East Asian ceramic supply volatility. |
| Software Companion Development | Bluetooth dose-tracking platforms capture adherence data for managed care contracting. |
| Reimbursement Strategy | Ayushman Bharat domiciliary coverage opens tier-2 and tier-3 procurement pathways. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital respiratory therapy directors, homecare procurement managers, biomedical engineers, GPO contracts specialists, and pharmacy channel distributors. Secondary validation drew from FDA 510(k) filings, EU MDR registration databases, CMS Medicare reimbursement schedules, and ISO 27427 certification records. Bottom-up unit demand estimates triangulated against top-down market sizing across product type, end user, technology, and application segments.
Across the analysis window, volume and value outputs reflect modeled assumptions for portable, tabletop, rechargeable, and pediatric configurations interacting with COPD, asthma, cystic fibrosis, and pneumonia patient populations. CAGRs were derived from replacement cycle dynamics, reimbursement expansion trajectories, and technology substitution elasticities. Forecast inputs incorporated piezoelectric transducer miniaturization curves, battery density improvement rates, and regulatory approval timeline distributions.
Forecasts assume regulatory continuity in FDA 510(k) and EU MDR regimes; material policy shifts would require re-modeling around evidentiary burden changes or registration sunset clauses. Supply disruption scenarios, reimbursement coding revisions, and mesh nebulizer substitution acceleration represent specific revision triggers. Recalibration cycles align with material shifts in reimbursement policy, ceramic supply availability, and hospital-at-home program adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Autosamplers Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
Wireless Breast Pump Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
Europe Breast Pumps Market
Medical Devices
Eye Socket Implants Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
Infertility Devices Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Tinnitus Maskers Market