
 MRI Pulse Oximeters Market | 2026-2036
MRI Pulse Oximeters Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Pulse Oximeters Market Foresight
ISO 13485 certification is reorganizing competitive access in the MRI pulse oximeter landscape, forcing smaller participants into costly quality management overhauls. Masimo sustains technology leadership through proprietary signal processing algorithms optimized for high-field magnetic environments. Nonin Medical specializes in portable form factors that address inter-facility patient transport workflows. Koninklijke Philips N.V. leverages its installed imaging base to bundle oximetry solutions with MRI system service contracts.
An MRI pulse oximeter is a non-invasive photoplethysmographic device engineered with non-ferromagnetic components and fiber-optic signal transmission to measure arterial oxygen saturation during magnetic resonance imaging, typically operating at wavelengths near 660 nm and 940 nm while withstanding static fields exceeding 1.5 Tesla. The product type landscape tilts toward portable and handheld configurations as ambulatory surgical centers expand their MRI sedation capabilities. Technology segmentation shows LED-based platforms dominating current installations while reflectance methods gain traction for forehead and ear canal placements that circumvent digit-access limitations during prone positioning. Application demand clusters in anesthesia monitoring and critical care where continuous SpO2 surveillance is mandatory under ASA guidelines.
FDA 510(k) pathways and the EU Medical Device Regulation impose divergent clinical evidence requirements that fragment go-to-market strategies between the United States and European markets. The country's national pharmaceutical regulator in Japan adds layer-specific electromagnetic compatibility testing that extends approval timelines for foreign manufacturers. Stakeholders must monitor evolving MRI-conditional labeling standards from IEC 60601-1-10 and anticipate how revised electromagnetic immunity thresholds will reshape component sourcing and validation budgets.
Market Dynamics
FDA 510(k) clearance timelines for MRI-conditional devices have extended qualification cycles, compressing revenue recognition windows and forcing manufacturers to front-load R&D expenditure against uncertain approval schedules.
Growth Catalysts
- Hospital-based anesthesia monitoring:Rising surgical volumes across tertiary care centers in the United States drive replacement demand for legacy pulse oximetry systems.
- EU Medical Device Regulation:MDR compliance mandates for electromagnetic compatibility testing create upgrade cycles among European healthcare providers.
- Fiber-optic signal transmission:Adoption of non-ferromagnetic photoplethysmographic platforms enables safe operation in 3 Tesla environments.
Market Restraints
- ISO 13485 certification costs:Quality management system overhauls impose six-figure compliance burdens on sub-scale manufacturers.
- Japan electromagnetic compatibility testing:Layer-specific validation protocols extend approval timelines for foreign device submissions.
- LED component supply concentration:Sourcing of 660 nm and 940 nm emitters depends on limited Asian semiconductor foundries.
Strategic Opportunities
- Ambulatory surgical centers:Portable and handheld configurations address sedation monitoring gaps in outpatient MRI suites across Germany.
- Reflectance measurement methods:Forehead and ear canal placements circumvent digit-access limitations during prone patient positioning.
- ASA guideline mandates:Continuous SpO2 surveillance requirements in anesthesia monitoring create replacement pull for non-compliant legacy devices.
Industry Challenges
- IEC 60601-1-10 validation:Revised electromagnetic immunity thresholds demand component respecification and extended validation budgets.
- Signal processing algorithm development:High-field magnetic environment optimization requires specialized firmware engineering talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Pulse Oximeters Market |
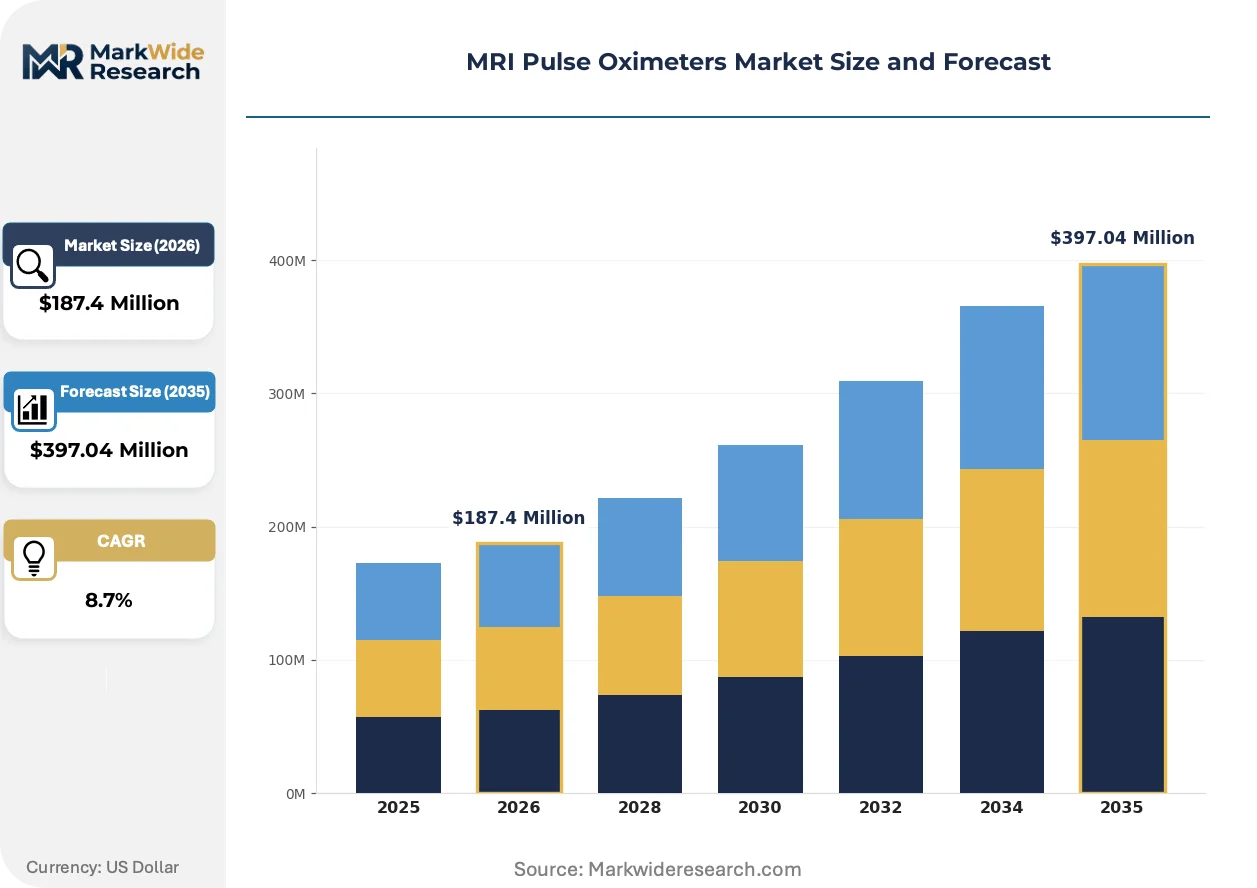
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fingertip, Wall-mounted, Portable Technology: LED, Photoelectric, Reflectance, Optical End User: Clinics, Hospitals, Home Healthcare, Emergency Services Application: Critical Care, Anesthesia Monitoring, Neonatal Care, Sports Medicine |
| Companies Covered | Koninklijke Philips N.V., IRadimed Corporation, Nihon Kohden Corporation, Masimo, Nonin Medical, EMCO Meditek Pvt. Ltd., MIPM - Mammendorfer Institut für Physik und Medizin GmbH, Medtronic, Spacelabs Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Pulse Oximeters Market Shifts & Advancements
Reflectance-based photoplethysmography is reshaping sensor placement protocols, while regulatory divergence between FDA and EU MDR pathways fragments go-to-market strategies. Device manufacturers now optimize for either 510(k) efficiency or MDR clinical evidence depth.
Reflectance pulse oximetry is displacing transmittance methods in MRI suites. Forehead and ear canal sensors eliminate digit-access constraints during prone surgical positioning. Academic medical centers in the United States adopt these platforms for neurosurgical anesthesia protocols, compressing demand for conventional fingertip designs.
EU Medical Device Regulation clinical evidence requirements diverge from FDA 510(k) substantial equivalence pathways. European notified bodies demand prospective electromagnetic interference studies that US regulators accept through predicate device referencing. German and French hospital procurement departments now require MDR certificates for new installations, bifurcating vendor qualification strategies.
After-sales service unbundling from MRI system contracts creates standalone oximetry procurement channels. Ambulatory surgical centers in Japan negotiate direct device purchases rather than bundled imaging service agreements. This purchasing autonomy concentrates in metropolitan Tokyo and Osaka healthcare clusters where independent anesthesia departments control capital budgets.
MRI Pulse Oximeters Market Segmentation
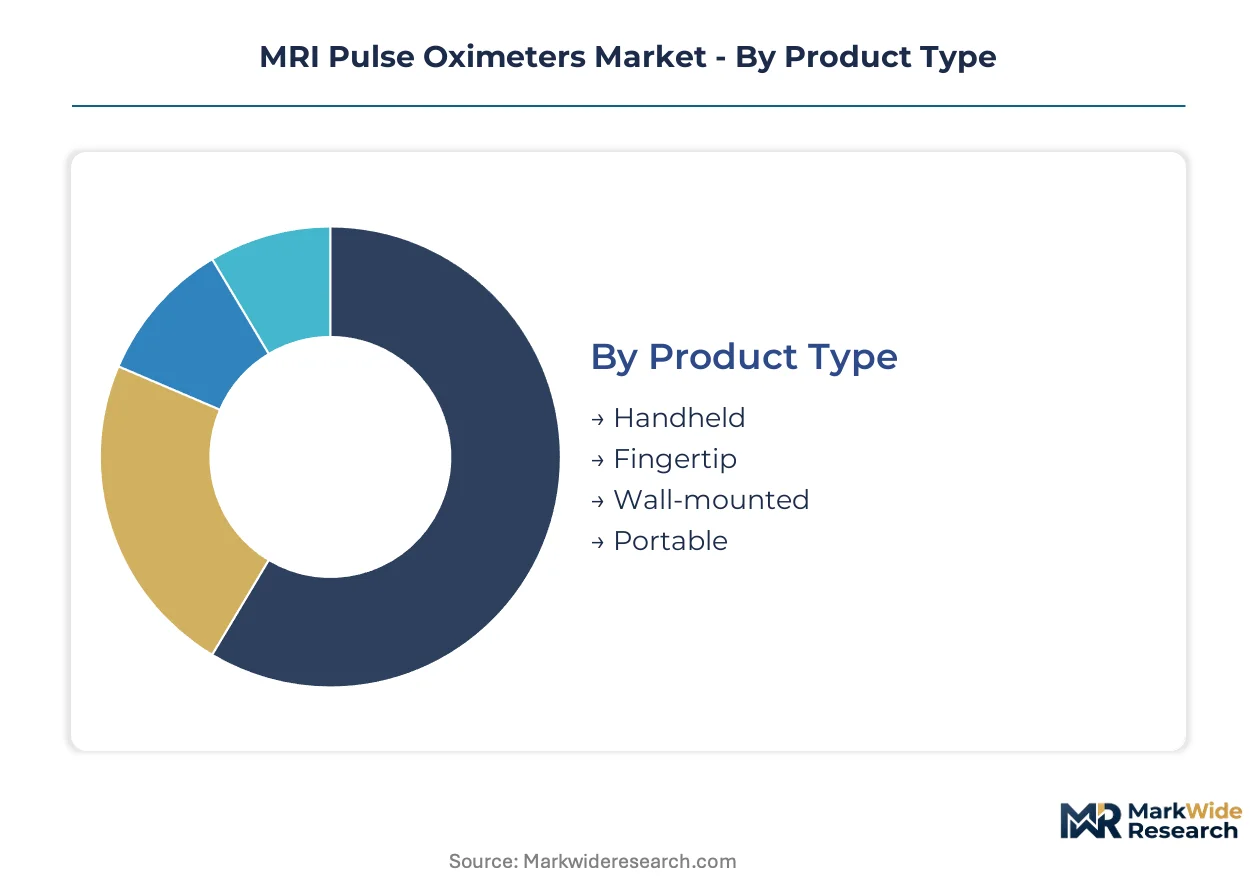
MRI pulse oximeter purchasing patterns diverge sharply between high-volume hospital systems and distributed outpatient settings. Technology selection and form factor preferences cluster around field strength requirements and patient positioning constraints.
Product Type:
Portable and handheld configurations dominate export shipments to ambulatory surgical centers, while wall-mounted systems concentrate in domestic tertiary hospital installations.
- Handheld:Battery-operated units with fiber-optic signal transmission enable inter-facility patient transport workflows. Demand concentrates in German metropolitan hospital networks where sedation monitoring extends beyond fixed MRI suites.
- Portable:Compact form factors with rechargeable power systems address outpatient MRI expansion in United States ambulatory surgical centers. These units bypass bundled imaging service contracts through direct anesthesia department procurement.
- Fingertip:Conventional digit-based sensors face positioning constraints during prone neurosurgical procedures.
- Wall-mounted:Fixed installations predominate in Japanese university hospital complexes with dedicated intraoperative MRI capabilities.
Portable configurations hold the largest share; momentum sits with handheld systems.
Technology:
LED-based platforms command premium pricing tiers due to electromagnetic compatibility certification costs, while reflectance methods penetrate cost-sensitive forehead-placement applications.
- LED:Dual-wavelength emitters at 660 nm and 940 nm provide standardized SpO2 measurement accuracy. Supply concentration in Asian semiconductor foundries creates sourcing vulnerability for manufacturers qualifying new product lines.
- Reflectance:Forehead and ear canal sensor designs eliminate digit-access limitations during prone patient positioning. Academic medical centers in the United States adopt these platforms for neurosurgical anesthesia protocols.
- Photoelectric:Transmittance-based architectures retain installed base in conventional MRI suites without surgical positioning constraints.
- Optical:Hybrid signal processing approaches combine multiple detection modalities for high-field 3 Tesla environments.
LED platforms anchor current revenue; reflectance methods are climbing the fastest.
End User:
Hospital procurement departments control capital equipment budgets, while home healthcare and emergency services segments depend on distributor-mediated channel access.
- Hospitals:Tertiary care centers in the United States drive replacement demand for legacy pulse oximetry systems as surgical volumes rise. These facilities require FDA-cleared MRI-conditional devices for anesthesia monitoring compliance.
- Clinics:Outpatient diagnostic centers in Germany seek MDR-certified portable configurations for standalone MRI sedation capabilities.
- Home Healthcare:Limited adoption due to MRI accessibility constraints; niche applications in mobile diagnostic services.
- Emergency Services:Pre-hospital applications remain minimal given MRI suite access requirements and device conditioning protocols.
Hospitals dominate absolute volume; clinics are gaining share fastest.
Application:
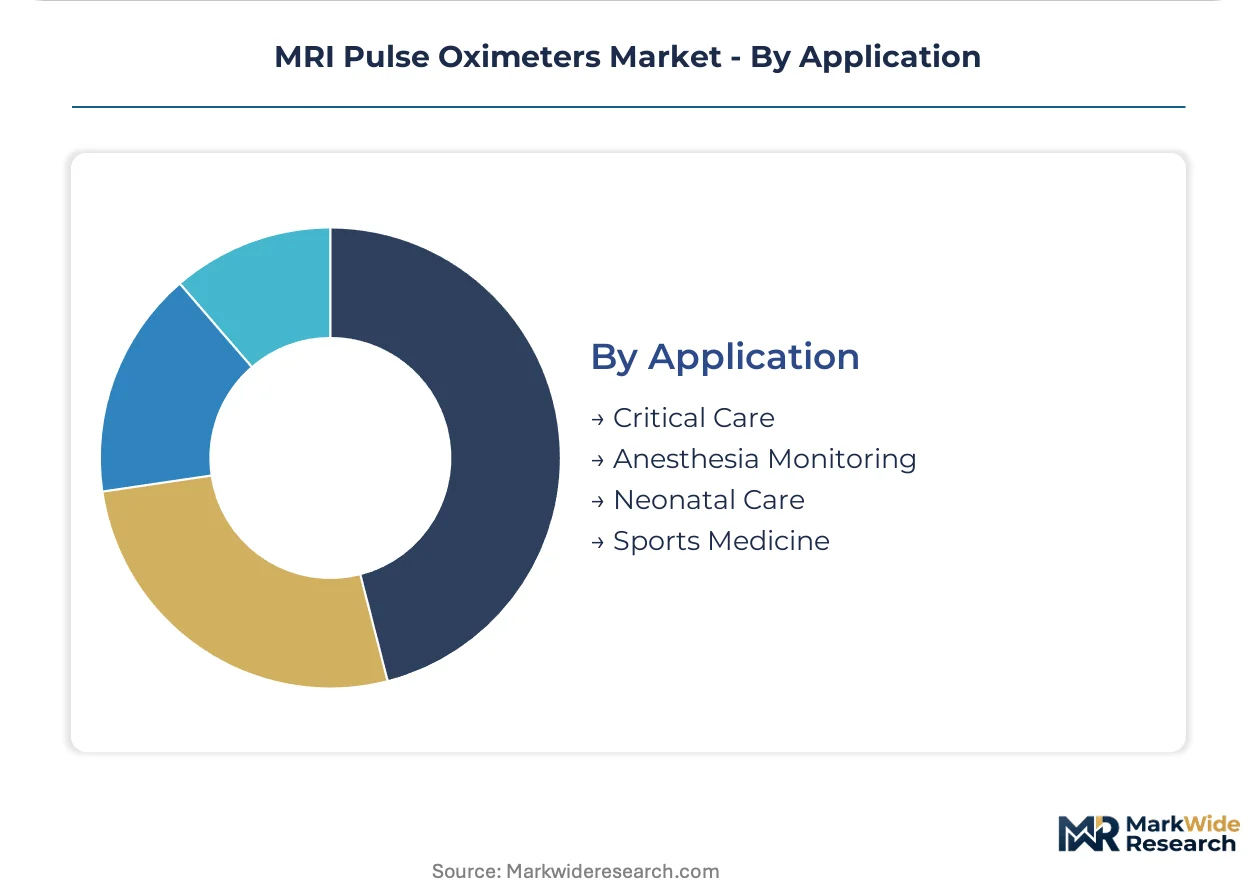
Anesthesia monitoring applications carry mandatory continuous SpO2 surveillance requirements under ASA guidelines, while sports medicine represents an emerging volume segment.
- Anesthesia Monitoring:Continuous SpO2 surveillance mandates under ASA guidelines create replacement pull for non-compliant legacy devices. This segment concentrates in United States hospital-based surgical suites with rising procedural volumes.
- Critical Care:Intraoperative and post-operative monitoring in high-field MRI environments demands specialized electromagnetic immunity validation.
- Neonatal Care:Specialized sensor sizing and signal processing for low-perfusion states; limited addressable market relative to adult applications.
- Sports Medicine:Functional MRI protocols for athletic performance assessment drive niche demand in Japanese and German research institutions.
Anesthesia monitoring commands the largest share; sports medicine shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance timelines and EU MDR compliance mandates are redistributing procurement authority across hospital systems. Reimbursement frameworks in advanced economies now predicate device qualification on electromagnetic immunity certification.
United States
Tertiary care centers in the United States drive replacement demand for legacy pulse oximetry systems as surgical volumes rise. FDA 510(k) pathways impose substantial equivalence requirements that compress revenue recognition windows for manufacturers. Academic medical centers in Boston and Baltimore adopt reflectance-based platforms for neurosurgical anesthesia protocols.
Germany
German metropolitan hospital networks seek MDR-certified portable configurations for standalone MRI sedation capabilities. EU Medical Device Regulation mandates for electromagnetic compatibility testing create upgrade cycles among healthcare providers. Procurement departments in Munich and Frankfurt now require MDR certificates for new installations.
Japan
Japan's national pharmaceutical regulator imposes layer-specific electromagnetic compatibility testing that extends approval timelines for foreign manufacturers. University hospital complexes in Tokyo and Osaka with dedicated intraoperative MRI capabilities dominate fixed installation demand. Independent anesthesia departments in metropolitan clusters now control capital budgets for direct device purchases.
United Kingdom
UK hospital trusts face MDR transition deadlines that accelerate replacement of legacy pulse oximetry systems. NHS procurement frameworks increasingly weight electromagnetic immunity certification in vendor qualification. Research institutions in London and Cambridge drive niche demand for sports medicine applications in functional MRI protocols.
India
India's CDSCO regulatory pathways for medical devices are tightening electromagnetic compatibility documentation requirements for imported MRI-conditional equipment. Private hospital chains in Mumbai and Delhi expand MRI sedation capabilities in outpatient diagnostic centers. Domestic manufacturers face ISO 13485 certification costs that reorganize competitive access for sub-scale participants.
MRI Pulse Oximeters Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and certification depth. The vendor base clusters around three tiers: multinational imaging conglomerates with bundled service contracts, mid-scale device specialists with proprietary signal processing, and regional fabricators with cost-optimized form factors. Strategic moves concentrate on M&A for regulatory clearance portfolios and backward integration into fiber-optic component sourcing.
Within the multinational tier, Koninklijke Philips N.V. and Medtronic occupy positions anchored by installed imaging base leverage. Among mid-scale specialists, Masimo exemplifies algorithm-driven differentiation for high-field magnetic environments. EMCO Meditek Pvt. Ltd. represents regional fabrication archetypes targeting cost-sensitive procurement channels in South Asian hospital networks.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| IRadimed Corporation |
| Nihon Kohden Corporation |
| Masimo |
| Nonin Medical |
| EMCO Meditek Pvt. Ltd. |
| MIPM - Mammendorfer Institut für Physik und Medizin GmbH |
| Medtronic |
| Spacelabs Healthcare |
| Others |
Supply & Pricing Matrix
Capacity utilization at Asian semiconductor foundries producing 660 nm and 940 nm LED emitters creates asymmetric pricing power among MRI pulse oximeter manufacturers, compressing margins for sub-scale participants while rewarding volume-certified incumbents with component allocation priority and cost absorption capacity.
Pricing Analysis
Certification level creates the primary spread across MRI pulse oximeter tiers, with FDA 510(k)-cleared and MDR-certified devices commanding premium positioning against uncertified alternatives. Three-tier pricing structure separates premium fiber-optic systems from standard LED-based units and economy-grade photoelectric sensors. Cost compression in the economy tier is intensifying because Asian foundry concentration limits component sourcing flexibility. Ambulatory surgical centers exhibit highest price sensitivity, while tertiary hospital systems prioritize electromagnetic immunity certification over unit cost.
Supply Chain Analysis
Strategic stockpiling of fiber-optic cables and non-ferromagnetic sensors dominates inventory strategy among manufacturers facing extended FDA qualification timelines. Component sourcing draws from Taiwan and South Korea for LED emitters, Japan for precision optical fibers, and Germany for electromagnetic shielding materials. Single-source vulnerability concentrates in 940 nm emitter supply from limited foundry capacity. Distribution runs through hospital GPO contracts in the United States, direct anesthesia department procurement in Germany, and bundled imaging service agreements in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized firmware engineering talent for high-field magnetic environment optimization represents the critical capability gap constraining competitive entry, with algorithm development timelines extending 18-24 months beyond hardware qualification cycles.
For Market Incumbents: Shield installed base relationships through backward integration into fiber-optic component sourcing, securing captive supply against Asian foundry allocation constraints. Accelerate IEC 60601-1-10 pre-validation investments ahead of revised electromagnetic immunity thresholds to compress competitor response windows. For New Entrants and Emerging Players: FDA 510(k) substantial equivalence pathways offer the fastest certification fast-track for reflectance-based platforms targeting forehead-placement applications in ambulatory surgical centers. White-space concentration sits in German outpatient MRI suites seeking MDR-certified portable configurations outside bundled imaging contracts. Direct anesthesia department procurement channels bypass incumbent GPO lock-in. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mid-scale specialists with proprietary signal processing algorithms and established hospital service contracts. Long-term viability centers on regulatory clearance portfolio depth rather than hardware differentiation alone. Acquisition targets should demonstrate FDA 510(k) or MDR certification momentum with incomplete geographic coverage. The signal to monitor is Japan PMDA approval timeline compression for foreign manufacturers, which would reset competitive access assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses revenue recognition windows against MDR clinical evidence requirements. |
| CE Marking Pathway Investment | Unlocks German and French hospital procurement requiring MDR certificates. |
| Hospital System Partnership | Bypasses bundled imaging contracts through direct anesthesia department engagement. |
| Software Companion Development | Integrates SpO2 data with MRI system workflows for tertiary care stickiness. |
| Reimbursement Strategy | Aligns device qualification with ASA guideline mandates for continuous monitoring. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and GPO contract disclosures. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, end user, and application dimensions.
Segmentation dimensions modeled include product configuration, signal transmission technology, end-user facility type, and clinical application across the analysis window. CAGRs derived from fitted growth curves incorporating surgical volume trajectories, regulatory approval pipeline visibility, and replacement cycle assumptions for legacy pulse oximetry systems. Electromagnetic compatibility certification cost inflation and LED component supply concentration anchored supply-side forecast inputs.
Underlying assumptions cover stable FDA 510(k) review timelines and intact reimbursement frameworks in the United States, Germany, and Japan, with deviation risk concentrated in EU MDR notified body capacity constraints and Asian semiconductor foundry allocation disruptions. Revision becomes warranted when IEC 60601-1-10 electromagnetic immunity thresholds cross implementation thresholds ahead of manufacturer respecification cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
Infusion Rate Monitoring Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
Neurology Patient Monitoring Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Australia Patient Monitoring Market