
 Respiratory Devices Market | 2026-2036
Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Devices Market Intelligence
Hospital-grade specification upgrades is bifurcating the competitive landscape between premium clinical systems and cost-optimized home-use platforms. ResMed Inc. dominates the sleep apnea therapy segment through integrated digital health ecosystems. Philips leverages its diagnostic imaging heritage to anchor its respiratory portfolio within acute care networks. Fisher & Paykel Healthcare Limited specializes in humidification technologies that differentiate its ventilator interfaces.
Respiratory devices encompass mechanical and electromechanical systems engineered to deliver, monitor, or augment pulmonary gas exchange, with critical specifications including flow rates, pressure ranges, and oxygen concentration precision. These systems serve therapeutic intervention, diagnostic measurement, and life-support functions across clinical and non-clinical environments. CPAP devices lead the product-type landscape due to established reimbursement pathways for sleep apnea management, while smart devices represent the fastest-growing technology segment as connectivity and remote patient monitoring capabilities reshape device architecture. Home care settings command expanding share within the end-user dimension as payors and patients prioritize cost containment and quality-of-life outcomes outside institutional walls.
The FDA's 510(k) clearance framework and the European Union's Medical Device Regulation (MDR) impose divergent evidentiary requirements that reshape product development cycles and market access timelines for manufacturers. ISO 13485 quality management standards and IEC 60601-1 electrical safety specifications form the baseline compliance architecture governing design controls and risk management across jurisdictions. Stakeholders must monitor evolving cybersecurity guidance from regulators as connected respiratory platforms proliferate and data integrity becomes inseparable from patient safety.
Market Dynamics
The migration from acute care facilities to home-based therapy is restructuring procurement patterns across the respiratory devices sector, with reimbursement codes and remote monitoring infrastructure determining competitive viability.
Growth Catalysts
- FDA 510(k) premarket notification:This clearance pathway accelerates iterative device iterations for Class II respiratory systems, compressing development timelines relative to full PMA submissions.
- Japan's aging demographic concentration:The country's super-aged population sustains institutional and home-care demand for mechanical ventilation and oxygen therapy platforms.
- Integrated digital health ecosystems:Cloud-connected CPAP and BiPAP devices enable remote adherence monitoring and automated pressure adjustments, expanding reimbursable service bundles.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate sensor and processor fabrication for flow-control modules, creating vulnerability to geopolitical disruption.
- EU MDR technical documentation requirements:The expanded clinical evidence mandates for legacy device recertification are extending renewal cycles and freezing portfolio rationalization.
- Reusable interface substitution:Silicone mask cushions and tubing assemblies face pressure from single-use alternatives in infection-sensitive acute settings.
Strategic Opportunities
- India's underpenetrated sleep apnea diagnosis rate:Less than one percent of suspected cases receive polysomnography testing, creating whitespace for home screening devices and telemedicine-integrated CPAP dispensing.
- US IRA Medicare price negotiation provisions:The inflation rebate mechanism creates procurement leverage for durable medical equipment suppliers negotiating with concentrated hospital networks.
- AI-enabled predictive maintenance:Machine learning algorithms analyzing motor vibration patterns and flow curve anomalies are converging with subscription service models to unbundle hardware from recurring revenue.
Industry Challenges
- Biomedical engineering talent scarcity:The intersection of pneumatics, embedded systems, and regulatory science requires hybrid skill sets that outpace university pipeline output.
- Legacy EHR integration complexity:Proprietary data formats from incumbent ventilator manufacturers resist standardized HL7 FHIR connectivity, forcing costly middleware development for health system customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Devices Market |
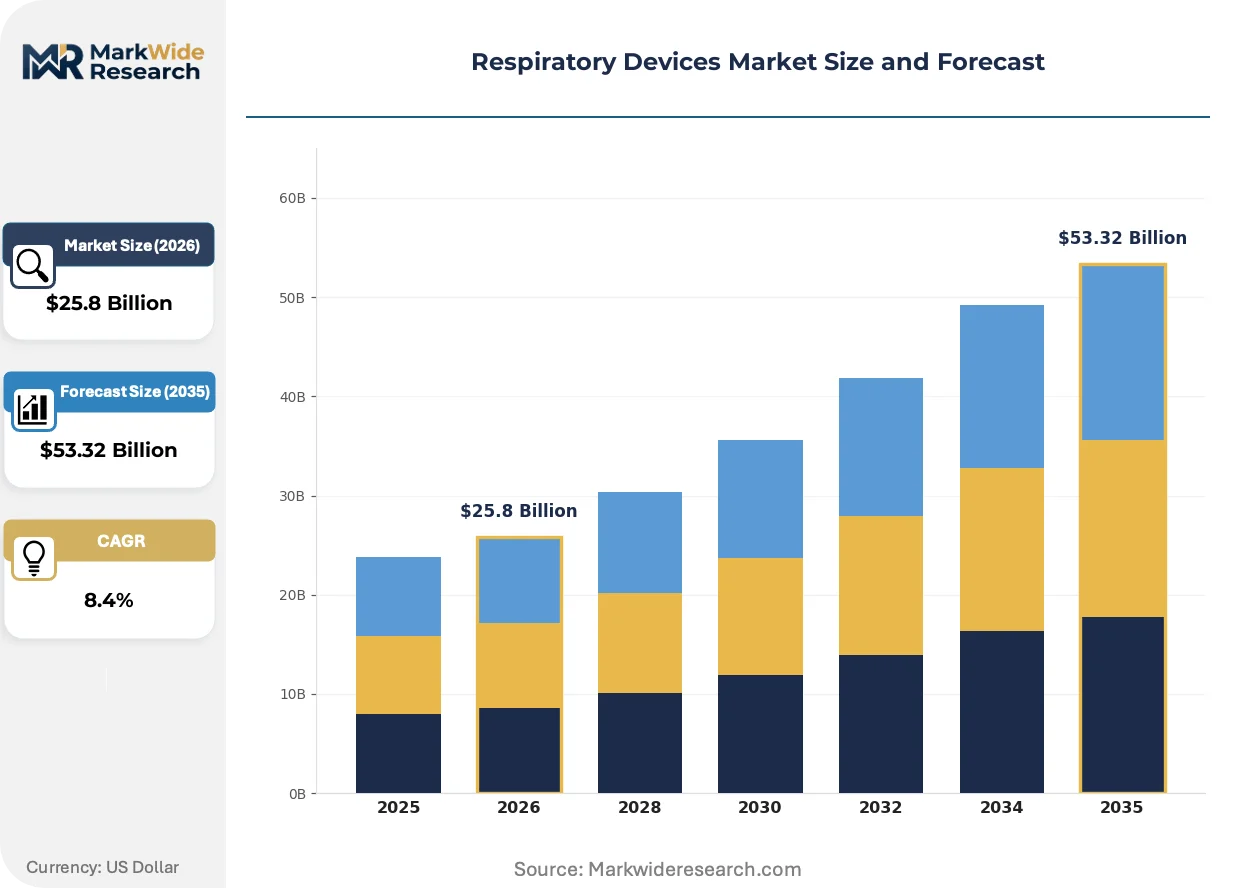
| Market Size in 2026 | $25.8 Billion |
| Market Size in 2035 | $53.32 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Concentrators, CPAP Devices End User: Hospitals, Home Care Settings, Clinics, Rehabilitation Centers Technology: Digital Devices, Mechanical Devices, Portable Devices, Smart Devices Application: Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Interstitial Lung Disease |
| Companies Covered | Koninklijke Philips N.V., ResMed Inc., GE Healthcare, Medtronic, Fisher & Paykel Healthcare Limited, Drägerwerk AG & Co. KGaA, Masimo, Getinge AG, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Devices Market Strategic Shifts & Innovations
Connectivity architectures and algorithmic therapy personalization are redefining device value propositions, shifting competitive advantage from mechanical precision to data-enabled clinical outcomes.
Micro-blower motor technology with magnetically levitated impellers is displacing traditional piston-based compression systems in portable oxygen concentrators. Home care providers across Germany and the United States are adopting these platforms for ambulatory patients requiring continuous flow. The shift is compressing device weight thresholds and extending battery-operated mobility ranges, forcing established manufacturers to reconfigure supply chains around solid-state component sourcing.
The European Union's Medical Device Regulation (MDR) Article 10 post-market surveillance requirements impose systematic implantable-equivalence tracking on high-risk respiratory devices. Manufacturers must now maintain active safety monitoring systems with direct healthcare professional feedback loops. This regulatory architecture most severely affects legacy ventilator platforms with decades-old design histories, compelling portfolio-wide technical documentation reconstruction.
Hospital procurement committees are consolidating vendor relationships through single-source contracting for entire respiratory therapy categories. Integrated delivery networks in the United States are replacing fragmented point-of-purchase decisions with multi-year enterprise agreements bundling devices, disposables, and clinical training. This concentration is most visible in the Southeast and Midwest regions where Catholic health systems and for-profit chains dominate acute care bed capacity.
Respiratory Devices Market Segmentation
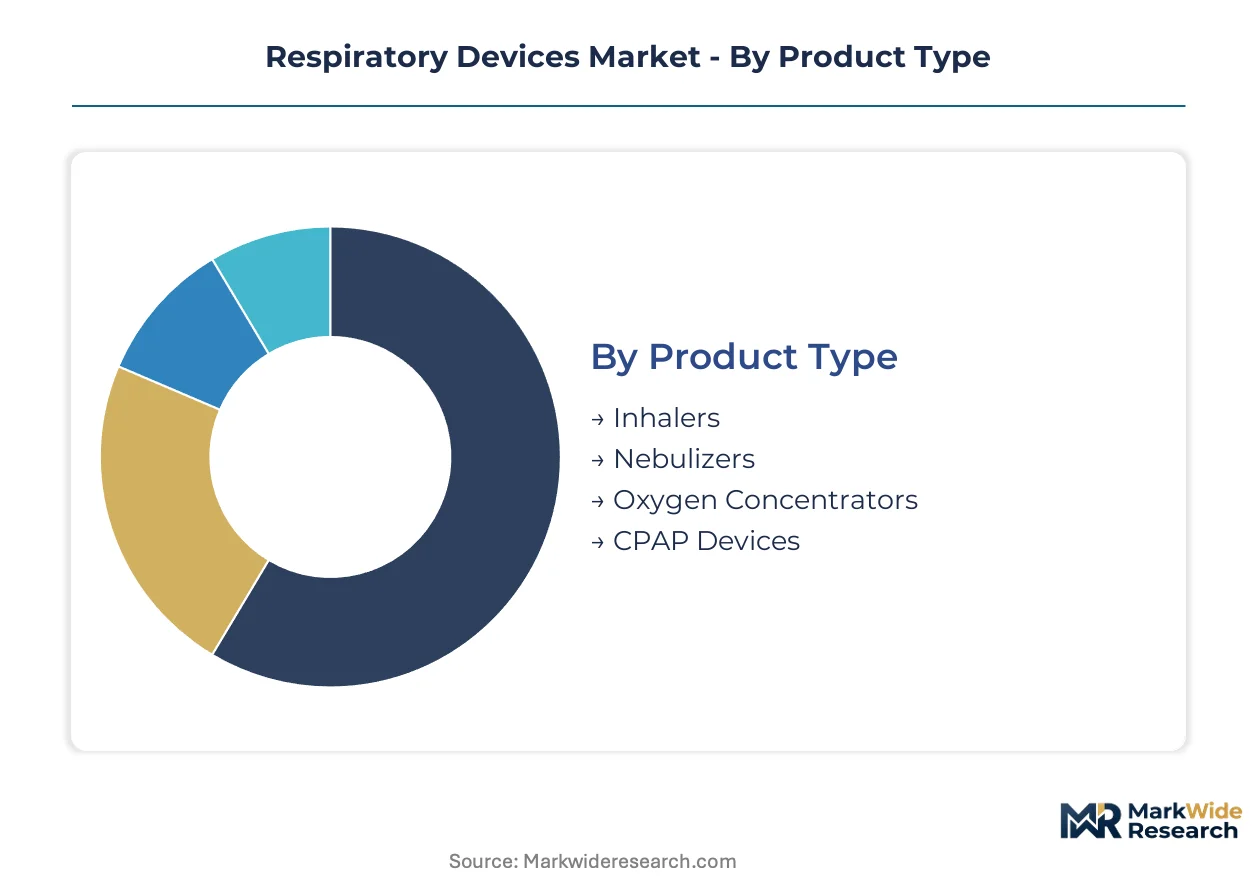
Respiratory device procurement diverges sharply across care settings and disease pathways, with reimbursement codes and clinical workflow integration determining which segments capture margin. Manufacturers must align technical specifications with specific regulatory pathways and patient adherence profiles to avoid commodity trap.
Product Type:
Substitution pressure concentrates in portable oxygen delivery where lightweight concentrators displace traditional compressed gas cylinders in ambulatory care. Reusable interface components face single-use alternatives in infection-sensitive settings.
- Inhalers:Pressurized metered-dose and dry-powder systems dominate ambulatory asthma and COPD maintenance therapy. Demand clusters in Germany and the United States where formulary placement determines patient access to combination corticosteroid-long-acting beta agonist formulations.
- Nebulizers:Jet and mesh nebulization systems convert liquid medication into respirable aerosols for patients unable to coordinate breath-actuated delivery. Pediatric and geriatric populations in Japan sustain institutional procurement despite higher per-dose cost versus inhalers.
- Oxygen Concentrators:Pressure swing adsorption units extract medical-grade oxygen from ambient air, eliminating cylinder logistics for home-bound patients.
- CPAP Devices:Continuous positive airway pressure systems with integrated humidification and data transmission capabilities anchor sleep apnea therapy protocols.
CPAP devices anchor the volume base while oxygen concentrators gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive acute care installations from distributed home care platforms with lower per-unit margins but recurring consumable revenue.
- Hospitals:Acute care networks deploy ventilator fleets with advanced invasive and non-invasive modes alongside high-flow nasal cannula systems. Integrated delivery networks in the United States negotiate enterprise contracts bundling devices, disposables, and clinical training.
- Home Care Settings:Patients transition from institutional care to domiciliary oxygen, CPAP, and ventilator support as payors prioritize cost containment. Remote monitoring infrastructure and reimbursement codes for remote patient management determine competitive viability in Germany and Japan.
- Clinics:Pulmonary function testing and diagnostic sleep studies concentrate in outpatient settings with polysomnography and spirometry equipment.
- Rehabilitation Centers:Post-acute facilities manage ventilator weaning and respiratory muscle training for prolonged mechanical ventilation survivors.
Home care settings command the steepest expansion trajectory while hospitals retain the highest absolute equipment value.
Technology:
Application maturity separates established mechanical platforms from connected architectures requiring cybersecurity compliance and software validation.
- Digital Devices:Cloud-connected platforms with cellular or Wi-Fi telemetry enable remote adherence monitoring and automated therapy adjustment. FDA cybersecurity guidance and EU MDR software lifecycle requirements extend development timelines for manufacturers.
- Mechanical Devices:Pneumatic and electromechanical systems without data connectivity serve cost-sensitive markets and backup power scenarios. These platforms dominate procurement in regions with limited broadband infrastructure.
- Portable Devices:Battery-operated oxygen concentrators and miniaturized CPAP systems support ambulatory patient mobility.
- Smart Devices:Machine learning algorithms analyzing respiratory patterns enable predictive exacerbation detection and personalized pressure titration.
Mechanical devices anchor installed base volume while smart devices expand most quickly.
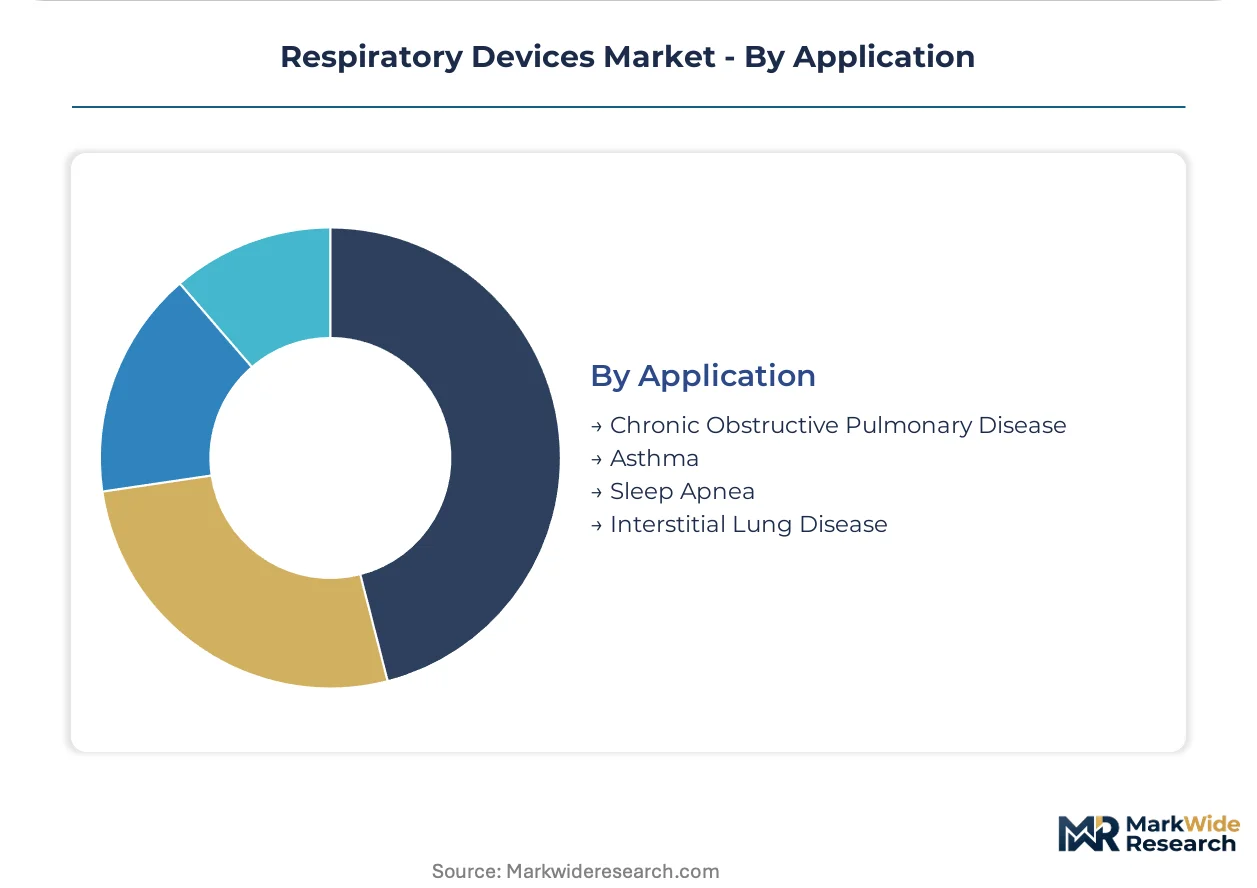
Application:
Geographic disease prevalence determines addressable market size, with diagnostic penetration rates creating divergence between suspected and confirmed patient populations.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation drives long-term oxygen therapy and non-invasive ventilation demand. Smoking prevalence and aging demographics in Japan and Germany sustain device procurement despite declining incidence in some developed markets.
- Asthma:Reversible airway obstruction management concentrates in inhaler-based maintenance and rescue therapy. Pediatric populations and allergen exposure patterns shape regional demand concentration.
- Sleep Apnea:Obstructive sleep apnea diagnosis rates lag suspected prevalence, particularly in India where less than one percent of cases receive polysomnography testing.
- Interstitial Lung Disease:Fibrotic parenchymal disorders require supplemental oxygen and eventual mechanical ventilation in advanced stages.
Sleep apnea anchors revenue concentration while interstitial lung disease shows the steepest unmet need expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision ventilator components to hospital networks across the United States and Japan, establishing a trade corridor that channels European engineering expertise into high-specification acute care procurement channels worldwide.
United States
Medicare reimbursement codes for home oxygen therapy and sleep apnea management sustain institutional procurement volumes. The FDA's 510(k) premarket notification pathway compresses development timelines for Class II respiratory systems. Minneapolis-St. Paul anchors concentrator manufacturing clusters where suppliers serve integrated delivery networks across the Midwest and Southeast.
Germany
Super-aged demographics and high COPD prevalence drive mechanical ventilation and oxygen therapy demand across clinical and domiciliary settings. The EU MDR Article 10 post-market surveillance requirements impose systematic safety monitoring obligations on high-risk device manufacturers. Baden-Württemberg hosts precision pneumatic component fabricators supplying flow-control modules to ventilator OEMs throughout Europe.
Japan
The world's highest elderly population concentration sustains institutional and home-care demand for non-invasive ventilation platforms. PMDA regulatory frameworks align with international standards while maintaining distinct quality management expectations. Osaka-Kobe industrial corridors concentrate humidification technology specialists serving domestic hospital networks and export markets.
India
Sub-one-percent polysomnography diagnosis rates create whitespace for home screening devices and telemedicine-integrated CPAP dispensing. CDSCO medical device registration requirements are converging with global harmonization initiatives. Bangalore and Hyderabad clusters host digital health startups developing cloud-connected respiratory monitoring platforms for price-sensitive emerging markets.
United Kingdom
NHS long-term plan commitments to community-based respiratory care redirect procurement toward home oxygen and ventilation services. MHRA post-Brexit regulatory autonomy maintains EU MDR equivalence while streamlining certain approval pathways. Cambridge-Oxford-London corridor concentrates connected device R&D operations targeting algorithmic therapy personalization.
Respiratory Devices Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and regulatory sophistication dimensions, producing a tiered structure where scale-driven conglomerates and focused mid-cap innovators occupy distinct competitive positions. The vendor base separates into three strategic archetypes: diversified healthcare conglomerates leveraging diagnostic imaging heritage, sleep therapy specialists building integrated digital ecosystems, and precision component specialists differentiating through humidification and interface technologies. M&A activity concentrates on digital health capability acquisition, while portfolio diversification moves target adjacent respiratory therapy categories.
Among diversified healthcare conglomerates, Koninklijke Philips N.V. and GE Healthcare exemplify the imaging-to-therapy extension archetype, anchoring acute care network relationships through enterprise procurement contracts. ResMed Inc. occupies a position within the sleep therapy specialist tier, representing the integrated digital ecosystem model that bundles hardware with remote monitoring services. Fisher & Paykel Healthcare Limited sits within the precision component specialist category, exemplifying differentiation through humidification technology expertise.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| ResMed Inc. |
| GE Healthcare |
| Medtronic |
| Fisher & Paykel Healthcare Limited |
| Drägerwerk AG & Co. KGaA |
| Masimo |
| Getinge AG |
| 3M |
| Others |
Cost & Logistics Intelligence
Ninety-day safety stock buffers for semiconductor flow sensors concentrate procurement leverage among ventilator OEMs with balance-sheet capacity to pre-position inventory, compressing margin structures for mid-tier competitors without captive supply arrangements. This inventory asymmetry feeds directly into pricing power bifurcation across the respiratory device landscape.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate hospital procurement committees and integrated delivery networks. Price differentiation separates FDA 510(k)-cleared platforms from CE-marked economy tiers, with certification grade and volume scale as primary drivers. Cost compression in home-use CPAP segments intensifies as single-use interface alternatives gain traction in infection-sensitive settings. Price sensitivity peaks among distributed home care providers negotiating reimbursement-capped oxygen therapy contracts, while acute care networks exhibit lower elasticity due to enterprise bundling requirements.
Supply Chain Analysis
Ninety-day safety stock buffers for semiconductor flow sensors reflect Taiwan and South Korea concentration in sensor and processor fabrication for pneumatic control modules. Raw material dependencies center on rare-earth magnets for micro-blower motors, medical-grade silicones for mask interfaces, and lithium-ion cells for portable concentrator power systems. Single-source vulnerability in Taiwan semiconductor fabrication creates exposure to geopolitical disruption. Distribution runs through specialized durable medical equipment distributors serving hospital networks and direct-to-patient home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The respiratory devices market exhibits cyclical recovery characteristics as post-pandemic hospital capital expenditure normalization and aging demographic tailwinds reactivate procurement pipelines. Medicare reimbursement stability and EU MDR recertification waves create predictable demand windows for prepared suppliers.
For Market Incumbents: Fortify digital health ecosystem integration to defend against software-native entrants threatening hardware commoditization. Deepen backward integration into humidification component manufacturing to capture margin currently flowing to precision pneumatic specialists. Prioritize FDA 510(k) pathway expertise as a certification moat against European and Asian competitors facing extended MDR timelines. For New Entrants and Emerging Players: Remote patient monitoring service gaps where incumbents under-serve present whitespace for subscription-based adherence platforms bundling hardware with clinical coaching. India's sub-one-percent sleep apnea diagnosis penetration offers the most penetrable geography for telemedicine-integrated CPAP dispensing models. Target GPO contract exclusion zones in Southeast US Catholic health systems through direct hospital pilot programs bypassing enterprise procurement committees. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates rationalizing respiratory portfolios under portfolio optimization mandates. Long-term viability over a multi-year horizon hinges on software-enabled recurring revenue attachment rates rather than device shipment volumes. Watch FDA 510(k) clearance velocity for connected platforms as an inflection indicator separating sustainable competitive positions from stranded legacy hardware investments.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Health Platform Integration | Cloud-connected CPAP ecosystems with automated pressure adjustment expand reimbursable service bundles beyond hardware margins. |
| FDA 510(k) Submission Acceleration | Premarket notification expertise compresses development timelines relative to full PMA pathways for Class II respiratory systems. |
| Hospital System Partnership | Enterprise agreements with integrated delivery networks in the US Midwest and Southeast consolidate fragmented procurement decisions. |
| Software Companion Development | AI-enabled predictive maintenance algorithms analyzing motor vibration patterns unbundle hardware from recurring subscription revenue. |
| Reimbursement Strategy | Medicare remote patient management codes determine competitive viability in German and Japanese home care expansion. |
Research Approach
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and home care equipment distributors and refined through secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS Medicare reimbursement code updates, and hospital procurement transaction records. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure flows across the analysis window.
Variance decomposition across product type, end-user setting, technology architecture, and application disease pathway segments structured the analytical framework. CAGRs were derived from segment-level growth trajectory synthesis rather than single-point extrapolation. Forecast inputs incorporated semiconductor lead-time volatility, EU MDR recertification backlog projections, and Medicare reimbursement rate stability assumptions.
Forecasts assume regulatory continuity in FDA 510(k) clearance frameworks and EU MDR post-market surveillance regimes; material policy shifts would require re-modeling. Semiconductor supply concentration and geopolitical disruption represent specific risk factors that could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Silastic Implant Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Liposuction Devices Market
Medical Devices
US Nebulizer Market
Medical Devices
Slip Disc Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Medical Oxygen Concentrators Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Global Abutment Implants Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Microdebrider Market
Medical Devices
IV Equipment Market