
 Global Foot Orthotic Insoles Market | 2026-2036
Global Foot Orthotic Insoles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Foot Orthotic Insoles Market Foresight
The EU Medical Device Regulation is restructuring demand for foot orthotic insoles by mandating biocompatibility documentation and post-market surveillance for devices with sustained skin contact. Bauerfeind AG leverages its German manufacturing base to sustain CE-marked production lines that satisfy these tightened protocols. Ottobock SE & Co. KGaA anchors its competitive position through specialized rehabilitation channels across European orthopedic clinics. Superfeet Worldwide Inc. competes in North American sports retail by dominating carbon-fiber performance insole segments with podiatrist-certified designs.
Foot orthotic insoles are biomechanical devices engineered from layered composites of EVA foam, thermoplastic polymers, or carbon fiber to redistribute plantar pressure, correct gait abnormalities, and absorb shock during ambulation or athletic activity. Manufacturing employs CAD-CAM milling, vacuum forming, or direct 3D printing from foot scan data to achieve patient-specific arch geometries and heel cup depths. Custom-made insoles command the highest margin pools due to clinical prescription requirements and specialized fitting protocols, while soft insoles lead volume through over-the-counter pharmacy and e-commerce channels. Semi-rigid insoles represent the fastest-growing structural category as athletic users and aging populations seek intermediate support between accommodative cushioning and rigid correction.
The FDA classifies prescription orthotic insoles as Class I or II medical devices depending on material claims and intended therapeutic use, shaping market access through 510(k) clearance pathways and quality system regulations. Japan's PMDA and Germany's BfArM enforce parallel material safety and labeling standards that influence formulation choices by multinational manufacturers. ISO 13485 certification has become a baseline qualifier for supplier relationships with hospital purchasing consortia and podiatry networks. Stakeholders must monitor evolving reimbursement codes for preventive diabetic foot care, as coverage expansion decisions by CMS and comparable agencies will directly shift volume between custom prescription and retail self-pay segments.
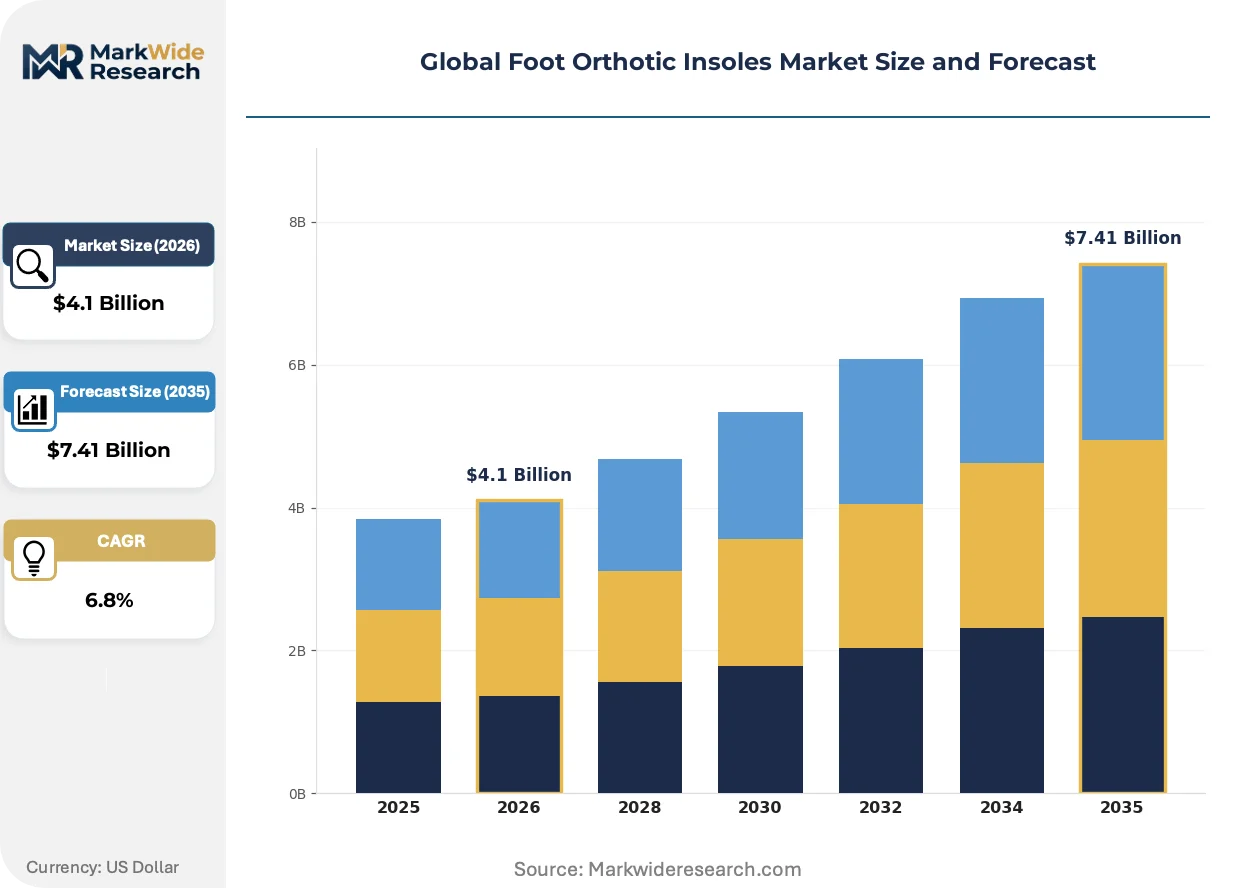
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing market access timelines by mandating clinical evidence and post-market surveillance for prolonged skin-contact devices, forcing manufacturers to restructure quality systems and supplier documentation.
Growth Catalysts
- Diabetic foot care reimbursement expansion:CMS in the United States and Germany's statutory health insurers are broadening coverage for prescription-grade orthotics, pulling volume from retail self-pay into clinical channels.
- 3D printing adoption:Direct manufacturing from foot scan data is collapsing lead times for custom arch geometries, enabling podiatry networks to scale patient throughput without proportional labor expansion.
- Japan's geriatric podiatry integration:Municipal health systems in Tokyo and Osaka prefectures are embedding orthotic management into routine elderly care protocols, creating institutional demand anchors.
Market Restraints
- Carbon fiber supply concentration:Aerospace and automotive offtake dominates high-modulus fiber allocation, constraining availability for performance insole manufacturers at contracted volumes.
- EVA foam price volatility:Ethylene-vinyl acetate feedstock tracks ethylene cracker margins and naphtha differentials, compressing margin predictability for mass-market soft insole producers.
- Biocompatibility testing burden:ISO 10993 cytotoxicity and sensitization studies for novel thermoplastic formulations extend development cycles by 8-14 months before CE marking eligibility.
Strategic Opportunities
- Sports retail channel digitization:AI-driven foot scanning kiosks in running specialty stores are bridging the fitting-gap between over-the-counter convenience and custom prescription accuracy.
- Preventive care mandate alignment:Australia's Medicare Benefits Schedule and comparable programs are piloting orthotic coverage for pre-diabetic populations, expanding addressable incidence pools.
- Multi-material 3D printing convergence:Simultaneous deposition of rigid nylon lattice structures with TPU cushioning layers is enabling single-process manufacture of semi-rigid insoles previously requiring assembly.
Industry Challenges
- CAD-CAM technician scarcity:Podiatric orthotic fabrication requires cross-trained operators competent in biomechanical assessment software and CNC milling operation, with training pipelines lagging demand.
- Legacy ERP integration friction:Custom insole workflows involving foot scan data, prescription validation, and insurance pre-authorization resist standardization into existing orthopedic device manufacturing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Foot Orthotic Insoles Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Insoles, Semi-Rigid Insoles, Soft Insoles, Custom-Made Insoles Material: EVA Foam, Gel, Cork, Polyurethane, Silicone Application: Sports Performance, Posture Correction, Diabetes Care, Aging Support End User: Orthopedic Clinics, Podiatry Centers, Sports Rehabilitation, Elderly Care Facilities |
| Companies Covered | Superfeet Worldwide Inc., Hanger Inc., Bauerfeind AG, Ottobock SE & Co. KGaA, Dr. Scholl's (Reckitt Benckiser Group PLC), Aetrex Worldwide Inc., Implus LLC, Algeo Limited, Foot Science International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Foot Orthotic Insoles Market Shifts & Advancements
Digital manufacturing workflows and regulatory documentation automation are compressing the gap between clinical assessment and device delivery, while material science advances enable function-graded structures previously unattainable through foam lamination.
Pressure-mapping sensor arrays embedded within diagnostic insoles are integrating real-time gait analysis into fitting protocols. Sports medicine clinics and rehabilitation centers are adopting these systems to quantify biomechanical improvement trajectories. The technology is integrating objective outcome measurement into reimbursement justification, expanding payer acceptance of preventive orthotic interventions.
Europe's MDR Article 10 technical documentation requirements are mandating biological safety assessment reports for all devices exceeding 30 days skin contact. Manufacturers must now maintain post-market surveillance systems with periodic safety update reports. German notified bodies are experiencing backlog extending conformity assessment timelines, compressing competitive advantage for firms with established quality management infrastructure.
Self-directed purchasing through direct-to-consumer platforms is fragmenting traditional pharmacy and podiatry channel control. Athletic consumers increasingly initiate orthotic use based on app-based foot morphology assessments before clinical consultation. This pattern is most visible in North American urban markets where running culture penetration and digital health literacy overlap.
Global Foot Orthotic Insoles Market Segmentation
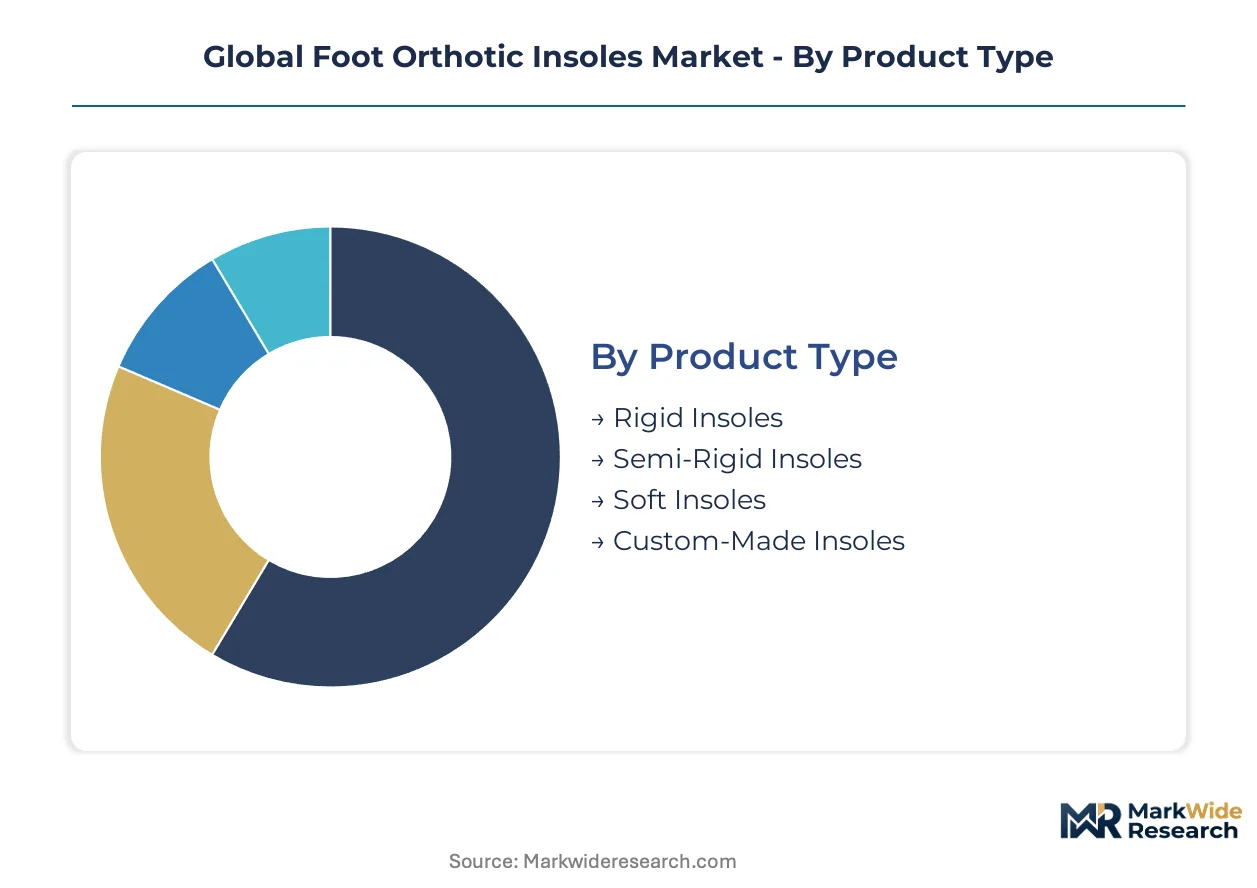
Foot orthotic insoles demand fragments across structural rigidity, material composition, clinical application, and institutional channel. Each axis carries distinct margin profiles, regulatory pathways, and procurement dynamics that shape manufacturer positioning.
Product Type:
Structural rigidity determines manufacturing complexity, prescription requirements, and reimbursement eligibility across patient populations.
- Rigid Insoles:Fabricated from carbon fiber or thermoplastic composites with minimal flexural yield. German orthopedic clinics prescribe these for severe pronation correction where biomechanical control overrides cushioning comfort.
- Semi-Rigid Insoles:Hybrid constructions layer EVA foam over polypropylene shells to balance support with shock absorption. Tokyo's municipal geriatric care programs are expanding procurement of these intermediate structures for fall-prevention protocols in aging populations.
- Soft Insoles:Gel and foam laminates dominate pharmacy retail and e-commerce self-pay channels with minimal fitting friction.
- Custom-Made Insoles:CAD-CAM or 3D-printed from patient-specific scans command premium pricing through podiatry networks with prescription validation workflows.
Soft insoles lead on scale; semi-rigid insoles lead on momentum.
Material:
Feedstock selection governs biocompatibility certification burden, supply security, and end-use performance specifications.
- EVA Foam:Ethylene-vinyl acetate copolymers provide compressible cushioning at mass-market cost structures. Japanese manufacturers face margin compression when naphtha cracker margins spike, forcing formulation adjustments toward recycled content blends.
- Gel:Viscoelastic silicone or thermoplastic elastomer inserts deliver targeted pressure relief for diabetic foot ulcer prevention. CMS reimbursement expansion in the United States is pulling gel insole volume into clinical channels previously dominated by foam.
- Cork:Natural fiber composites offer moisture management and biodegradability for sustainability-positioned European brands.
- Polyurethane:Open-cell structures provide durable cushioning with slower compression set than EVA alternatives.
- Silicone:Medical-grade formulations satisfy ISO 10993 requirements for prolonged skin contact under EU MDR protocols.
EVA foam dominates volume throughput; gel formulations are climbing the fastest on diabetic care reimbursement tailwinds.
Application:
Clinical indication determines regulatory classification, channel access, and payer coverage determination.
- Sports Performance:Carbon fiber and thermoplastic designs optimize energy return and torsional rigidity for athletic gait cycles. Australian running specialty retailers are deploying AI foot-scanning kiosks to bridge fitting precision gaps between retail convenience and prescription accuracy.
- Posture Correction:Biomechanical devices address kinetic chain alignment from plantar surface through spinal column. German statutory health insurers require podiatrist certification for reimbursement eligibility, concentrating demand through clinical networks.
- Diabetes Care:Pressure-redistributing insoles prevent neuropathic ulcer formation in high-risk populations. Germany and the United States are expanding preventive coverage mandates, shifting volume from self-pay retail toward prescription channels.
- Aging Support:Fall-prevention and mobility maintenance applications align with Japan's integrated geriatric podiatry protocols in Osaka and Tokyo prefectures.
Diabetes care commands the steepest expansion trajectory; sports performance retains the broadest addressable consumer base.
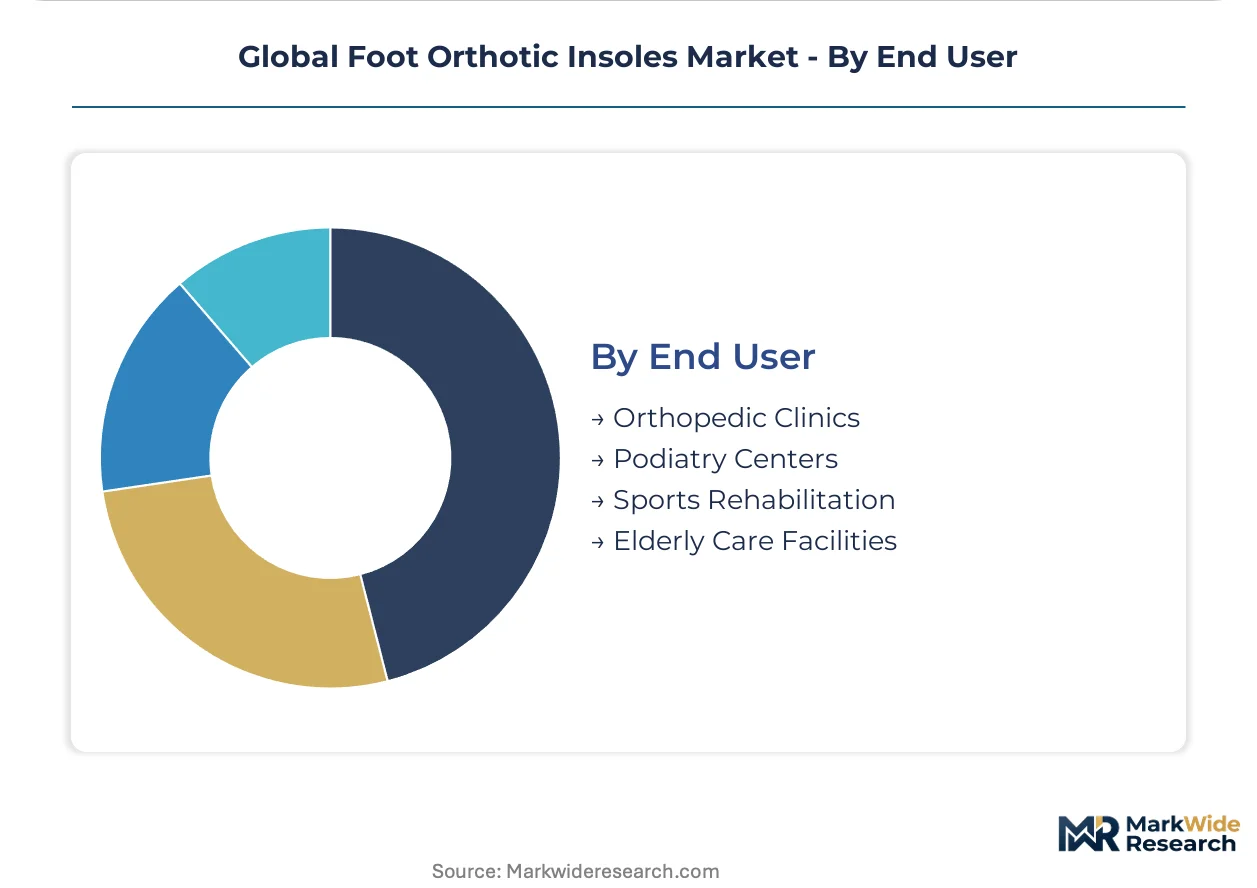
End User:
Institutional channel structure dictates procurement scale, technical specification requirements, and relationship durability.
- Orthopedic Clinics:Hospital-affiliated practices in Germany and the United States drive prescription-grade volume with insurance pre-authorization workflows. ISO 13485 certification has become a baseline qualifier for supplier relationships with purchasing consortia.
- Podiatry Centers:Independent specialist practices concentrate custom fabrication demand through foot-scanning and CAD-CAM integration.
- Sports Rehabilitation:Physical therapy networks in North America are adopting pressure-mapping diagnostic insoles to quantify biomechanical outcomes for payer justification.
- Elderly Care Facilities:Institutional procurement in Japan's municipal health systems embeds orthotic management into routine preventive care protocols.
Orthopedic clinics anchor procurement scale; elderly care facilities are gaining share fastest on aging population program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German orthopedic engineering established the clinical foundation for prescription-grade foot orthotics during the mid-twentieth century. The industry's geographic footprint now extends across manufacturing clusters in Central Europe, North American rehabilitation networks, and East Asian geriatric care systems.
United States
CMS reimbursement expansion for diabetic foot care is pulling prescription-grade orthotic volume from retail self-pay into clinical channels. The FDA's 510(k) clearance pathways for Class I and II medical devices shape manufacturer quality system investments. Boston's podiatry networks and Atlanta's rehabilitation centers anchor demand concentration for custom CAD-CAM fabrication.
Germany
Statutory health insurers mandate podiatrist certification for posture-correction orthotic reimbursement, concentrating demand through clinical networks. The EU MDR's biocompatibility documentation requirements for prolonged skin-contact devices compress market access timelines. Bavaria's orthopedic manufacturing corridor and North Rhine-Westphalia's rehabilitation infrastructure sustain CE-marked production scale.
Japan
Municipal health systems in Tokyo and Osaka prefectures embed orthotic management into routine geriatric care protocols, creating institutional demand anchors. The PMDA enforces parallel material safety standards that influence thermoplastic formulation choices by multinational manufacturers. Nagoya's medical device clusters supply prefabricated components to podiatry networks nationwide.
Australia
Medicare Benefits Schedule pilots for pre-diabetic orthotic coverage are expanding addressable incidence pools beyond established diabetes populations. The TGA's medical device framework aligns with ISO 13485 certification requirements for hospital purchasing consortia. Sydney and Melbourne running specialty retailers deploy AI foot-scanning kiosks to bridge fitting precision gaps.
China
NMPA regulatory pathways for imported medical devices create tiered market access for domestic versus multinational manufacturers. The country's dual carbon goals accelerate cork and bio-based material adoption in sustainability-positioned product lines. Yangtze River Delta manufacturing hubs produce EVA foam laminates for export-oriented soft insole brands.
Global Foot Orthotic Insoles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across prescription validation workflows and biocompatibility certification depth. The market structures around three tiers: multinational orthopedic device conglomerates with hospital purchasing consortia relationships, specialized podiatry fabricators with CAD-CAM integration, and mass-market consumer brands with pharmacy and e-commerce distribution. Strategic moves concentrate on M&A to acquire foot-scanning technology assets and capacity expansion in ISO 13485-certified production facilities.
Within the multinational conglomerate tier, Bauerfeind AG and Ottobock SE & Co. KGaA exemplify European orthopedic heritage with CE-marked production infrastructure. Superfeet Worldwide Inc. occupies a position in North American sports retail channels. These three anchors represent distinct competitive archetypes: clinical prescription workflow integration, rehabilitation network penetration, and athletic performance specialization.
| Leading Market Players |
|---|
| Superfeet Worldwide Inc. |
| Hanger Inc. |
| Bauerfeind AG |
| Ottobock SE & Co. KGaA |
| Dr. Scholl's (Reckitt Benckiser Group PLC) |
| Aetrex Worldwide Inc. |
| Implus LLC |
| Algeo Limited |
| Foot Science International |
| Others |
Supply & Pricing Matrix
Hospital purchasing consortia in Germany and the United States anchor procurement volume for prescription-grade orthotics, enforcing contract-based pricing with ISO 13485 certification as a non-negotiable qualifier. This buyer concentration compresses margin pools for uncertified manufacturers while rewarding established players with multi-year offtake agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, with custom CAD-CAM fabrication commanding premium positioning against mass-market foam laminates. Certification grade and volume scale differentiate price bands, with CE-marked and FDA-cleared products sustaining 40-60% premiums over uncertified alternatives. Cost compression in the soft insole tier is intensifying because of EVA feedstock volatility and Asian import competition. Retail self-pay consumers exhibit highest price sensitivity, while orthopedic clinics with insurance pre-authorization workflows absorb premium pricing for validated clinical outcomes.
Supply Chain Analysis
ISO 13485 certification gates supplier relationships with hospital purchasing consortia and podiatry networks, filtering out uncertified manufacturers from institutional channels. Manufacturing concentrates in Germany, China, and the United States, with Bavaria's orthopedic corridor and Yangtze River Delta EVA foam clusters anchoring upstream capacity. Supply chains draw from carbon fiber, ethylene-vinyl acetate copolymers, and medical-grade thermoplastics as critical inputs. Single-source vulnerability in high-modulus carbon fiber allocation—dominated by aerospace and automotive offtake—constrains performance insole production at contracted volumes. Distribution runs through orthopedic clinics, pharmacy retail, and direct-to-consumer platforms with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foot orthotic insoles market represents a late-cycle quality story as reimbursement expansion for diabetic foot care shifts demand toward prescription-grade specifications with validated biocompatibility documentation.
For Market Incumbents: Deploy M&A-led technology acquisition to capture foot-scanning software assets and 3D printing workflows before CAD-CAM technician scarcity worsens. Consolidate position by expanding ISO 13485-certified production capacity in Central Europe to exploit EU MDR assessment backlogs. The regulatory documentation burden emerging from Article 10 technical requirements threatens smaller competitors with 8-14 month development cycle extensions. For New Entrants and Emerging Players: AI-enabled retail fitting kiosks represent the most penetrable entry vector, bridging the precision gap between over-the-counter convenience and prescription accuracy. Sports rehabilitation networks in Australia and North American running specialty channels offer white-space expansion with lower certification barriers than hospital purchasing consortia. A direct-to-consumer platform paired with app-based foot morphology assessment enables bypass of traditional pharmacy and podiatry gatekeepers. For Investors and Strategic Acquirers: Orthopedic device conglomerates with hospital purchasing consortia relationships are the most active acquirer in this space, targeting CAD-CAM-integrated podiatry fabricators to fill technology gaps. The five-to-ten-year viability window favors assets with established CE marking and FDA 510(k) clearance infrastructure. Watch for CMS reimbursement code expansion for preventive diabetic foot care as the inflection signal shifting volume from retail self-pay toward clinical prescription channels.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance unlocks hospital procurement in Germany and statutory health insurer contracts. |
| Hospital System Partnership | ISO 13485-certified suppliers secure multi-year offtake agreements with orthopedic clinic purchasing consortia. |
| Software Companion Development | Pressure-mapping diagnostic insoles integrate real-time gait analysis into reimbursement justification workflows. |
| Reimbursement Strategy | CMS coverage expansion for diabetic foot care shifts volume from retail self-pay into prescription channels. |
| Backward Integration | In-house production of medical-grade thermoplastic formulations reduces ISO 10993 testing cycle exposure. |
Research Methodology
Direct dialogue with podiatrists, orthopedic clinic procurement managers, biomedical engineers, and GPO contracts managers grounded the qualitative foundation of this study. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement consortium contract records. Bottom-up patient volume modeling and top-down macroeconomic triangulation converged on segment-level estimates.
Bottom-up volume builds started with diabetic population incidence, sports participation rates, and geriatric podiatry protocol adoption across the projection horizon. Segmentation dimensions spanned structural rigidity, material composition, clinical application, and institutional channel. CAGRs were derived from fitted growth curves calibrated against reimbursement policy trajectories and 3D printing adoption curves. Feedstock price indices for ethylene-vinyl acetate and carbon fiber spot markets informed cost-side assumptions.
Inputs from CMS, Germany's statutory health insurers, and Japan's municipal health systems were available through the study window; gaps in real-time EU MDR conformity assessment timelines introduce uncertainty bands around market access forecasts. A model refresh is warranted upon material change in diabetic foot care reimbursement determinations by major payers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Trial Prostheses Market
Medical Devices
Medical Tricorder Market
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
Cryoablation System Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Microscope Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Global Biopsy Punch Market