
 Digital Blood Pressure Monitors Market | 2026-2036
Digital Blood Pressure Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Blood Pressure Monitors Market Intelligence
The replacement of discrete electronic components with integrated System-on-Chip (SoC) solutions is restructuring the product economics for digital blood pressure monitors. This integration enables more compact designs and advanced features like wireless connectivity. Omron Healthcare leverages its manufacturing scale to lead in the home care segment. In contrast, Welch Allyn specializes in devices for clinical settings, focusing on durability and integration with hospital EMR systems, while Koninklijke Philips competes by offering connected health ecosystems that incorporate blood pressure data.
Digital blood pressure monitors are automated electronic devices that measure arterial blood pressure using an inflatable cuff. These instruments typically employ the oscillometric method, detecting blood flow oscillations as the cuff deflates to calculate systolic and diastolic pressures. Upper arm monitors constitute the largest product segment due to their perceived higher accuracy, a critical factor for both clinical settings and home care applications. The home care application segment itself is a primary growth engine, supported by patient demand for self-monitoring tools.
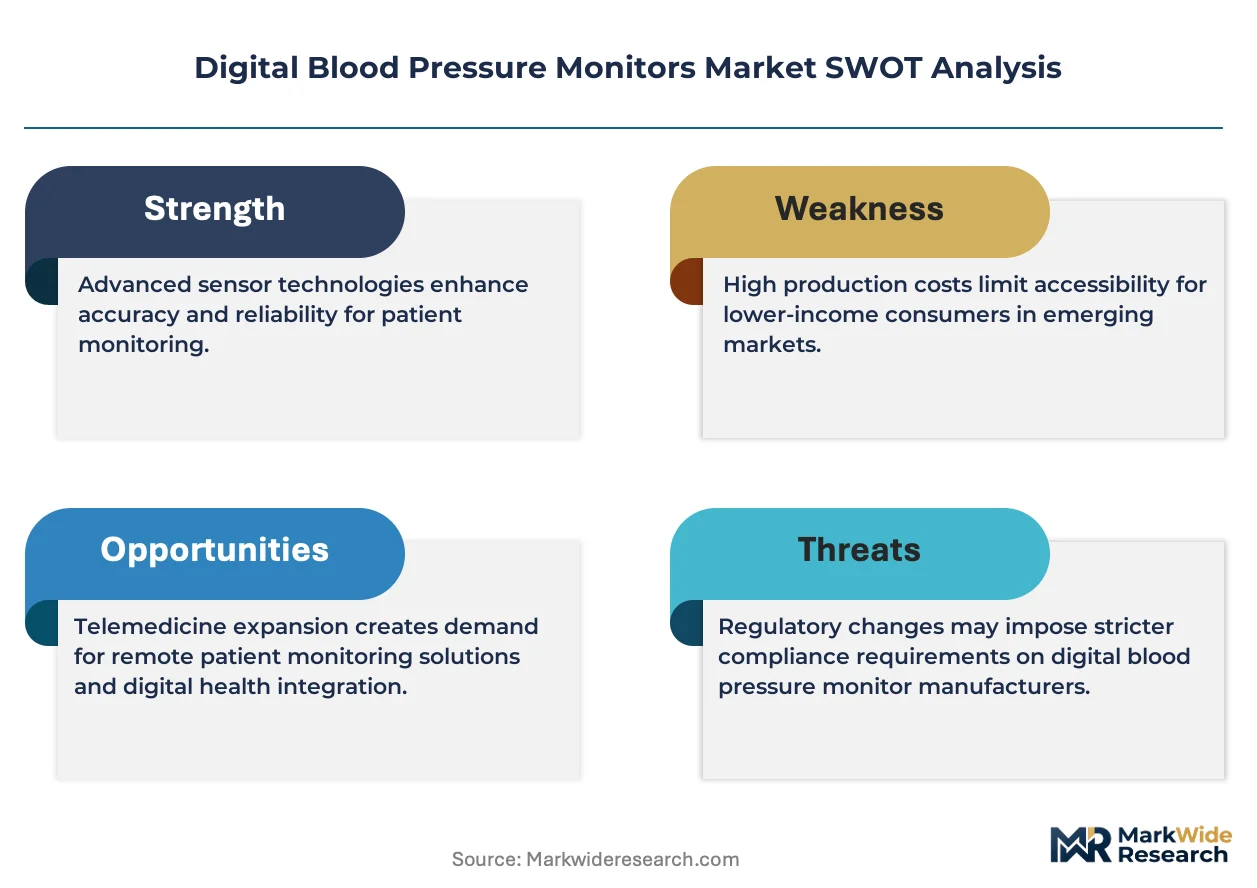
Market access is governed by stringent regulatory approvals for medical device accuracy and safety. Manufacturers must secure clearance from bodies like the U.S. FDA, adhere to Europe's Medical Device Regulation (MDR) for CE marking, and meet NMPA standards in China. Success for device makers depends on navigating these varied international validation protocols while innovating in software and data connectivity features.
Market Dynamics
The central force shaping the market is the product's evolution from a standalone measurement device into a connected data node for chronic disease management. This shift is driven by the integration of System-on-Chip (SoC) solutions that enable seamless Bluetooth connectivity with regulated mobile health applications.
Growth Catalysts
- Remote Patient Monitoring Initiatives:Government and private payer support for remote patient monitoring programs, particularly in the United States, creates direct reimbursement pathways for the use of connected blood pressure monitors in home care settings.
- Mobile Health Integration:The proliferation of smartphones and FDA-approved health applications provides a ready infrastructure for patients to track, manage, and share their blood pressure data with healthcare providers, supporting self-management.
- Chronic Disease Prevalence:A rising global incidence of hypertension and related cardiovascular diseases necessitates continuous monitoring, driving patient demand for accessible and accurate self-monitoring tools for use at home.
Market Restraints
- Regulatory Fragmentation:Manufacturers face significant hurdles navigating disparate and stringent regulatory requirements, such as the FDA's clearance process, Europe's Medical Device Regulation (MDR), and China's NMPA standards, increasing time-to-market.
- Accuracy Perceptions:Lingering user and clinician skepticism regarding the accuracy of non-traditional form factors, like wrist-based monitors, compared to upper arm cuffs can limit adoption in specific clinical and high-risk patient applications.
- Component Dependency:A heavy reliance on a concentrated supplier base for critical System-on-Chip (SoC) solutions exposes device manufacturers to supply chain volatility and potential price fluctuations for essential integrated circuits.
Strategic Opportunities
- Connected Health Ecosystems:There is a significant opportunity to develop devices that integrate seamlessly into broader digital health platforms, aggregating blood pressure data with other vital signs to provide a holistic view of patient health.
- Software and Analytics Services:Moving beyond hardware, companies can create value through subscription-based software services that offer advanced data analysis, trend identification, and personalized health insights for both patients and clinicians.
- Underserved Clinical Niches:Development of specialized monitors for specific medical scenarios, such as 24-hour ambulatory blood pressure monitoring (ABPM) or devices ruggedized for emergency medical services, presents a path for differentiation.
Industry Challenges
- EMR Integration Complexity:Ensuring secure and standardized interoperability between new digital monitors and the wide variety of legacy Electronic Medical Record (EMR) systems used in hospitals and clinics remains a persistent technical challenge.
- Data Security and Privacy:As devices become more connected, manufacturers face the growing challenge of safeguarding sensitive patient health information against cybersecurity threats and ensuring compliance with data privacy laws like HIPAA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Blood Pressure Monitors Market |
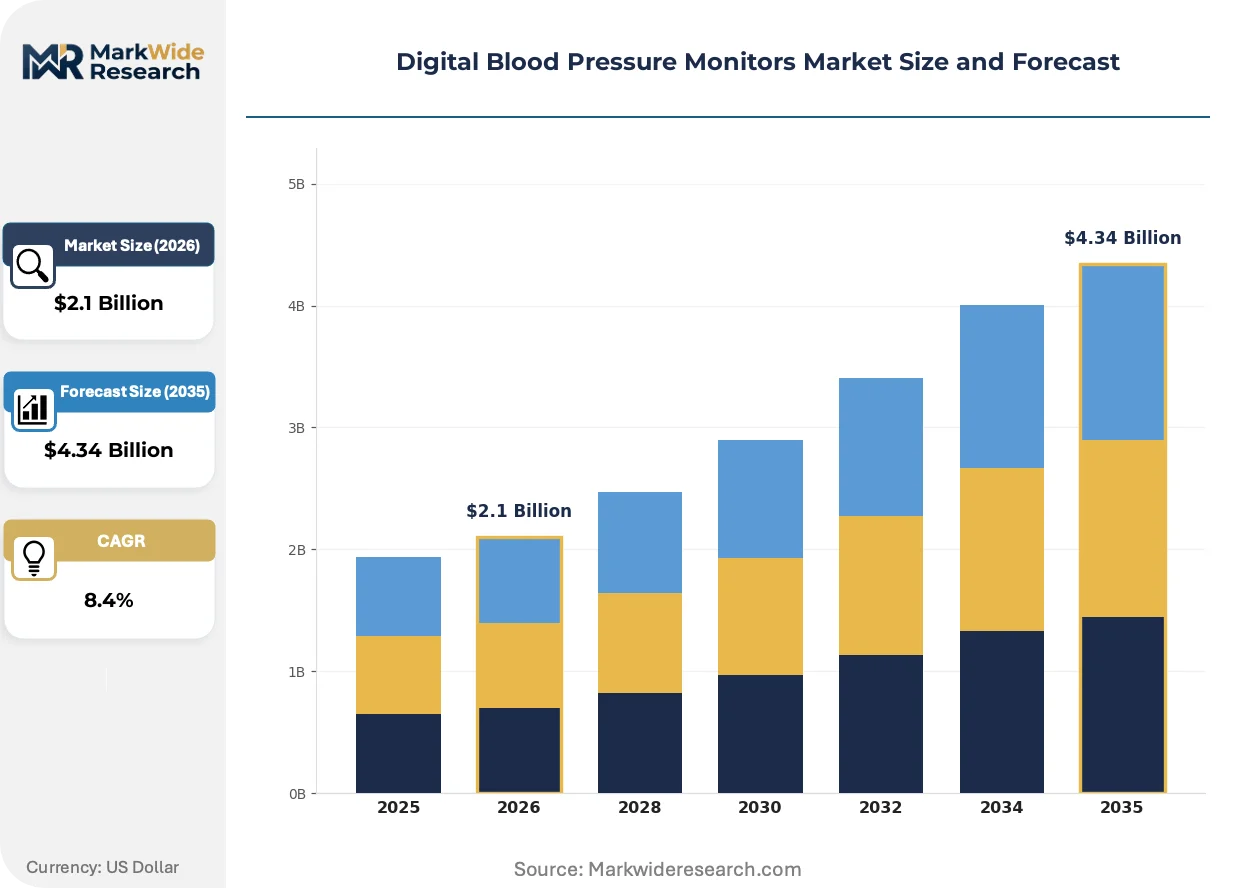
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Arm Monitors, Wrist Monitors, Finger Monitors, Ambulatory Monitors Technology: Oscillometric, Auscultatory, Pulse Wave Analysis, Tonometry Application: Home Care, Clinical Settings, Telemedicine, Fitness Tracking End User: Patients, Healthcare Professionals, Remote Care Providers, Fitness Enthusiasts |
| Companies Covered | Omron Healthcare, A&D Medical, Koninklijke Philips, Welch Allyn, GE Healthcare, Microlife, Withings, SunTech Medical, American Diagnostic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Blood Pressure Monitors Market Strategic Shifts & Innovations
Product evolution is defined by the convergence of medical-grade hardware with consumer electronics design principles and connectivity. The market is shifting focus from measurement accuracy alone to include user experience, data portability, and integration within digital health ecosystems.
System-on-Chip (SoC) solutions integrate microcontrollers, memory, and wireless radios like Bluetooth into a single semiconductor. Device manufacturers across both home care and clinical segments are rapidly standardizing on these components for new product designs. This consolidation of functions is unifying discrete electronic parts into a compact architecture, enabling smaller device footprints and more advanced connectivity features.
Europe's stringent Medical Device Regulation (MDR) has elevated the requirements for clinical validation and post-market surveillance for all medical devices. The regulation forces manufacturers to generate more extensive technical documentation and clinical evidence to obtain or maintain CE marking. This shift particularly affects devices with software components, as the software itself is now subject to rigorous validation as a medical device.
Consumer behavior is pivoting from passive self-measurement to active data sharing with healthcare providers for remote management of chronic conditions. This change disrupts the traditional model of infrequent, in-office blood pressure checks, favoring a continuous flow of data from the patient's home to the clinical team. This trend is most advanced in the United States, where evolving reimbursement policies for remote patient monitoring are incentivizing provider adoption.
Digital Blood Pressure Monitors Market Segmentation
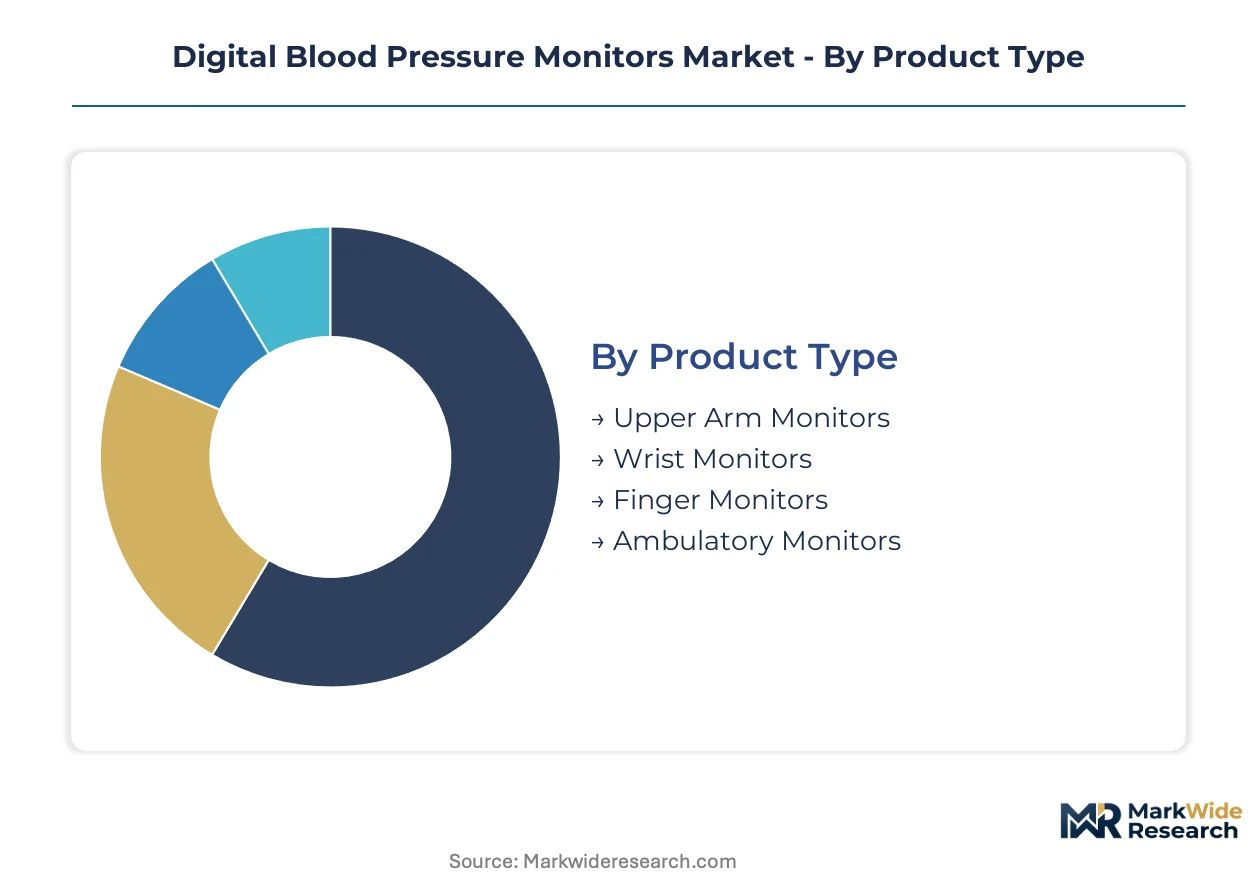
The digital blood pressure monitors market segmentation reveals distinct pathways for product development, technological innovation, and end-user engagement. Understanding these categories is critical for device manufacturers to align their offerings with evolving patient needs and clinical requirements. This granular analysis illuminates where market value is generated and where future growth opportunities reside.
Product Type:
Manufacturing digital blood pressure monitors involves varying levels of capital expenditure, with certain product types demanding more intricate production lines and certification processes.
- Upper Arm Monitors:These devices utilize an inflatable cuff placed on the upper arm to measure blood pressure via the oscillometric method. Their perceived higher accuracy drives strong demand in both clinical settings and home care applications, particularly for chronic disease management.
- Ambulatory Monitors:Ambulatory monitors automatically measure blood pressure at regular intervals over a 24-hour period, providing a comprehensive profile for diagnosis and treatment adjustment. Their specialized nature and integration with analytical software cater to underserved clinical niches, offering detailed diagnostic data.
- Wrist Monitors:These compact devices offer convenience for self-monitoring, appealing to users seeking portability and ease of use.
- Finger Monitors:Finger monitors provide a quick, less intrusive measurement option, integrated into wearable technology.
Upper Arm Monitors absorb the bulk of installed capacity; Ambulatory Monitors are expanding most quickly.
Technology:
Technological differentiation within digital blood pressure monitors reflects varying levels of R&D investment and clinical validation required for market acceptance.
- Oscillometric:This widely adopted method detects blood flow oscillations as a cuff deflates, calculating systolic and diastolic pressures. Its cost-effectiveness and proven reliability make it the standard for home care and many clinical devices, supporting broad market penetration.
- Pulse Wave Analysis:Pulse wave analysis measures arterial stiffness and central blood pressure by analyzing the arterial pulse waveform. This advanced technique offers deeper cardiovascular insights, attracting interest from specialized clinical research and high-end diagnostic applications.
- Auscultatory:Auscultatory methods, integrated into some digital devices, enhance accuracy through sound detection in professional settings.
- Tonometry:Tonometry measures blood pressure by flattening an artery, explored for continuous, non-invasive monitoring.
Oscillometric technology dominates current market offerings, while Pulse Wave Analysis represents a significant area for future innovation in cardiovascular diagnostics.
Application:
The application segments for digital blood pressure monitors are shaped by distinct end-user needs and the specific utility they provide in different healthcare contexts.
- Home Care:This segment encompasses devices used by patients for self-monitoring and chronic disease management outside clinical environments. Patient demand for accessible and accurate self-monitoring tools, coupled with remote patient monitoring initiatives, propels this segment's expansion in the United States.
- Clinical Settings:Clinical settings utilize monitors for diagnostic purposes, inpatient care, and routine check-ups within hospitals and physician offices. These devices prioritize durability and seamless integration with Electronic Medical Record (EMR) systems, ensuring data consistency across healthcare facilities.
- Telemedicine:Telemedicine leverages connected monitors for remote consultations and data sharing between patients and providers.
- Fitness Tracking:Fitness tracking integrates blood pressure monitoring into wearables for general wellness insights.
Home Care represents the largest application area, transforming the device from a standalone tool into a connected data node for chronic disease management.
End User:
End-user categories exert differing purchasing power and influence on product design, driving innovation towards specific features and connectivity options.
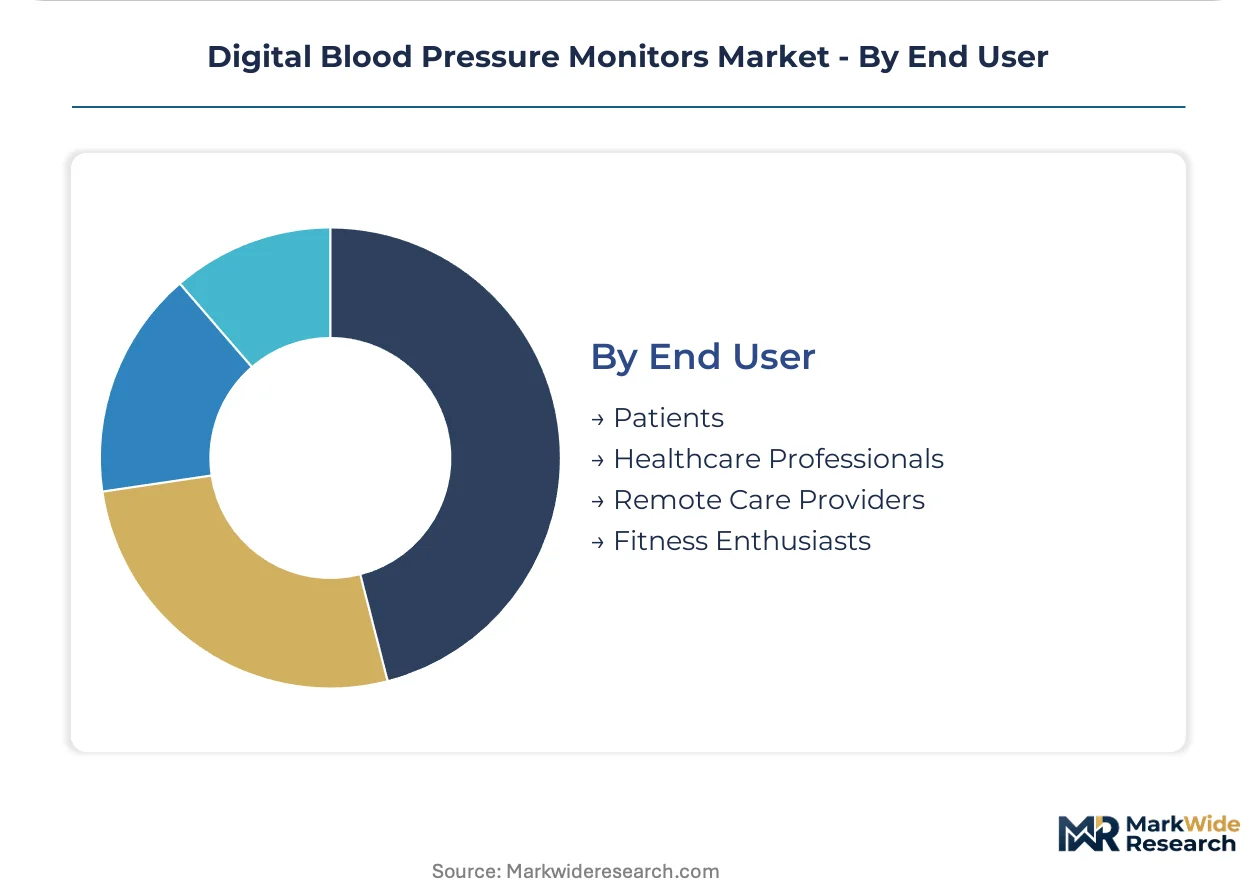
- Patients:Patients are direct consumers seeking user-friendly devices for personal health management and adherence to treatment plans. Their preference for self-monitoring tools and integration with mobile health applications fuels demand for intuitive and connected solutions across Asia-Pacific.
- Healthcare Professionals:This group includes physicians, nurses, and medical assistants who require precise, reliable devices for diagnosis, treatment, and ongoing patient care. Their need for clinical accuracy and EMR system compatibility influences design specifications and regulatory compliance, particularly in Germany.
- Remote Care Providers:Remote care providers manage patient data from connected monitors, requiring platforms for data aggregation.
- Fitness Enthusiasts:Fitness enthusiasts use monitors for performance tracking and general wellness, valuing convenience.
Patients remain the primary focus for product development, while Remote Care Providers represent a rapidly emerging segment due to evolving care models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones like the Yangtze River Delta in China are attracting significant investment in medical device manufacturing, fostering innovation in digital blood pressure monitors. These zones provide infrastructure and regulatory support, driving production efficiencies and market expansion. Such concentrations are crucial for global supply chains.
United States
Remote patient monitoring initiatives drive demand for connected blood pressure monitors in home care settings. The FDA's rigorous clearance process ensures device accuracy and safety for consumers. Boston's MedTech hub develops advanced health monitoring solutions, integrating blood pressure data into broader digital platforms.
Germany
Strong demand for clinical-grade devices and seamless integration with Electronic Medical Record (EMR) systems exists. Europe's Medical Device Regulation (MDR) sets high standards for clinical validation and post-market surveillance. The Stuttgart region specializes in precision engineering for medical instruments, supporting advanced sensor development.
China
Rapid expansion of home care applications and telemedicine fuels market growth for digital blood pressure monitors. The NMPA's standards govern product approval and market access for domestic and international manufacturers. Shenzhen's technology parks are centers for mass production and development of cost-effective digital health devices.
Japan
A focus on aging populations and preventative healthcare increases demand for user-friendly home monitoring devices. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates medical devices, emphasizing reliability and technological advancement. Tokyo's research institutions collaborate on next-generation wearable health technologies, including non-invasive blood pressure sensing.
United Kingdom
Government support for digital health services and chronic disease management programs influences device adoption. The Medicines and Healthcare products Regulatory Agency (MHRA) ensures medical device safety and performance, aligning with European standards. Cambridge's biomedical campus fosters innovation in connected health ecosystems and data analytics for patient care.
Digital Blood Pressure Monitors Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with established brands dominating the home care and clinical device markets. The market exhibits a tiered structure, from premium device manufacturers to value-focused OEM providers. Key strategic archetypes include integrated health ecosystem providers, niche clinical specialists, and high-volume consumer electronics manufacturers. Competitive moves involve technology licensing agreements and strategic partnerships for data integration.
Within the integrated health ecosystem tier, Koninklijke Philips exemplifies a strategy of combining blood pressure monitors with broader digital health platforms. Omron Healthcare represents a leading branded specialist, leveraging manufacturing scale for the home care segment. Welch Allyn, conversely, occupies a position as a clinical device specialist, focusing on durability and EMR integration for professional settings.
| Leading Market Players |
|---|
| Omron Healthcare |
| A&D Medical |
| Koninklijke Philips |
| Welch Allyn |
| GE Healthcare |
| Microlife |
| Withings |
| SunTech Medical |
| American Diagnostic Corporation |
| Others |
Cost & Logistics Intelligence
The global semiconductor price index directly influences the manufacturing cost of System-on-Chip (SoC) solutions, cascading into tiered pricing for digital blood pressure monitors across clinical and home care segments. This dependency shapes product economics for device manufacturers.
Pricing Analysis
Expedited lead times for specialized components command premium pricing for digital blood pressure monitors, while standard inventory often sees competitive discounts. The market operates on a hybrid pricing model, blending per-unit transactional sales with emerging subscription-based software services. FDA and CE certification levels create significant price differentiation, alongside established brand premiums. Pricing softness reflects intense competition from mass-market manufacturers. Patients in the home care segment are most price-sensitive, while healthcare professionals prioritize accuracy and EMR integration.
Supply Chain Analysis
System-on-Chip (SoC) solution supply relies heavily on manufacturing hubs in Taiwan, China, and South Korea. This market's supply chain draws critical components like pressure sensors and medical-grade plastics from these concentrated regions. A significant structural risk involves single-source vulnerability for advanced SoCs, exposing device manufacturers to volatility. Distribution runs through established medical device distributors for clinical settings and direct-to-consumer retail channels for home care devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a significant technology-transition phase, as System-on-Chip (SoC) solutions increasingly replace discrete electronic components in digital blood pressure monitors. This shift enables new functionalities and connected health ecosystems.
For Market Incumbents: Cement market leadership by investing heavily in software and data analytics services that integrate blood pressure monitoring into broader connected health platforms. Incumbents must also vertically integrate into core System-on-Chip (SoC) design to mitigate supply chain volatility and reduce reliance on external suppliers. The persistent threat of regulatory fragmentation and consumer-focused new entrants demands continuous investment in FDA and CE marking processes.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce channels offer a viable entry point for new players to penetrate the home care segment with user-friendly, connected devices. Focus on developing specialized monitors for underserved clinical niches, such as 24-hour ambulatory blood pressure monitoring (ABPM), bundled with advanced analytics software. A strategic go-to-market angle involves partnering with existing telemedicine platforms to offer integrated monitoring solutions.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers targeting companies with strong software and data analytics capabilities in the long term, spanning the next 5-10 years. Acquisition targets should include niche clinical specialists with validated device accuracy or innovative health tech firms offering seamless EMR integration. Investors should watch for further expansion of government and private payer reimbursement pathways for remote patient monitoring.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Subscription-based Analytics | Shifts revenue model from hardware to recurring software services, enhancing customer lifetime value. |
| Secure NMPA Approval in China | Unlocks access to the rapidly expanding Chinese home care and telemedicine markets. |
| Invest in SoC Design Capability | Mitigates supply chain risks and enables greater control over product innovation and cost. |
| Form Telemedicine Partnerships | Integrates devices into existing digital health ecosystems, expanding reach to remote patients. |
| Target Ambulatory Monitoring Niche | Captures specialized clinical demand for comprehensive 24-hour blood pressure data. |
Research Approach
Independent corroboration across primary interviews, regulatory filings, and medical device databases underwrites the qualitative findings and quantitative projections. This included discussions with clinicians, biomedical engineers, hospital purchasing committees, and regulatory affairs leads. Secondary sources like FDA submissions, Europe's MDR documentation, and NMPA standards provided market validation. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Rate-of-change decomposition analyzed market dynamics across the entire analysis window, modeling key segments including product type, technology, application, and end user. Compound annual growth rates were derived from historical trends and projected future adoption patterns. The analytical framework incorporated inputs such as remote patient monitoring program adoption rates and chronic disease prevalence to refine market projections over the forecast period.
Inputs from public financial reports and regulatory databases were available through the study window; gaps in real-time supply chain data introduce uncertainty bands into short-term component availability. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. A small set of named triggers, including major regulatory shifts or significant SoC supply disruptions, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Venous Procedure Devices Market
Medical Devices
Tissue Expanders Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Global Angiography Catheters Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
North America Wheelchair Market
Medical Devices
France Respiratory Devices Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market