
 Diamond Wire Market | 2026-2036
Diamond Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond Wire Market Intelligence
Expanded manufacturing capacity in China is tilting the supply landscape toward Asia-based producers. This shift challenges established firms like Japan's Asahi Diamond, which leverages its long-standing expertise in ultra-fine wire production. Meanwhile, Chinese firms such as DIAT New Material and Sino-Crystal Diamond compete aggressively on production scale and cost. The LEONI Group specializes in providing high-performance wires for niche European industrial applications.
Diamond wire is a cutting tool composed of a high-tensile steel core coated with fixed diamond abrasives. These abrasives, often sized in microns, are bonded to the core using methods like electroplating or resin bonding. Its primary function is slicing hard, brittle materials such as silicon ingots, sapphire, and quartz with minimal kerf loss. The solar panel cutting application consumes the highest volume of wire, while semiconductor manufacturing requires finer wires for advanced wafering.
Manufacturing and use are influenced by environmental and material standards. The EU's RoHS directive restricts hazardous substances, affecting wire composition and coatings. In parallel, China's dual carbon goals stimulate demand for solar components, including the wires used in their production. Stakeholder focus now centers on developing wires that improve wafer yield and reduce slicing costs for next-generation electronics.
Market Dynamics
The central dynamic shaping the diamond wire market is the immense production scaling in solar photovoltaics, which drives volume, juxtaposed with the extreme precision requirements of semiconductor manufacturing, which drives technological innovation. This dual demand creates a fundamental tension between optimizing for low-cost, high-throughput slicing and developing ultra-fine wires for next-generation electronics.
Growth Catalysts
- China's Dual Carbon Goals:National policies in China promoting massive expansion of solar energy capacity directly stimulate demand for diamond wire, a critical consumable for slicing silicon ingots into wafers for solar panels.
- Thinner Wafer Technology:The push in the photovoltaic and semiconductor industries for thinner, more efficient wafers necessitates cutting tools like diamond wire that minimize kerf loss and subsurface damage, boosting consumption.
- Photovoltaic Industry Expansion:Rapid growth in solar panel manufacturing, particularly concentrated in Asia, creates a large, centralized customer base for high-volume diamond wire supply, supporting economies of scale for producers.
Market Restraints
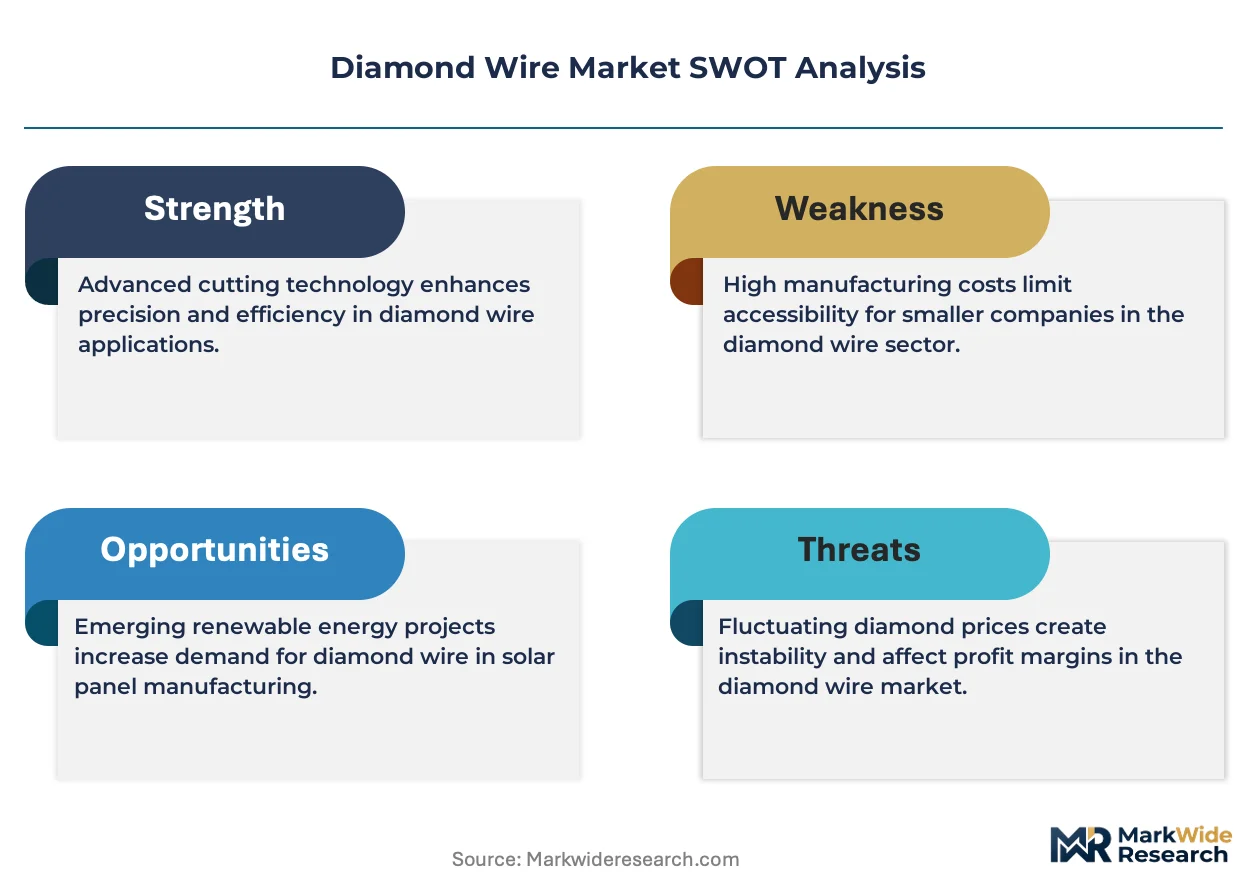
- Input Material Volatility:The cost of high-tensile steel for the core wire and industrial-grade diamond abrasives can be volatile, creating margin pressure for manufacturers who cannot pass on price hikes in competitive segments.
- Technical Performance Limits:While kerf loss is minimal, it remains a significant factor in material waste. Further reducing wire diameter to decrease waste introduces challenges related to wire breakage and tensile strength during high-speed cutting.
- Regulatory Compliance Costs:The EU's RoHS directive restricts certain hazardous materials, affecting the composition of bonding agents and coatings, which can increase R&D and production costs for suppliers targeting the European market.
Strategic Opportunities
- New Material Slicing:The application of diamond wire for slicing novel, hard-brittle materials used in aerospace, defense, and medical device manufacturing offers a pathway to high-margin, specialized market segments.
- Process Control Integration:Developing integrated solutions that combine diamond wire with AI-powered monitoring systems allows for real-time optimization of slicing parameters, offering a value-added service beyond the consumable wire itself.
- North American Solar Manufacturing:Policy incentives like the US Inflation Reduction Act (IRA) are fostering a resurgence in domestic solar component manufacturing, creating new geographic demand centers for diamond wire outside of Asia.
Industry Challenges
- Capital Investment Hurdles:Establishing production lines for ultra-fine wires suitable for advanced semiconductor wafering requires significant capital expenditure on precision machinery, creating a high barrier to entry for new players.
- Intellectual Property Protection:Proprietary methods for bonding abrasives and coating wires are difficult to protect, especially in markets with inconsistent IP enforcement, leading to risks of technology imitation and price erosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond Wire Market |
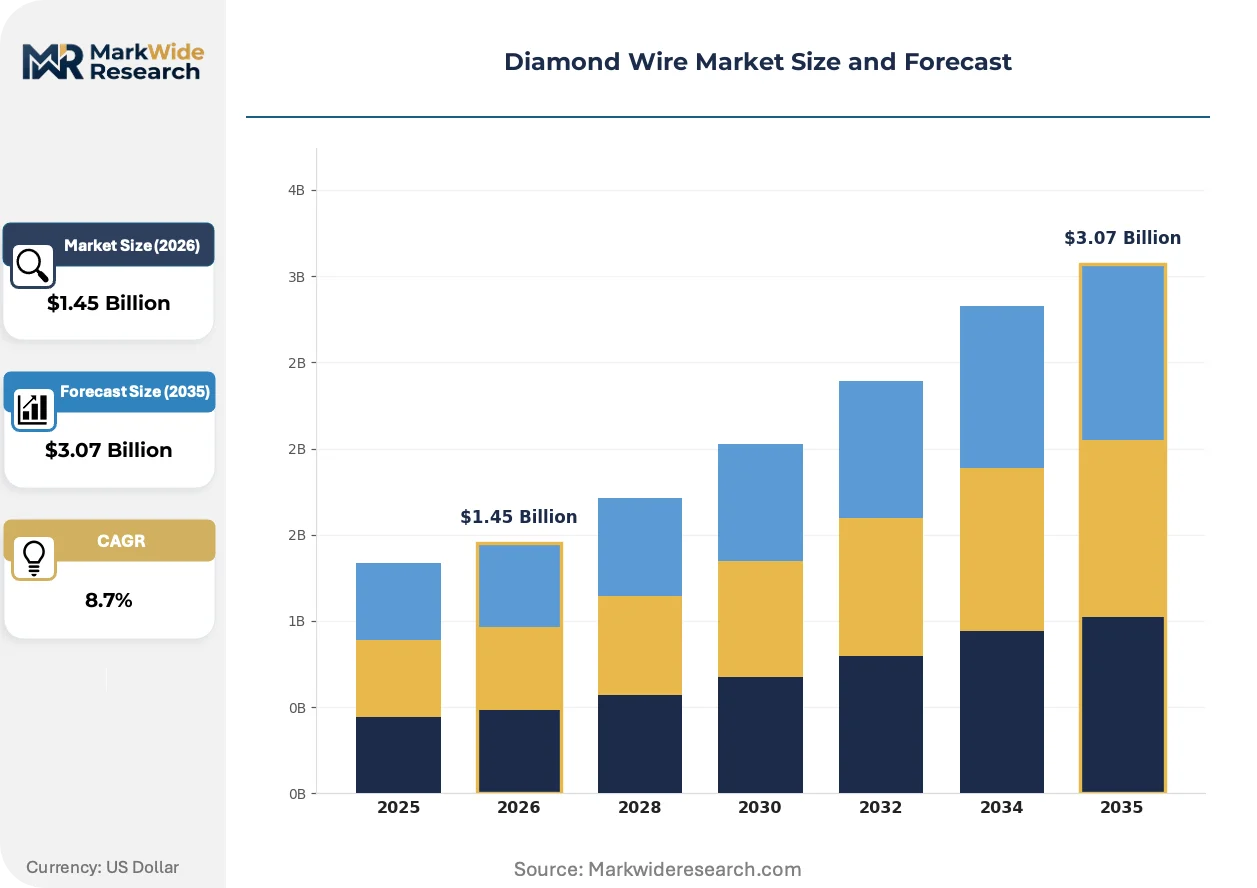
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Poly-Silicon, Multicrystalline, Ribbon Wires Application: Solar Panel Cutting, Semiconductor Manufacturing, Stone Quarrying, Precision Cutting, Electronics Fabrication End User: Photovoltaic Manufacturers, Semiconductor Foundries, Mining Companies, Electronic Component Makers, Precision Engineering Firms Technology: Electroplated, Brazed, Resin Bonded, Vacuum Brazed, Mechanical Fastened |
| Companies Covered | Asahi Diamond, Nakamura Choukou, DIAT New Material, Diamond Pauber, Sino-Crystal Diamond, Noritake Co., Limited, Element Six, Henan Yicheng, LEONI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond Wire Market Strategic Shifts & Innovations
The market is being reshaped by an intense focus on maximizing material yield and reducing the total cost of ownership in slicing operations. This is driving rapid innovation in wire construction, diameter reduction, and the integration of process intelligence to optimize performance for both solar and semiconductor applications.
Ultra-fine diameter wires, often below 40 microns, are engineered with high-tensile steel cores and precisely graded diamond abrasives for slicing hard materials. Semiconductor manufacturers are rapidly adopting these advanced wires to cut next-generation silicon and silicon carbide (SiC) wafers. This move toward finer wires is collapsing the kerf loss allowance, dramatically increasing the number of usable wafers obtained from each silicon ingot.
The European Union's RoHS directive restricts the use of hazardous substances like lead and cadmium in electronic equipment and their components. This regulation directly impacts diamond wire manufacturers by governing the composition of metallic bonding agents and coatings used to fix abrasives to the steel core. Firms supplying the European market must invest in compliant material science to ensure continued access, particularly for niche industrial and electronics applications.
A notable shift in purchasing behavior involves buyers evaluating wire based on the total cost of slicing per wafer, not just the price per meter. This de-emphasizes the transactional sale of the consumable and favors suppliers who can demonstrate lower kerf loss, higher cutting speeds, and reduced wafer breakage. This trend is most prominent in the highly competitive solar photovoltaic wafering segment, where scale and efficiency are paramount.
Diamond Wire Market Segmentation
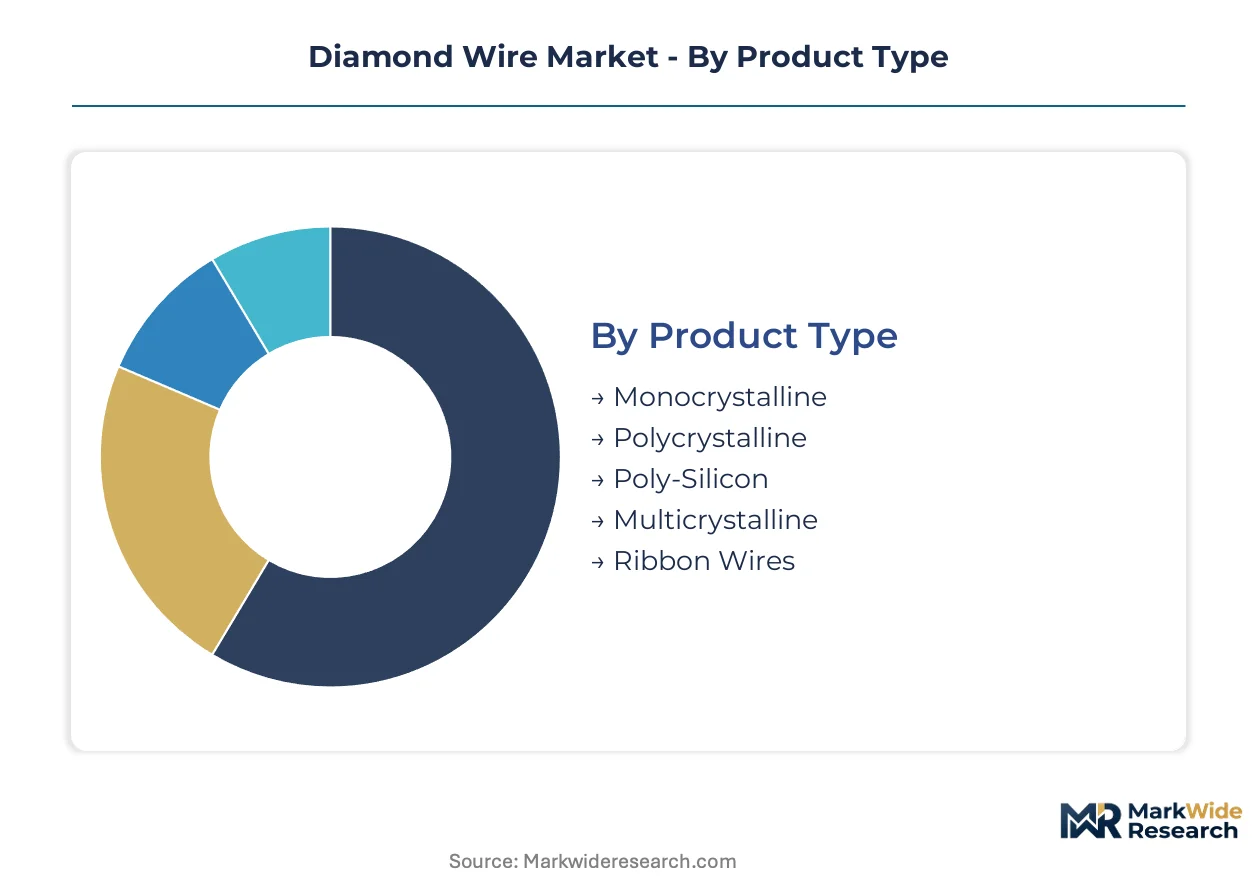
The diamond wire market's segmentation reflects the diverse precision cutting requirements across industrial applications, from large-scale material processing to micro-level electronics fabrication. Understanding these segments is critical for manufacturers to align product development with specific performance demands and for end-users to optimize material yield and operational costs.
Product Type:
The use-case spectrum for diamond wire product types ranges from high-volume solar wafering to specialized semiconductor substrate preparation.
- Monocrystalline:This wire type is engineered for cutting single-crystal silicon ingots, primarily for high-efficiency solar cells and advanced semiconductor wafers. Demand concentrates in China and Southeast Asia, driven by the push for thinner, more efficient photovoltaic cells.
- Polycrystalline:Composed of multiple crystal grains, this diamond wire is widely used for slicing multi-crystalline silicon ingots into solar wafers. Its application is prevalent in large-scale solar panel manufacturing facilities, especially in China, where cost-effective, high-throughput slicing is paramount.
- Poly-Silicon:These wires are designed for processing polysilicon materials, often used in less demanding solar applications or for feedstock preparation.
- Multicrystalline:Targeting multicrystalline silicon, these wires balance cutting efficiency with material integrity for mainstream solar panels.
- Ribbon Wires:Characterized by their flat profile, ribbon wires offer distinct advantages in certain precision cutting scenarios, reducing kerf loss in specialized material processing.
Established volume favors Polycrystalline wires; emerging adoption favors Monocrystalline wires.
Application:
Diamond wire applications span a wide range of industrial processes, demanding tailored wire characteristics for optimal performance.
- Solar Panel Cutting:This segment utilizes diamond wire for slicing large silicon ingots into wafers destined for photovoltaic cells, representing the largest volume consumption globally. High-throughput facilities in China and India drive significant demand for durable, cost-effective wires.
- Semiconductor Manufacturing:Requiring ultra-fine wires, this application focuses on precision slicing of silicon, SiC, and sapphire substrates for advanced electronic components. Manufacturers in Japan and South Korea prioritize minimal kerf loss and subsurface damage for high-value wafers.
- Stone Quarrying:Large-diameter diamond wires are employed in extracting massive blocks of granite, marble, and other natural stones from quarries.
- Precision Cutting:This broad category includes slicing various hard and brittle materials for optics, ceramics, and advanced composites.
- Electronics Fabrication:Specialized diamond wires cut delicate electronic components and substrates where material integrity is critical.
High-volume demand drives Solar Panel Cutting; specialized requirements elevate Semiconductor Manufacturing.
End User:
The end-user landscape for diamond wire is dominated by industries requiring precise and efficient material slicing at different scales.
- Photovoltaic Manufacturers:These companies consume vast quantities of diamond wire for mass production of silicon wafers, aiming for high yield and low cost per wafer. Operations in China and Southeast Asia are primary drivers.
- Semiconductor Foundries:Focused on precision, these foundries use advanced diamond wires to create thin, high-quality wafers for microprocessors and memory chips. Firms in Taiwan and South Korea represent significant demand.
- Mining Companies:Stone quarrying operations utilize robust diamond wires for extracting large blocks of natural stone.
- Electronic Component Makers:These manufacturers employ diamond wire for cutting various hard materials into specific shapes for electronic devices.
- Precision Engineering Firms:Companies specializing in high-tolerance components use diamond wire for intricate and delicate cutting tasks across multiple industries.
Efficiency gains are paramount for Photovoltaic Manufacturers; technological advancement is critical for Semiconductor Foundries.
Technology:
The bonding technology used to affix diamond abrasives to the core wire significantly influences the wire's performance characteristics and application suitability.
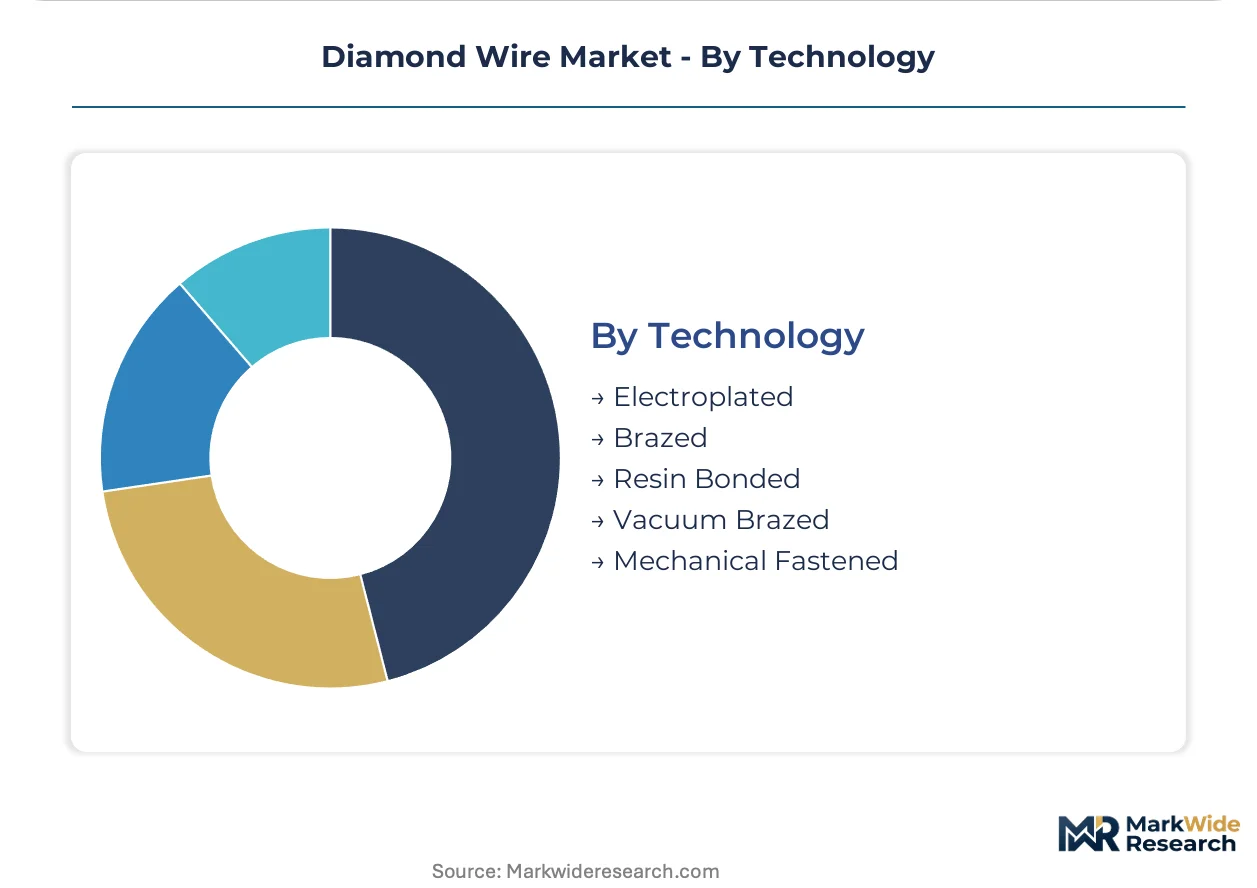
- Electroplated:This common method involves electrodepositing a metallic matrix, typically nickel, around the diamond particles to bond them to the steel core. Electroplated wires are widely used due to their cost-effectiveness and versatility in solar panel cutting.
- Resin Bonded:Utilizing a polymer resin to secure diamond abrasives, these wires offer excellent cutting precision and reduced subsurface damage, making them ideal for sensitive materials in semiconductor manufacturing. Adoption is growing in high-end electronics.
- Brazed:Diamond particles are metallurgically bonded to the wire core using a brazing alloy, offering strong retention for demanding applications.
- Vacuum Brazed:This process enhances the bond strength and diamond exposure, leading to higher cutting efficiency and longer wire life in specific industrial uses.
- Mechanical Fastened:Less common, this method involves mechanically securing diamond segments onto the wire, often for very large-scale or specialized cutting tasks.
Cost-effectiveness underpins Electroplated technology; advanced performance distinguishes Resin Bonded technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals significantly influence the global diamond wire market. These national policies drive immense demand for solar panel components, including the specialized wires for silicon wafer production. This strong policy push positions China as a central hub for diamond wire consumption and manufacturing innovation.
China
China's dual carbon goals directly stimulate demand for diamond wire, a critical consumable for silicon wafer production. The Ministry of Ecology and Environment (MEE) implements policies supporting massive solar energy capacity expansion. Manufacturing hubs like the Yangtze River Delta actively scale up photovoltaic wafer production, creating significant wire consumption.
Japan
Established firms like Asahi Diamond leverage long-standing expertise in ultra-fine wire production. The Ministry of Economy, Trade and Industry (METI) promotes advanced materials research and high-precision manufacturing. Industrial centers in the Kanto region focus on developing next-generation semiconductor wafering technologies.
South Korea
Semiconductor manufacturing requires ultra-fine wires for advanced electronic components. Government initiatives support the growth of high-tech industries, including precision wafering. Gyeonggi Province hosts major semiconductor foundries, driving demand for specialized diamond wire solutions.
United States
The US Inflation Reduction Act (IRA) fosters domestic solar component manufacturing. This policy creates new geographic demand centers for diamond wire outside of established Asian markets. States like Arizona are attracting semiconductor fabrication plants, increasing demand for advanced wafering tools.
Germany
The EU's RoHS directive restricts hazardous substances, influencing wire composition for European applications. This regulation impacts bonding agents and coatings for diamond wire used in niche industrial segments. Bavarian high-tech manufacturing centers require specialized wires for precision cutting in advanced electronics.
Diamond Wire Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the diamond wire market. This market structure is characterized by a tiered landscape, with established precision specialists and aggressive high-volume producers. Strategic archetypes include technology innovators, cost-competitive mass producers, and niche solution providers. Firms primarily engage in capacity expansion and technological innovation to secure market share.
Established precision specialists like Japan's Asahi Diamond Co., Ltd. anchor the high-end segment, leveraging their long-standing expertise in ultra-fine wire production for demanding applications. Chinese firms such as DIAT New Material Co., Ltd. and Sino-Crystal Diamond Co., Ltd. exemplify the high-volume, cost-competitive manufacturing archetype, competing aggressively on production scale. Meanwhile, the LEONI Group occupies a distinct position as a provider of high-performance wires tailored for niche European industrial applications, emphasizing specialized material requirements.
| Leading Market Players |
|---|
| Asahi Diamond |
| Nakamura Choukou |
| DIAT New Material |
| Diamond Pauber |
| Sino-Crystal Diamond |
| Noritake Co., Limited |
| Element Six |
| Henan Yicheng |
| LEONI Group |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta's immense manufacturing capacity in China directly influences diamond wire market dynamics, shaping downstream pricing power through high-volume production. This regional concentration creates both efficiencies and competitive pressures across the supply chain.
Pricing Analysis
Geographic price spreads exist, with China's high-volume producers offering more competitive per-unit transactional pricing compared to specialized European or Japanese suppliers. Pricing stratifies across performance tiers, driven by factors like wire diameter precision and after-sales technical support. Cost compression in the solar panel cutting segment is intensifying, stemming from intense competition among Chinese manufacturers. Semiconductor foundries exhibit lower price sensitivity, prioritizing minimal kerf loss and subsurface damage over raw cost, while photovoltaic manufacturers are highly price-sensitive due to scale requirements.
Supply Chain Analysis
China, Japan, and South Korea represent the primary geographic supply concentrations for diamond wire manufacturing. The supply chain relies heavily on high-tensile steel for core wire production and industrial-grade diamond abrasives sourced from a limited number of suppliers. Input material volatility, particularly for diamond abrasives, presents a structural risk for manufacturers. Downstream distribution runs through direct sales channels to large-scale photovoltaic and semiconductor fabrication plants, supplemented by specialized industrial distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits within a cyclical recovery, primarily driven by the ongoing expansion of global solar energy capacity and the demand for advanced semiconductor manufacturing.
For Market Incumbents: Build a technological moat by investing in advanced material science for ultra-fine wire development and improved bonding agents. This addresses the threat from aggressive, cost-competitive mass producers and leverages R&D in new coating technologies. Consolidate market share in high-precision segments through strategic acquisitions of smaller, innovative firms specializing in resin-bonded wire technologies.
For New Entrants and Emerging Players: Pursue niche market opportunities by focusing on specialized materials slicing for aerospace, defense, and medical device manufacturing, where performance outweighs cost. The precision cutting segment represents the most penetrable application area. A go-to-market angle should emphasize integrated solutions, bundling high-performance wires with AI-powered process control systems.
For Investors and Strategic Acquirers: Long-term, this sits as a critical enabling technology play because it underpins the growth of both renewable energy and advanced electronics. Target precision specialists with proprietary bonding technologies or strong intellectual property in ultra-fine wire production. The signal to watch is the adoption rate of sub-40-micron wires in next-generation SiC wafering for electric vehicles and 5G infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Ultra-Fine SiC Wires | This initiative directly enables next-generation semiconductor manufacturing for high-power electronics. |
| Expand Resin-Bonded Wire Capacity | Increased capacity supports growing demand from semiconductor foundries prioritizing precision and minimal damage. |
| Integrate AI-Powered Process Monitoring | Real-time optimization of slicing parameters enhances wafer yield and reduces operational costs for end-users. |
| Secure Long-Term Steel Core Supply | Stabilizing input costs mitigates margin pressure from raw material volatility for manufacturers. |
| Target North American Solar Manufacturing | Geographic expansion leverages policy incentives from the US Inflation Reduction Act for new demand centers. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation across multiple data sources. This involved engaging R&D directors, procurement managers at photovoltaic and semiconductor foundries, and material science experts to gather nuanced insights. Secondary data sources included trade association reports, regulatory filings, and company annual reports, providing a comprehensive view of market dynamics.
Forecast inputs considered the interplay of technological advancements and market demand across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, technology, and key geographic regions. Compound annual growth rates were derived through a combination of historical trend analysis and future growth projections, with specific inputs like projected solar capacity additions and trends in wafer thickness driving the model.
Macroeconomic conditions sit as an overlay; deviation in global energy policies or semiconductor investment cycles would shift the trajectory. Forecasts reflect assumptions regarding technological stability and sustained demand from key end-use industries. Quarterly review of solar installation rates and semiconductor capital expenditures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Metal Heat Treatment Market
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Band File Sander Belts Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Industrial Furnaces Market
Industrial Materials
Acrylic Sheet Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Tooling Board Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Wire Drawing Dies Market